
 Asia-Pacific Tofu Market | 2026-2036
Asia-Pacific Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tofu Market Outlook
Soybean processing clusters across China's Yangtze River Delta are restructuring capacity to serve chilled tofu export channels into Japan and South Korea. House Foods Group Inc anchors premium silken tofu production through controlled nigari coagulation systems in its domestic Japanese facilities. Pulmuone Corporate leverages integrated soybean crushing and curd-forming operations to sustain cost advantages across Korean retail and food-service channels. Hangzhou Bean Food Co. Ltd dominates fresh block distribution through direct-store-delivery networks spanning Zhejiang and Jiangsu provinces.
Tofu is a protein-rich food product manufactured by coagulating soy milk and pressing the resulting curds into solid blocks, with firmness determined by water content and coagulant type—calcium sulfate, magnesium chloride, or glucono delta-lactone. The product serves as a versatile meat alternative in commercial kitchens and a staple protein source in residential diets across East Asia. Firm tofu occupies the largest volume share in food manufacturing applications where structural integrity under frying and grilling is essential. Silken tofu represents the fastest-growing product type within premium residential and restaurant segments where texture purity commands price premiums. Block form leads distribution through supermarkets, while crumb formats are gaining traction among food manufacturers developing plant-based burger and sausage analogues.
Japan's Ministry of Health, Labour and Welfare enforces stringent food sanitation standards for soy-based products that constrain import eligibility and favor domestic producers with certified HACCP systems. China's SAMR administers GB/T 22106 soybean product standards that mandate protein minimums and restrict preservative categories, shaping formulation decisions for manufacturers serving mainland retail. South Korea's MFDS operates positive-list additive regulations for tofu that complicate cross-border sourcing from suppliers using non-harmonized ingredient decks. Stakeholders must monitor regulatory divergence on coagulant approvals and organic certification reciprocity as these determine which production bases can access premium channel placements across the region.
Market Dynamics
Fresh tofu supply chains across East Asia are consolidating around cold-chain infrastructure investments that compress distribution timelines from production facilities to retail shelves, fundamentally altering competitive positioning between integrated processors and traditional fresh-curd artisans.
Growth Catalysts
- Plant-forward QSR procurement:Quick-service restaurant chains across Southeast Asia are expanding silken and firm tofu volumes for meat-alternative menu items, creating sustained pull from centralized food-service distributors.
- Japan's Food Labeling Act:Revisions tightening protein-content disclosures and additive limits are advantaging certified domestic producers with compliant HACCP systems against non-conforming imports.
- China's eastern manufacturing corridor:Cold-chain networks from Shanghai to Hangzhou now achieve same-day retail coverage for fresh tofu blocks, enabling premium positioning previously reserved for ambient-stable products.
Market Restraints
- Input cost volatility:Non-GMO soybean premiums fluctuate with Brazilian and Argentinian harvest cycles, squeezing margin structures for processors without captive crushing operations.
- Regulatory friction:South Korea's MFDS positive-list additive regulations complicate cross-border sourcing from Chinese suppliers using non-harmonized coagulant decks.
- Substitution pressure:Pea and fava protein isolates are gaining formulation share in plant-based meat analogues, displacing textured tofu crumb in some food-manufacturing applications.
Strategic Opportunities
- Underpenetrated Vietnam:Modern retail expansion in Ho Chi Minh City and Hanoi creates first-mover advantage for chilled tofu brands with localized flavor profiles.
- Export channel development:Japanese and South Korean import demand for premium silken varieties rewards Yangtze River Delta processors investing in nigari coagulation upgrades.
- Food-service crumb formats:Burger and sausage analogue manufacturers represent emerging offtake for specialized tofu crumb with controlled moisture content and protein binding.
Industry Challenges
- Certification timeline compression:Organic and JAS certification requirements for Japanese market access demand 18-24 month conversion periods that strain working capital for mid-scale processors.
- Cold-chain capex intensity:Same-day distribution coverage requires refrigerated vehicle fleets and hub-and-spoke logistics infrastructure that fragments returns below threshold scale.
- Coagulant standardization gaps:Divergent GB standards, JIS specifications, and MFDS positive lists create formulation complexity for manufacturers serving multiple national markets from single production bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tofu Market |
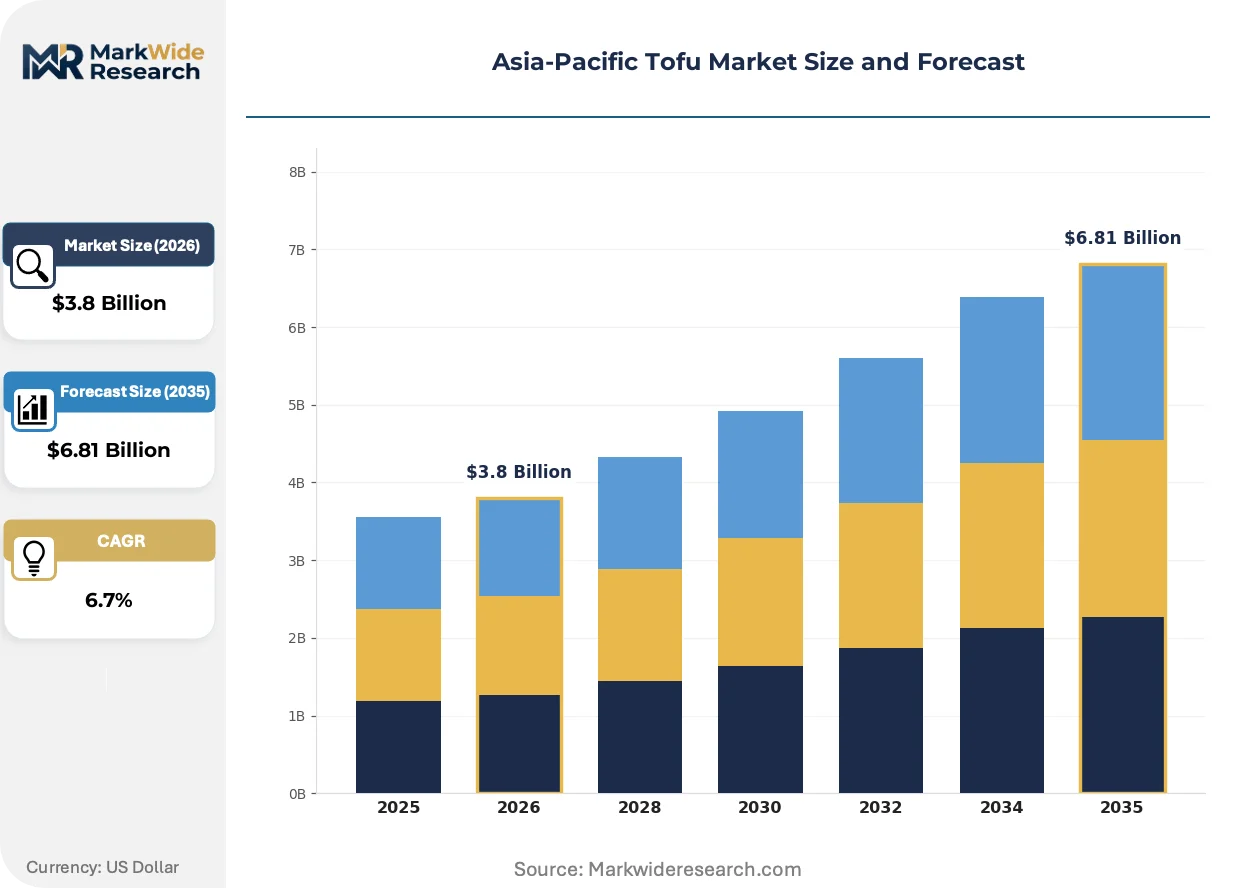
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Tofu, Soft Tofu, Silken Tofu, Baked Tofu Form: Block, Cubes, Slices, Crumbs Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops End User: Residential Consumers, Restaurants, Food Service, Food Manufacturers |
| Companies Covered | Misuzu Corporation Co. Ltd, Invigorate Foods Pvt. Ltd, Vitasoy International Holdings Ltd, Miracle Soybean Food International Corporation, PSC Corporation Limited, House Foods Group Inc, Pulmuone Corporate, Hangzhou Bean Food Co. Ltd, Morinaga Milk Industry Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tofu Market Strategic Shifts
Processing technology and distribution infrastructure are converging to transform tofu from a commodity staple into a segmented fresh-protein category with distinct quality tiers and channel-specific formulations.
Continuous nigari coagulation systems with precision temperature and pH control are overtaking traditional batch methods in premium silken production. Japanese and Korean food-service buyers are specifying these systems for texture consistency in high-end restaurant applications. This equipment shift is compressing the supplier base toward capital-intensive integrated processors and marginalizing artisan producers without upgrade pathways.
China's SAMR administration of GB/T 22106 standards is tightening protein minimums and restricting preservative categories for soybean products. Domestic manufacturers are reformulating to eliminate benzoate-based shelf-life extenders previously common in ambient tofu. Export-oriented processors in Zhejiang and Jiangsu provinces are accelerating HACCP certification to maintain Japanese market eligibility under these converging standards.
Direct-store-delivery networks are displacing traditional wholesale market intermediaries for fresh block distribution. Supermarket chains in China's eastern provinces are consolidating procurement through dedicated logistics partnerships with single-source tofu processors. This channel restructuring is most visible in Hangzhou and Nanjing, where same-day replenishment contracts now specify microbial load thresholds and temperature logging that informal distributors cannot satisfy.
Asia-Pacific Tofu Market Segmentation
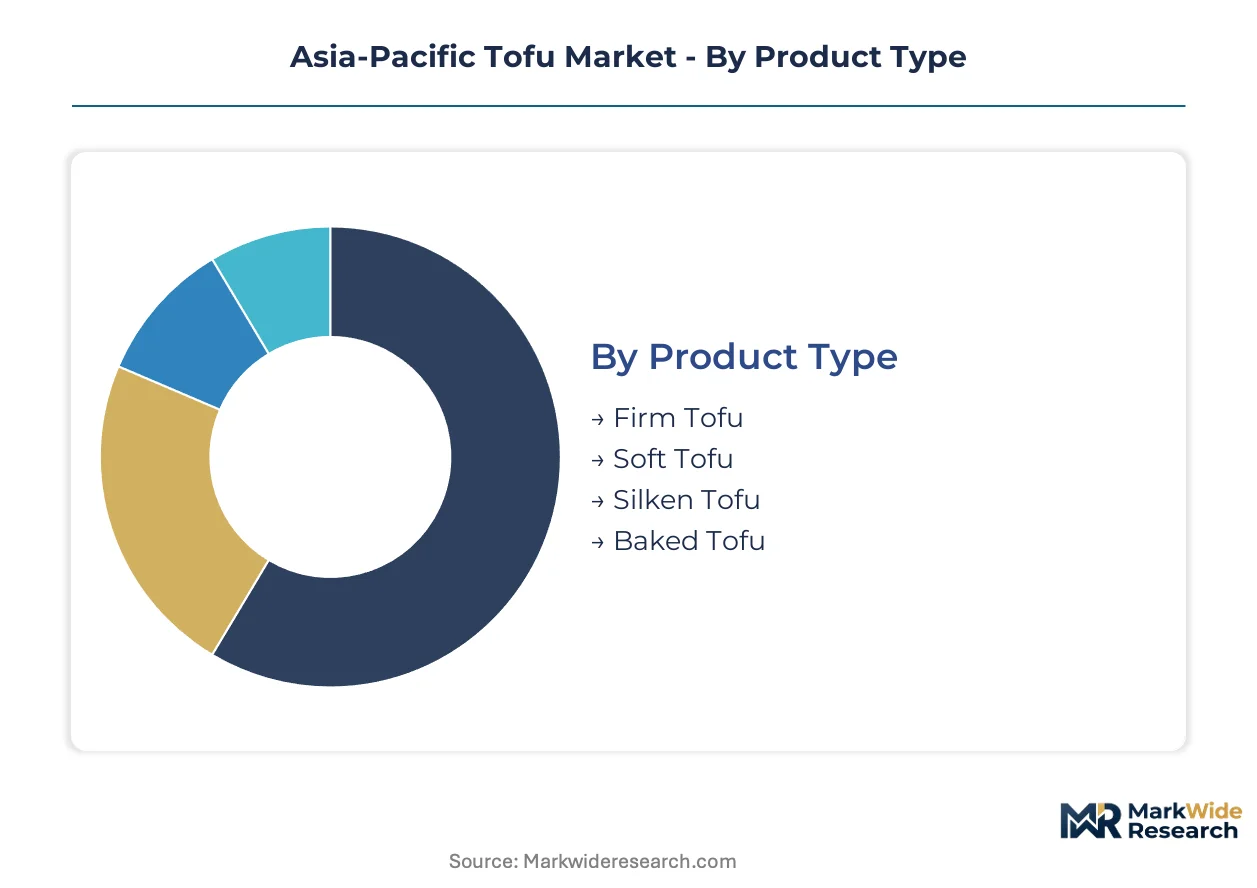
Tofu segmentation in Asia-Pacific reflects divergent supply chain requirements between fresh-protein distribution and processed ingredient channels. Structural integrity, moisture content, and cold-chain compatibility determine which product configurations command premium placement versus commodity positioning.
Product Type:
Texture and coagulant chemistry drive buyer selection across food-service and residential channels.
- Firm Tofu:Pressed curd with low moisture content (below 80%) delivers structural integrity for frying, grilling, and stir-fry applications. China's Yangtze River Delta processors dominate volume production for quick-service restaurant chains requiring consistent cube and slice performance under thermal stress.
- Silken Tofu:Unpressed curd with high moisture content (above 88%) uses nigari or glucono delta-lactone coagulation for custard-like texture. Japanese import demand from Zhejiang and Jiangsu province exporters is climbing fastest for premium residential and high-end restaurant segments where texture purity commands price premiums.
- Soft Tofu:Intermediate moisture content suits hot-pot and soup applications across South Korea and Taiwan residential markets.
- Baked Tofu:Pre-cooked firm variety with caramelized exterior targets convenience-seeking consumers in Australia's urban centers and Japan's convenience store channels.
Firm tofu leads on scale; silken tofu leads on momentum.
Form:
Processing depth and packaging format determine cold-chain investment thresholds and retail channel access.
- Block:Traditional fresh-curd format dominates supermarket distribution across China's eastern manufacturing corridor from Shanghai to Hangzhou. Same-day replenishment contracts now specify microbial load thresholds that informal distributors cannot satisfy.
- Crumbs:Controlled-moisture crumb with optimized protein binding is gaining formulation share among plant-based burger and sausage analogue manufacturers in South Korea and Japan. Food-service distributors are consolidating procurement through specialized processors with HACCP-certified crumb lines.
- Cubes:Pre-cut uniform sizing reduces kitchen labor for quick-service restaurant chains across Southeast Asia.
- Slices:Thin-cut format targets Japanese convenience store bento and hot-grill applications.
Block form anchors volume throughput; crumbs are expanding most quickly.
Distribution Channel:
Certification requirements and temperature logging capabilities filter which processors access modern retail versus traditional wholesale.
- Supermarkets:Direct-store-delivery networks are displacing traditional wholesale intermediaries across China's Jiangsu and Zhejiang provinces. Chains now consolidate procurement through dedicated logistics partnerships with single-source processors.
- Online Retail:Cold-chain express delivery enables premium silken tofu reach in Vietnam's underpenetrated Ho Chi Minh City and Hanoi markets where modern retail infrastructure remains sparse.
- Health Food Stores:Organic and non-GMO certified varieties target premium residential segments in Australia's metropolitan areas.
- Specialty Shops:Artisan producers without HACCP certification retain access through traditional tofu-ya channels in Japan's regional cities.
Supermarkets dominate current volume; online retail shows steepest expansion trajectory.
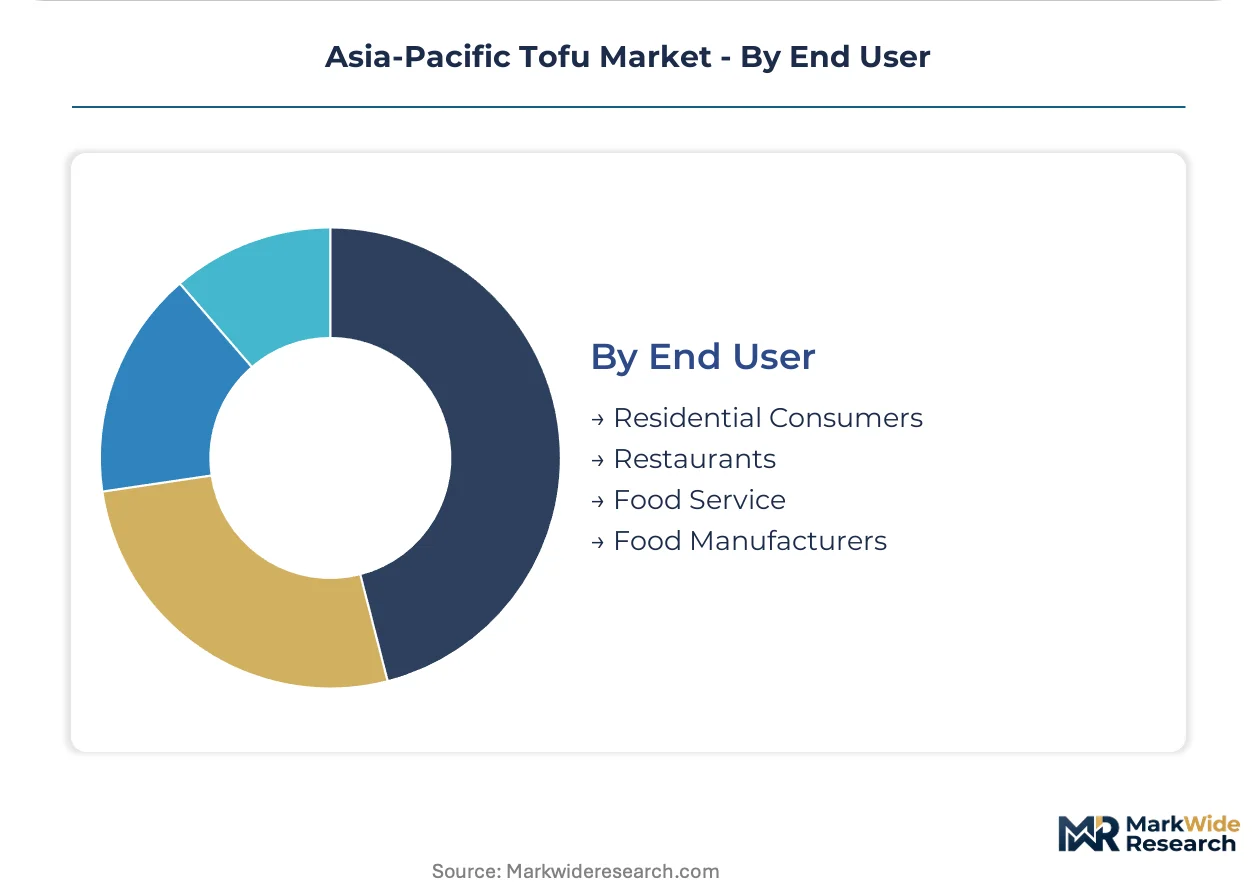
End User:
Application-specific performance requirements split procurement between structural durability and texture purity specifications.
- Restaurants:High-end Japanese and Korean establishments specify continuous nigari coagulation systems for silken tofu consistency. This equipment shift compresses the supplier base toward capital-intensive integrated processors.
- Food Manufacturers:Plant-based meat analogue developers in South Korea are reformulating with textured tofu crumb to replace pea and fava protein isolates where binding performance improves.
- Residential Consumers:Fresh block demand concentrates in China's cold-chain-enabled eastern provinces where same-day coverage supports daily purchase patterns.
- Food Service:Quick-service chains across Southeast Asia are expanding silken and firm tofu volumes for meat-alternative menu items through centralized distributors.
Restaurants lead on premium pricing; food manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting investment flows across the Asia-Pacific tofu sector, as processors weigh certification costs against market-access premiums in Japan and South Korea versus lower-compliance basins in Southeast Asia.
China
Quick-service restaurant chains in Shanghai and Hangzhou are expanding silken and firm tofu procurement for plant-forward menus. SAMR's GB/T 22106 standards mandate protein minimums and restrict preservative categories, forcing reformulation across Zhejiang and Jiangsu processors. The Yangtze River Delta cold-chain corridor now achieves same-day retail coverage for fresh blocks.
Japan
High-end restaurant establishments specify continuous nigari coagulation systems for texture consistency in premium silken applications. The Ministry of Health, Labour and Welfare enforces stringent food sanitation standards that constrain import eligibility and favor domestic producers with certified HACCP systems. Domestic facilities anchor premium production through controlled coagulation technology.
South Korea
Food manufacturers are reformulating plant-based meat analogues with textured tofu crumb to improve binding performance. MFDS positive-list additive regulations complicate cross-border sourcing from Chinese suppliers using non-harmonized coagulant decks. Integrated soybean crushing and curd-forming operations sustain cost advantages across retail and food-service channels.
Vietnam
Modern retail expansion in Ho Chi Minh City and Hanoi creates first-mover opportunity for chilled tofu brands with localized flavor profiles. Cold-chain express delivery enables premium silken reach where modern retail infrastructure remains sparse. Urban procurement is concentrating through supermarket chains displacing traditional wet-market intermediaries.
Australia
Organic and non-GMO certified varieties target premium residential segments in metropolitan Sydney and Melbourne. Health food stores and specialty grocers are consolidating shelf space around certified imports from East Asian processors. Convenience-seeking consumers drive demand for pre-cooked baked formats through urban convenience store channels.
Asia-Pacific Tofu Market Competitive Environment
Japanese producers anchor the premium certification tier; Chinese specialists hold volume-scale positions in fresh-block distribution. The vendor base stratifies between integrated processors with captive crushing operations and artisan curd-formers without cold-chain infrastructure. Three archetypes dominate: HACCP-certified exporters serving Japanese import demand, direct-store-delivery networks covering China's eastern corridor, and hybrid food-service crumb suppliers for plant-based meat developers. Competitive maneuvering concentrates on cold-chain capex deployment and nigari coagulation system upgrades.
Within the integrated-processor tier, House Foods Group Inc and Pulmuone Corporate exemplify capital-intensive operators with domestic market anchoring positions. Hangzhou Bean Food Co. Ltd occupies a position among fresh-block distributors with direct-store-delivery network concentration. These three entities represent divergent strategic postures: Japanese certification compliance, Korean vertical integration, and Chinese logistics scale.
| Leading Market Players |
|---|
| Misuzu Corporation Co. Ltd |
| Invigorate Foods Pvt. Ltd |
| Vitasoy International Holdings Ltd |
| Miracle Soybean Food International Corporation |
| PSC Corporation Limited |
| House Foods Group Inc |
| Pulmuone Corporate |
| Hangzhou Bean Food Co. Ltd |
| Morinaga Milk Industry Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between JAS-certified premium silken and commodity-grade fresh block tofu manifests in divergent margin structures and cold-chain investment thresholds across Japanese import channels versus China's domestic wholesale markets. Premium tiers command three-tier pricing separation across organic-certified, HACCP-compliant, and conventional grades, while supply configurations split between dedicated nigari coagulation facilities and batch-process artisan operations.
Pricing Analysis
Distributor margins for premium silken tofu bound for Japanese retail absorb 18-22 point markups over ex-factory Zhejiang prices, whereas direct-store-delivery networks serving Chinese supermarkets compress intermediary layers to single-digit spreads. Price differentiation hinges on organic certification reciprocity and nigari coagulation system pedigree, with HACCP compliance commanding measurable premia over GB-standard baselines. Cost compression in commodity fresh blocks is intensifying because Yangtze River Delta processors without captive soybean crushing face Brazilian non-GMO premium volatility. Quick-service restaurant chains across Southeast Asia exhibit highest price sensitivity, while high-end Japanese restaurants prioritize texture consistency over unit cost.
Supply Chain Analysis
Return flows of temperature-compromised fresh blocks drive reverse-logistics costs that informal distributors cannot absorb, accelerating consolidation toward hub-and-spoke cold-chain operators with dedicated refurbishment protocols. Geographic supply concentration centers on China's Jiangsu and Zhejiang provinces, with secondary nodes in Japan's domestic nigari-specialist facilities and South Korea's integrated Pulmuone operations. Raw material dependencies rest on Brazilian and Argentinian non-GMO soybean premiums, Japanese nigari coagulant imports, and glucono delta-lactone chemical supply. Single-source vulnerability runs through the Yangtze River Delta cold-chain corridor where same-day coverage depends on finite refrigerated fleet capacity. Distribution runs through direct-store-delivery partnerships displacing traditional wholesale market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific tofu market functions as a geographic-arbitrage play where Japanese certification timelines and South Korean additive positive-list compliance create 18-24 month entry barriers that Chinese processors with pre-existing HACCP systems can exploit for premium channel access.
For Market Incumbents: Extend cold-chain coverage density in Vietnam's Ho Chi Minh City and Hanoi corridors before modern retail consolidation locks in exclusive supplier relationships. Deepen backward integration into captive soybean crushing to buffer Brazilian harvest cycle volatility that squeezes margin structures for non-integrated competitors. Certification investment in JAS-organic dual compliance represents the critical defensive lever against Yangtze River Delta exporters upgrading nigari coagulation systems. For New Entrants and Emerging Players: Food-service distributors specializing in plant-based meat analogue crumb supply present the most penetrable channel wedge, as South Korean and Japanese manufacturers reformulate away from pea protein isolates toward textured tofu with controlled moisture binding. Vietnam's underpenetrated chilled tofu segment offers white-space expansion where cold-chain express delivery can bypass sparse modern retail infrastructure. A localized flavor profile strategy targeting Vietnamese hot-pot and soup applications enables rapid volume accumulation before multinational brands establish shelf presence. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale Chinese processors lack working capital for 18-24 month organic conversion timelines but possess established direct-store-delivery networks in Jiangsu and Zhejiang provinces. Long-term viability across the analysis window favors acquisition targets with dual HACCP-GB certification and existing Japanese import relationships rather than greenfield nigari system deployment. The signal to watch is MFDS additive harmonization negotiations with Chinese regulators, which would unlock cross-border sourcing scale for compliant processors.| Strategic Initiative | Industry Significance |
|---|---|
| Nigari Coagulation System Upgrade | Continuous precision temperature and pH control satisfies Japanese high-end restaurant texture specifications. |
| Direct-Store-Delivery Network Expansion | Same-day replenishment contracts with Chinese supermarket chains displace informal wholesale intermediaries. |
| HACCP-JAS Dual Certification Investment | Dual compliance unlocks premium Japanese import channels previously reserved for domestic producers. |
| Food-Service Crumb Line Specialization | Controlled-moisture crumb with optimized protein binding captures South Korean plant-based meat analogue reformulation demand. |
| Cold-Chain Infrastructure Buildout in Vietnam | Refrigerated express delivery enables premium silken reach where modern retail infrastructure remains sparse. |
Study Parameters
Bottom-up food-service procurement modeling reconciled against top-down soybean crushing and curd-forming capacity tracking forms the analytical core of this study. Primary interviews with quick-service restaurant procurement directors, Japanese import compliance officers, Chinese supermarket category buyers, and South Korean plant-based meat formulation scientists combined with secondary validation from SAMR GB standard filings, MFDS additive positive-list updates, Japanese customs trade statistics, and Yangtze River Delta cold-chain operator disclosures. Triangulation between demand-side menu expansion signals and supply-side coagulation system deployment patterns ensures cross-verified volume and value estimates.
Historical trendline analysis of silken versus firm tofu volume ratios across Japanese import channels and Chinese domestic retail tracked structural shifts in premiumization trajectories. Segmentation modeling across product type, form, distribution channel, and end-user application incorporates protein content thresholds, coagulant chemistry specifications, and cold-chain compatibility requirements. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Forecast inputs include QSR menu expansion timelines, certification conversion completion rates, and nigari system installation backlogs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Brazilian non-GMO soybean premium volatility, MFDS-China regulatory harmonization progress, and substitution pressure from pea and fava protein isolates in meat analogue formulations. Forecasts reflect documented assumptions on cold-chain capex deployment rates and JAS certification queue lengths. Practitioners should monitor QSR procurement contract announcements, nigari coagulation system order backlogs, and MFDS additive list revisions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sea Moss Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Halal Foods Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Dong Quai Market
Specialty Foods
Natural Honey Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Areca Bowl Market