
 Mediterranean Kimchi-Style Vegetable Culture Starters Market | 2026-2036
Mediterranean Kimchi-Style Vegetable Culture Starters Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Kimchi-Style Vegetable Culture Starters Market Insights
ISO 22000 certification is redrawing competitive boundaries for Mediterranean kimchi-style vegetable culture starters, filtering out suppliers lacking documented hazard control systems. Novonesis leverages its consolidated enzyme-culture platform to anchor supply relationships with large-scale specialty food manufacturers across Southern Europe. Sacco System specializes in region-specific strain banking, sustaining deep inventories of thermotolerant Lactobacillus lineages suited to olive-oil-adjacent fermentation protocols.
Mediterranean kimchi-style vegetable culture starters comprise defined microbial consortia—typically Lactobacillus plantarum, Pediococcus pentosaceus, and Leuconostoc mesenteroides—formulated to drive controlled lactic acid fermentation of brassica and allium vegetables in salt-reduced, olive-oil-enriched matrices. These cultures standardize pH decline, texture retention, and volatile sulfur compound profiles for shelf-stable retail products. Powder sachets dominate artisanal channels for their ambient stability and dosing precision, while liquid cultures capture share among culinary labs seeking rapid batch turnaround. Health food brands now drive fastest growth in freeze-dried pellet procurement, valuing strain-specific CFU counts for clean-label positioning.
EFSA novel food assessments and EU Regulation 1169/2011 labeling mandates shape strain documentation burdens and consumer-facing transparency requirements across member-state markets. REACH compliance for culture media substrates further constrains input sourcing for producers serving export-oriented health food brands. Stakeholders must weigh strain patent expirations against emerging national organic fermentation standards to time capacity investments and geographic prioritization.
Market Dynamics
The EU's Farm to Fork Strategy under the European Green Deal is forcing additive-free labeling requirements that push Mediterranean specialty food manufacturers toward defined-strain starter systems. This regulatory pivot is reshaping supplier qualification criteria across Spain, Italy, and Greece.
Growth Catalysts
- REACH-compliant substrate sourcing:Export-oriented health food brands now mandate documented chemical safety for culture media, filtering out non-compliant suppliers and consolidating procurement among certified producers.
- Clean-label positioning by health food brands:Strain-specific CFU counts on freeze-dried pellet packaging satisfy consumer transparency demands and command shelf space in premium retail channels.
- Artisanal producer network clustering:Dense concentrations of small-batch fermenters around Barcelona, Naples, and Thessaloniki create localized demand pools for powder sachet formats with ambient stability.
Market Restraints
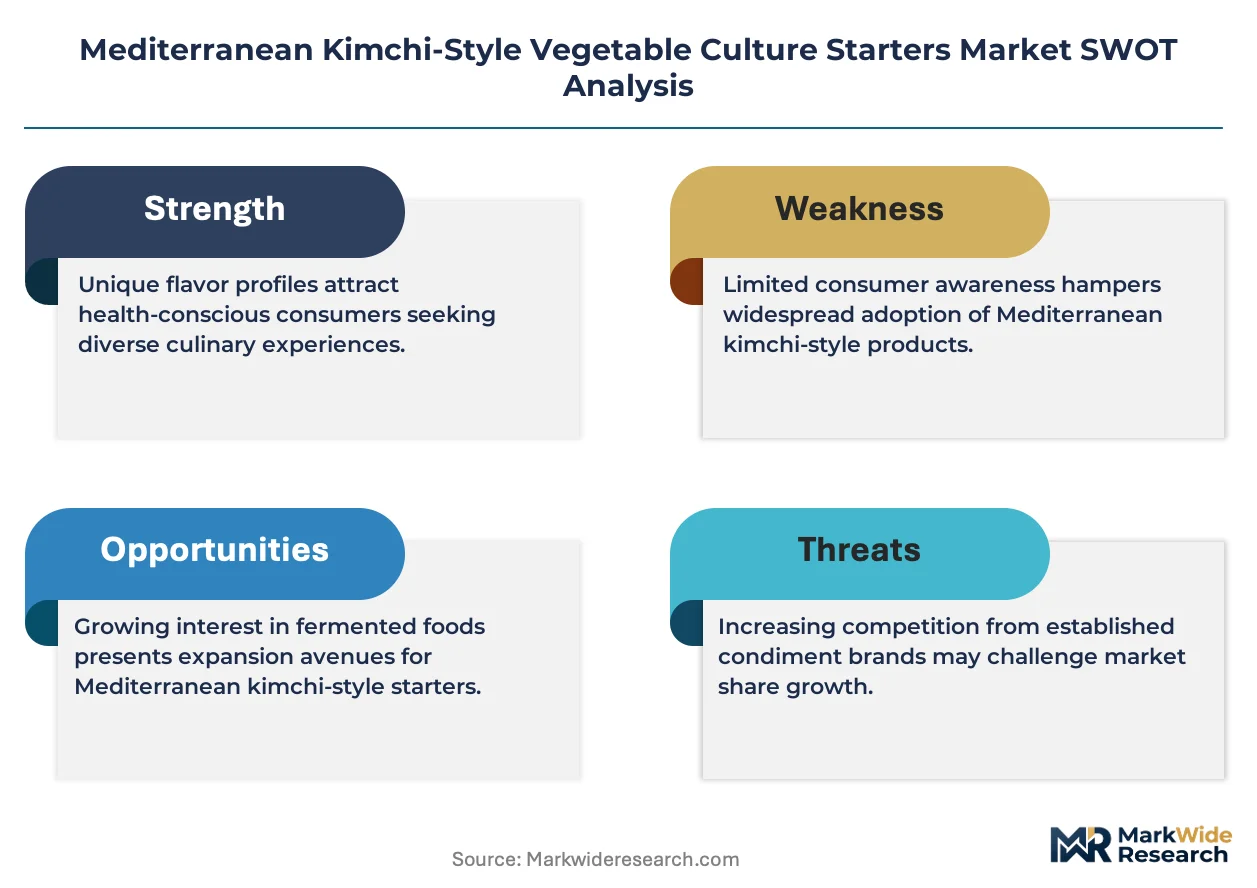
- EFSA novel food assessment timelines:Strain documentation burdens for new microbial consortia extend commercialization cycles by 18-36 months, freezing innovation pipelines for emerging suppliers.
- Olive oil price volatility:Input cost swings for cold-pressed extra virgin grades compress margins on oil-enriched fermentation matrices, forcing reformulation trade-offs.
- Defined-strain patent expirations:Loss of exclusivity on thermotolerant Lactobacillus lineages erodes technical differentiation and triggers price compression in commoditized segments.
Strategic Opportunities
- National organic fermentation standards:Emerging certification schemes in Greece and Portugal create first-mover positioning for suppliers with pre-validated organic-compliant strain banks.
- Culinary lab channel expansion:Liquid culture formats capture share among restaurant R&D facilities seeking rapid batch turnaround for menu innovation cycles.
- Reduced-salt fermentation protocols:Converging advances in osmotolerant strain selection and precision pH monitoring enable sodium-reduced positioning aligned with WHO dietary guidelines.
Industry Challenges
- ISO 22000 certification timelines:Documented hazard control system implementation stretches 12-18 months for mid-tier suppliers, delaying access to large-scale manufacturer procurement lists.
- Strain banking infrastructure capex:Cryopreservation facilities and genomic characterization equipment require seven-figure capital commitments that strain artisanal-scale balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Kimchi-Style Vegetable Culture Starters Market |
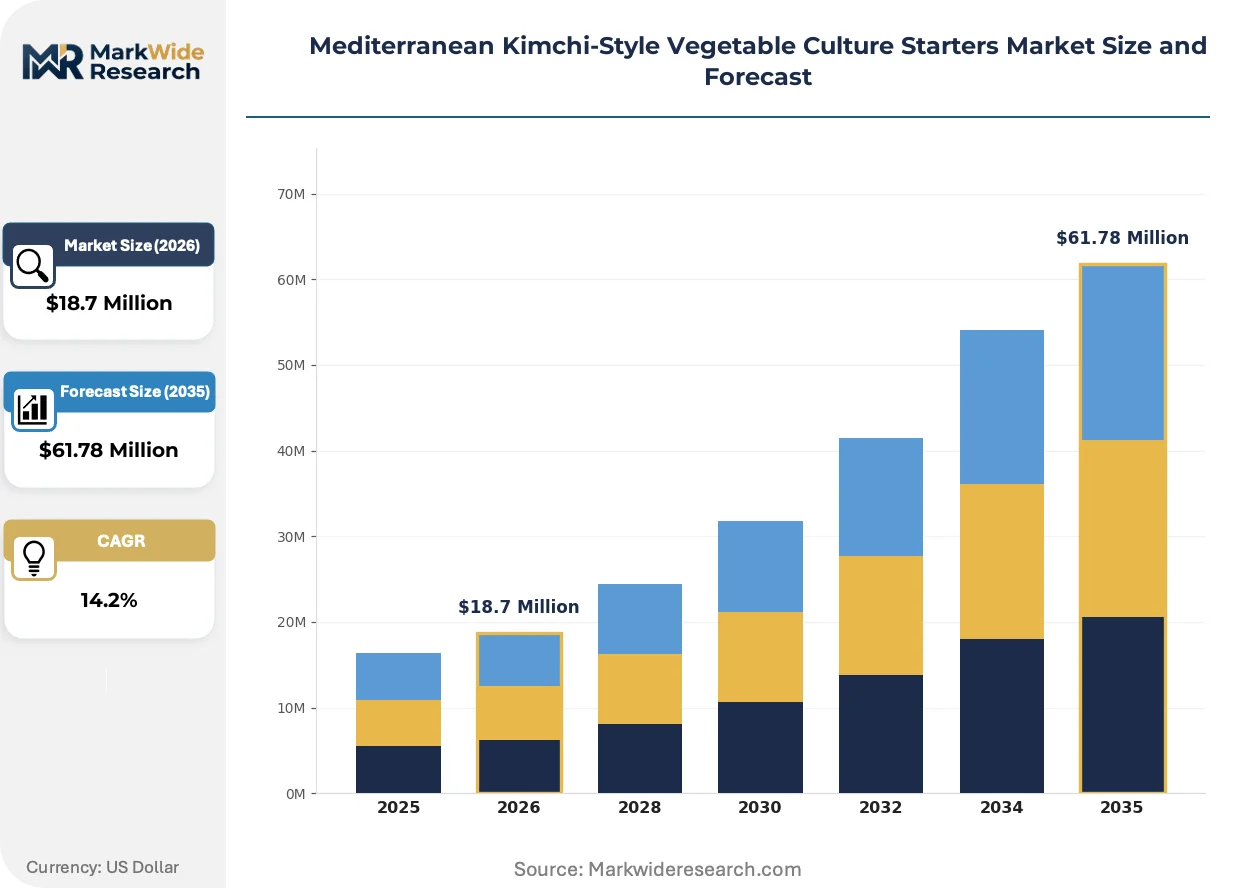
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactobacillus Plantarum, Pediococcus Pentosaceus, Leuconostoc Mesenteroides, Lactobacillus Brevis, Weissella Cibaria Application: Fermented Vegetables, Sauerkraut, Pickled Products, Spicy Kimchi Variants, Cold-Storage Ferments End User: Artisanal Producers, Specialty Food Manufacturers, Culinary Labs, Health Food Brands, Nutraceutical Firms Packaging Type: Powder Sachets, Liquid Cultures, Freeze-Dried Pellets, Concentrated Suspensions, Bulk Containers |
| Companies Covered | Novonesis, Sacco System, Lallemand Specialty Cultures, IFF, DSM-Firmenich, Chr. Hansen, Clerici-Sacco, BioGrowing, Danisco Animal Nutrition & Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Kimchi-Style Vegetable Culture Starters Market Trends and Innovations
Starter culture formulation is bifurcating between precision-defined consortia for industrial scale and terroir-linked wild ferments for premium positioning. This technical divergence is fragmenting R&D investment and reshaping supplier specialization.
Freeze-dried pellet technology is bifurcating the artisanal channel. Health food brands with clean-label mandates now specify strain-level CFU transparency, while traditional powder sachet users resist the cost premium. This split is compressing mid-tier suppliers lacking either genomic characterization capability or heritage positioning authenticity.
EU Regulation 1169/2011 labeling mandates are tightening consumer-facing transparency requirements for microbial ingredients. EFSA novel food assessments now demand full genomic sequencing documentation for new strain introductions. Small-scale producers serving export markets are responding by consolidating strain portfolios around pre-approved lineages rather than pursuing novel consortium development.
Buyer concentration among specialty food manufacturers is shortening supplier evaluation cycles. Large-scale producers in Southern Europe now mandate simultaneous ISO 22000 certification and defined-strain provenance documentation, displacing informal quality assurances. This compression is most visible in Spanish procurement offices, where technical qualification timelines have halved since 2023.
Mediterranean Kimchi-Style Vegetable Culture Starters Market Segmentation
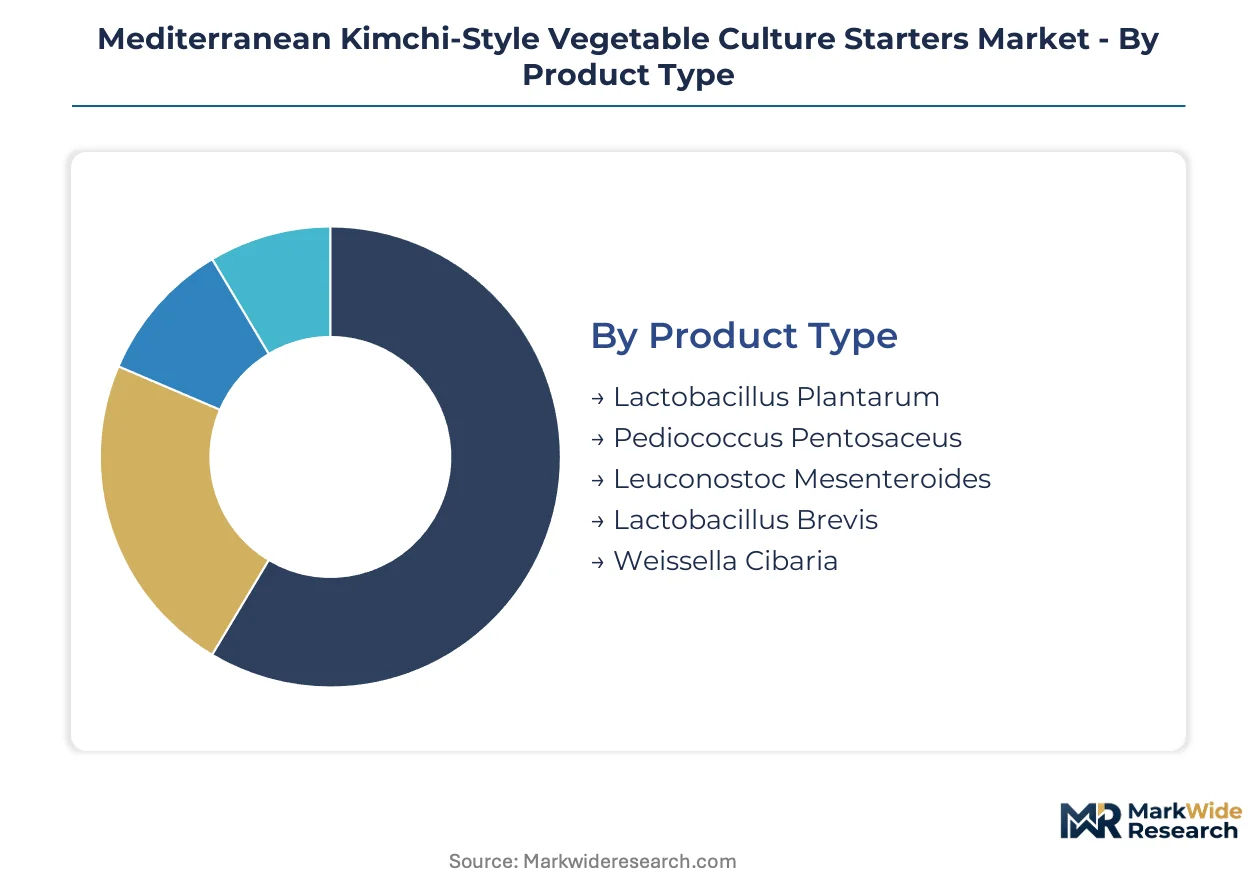
Strain specificity and packaging format choices determine competitive positioning across Mediterranean kimchi-style vegetable culture starters. Segmentation reveals divergent technical requirements between artisanal clusters in Barcelona and export-oriented health food brands demanding genomic documentation.
Product Type:
Domestic demand concentrates on thermotolerant strains suited to olive-oil-enriched matrices, while export procurement prioritizes genomic-characterized lineages for novel food dossiers.
- Lactobacillus Plantarum:Dominant workhorse strain driving rapid pH decline in salt-reduced fermentation protocols. Greek and Portuguese organic certification schemes now mandate this lineage for approved starter lists, locking in procurement preference among premium positioning suppliers.
- Pediococcus Pentosaceus:Specialized for texture retention in brassica-heavy formulations with extended shelf stability. Naples-area specialty manufacturers specify this strain for cold-storage retail products distributed across Southern Italian retail chains.
- Leuconostoc Mesenteroides:Early-stage acidifier prized for volatile sulfur compound modulation in allium-rich matrices. Spanish artisanal networks around Barcelona favor ambient-stable powder formulations containing this heterofermentative species.
- Lactobacillus Brevis:Osmotolerant lineage enabling reduced-sodium positioning aligned with WHO dietary guidelines. Health food brands in Thessaloniki cluster specify this strain for clean-label pellet procurement.
- Weissella Cibaria:Emerging candidate for terroir-linked wild ferment positioning in premium channels. Limited commercial deployment due to pending EFSA novel food assessment timelines.
Lactobacillus Plantarum holds the largest share; momentum sits with Pediococcus Pentosaceus as organic certification schemes proliferate.
Application:
Volume concentration varies sharply between mass-market fermented vegetables and niche spicy variants commanding formulation premiums.
- Fermented Vegetables:Broad-category workhorse encompassing brassica and allium bases with standardized pH targets. Italian specialty food manufacturers drive procurement consolidation through ISO 22000-mandated supplier qualification.
- Sauerkraut:Traditional cabbage-dominant format with established consumer recognition. Greek and Spanish retail channels show saturated penetration with limited strain innovation incentive.
- Pickled Products:Acidification-focused applications emphasizing shelf stability over live culture retention. Cold-pressed olive oil price volatility compresses margin on oil-enriched variants.
- Spicy Kimchi Variants:Heat-adjusted formulations requiring precise capsaicin tolerance in strain selection. Culinary labs in Barcelona and Naples drive fastest growth for rapid batch turnaround liquid cultures.
- Cold-Storage Ferments:Extended maturation protocols favoring slow acidification kinetics. Premium health food brands specify this application for probiotic count retention claims.
Fermented Vegetables anchors volume; Spicy Kimchi Variants climbs the fastest on restaurant R&D channel expansion.
End User:
Procurement sophistication separates artisanal cash buyers from nutraceutical firms demanding full genomic traceability.
- Artisanal Producers:Small-batch fermenters clustered around Barcelona, Naples, and Thessaloniki sourcing ambient-stable powder sachets. REACH-compliant substrate documentation remains inconsistent across this fragmented base.
- Specialty Food Manufacturers:Mid-scale producers with formal supplier qualification systems mandating simultaneous ISO 22000 certification and defined-strain provenance. Spanish procurement offices have compressed technical evaluation cycles substantially.
- Culinary Labs:Restaurant R&D facilities prioritizing rapid batch turnaround through liquid culture formats. Menu innovation cycles drive preference for concentrated suspensions with dosing precision.
- Health Food Brands:Clean-label positioning specialists specifying strain-specific CFU counts on freeze-dried pellet packaging. EFSA novel food assessments and EU Regulation 1169/2011 labeling mandates shape their documentation burdens.
- Nutraceutical Firms:Probiotic supplement manufacturers requiring live culture stability through gastric transit. Cryopreservation infrastructure and genomic characterization equipment demands strain banking partnerships with seven-figure capital commitments.
Specialty Food Manufacturers command the largest procurement volume; Health Food Brands gain share fastest on clean-label retail shelf space expansion.
Packaging Type:
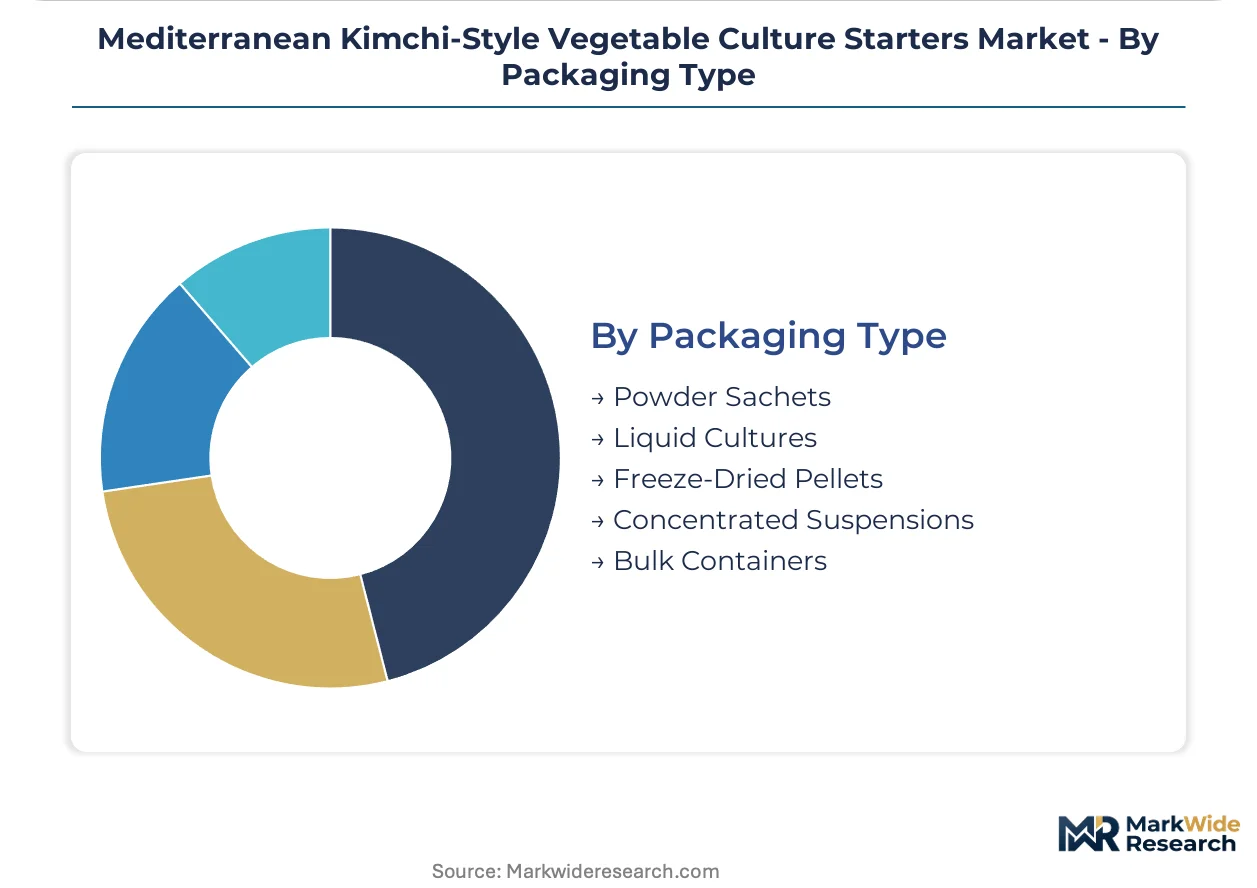
Format choice tracks directly against end-user technical capability and batch frequency requirements.
- Powder Sachets:Ambient-stable unit dosing dominating artisanal channels with limited cold chain infrastructure. Greek and Portuguese organic standards increasingly specify this format for pre-validated strain distribution.
- Liquid Cultures:Rapid-activation format capturing culinary lab share through shortened lag phases. Barcelona restaurant R&D facilities drive concentrated regional demand.
- Freeze-Dried Pellets:Strain-specific CFU transparency enabling health food brand clean-label positioning. Premium cost structure compresses mid-tier suppliers lacking genomic characterization capability.
- Concentrated Suspensions:Industrial-scale dosing efficiency for large-batch specialty manufacturers. REACH compliance for culture media substrates constrains input sourcing flexibility.
- Bulk Containers:Cost-optimized procurement for high-volume fermenters with in-house quality control. Olive oil price volatility forces reformulation trade-offs on oil-enriched matrix batches.
Powder Sachets retains dominant share; Freeze-Dried Pellets shows steepest expansion trajectory on health food brand procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Valencia anchors Iberian Peninsula distribution for olive-oil-adjacent fermentation inputs, while Adriatic rail corridors link Italian processing clusters to Balkan raw material sources.
Spain
Barcelona's artisanal fermenter network drives powder sachet procurement for ambient-stable culture distribution. EFSA novel food assessment timelines constrain strain innovation pipelines for emerging domestic suppliers. The Catalonia cluster concentrates ISO 22000-certified specialty manufacturers expanding defined-strain starter adoption.
Italy
Naples-area producers specify Pediococcus pentosaceus for cold-storage retail products across Southern Italian chains. EU Regulation 1169/2011 labeling mandates tighten consumer-facing transparency requirements for microbial ingredients. Emilia-Romagna's food technology corridor hosts mid-scale fermenters consolidating procurement around REACH-compliant substrate documentation.
Greece
Thessaloniki health food brands specify Lactobacillus brevis for reduced-sodium clean-label pellet positioning. Emerging national organic fermentation standards create first-mover positioning for suppliers with pre-validated organic-compliant strain banks. The Central Macedonia cluster concentrates culinary labs driving liquid culture format demand for rapid batch turnaround.
Portugal
Portuguese organic certification schemes mandate Lactobacillus plantarum for approved starter lists, locking procurement preference among premium suppliers. The country's national food safety regulator enforces additive-free labeling alignment with EU Farm to Fork Strategy timelines. The Lisbon-Porto corridor attracts strain banking infrastructure investment from export-oriented health food brands.
Mediterranean Kimchi-Style Vegetable Culture Starters Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and strain documentation depth, producing a bifurcated structure where consolidated enzyme-culture platforms anchor large-scale supply against fragmented artisanal strain banks. The vendor base separates into three strategic archetypes: consolidated biotechnology conglomerates with cross-enzyme fermentation expertise, regional strain banking specialists with thermotolerant lineage inventories, and mid-tier suppliers pursuing ISO 22000 certification to access manufacturer procurement lists. Dominant competitive moves include backward integration into cryopreservation infrastructure and geographic prioritization around emerging organic certification schemes.
Within the consolidated biotechnology tier, Novonesis anchors supply relationships through enzyme-culture platform consolidation, while Sacco System exemplifies the regional strain banking archetype with thermotolerant Lactobacillus lineage specialization. Lallemand Specialty Cultures occupies a position bridging industrial scale with defined-strain provenance documentation for health food brand procurement.
| Leading Market Players |
|---|
| Novonesis |
| Sacco System |
| Lallemand Specialty Cultures |
| IFF |
| DSM-Firmenich |
| Chr. Hansen |
| Clerici-Sacco |
| BioGrowing |
| Danisco Animal Nutrition & Health |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cryopreservation inventory cycles at regional strain banks concentrate supply-side pricing power among ISO 22000-certified suppliers serving Spanish and Italian specialty manufacturers, while olive oil price volatility feeds directly into fermentation matrix cost structures across Mediterranean procurement networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates genomic-characterized freeze-dried pellets from ambient-stable powder sachets and bulk liquid concentrates. Price differentiation hinges on ISO 22000 certification tier and strain-specific CFU transparency, with health food brands absorbing premium positioning costs while artisanal producers in Barcelona and Naples resist pellet format premiums. Cost compression in mid-tier powder sachets intensifies as patent expirations on thermotolerant Lactobacillus lineages erode technical differentiation. Specialty food manufacturers show lowest price sensitivity due to mandated supplier qualification systems, whereas fragmented artisanal clusters negotiate aggressively on volume.
Supply Chain Analysis
Adriatic rail corridor bottlenecks constrain cold-chain distribution of liquid culture formats from Italian processing hubs to Greek health food brands. Supply concentration rests on Spain, Italy, and Greece as primary strain banking and formulation centers, with Portugal emerging as organic certification compliance infrastructure. Raw material dependencies center on cold-pressed extra virgin olive oil, cryopreservation-grade nitrogen, and REACH-compliant culture media substrates. Single-source vulnerability characterizes thermotolerant Lactobacillus plantarum lineage supply from consolidated biotechnology platforms. Distribution runs through Port of Valencia for Iberian Peninsula anchoring, with overland corridors linking Naples-area Pediococcus pentosaceus specialists to Central Macedonia culinary labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mediterranean kimchi-style vegetable culture starters sit in early-cycle expansion as EU Farm to Fork Strategy enforcement accelerates defined-strain starter adoption among additive-free labeling compliance seekers.
For Market Incumbents: Consolidate cryopreservation infrastructure investments around Lisbon-Porto corridor organic certification pre-validation to preempt emerging Portuguese standards. Lock in backward integration into REACH-compliant substrate sourcing to defend margin position against olive oil price volatility and EFSA novel food assessment timeline extensions freezing competitor innovation pipelines.
For New Entrants and Emerging Players: ISO 22000 fast-track certification programs unlock procurement access to Spanish specialty manufacturer networks where technical evaluation cycles have compressed substantially. Target Thessaloniki health food brand clusters for Lactobacillus brevis reduced-sodium positioning, leveraging osmotolerant strain selection advances absent from incumbent portfolios. Pursue culinary lab liquid culture format white space in Barcelona restaurant R&D facilities seeking rapid batch turnaround.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier enzyme-culture platform divisions lacking genomic characterization capability to serve health food brand clean-label procurement. Long-term viability frames around strain banking infrastructure scarcity and organic certification scheme proliferation across Southern Europe. Watch EFSA novel food assessment pipeline velocity as inflection indicator for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryopreservation Infrastructure Expansion | Captures organic certification pre-validation advantage in Portugal and Greece before competitor lock-in. |
| REACH-Compliant Substrate Backward Integration | Insulates margin structures from chemical safety documentation filtering effects on export-oriented health food brands. |
| Genomic Characterization Capability Buildout | Enables strain-specific CFU transparency mandates from freeze-dried pellet procurement specialists. |
| Culinary Lab Channel Partnership | Secures liquid culture format demand from Barcelona and Naples restaurant R&D rapid batch turnaround requirements. |
| National Organic Fermentation Standard Pre-Validation | Positions first-mover supply relationships as Greece and Portugal implement additive-free labeling compliance schemes. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fermentation culture specialists and secondary validation through regulatory documentation. Interviews covered strain banking technical directors at consolidated biotechnology platforms, procurement leads at Spanish and Italian specialty food manufacturers, quality assurance officers navigating EFSA novel food dossier preparation, and supply chain managers at Port of Valencia logistics hubs. Secondary sources encompassed EU Regulation 1169/2011 implementation guidance, REACH substrate compliance registries, organic certification scheme draft standards from Greek and Portuguese regulators, and trade flow data through Mediterranean rail corridors. Bottom-up strain format demand modeling triangulated against top-down specialty food manufacturer procurement capacity estimates.
Across the analysis window, forecasts applied segment-level growth patterning across product type, application, end user, and packaging format dimensions, with additional layering for organic certification compliance tier and genomic documentation depth. CAGRs derived from adoption curve modeling for defined-strain starter systems versus wild ferment alternatives, incorporating EFSA assessment pipeline velocity and olive oil input cost trajectory assumptions. Industry-specific inputs included cryopreservation facility capacity expansion announcements and REACH-compliant substrate supplier qualification timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Farm to Fork Strategy enforcement and stable olive oil supply; material deviation in regulatory timeline acceleration or input cost spikes would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA novel food assessment throughput and national organic fermentation standard finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Halal Products Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Tahini Market