
 Hydrolyzed Egg Market | 2026-2036
Hydrolyzed Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolyzed Egg Market Foresight
Asset-light contract manufacturing and toll-processing arrangements are tilting competitive dynamics toward mid-scale entrants that lack captive spray-drying infrastructure. Rose Acre Farms leverages vertical integration from shell egg through fractionation to secure raw material cost advantages. Kewpie Corporation anchors its position through specialized enzymatic hydrolysis expertise accumulated in Japanese food processing. Bouwhuis Enthoven competes via geographic dominance across European nutraceutical supply chains.
Hydrolyzed egg denotes egg proteins—typically ovalbumin, ovotransferrin, or whole egg matrix—that have undergone enzymatic cleavage into smaller peptide fractions, generally achieving molecular weights below 10 kDa to enhance bioavailability and reduce allergenic potential. This processed ingredient serves primarily as a functional protein source in applications requiring rapid amino acid absorption, clean-label positioning, or reduced immunoreactivity compared to native egg proteins. Hydrolyzed egg protein occupies the largest value share among product types, reflecting entrenched demand from established sports nutrition brands that prioritize consistency and solubility in ready-to-mix powders. Egg white hydrolysate represents the fastest-expanding category, driven by zero-cholesterol positioning and rising adoption in geriatric nutrition and clinical dietary supplements where leucine-rich, rapidly digested protein fractions support muscle protein synthesis.
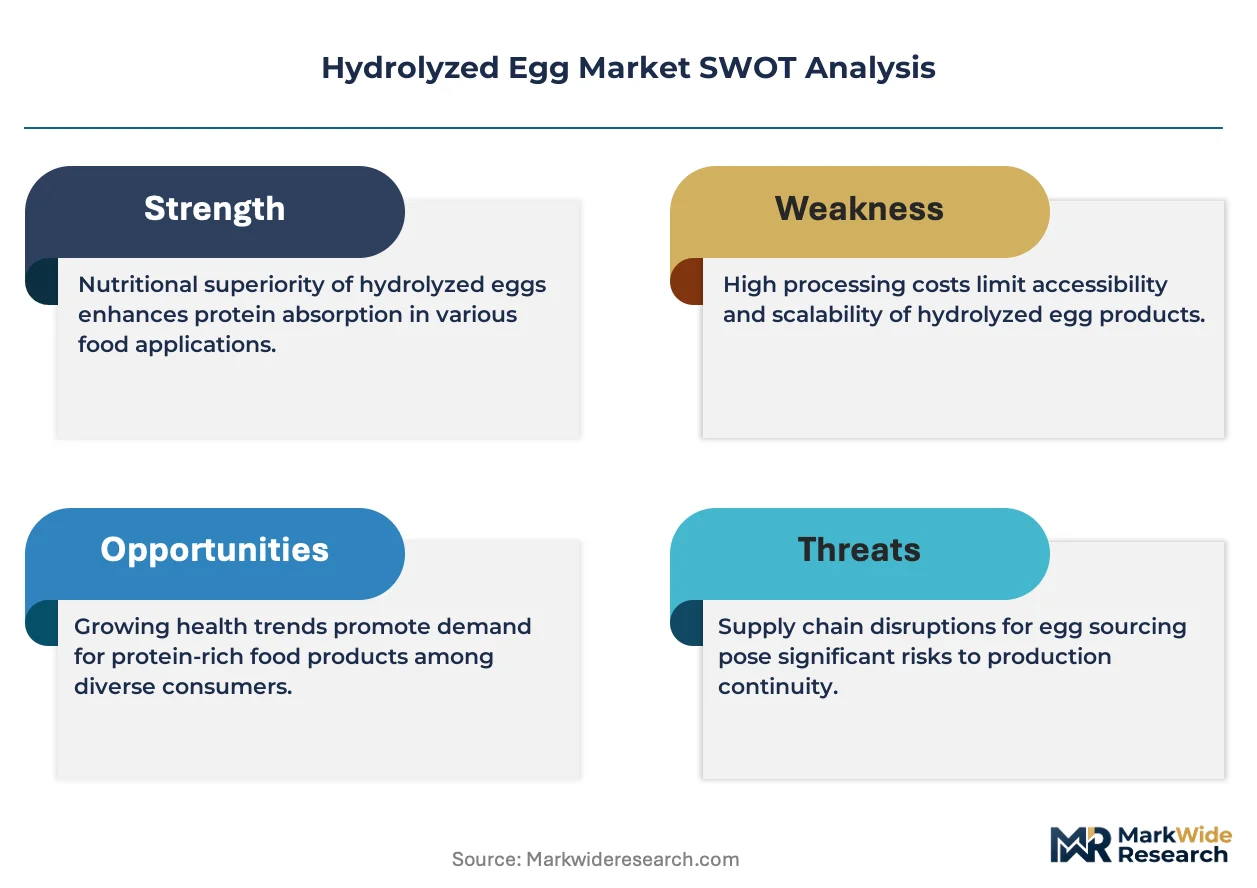
FDA food additive regulations and USDA egg products inspection standards govern manufacturing, labeling, and interstate commerce of hydrolyzed egg ingredients in the United States, while EFSA novel food assessments and EU hygiene regulations shape market access across European member states. These frameworks elevate compliance costs for new entrants but simultaneously reinforce quality premiums for certified suppliers that maintain Hazard Analysis Critical Control Point protocols and allergen control documentation. Stakeholders must monitor evolving peptide health claim authorization pathways, as regulatory recognition of specific bioactive benefits would unlock differentiated positioning in functional food and pharmaceutical channels.
Market Dynamics
Enzymatic hydrolysis scale-up is compressing production economics while fragmenting competitive advantage away from captive spray-drying infrastructure toward specialized enzyme engineering capabilities.
Growth Catalysts
- USDA Egg Products Inspection Standards:These protocols elevate quality premiums for certified suppliers, reinforcing Hazard Analysis Critical Control Point documentation that sports nutrition brands demand for liability protection.
- Sports nutrition formulation:Ready-to-mix powder manufacturers prioritize hydrolyzed egg protein for its rapid amino acid absorption kinetics and clean-label positioning.
- Midwest poultry processing clusters:Geographic concentration of shell egg supply enables toll-processors to minimize raw material transport costs and spoilage risk.
Market Restraints
- Shell egg price volatility:Feed grain costs and avian influenza outbreaks transmit directly into hydrolyzed egg input cost instability.
- Enzyme supplier concentration:Protease enzyme manufacturing concentrates among a handful of specialized biochemical suppliers, creating single-source vulnerability.
- Native egg protein substitution:Unhydrolyzed egg white powder and whey protein isolate compete on cost for applications not requiring rapid absorption.
Strategic Opportunities
- Geriatric nutrition segment:Leucine-rich egg white hydrolysate addresses sarcopenia management in aging populations with cholesterol-sensitive dietary requirements.
- EFSA novel food authorization pathway:Regulatory recognition of specific bioactive peptide health claims would unlock pharmaceutical and medical food channel access.
- Continuous-flow enzymatic reactors:Convergence of membrane filtration and immobilized enzyme technology enables real-time molecular weight fractionation with reduced batch variability.
Industry Challenges
- Peptide characterization expertise:Analytical chemists capable of validating molecular weight distribution and bioactivity markers remain scarce relative to formulation demand.
- Allergen control infrastructure:Dedicated production lines and cleaning validation protocols require capital investment that mid-scale entrants struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolyzed Egg Market |
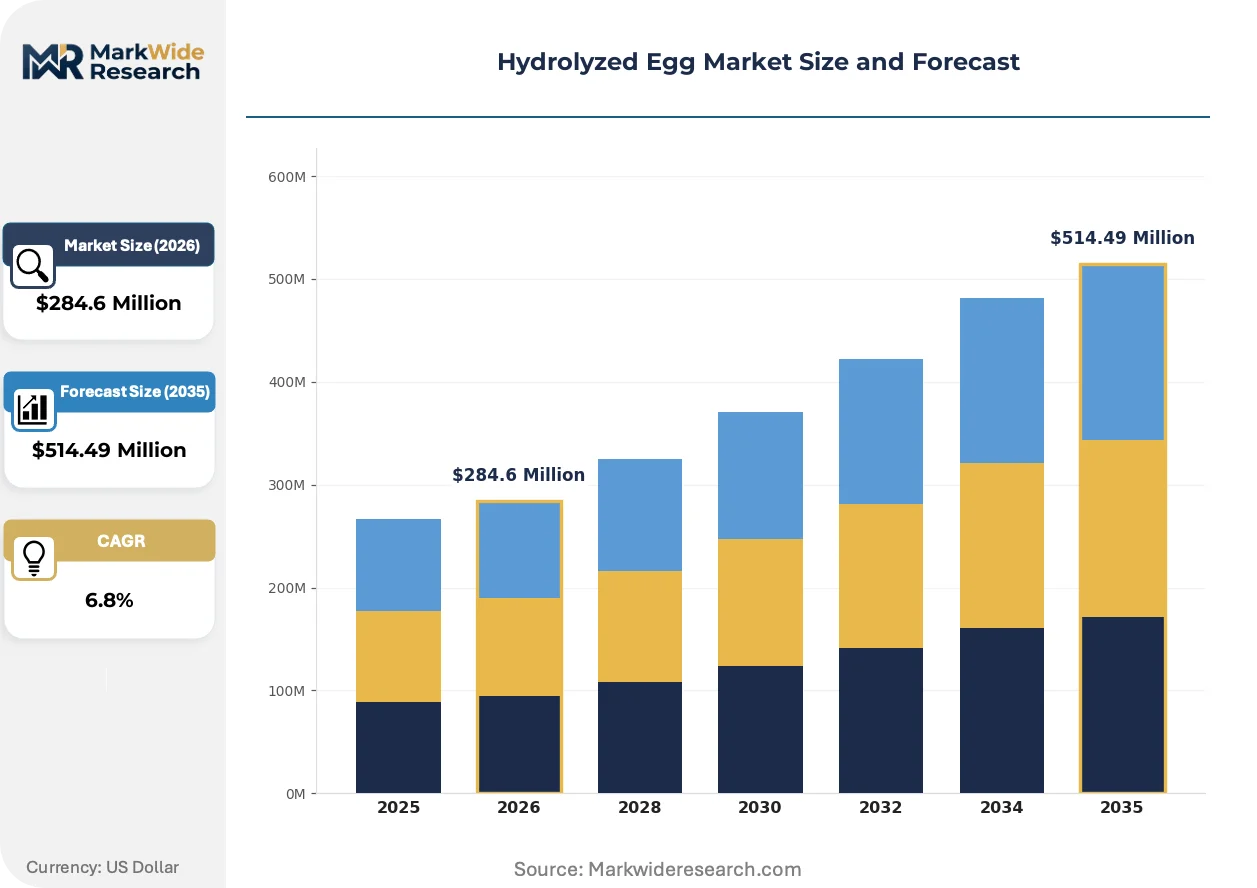
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Egg Protein, Whole Hydrolyzed Egg, Egg White Hydrolysate, Egg Yolk Hydrolysate End User: Food & Beverage, Nutraceuticals, Animal Feed, Pharmaceuticals Application: Sports Nutrition, Dietary Supplements, Functional Foods, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Rose Acre Farms, Bouwhuis Enthoven, Kewpie Corporation, Rembrandt Foods, IGRECA, Sanovo Technology Group, Merck KGaA, Herbruck's Poultry Ranch, EGGel LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolyzed Egg Market Shifts & Advancements
Process intensification and regulatory clarity are reshaping how hydrolyzed egg manufacturers compete on speed-to-market and bioactive claim substantiation.
Membrane-integrated enzymatic reactors are collapsing the traditional gap between hydrolysis and fractionation steps. California-based functional food startups adopt these systems to compress development cycles from months to weeks. The technology is collapsing batch-to-batch variability premiums that previously justified incumbent supplier relationships.
EFSA novel food assessments and EU hygiene regulations are tightening documentation requirements for peptide health claims. Manufacturers must now generate clinical evidence packages before market entry. Sports nutrition brands selling into European markets are responding by pre-qualifying suppliers with established EFSA submission track records.
Direct procurement from toll-processors is replacing distributor-mediated supply for mid-scale sports nutrition brands. These buyers now negotiate specifications directly with enzymatic hydrolysis specialists, bypassing ingredient trading houses. The United States exhibits the most pronounced shift, particularly among venture-backed functional food startups seeking supply chain transparency for investor due diligence.
Hydrolyzed Egg Market Segmentation
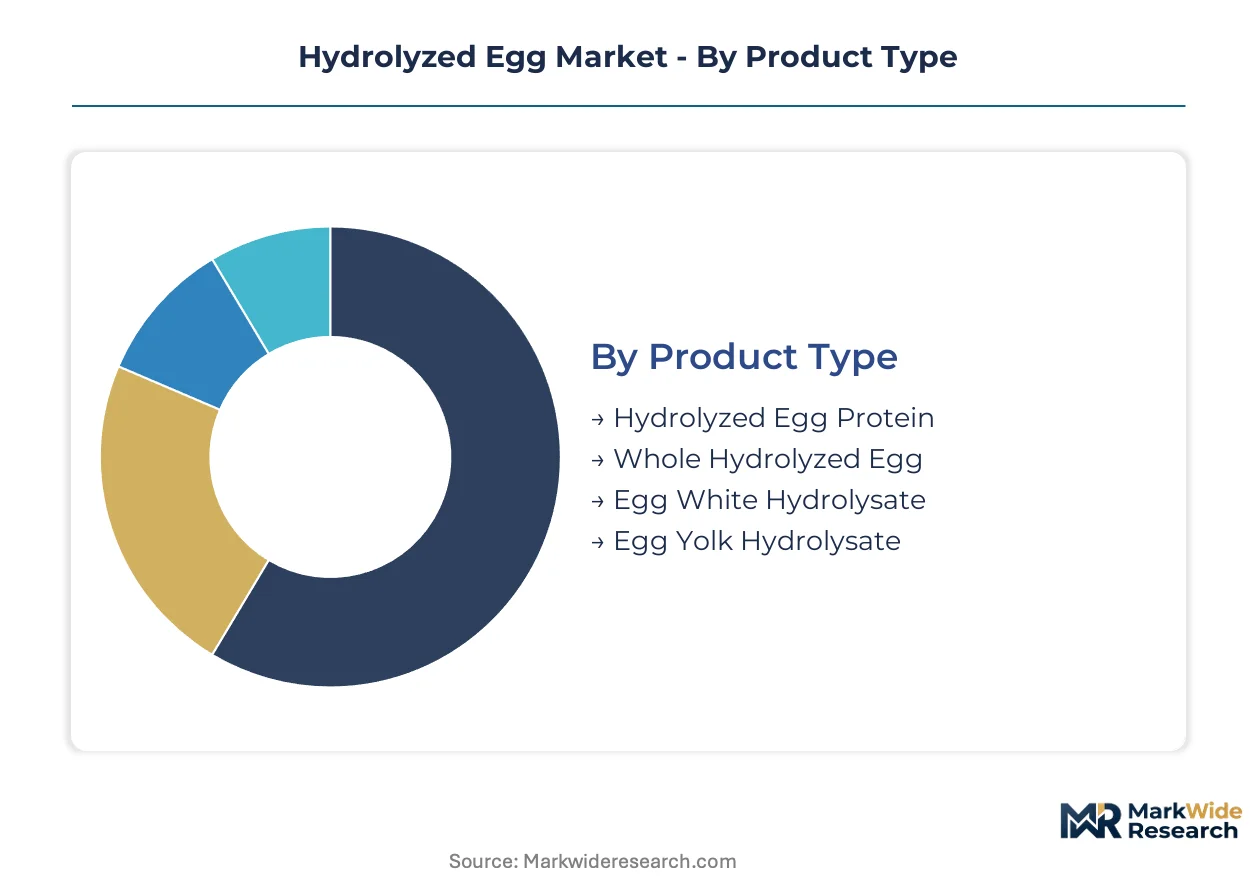
Segmentation in the hydrolyzed egg market reveals how enzymatic processing intensity and end-use specifications fragment pricing power across supply tiers. Manufacturers configure production lines around molecular weight targets and allergen thresholds that align with distinct buyer risk profiles.
Product Type:
Mature hydrolyzed egg protein formats coexist with emerging fractionated variants that command premium positioning through targeted peptide profiles.
- Hydrolyzed Egg Protein:Enzymatically cleaved whole egg matrix achieving molecular weights below 10 kDa for enhanced bioavailability. Sports nutrition brands in the United States specify this grade for ready-to-mix powders where solubility consistency reduces formulation rework.
- Egg White Hydrolysate:Fractionated ovomucin and ovalbumin peptides with zero-cholesterol positioning. Geriatric nutrition formulators source this segment for sarcopenia management applications where rapid leucine absorption takes priority over cost minimization.
- Whole Hydrolyzed Egg:Complete lipid-protein complex retaining phospholipid fractions alongside hydrolyzed peptides. Animal feed compounders utilize this grade for neonatal livestock nutrition where emulsification properties improve fat digestibility.
- Egg Yolk Hydrolysate:Phosphatidylcholine-rich hydrolysate targeting cosmetic and pharmaceutical phospholipid applications. Japanese functional food manufacturers represent the concentrated demand cluster for this specialized fraction.
Hydrolyzed egg protein handles the majority of throughput; egg white hydrolysate is expanding most quickly on share as cholesterol-sensitive positioning penetrates clinical nutrition channels.
End User:
Customer type segmentation tracks how regulatory scrutiny intensity and formulation complexity stratify procurement relationships across direct and intermediary buyers.
- Nutraceuticals:Dietary supplement manufacturers demanding batch-level peptide characterization and bioactivity documentation. FDA-compliant suppliers capture preference here due to liability exposure around structure-function claims.
- Food & Beverage:Clean-label functional food developers integrating hydrolyzed egg for emulsification and protein fortification simultaneously. California-based startups drive specification innovation through rapid product iteration cycles.
- Pharmaceuticals:Medical food and enteral nutrition formulators requiring EFSA novel food authorization or FDA medical food designation. Peptide health claim substantiation costs restrict supplier qualification to established enzymatic hydrolysis specialists.
- Animal Feed:Pet food and livestock nutrition compounders utilizing hydrolyzed egg for palatability enhancement and amino acid density. Midwest poultry processing clusters enable toll-processor relationships that compress raw material transport economics.
Nutraceuticals concentrates the highest value per kilogram; food and beverage applications are gaining share fastest as clean-label positioning penetrates mass-market retail.
Application:
Application segmentation exposes how absorption kinetics requirements and label positioning strategies fragment demand across performance-oriented and wellness-oriented use cases.
- Sports Nutrition:Ready-to-mix and ready-to-drink formulations prioritizing rapid amino acid appearance in bloodstream. Brands specify hydrolyzed egg protein for post-workout windows where whey alternatives face supply concentration risks.
- Functional Foods:Protein-fortified bars, beverages, and snacks requiring heat-stable emulsification without sensory degradation. European manufacturers lead adoption here as EFSA health claim pathways mature for peptide-specific positioning.
- Dietary Supplements:Capsule and tablet formats targeting allergen-reduced protein supplementation. Direct-to-consumer brands source through online retail channels that bypass traditional ingredient distributor markups.
- Bakery Products:Egg replacement and protein enrichment in clean-label bread and pastry applications. Volume demand concentrates in artisan and industrial bakeries seeking reduced immunoreactivity versus native egg powders.
Sports nutrition commands the dominant volume position; functional foods represent the steepest expansion trajectory as peptide characterization capabilities spread beyond specialized suppliers.
Distribution Channel:
Channel segmentation captures how buyer scale and supply chain transparency requirements reshape intermediary economics across digital and physical pathways.
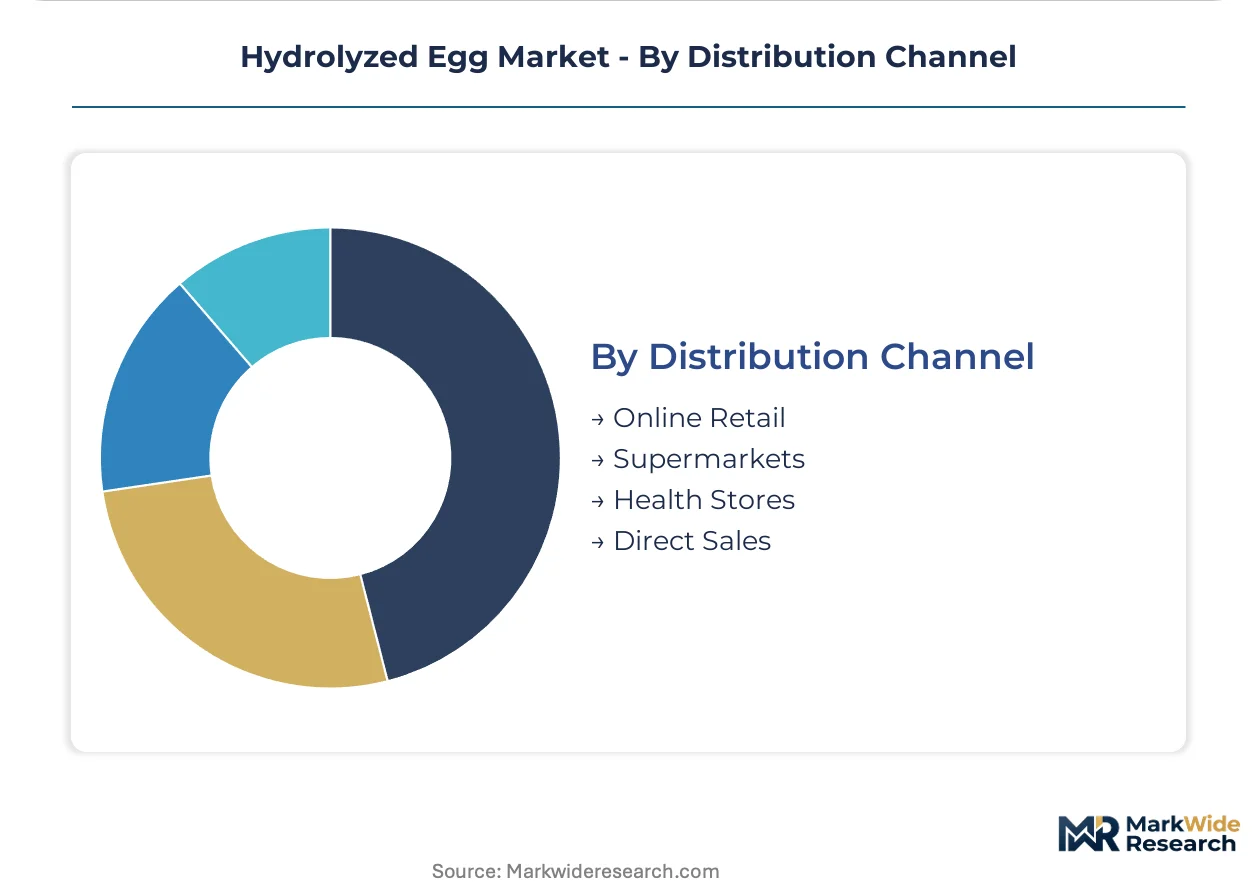
- Direct Sales:Long-term supply agreements between enzymatic hydrolysis specialists and multinational sports nutrition brands. Contract manufacturing arrangements enable mid-scale entrants to access production capacity without captive spray-drying infrastructure.
- Online Retail:E-commerce platforms serving small-batch functional food startups and direct-to-consumer supplement brands. Venture-backed California startups leverage this channel for supply chain transparency documentation during investor due diligence.
- Health Stores:Specialty retail networks curating premium-positioned hydrolyzed egg supplements for fitness and wellness consumers. Product differentiation here depends on third-party certification and peptide bioactivity marketing.
- Supermarkets:Mass-market retail placement for hydrolyzed egg ingredients in functional food and beverage formats. Shelf space competition with established protein sources constrains penetration velocity.
Direct sales manages the largest contract value throughput; online retail is climbing the fastest as startup formation accelerates and procurement bypasses traditional trading houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food additive regulations and USDA egg products inspection standards in the United States elevate compliance costs while reinforcing quality premiums for certified suppliers. EFSA novel food assessments in Europe and Japan's Food Sanitation Act create divergent pathway costs for peptide health claim substantiation. These regulatory frameworks fragment market access economics across major demand centers.
United States
Sports nutrition brands in the United States accelerate procurement of hydrolyzed egg protein for rapid-absorption formulations. USDA Egg Products Inspection Standards mandate Hazard Analysis Critical Control Point protocols that certified suppliers leverage for liability protection. Midwest poultry processing clusters in Iowa and Indiana enable toll-processors to minimize raw material transport costs and spoilage risk.
Germany
EFSA novel food authorization pathways shape pharmaceutical and medical food channel access for German formulators. REACH compliance requirements elevate documentation burdens for enzymatic hydrolysis specialists seeking peptide health claim recognition. Bavaria-based functional food developers adopt membrane-integrated enzymatic reactors to compress development cycles from months to weeks.
Japan
Japan's Food Sanitation Act and Ministry of Health, Labour and Welfare standards govern bioactive peptide marketing in functional foods. METI industrial policy supports enzymatic hydrolysis technology advancement through specialized food processing research programs. Kewpie Corporation anchors domestic expertise accumulation in Kanto region enzymatic hydrolysis specialization.
Netherlands
EU hygiene regulations and EFSA assessments concentrate European nutraceutical supply chain qualification requirements. Bouwhuis Enthoven competes via geographic dominance across Dutch and cross-border European distribution networks. Rotterdam-Antwerp logistics corridors enable efficient shell egg sourcing from surrounding poultry processing regions.
France
ANSM pharmaceutical regulations and DGCCRF consumer protection standards intersect for medical food applications of hydrolyzed egg peptides. French geriatric nutrition formulators source egg white hydrolysate for sarcopenia management in aging populations. Paris-region clinical dietary supplement developers prioritize leucine-rich, rapidly digested protein fractions.
Hydrolyzed Egg Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base distributes between vertically integrated poultry processors, enzymatic hydrolysis technology specialists, and toll-processing intermediaries. Three archetypes dominate: captive spray-drying infrastructure holders, enzyme engineering capability accumulators, and asset-light contract manufacturing arrangers. Capacity expansion and strategic partnerships represent the dominant competitive moves as mid-scale entrants bypass captive infrastructure requirements.
Among vertically integrated poultry processors, Rose Acre Farms and Herbruck's Poultry Ranch exemplify backward integration from shell egg through fractionation. Bouwhuis Enthoven occupies a position within European nutraceutical supply chain specialists. Kewpie Corporation represents Japanese enzymatic hydrolysis expertise accumulation. These three anchors illustrate how geographic origin and corporate structure map onto competitive archetype differentiation.
| Leading Market Players |
|---|
| Rose Acre Farms |
| Bouwhuis Enthoven |
| Kewpie Corporation |
| Rembrandt Foods |
| IGRECA |
| Sanovo Technology Group |
| Merck KGaA |
| Herbruck's Poultry Ranch |
| EGGel LLC |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp logistics corridors compress shell egg transport economics for European toll-processors while amplifying price spreads between FDA-certified and uncertified grades across Atlantic trade lanes.
Pricing Analysis
Certification level creates the primary spread between USDA-inspected and standard-grade hydrolyzed egg protein, with FDA food additive compliance adding a further tier. Three-tier pricing structure across premium, standard, and economy levels reflects HACCP documentation depth and peptide characterization rigor. Pricing pressure stems from whey protein isolate substitution in cost-sensitive sports nutrition applications. Mid-scale functional food startups exhibit highest price sensitivity; pharmaceutical medical food formulators show least.
Supply Chain Analysis
Asset-light contract manufacturing concentrates among mid-scale enzymatic hydrolysis specialists in the Netherlands, Iowa, and Japan. Raw material flows draw from Midwest poultry clusters, European shell egg cooperatives, and Japanese layer farms. Single-source vulnerability in protease enzyme supply creates structural risk. Distribution runs through direct long-term agreements with multinational sports nutrition brands and toll-processor arrangements for venture-backed startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrolyzed egg protein demand follows shell egg commodity cycles, with avian influenza recovery patterns setting the current upswing trajectory.
For Market Incumbents: Pre-empt native egg protein substitution by deepening peptide bioactivity documentation for EFSA novel food pathways. Expand membrane-integrated reactor capacity in Iowa to capture toll-processing demand from California functional food startups. Secure captive protease enzyme supply through backward integration into specialized biochemical suppliers.
For New Entrants and Emerging Players: French geriatric nutrition channels show underpenetration for leucine-rich egg white hydrolysate sarcopenia applications. Target direct-to-consumer online retail for allergen-reduced dietary supplements, bypassing distributor markups that constrain incumbent pricing. Lead with EFSA pre-submission engagement to differentiate against established suppliers lacking European regulatory track records.
For Investors and Strategic Acquirers: Japanese enzymatic hydrolysis technology accumulators with METI research program ties represent prime acquisition targets for pharmaceutical channel access. Long-term viability hinges on peptide health claim authorization velocity rather than commodity protein economics. Watch EFSA novel food assessment throughput rates as inflection indicator for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Pre-Submission | Unlocks pharmaceutical and medical food channel premiums ahead of competitors. |
| Membrane-Integrated Reactor Deployment | Compresses California startup development cycles from months to weeks. |
| Backward Integration into Protease Supply | Neutralizes single-source enzyme vulnerability threatening production continuity. |
| Midwest Toll-Processing Capacity Expansion | Captures Rose Acre Farms shell egg proximity advantages for cost leadership. |
| Direct-to-Consumer Channel Launch | Bypasses health store markups for margin recovery in supplement applications. |
Research Methodology
Operator-level perspectives from enzymatic hydrolysis plant managers, sports nutrition procurement directors, geriatric nutrition formulators, and FDA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from USDA egg products inspection records, EFSA novel food assessment databases, FDA food additive petitions, and Japanese Food Sanitation Act compliance filings. Bottom-up volume modeling and top-down value triangulation reconciled segment outputs.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions included product type, end user category, application use case, and distribution channel. CAGRs derived from elasticity-adjusted demand curves incorporating shell egg price volatility, enzyme cost trajectories, and peptide health claim authorization probabilities. Input assumptions tracked Midwest poultry processing cluster capacity utilization and California functional food startup formation rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by vertically integrated poultry processors or accelerated EFSA approval timelines would shift outcomes. Cross-checking against USDA shell egg inventory reports and EFSA assessment queue depth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Lipids Market
Ingredients
Mirepoix Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Maracuja Oil Market
Ingredients
China Gelatin Market
Ingredients
Dill Seed Oil Market
Ingredients
Coconut Cream Powder Market
Ingredients
Banana Flour Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Ice Cream Bases Market
Ingredients
Pea Starch Market
Ingredients
Roll-Dried Starch Market