
 Middle East and Africa Enterprise Software Market | 2026-2036
Middle East and Africa Enterprise Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Enterprise Software Market Foresight
Cloud-native architecture is reconfiguring how enterprise software vendors deliver value across the Middle East and Africa. SAP MENA leverages deep localization capabilities to anchor its position in Gulf Cooperation Council public-sector modernization programs. Oracle Middle East competes aggressively on database-to-application stack integration for large energy and petrochemical clients. Microsoft Gulf extends its cloud footprint through sovereign data center partnerships in the UAE and Qatar.
Enterprise software encompasses integrated application suites that automate business processes through modular functional components including financial ledger engines, customer data platforms, and supply chain optimization algorithms, typically deployed via client-server or browser-based architectures with API interoperability layers. ERP Software retains the largest installed base across manufacturing and finance verticals, though margin pools are shifting toward cloud-based deployment models as subscription economics displace perpetual licensing. CRM Software represents the fastest-expanding segment within retail and healthcare industry verticals, driven by customer data platform investments and omnichannel engagement requirements.
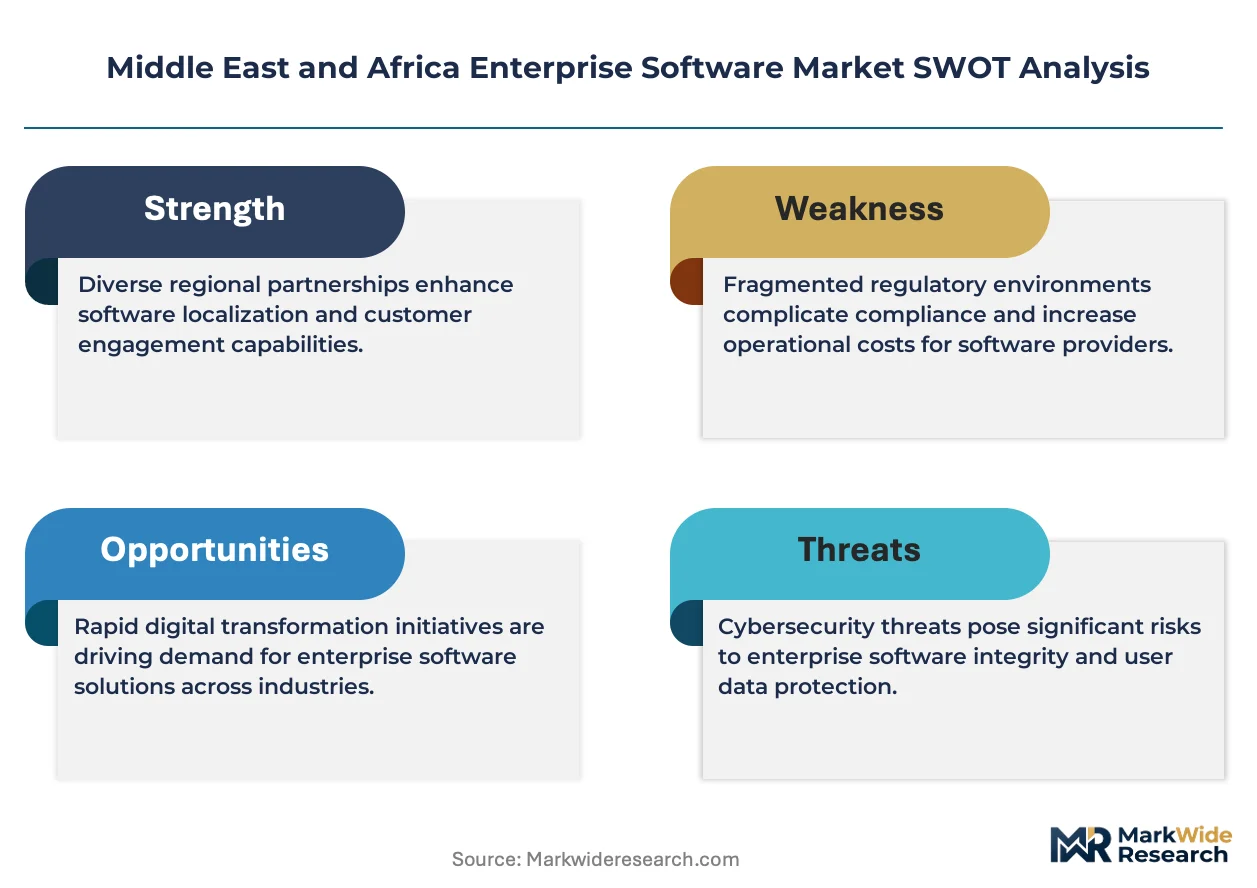
Saudi Arabia's National Data Management Office standards, South Africa's Protection of Personal Information Act, and UAE cybersecurity certification frameworks collectively reshape procurement criteria and vendor qualification pathways across the region. SAMR-equivalent national regulators in Gulf states enforce data sovereignty requirements that favor hybrid deployment architectures over pure public cloud. Stakeholders must weigh localization compliance costs against scalability gains when selecting deployment models for multi-country operations.
Market Dynamics
Cloud-native deployment architectures are compressing enterprise software procurement cycles across the Middle East and Africa, as Saudi Arabia's Vision 2030 mandates and UAE data sovereignty requirements force vendors to reconfigure delivery models around hybrid infrastructure.
Growth Catalysts
- Saudi Vision 2030 Digital Mandates:Public-sector modernization programs in the Kingdom are mandating ERP and CRM platform upgrades across government entities, creating concentrated demand for localized enterprise suites.
- API-First Integration Standards:Open banking frameworks in Nigeria and Kenya are compelling financial institutions to replace legacy core systems with modular, interoperable software stacks.
- UAE Data Sovereignty Partnerships:Sovereign cloud certification requirements are accelerating hybrid deployment investments among Dubai and Abu Dhabi headquartered multinationals.
Market Restraints
- USD-Denominated Licensing Costs:Currency volatility against the dollar elevates total cost of ownership for subscription-based enterprise software across import-dependent African markets.
- Concentrated Cloud Infrastructure:Hyperscaler data center presence clusters in Johannesburg, Dubai, and Riyadh, creating latency and failover risks for operations in secondary cities.
- South Africa POPIA Compliance Friction:Cross-border data transfer restrictions under the Protection of Personal Information Act complicate multi-country ERP deployments for regional headquarters.
Strategic Opportunities
- Ethiopia Manufacturing Digitalization:Industrial park expansion and foreign direct investment inflows are creating first-mover advantages for ERP vendors targeting textile and agro-processing verticals.
- Converged AI-ERP Platforms:Natural language interfaces and predictive analytics modules are opening premium pricing tiers among Gulf Cooperation Council energy and logistics operators.
- Egypt Fintech Regulatory Sandbox:Central Bank of Egypt licensing flexibility is enabling cloud-native core banking software pilots with faster deployment timelines than traditional on-premise procurement.
Industry Challenges
- Scarce Cloud Architecture Expertise:Kubernetes and microservices specialization remains concentrated in Dubai, Lagos, and Cape Town, inflating implementation costs for complex multi-tenant deployments.
- Legacy System Integration Complexity:COBOL and mainframe dependencies in South African banking and Nigerian telecom sectors extend migration timelines and erode projected ROI on cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Enterprise Software Market |
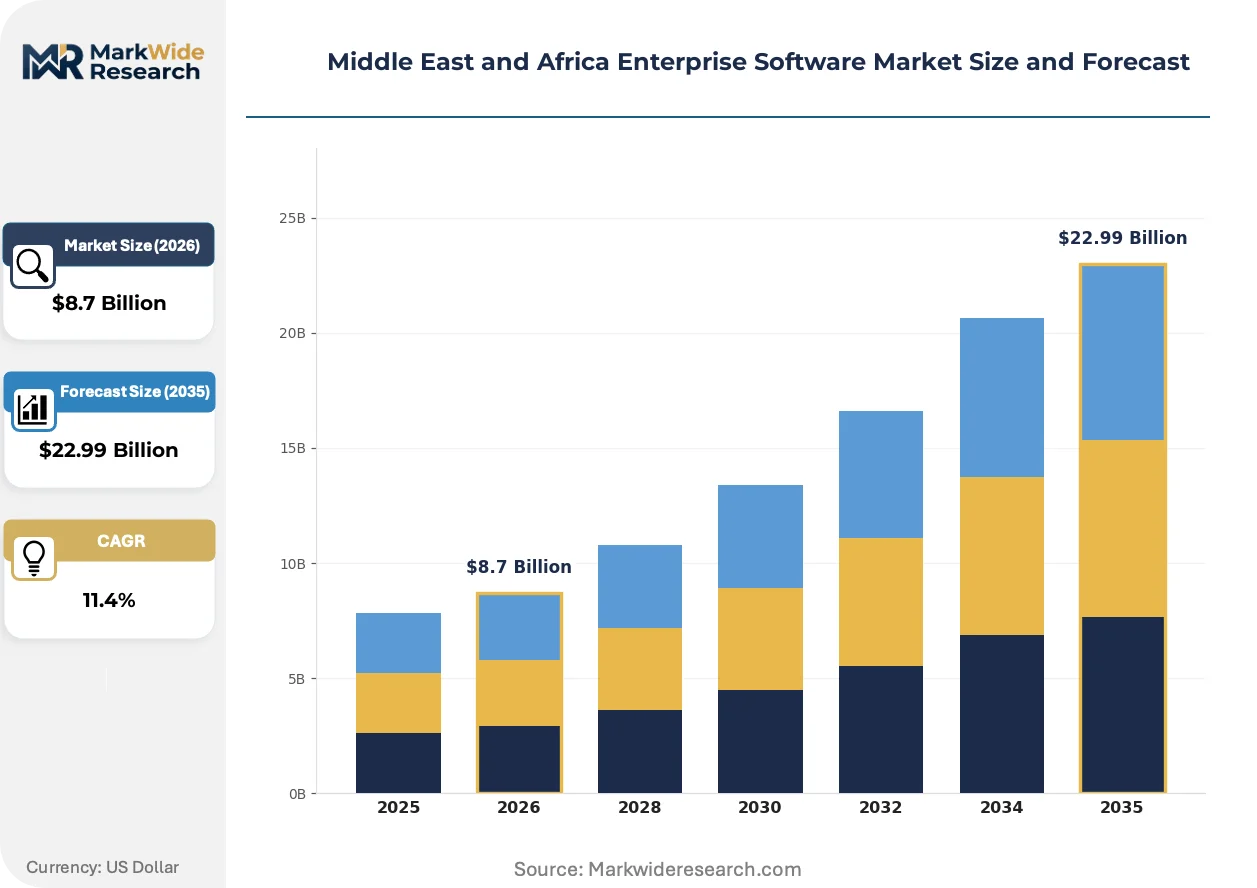
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM Software, ERP Software, HR Management Systems, Supply Chain Management Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: SMEs, Large Enterprises, Government Entities, Non-Profit Organizations Industry Vertical: Healthcare, Retail, Manufacturing, Finance |
| Companies Covered | SAP MENA, Oracle Middle East, Microsoft Gulf, Salesforce MENA, IBM Middle East, Infor Middle East, Sage Middle East, Zoho Corporation, ServiceNow, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Enterprise Software Market Shifts & Advancements
Enterprise software value delivery is fragmenting across deployment models, as buyers in the Middle East and Africa weigh data residency obligations against elasticity requirements. Three distinct shifts are restructuring competitive positioning.
Containerized microservices architectures are redefining how ERP and CRM functionality is packaged and consumed. Large energy and logistics operators in the UAE and Saudi Arabia are adopting Kubernetes-orchestrated workloads at scale. Monolithic suite licensing is migrating from perpetual enterprise agreements toward modular, API-connected component subscriptions.
Saudi Arabia's National Data Management Office standards, alongside South Africa's Protection of Personal Information Act and UAE cybersecurity certification frameworks, are collectively rewriting vendor qualification pathways. Procurement committees now require proof of in-country data processing capabilities before shortlisting. Hybrid deployment architectures are gaining preference over pure public cloud among multi-country operators seeking compliance coverage.
Enterprise buyers are unbundling implementation and managed services from software licensing, treating these as separately negotiated line items. Systems integrators in Dubai and Johannesburg are capturing margin pools that previously accrued to software vendors. This disaggregation is most pronounced among South African financial services institutions modernizing core banking platforms under regulatory pressure.
Middle East and Africa Enterprise Software Market Segmentation
Enterprise software procurement across the Middle East and Africa fragments sharply by deployment model and organizational scale. Buyers in Riyadh, Dubai, and Johannesburg weigh data sovereignty mandates against elasticity requirements when selecting platform architectures.
Product Type:
Use-case spectrum spans transactional automation at the operational layer through strategic decision-support at the executive tier.
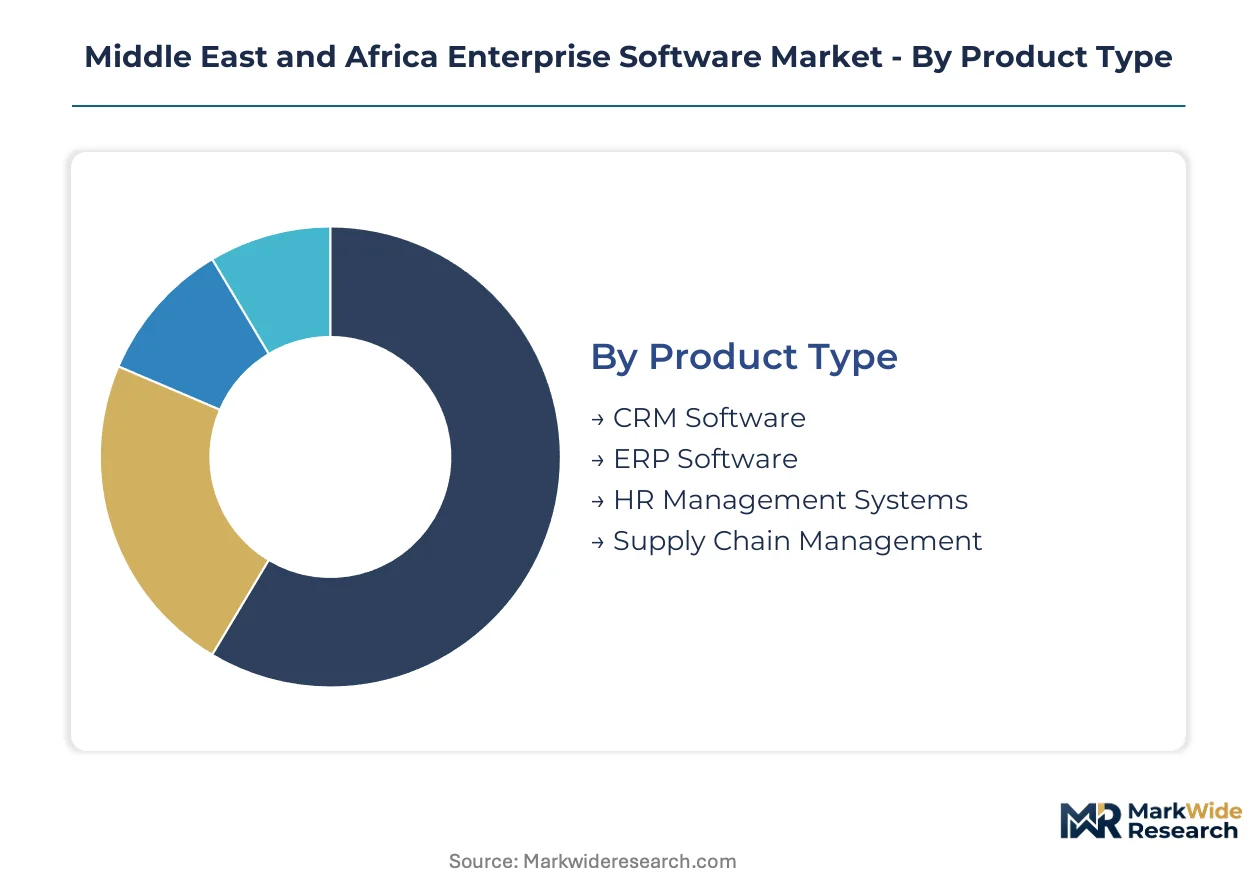
- CRM Software:Customer data platforms aggregate interaction histories across touchpoints for predictive engagement scoring. Retail chains in South Africa and healthcare networks in the UAE are consolidating fragmented point solutions into unified omnichannel suites.
- ERP Software:Integrated financial ledger, procurement, and inventory modules run on either monolithic or microservices architectures. Saudi government entities under Vision 2030 mandates are driving concentrated demand for localized Arabic-language deployments.
- HR Management Systems:Payroll, talent acquisition, and workforce analytics modules with Gulf-specific Wage Protection System integrations.
- Supply Chain Management:Demand forecasting and logistics optimization tools for petrochemical and port operators across the GCC.
The dominant share belongs to ERP Software, while CRM Software is closing the gap fastest.
Deployment:
Cost tier differentiation separates sovereign-certified premium offerings from standardized public cloud alternatives.
- On-Premises:Legacy client-server installations in South African banking and Nigerian telecom retain COBOL dependencies that extend migration timelines. These deployments satisfy strict data residency requirements but carry elevated total cost of ownership.
- Cloud-Based:Hyperscaler-hosted SaaS with automatic patching and elastic compute provisioning. Nigerian fintech startups and Kenyan open banking participants are bypassing on-premise infrastructure entirely.
- Hybrid:Sensitive workloads process locally while analytics layers run in sovereign cloud zones. Dubai and Abu Dhabi headquartered multinationals favor this architecture for POPIA and NDMO compliance coverage.
- Multi-Tenant:Shared infrastructure with tenant isolation via containerized namespaces, lowering per-seat economics for SME segments.
Hybrid deployments command premium pricing, though Cloud-Based alternatives are expanding most quickly among digitally native entrants.
End User:
Customer type determines implementation complexity and support intensity.
- SMEs:Modular, API-first subscriptions with rapid deployment templates. Egyptian fintech sandbox participants and Ethiopian manufacturing park tenants prioritize speed-to-value over customization depth.
- Large Enterprises:Multi-country ERP rollouts requiring change management at scale. Energy and logistics operators in the UAE and Saudi Arabia are converging AI modules with core platforms.
- Government Entities:Sovereign data center mandates with Arabic localization and accessibility compliance.
- Non-Profit Organizations:Grant-funded implementations with constrained professional services budgets.
Large Enterprises retain the deepest installed base, while Government Entities are climbing the fastest under digital transformation mandates.
Industry Vertical:
Application requirements vary by regulatory exposure and operational velocity.
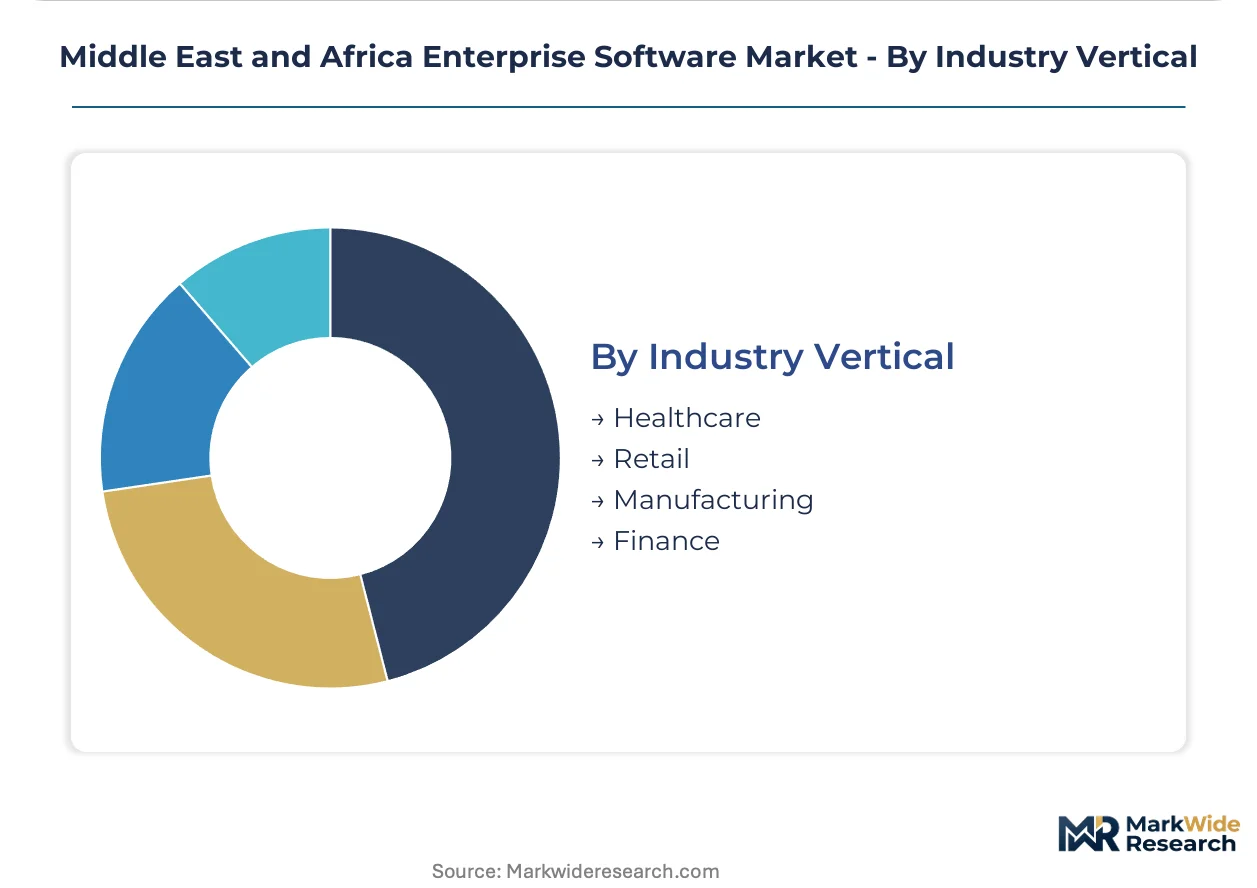
- Healthcare:Patient data platforms with clinical workflow integration and Ministry of Health reporting compliance.
- Retail:Omnichannel inventory and customer engagement systems for mall operators and e-commerce hybrids.
- Manufacturing:Shop-floor IoT integration and predictive maintenance modules for Ethiopian textile and agro-processing facilities.
- Finance:Core banking replacement and open API layers under Central Bank of Egypt and South African Reserve Bank supervision.
Finance verticals absorb the highest per-seat licensing values, with Manufacturing gaining share fastest through industrial park digitalization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public-sector digital transformation mandates and financial services modernization programs concentrate enterprise software procurement across the Middle East and Africa. Buyers in Riyadh, Dubai, and Johannesburg prioritize data sovereignty compliance alongside cloud scalability when evaluating platform vendors.
Saudi Arabia
Government entities under Vision 2030 directives are replacing legacy systems with localized Arabic-language ERP suites. The National Data Management Office enforces strict data residency standards that favor hybrid cloud architectures. Riyadh's King Abdullah Financial District hosts concentrated demand from banking and logistics operators converging AI modules with core platforms.
United Arab Emirates
Dubai and Abu Dhabi headquartered multinationals are procuring sovereign-certified cloud solutions to satisfy UAE cybersecurity certification frameworks. The Dubai International Financial Centre drives premium demand for customer data platforms among wealth management and retail banking clients. Sovereign data center partnerships with hyperscalers are accelerating hybrid deployment adoption across the Emirates.
South Africa
Financial institutions in Johannesburg and Cape Town are modernizing core banking systems under Protection of Personal Information Act compliance pressure. Cross-border data transfer restrictions complicate multi-country ERP deployments for regional headquarters. The Johannesburg Stock Exchange vicinity concentrates demand for risk management and regulatory reporting modules.
Egypt
Fintech startups in Cairo are bypassing on-premise infrastructure entirely through Central Bank of Egypt regulatory sandbox approvals for cloud-native core banking pilots. Industrial digitalization programs in the Suez Canal Economic Zone are creating first-mover opportunities for manufacturing ERP vendors. Cairo's Smart Village technology cluster anchors software implementation and systems integration capacity.
Nigeria
Open banking frameworks mandated by the country's national banking regulator are compelling Lagos-based financial institutions to replace legacy core systems with modular API-first stacks. Currency volatility elevates total cost of ownership concerns for USD-denominated subscription licensing. Lagos and Abuja concentrate cloud architecture expertise, though Kubernetes specialization remains scarce outside these metros.
Middle East and Africa Enterprise Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment model and localization capability vectors. The vendor base clusters around three strategic tiers: hyperscaler-aligned platform providers with sovereign cloud certifications, legacy suite vendors with deep Arabic localization, and emerging API-first specialists targeting fintech verticals. Dominant competitive moves include strategic partnerships with national data center operators and portfolio diversification into converged AI-ERP modules.
Within the hyperscaler-aligned tier, Microsoft Gulf and Oracle Middle East occupy positions defined by database-to-application stack integration and sovereign infrastructure partnerships. SAP MENA anchors the legacy localization specialist archetype through Gulf Cooperation Council public-sector relationships. Among emerging challengers, Zoho Corporation exemplifies the API-first, rapid-deployment model gaining traction with Egyptian fintech sandbox participants and Ethiopian manufacturing park tenants.
| Leading Market Players |
|---|
| SAP MENA |
| Oracle Middle East |
| Microsoft Gulf |
| Salesforce MENA |
| IBM Middle East |
| Infor Middle East |
| Sage Middle East |
| Zoho Corporation |
| ServiceNow |
| Others |
Supply & Pricing Matrix
The Red Sea shipping corridor's freight cost volatility directly shapes supply concentration and downstream pricing tiers for enterprise software vendors serving Middle East and Africa markets. Currency fluctuations against the dollar amplify total cost of ownership disparities between sovereign-certified hybrid deployments and standardized public cloud alternatives.
Pricing Analysis
Cost-plus contracts indexed to USD-EUR exchange rates dominate enterprise licensing agreements across Gulf Cooperation Council states. Three-tier pricing structure across premium sovereign-certified, standard regional cloud, and economy multi-tenant tiers reflects data residency compliance depth and localization investment. Pricing pressure stems from Nigerian naira and Egyptian pound depreciation against dollar-denominated subscriptions. SMEs in Ethiopian manufacturing parks exhibit highest price sensitivity, while UAE energy operators accept premium tiers for AI-ERP convergence.
Supply Chain Analysis
Supplier-financing facilities with 90-180 day extended payment terms anchor distributor relationships for legacy suite vendors across Dubai and Johannesburg hubs. Software development capacity concentrates in India, Ireland, and Poland for Arabic localization and cloud architecture specialization. Raw material dependencies span semiconductor chips for data center infrastructure, optical fiber for submarine cable connectivity, and lithium for backup power systems. Single-source vulnerability runs through concentrated hyperscaler data center presence in Johannesburg, Dubai, and Riyadh. Distribution runs through systems integrator partnerships in Dubai International Financial Centre and Johannesburg Sandton precinct.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vision 2030 digital mandates and open banking regulatory frameworks are accelerating high-growth disruption across Middle East and Africa enterprise software procurement. Sovereign data residency requirements and AI-ERP convergence create dual inflection points for vendor positioning.
For Market Incumbents: Entrench Gulf Cooperation Council public-sector relationships through National Data Management Office certification investments and sovereign cloud infrastructure partnerships. Deepen Arabic localization capabilities to defend against API-first challengers targeting fintech verticals. Prioritize AI module integration with core ERP platforms to capture premium pricing tiers among Saudi energy operators. For New Entrants and Emerging Players: Mid-market Egyptian fintech sandbox participants and Ethiopian manufacturing park tenants represent the most penetrable entry points for rapid-deployment SaaS models. Kenya's open banking framework compliance gaps offer white-space for modular core banking replacements. Lead with API-first architectures and pre-configured industry templates to bypass incumbent implementation timelines. For Investors and Strategic Acquirers: Saudi Arabia's NDMO certification deadlines reshape the acquisition landscape toward vendors with proven sovereign cloud deployments. Long-term viability centers on hybrid architecture expertise and regional systems integrator channel control. Target acquisition archetypes include Kubernetes-specialist implementation firms and Arabic-language localization studios. Monitor Central Bank of Egypt regulatory sandbox expansion rates as inflection indicator for cloud-native core banking demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | UAE cybersecurity framework compliance unlocks Dubai and Abu Dhabi multinational procurement committees. |
| AI-ERP Module Integration | Saudi Aramco and ADNOC logistics operators drive premium pricing for predictive analytics capabilities. |
| API-First Platform Architecture | Nigerian open banking mandates force legacy core system replacements at Lagos-based institutions. |
| Arabic Localization Investment | Saudi Vision 2030 government mandates require Wage Protection System and NDMO-compliant deployments. |
| Systems Integrator Partnership | Johannesburg and Dubai channel partners capture implementation margin pools from disaggregated procurement. |
Research Methodology
Cross-validation between vendor pricing disclosures and enterprise procurement committee documentation anchors the qualitative findings in this study. Primary interviews with CTOs at Saudi government entities, IT procurement officers at UAE energy operators, platform engineers at Nigerian fintechs, and channel partners in Dubai International Financial Centre combined with secondary validation from SEC filings, hyperscaler capex disclosures, and Central Bank of Egypt regulatory notices. Bottom-up deployment volume estimates and top-down addressable market sizing triangulate across the analysis window.
Calibration against historical adoption curves in comparable emerging markets shapes the analytical framework across deployment model, organization size, vertical, and regional adoption pattern dimensions. CAGRs derive from segment-level growth rate reconciliation with macroeconomic drivers. Forecast inputs include Vision 2030 budget allocation trajectories and open banking regulatory implementation timelines.
Practitioners should monitor currency volatility against the dollar and sovereign certification deadline acceleration for early signals of pricing tier compression or deployment model shifts. Forecasts reflect documented assumptions about regulatory implementation pace and hyperscaler infrastructure expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
IoT Professional Services Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Field Service Management Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Enterprise Social Graph Market