
 Consumer Technical Support Services Market | 2026-2036
Consumer Technical Support Services Market Size, Share, and Industry Trends Forecast 2026-2036
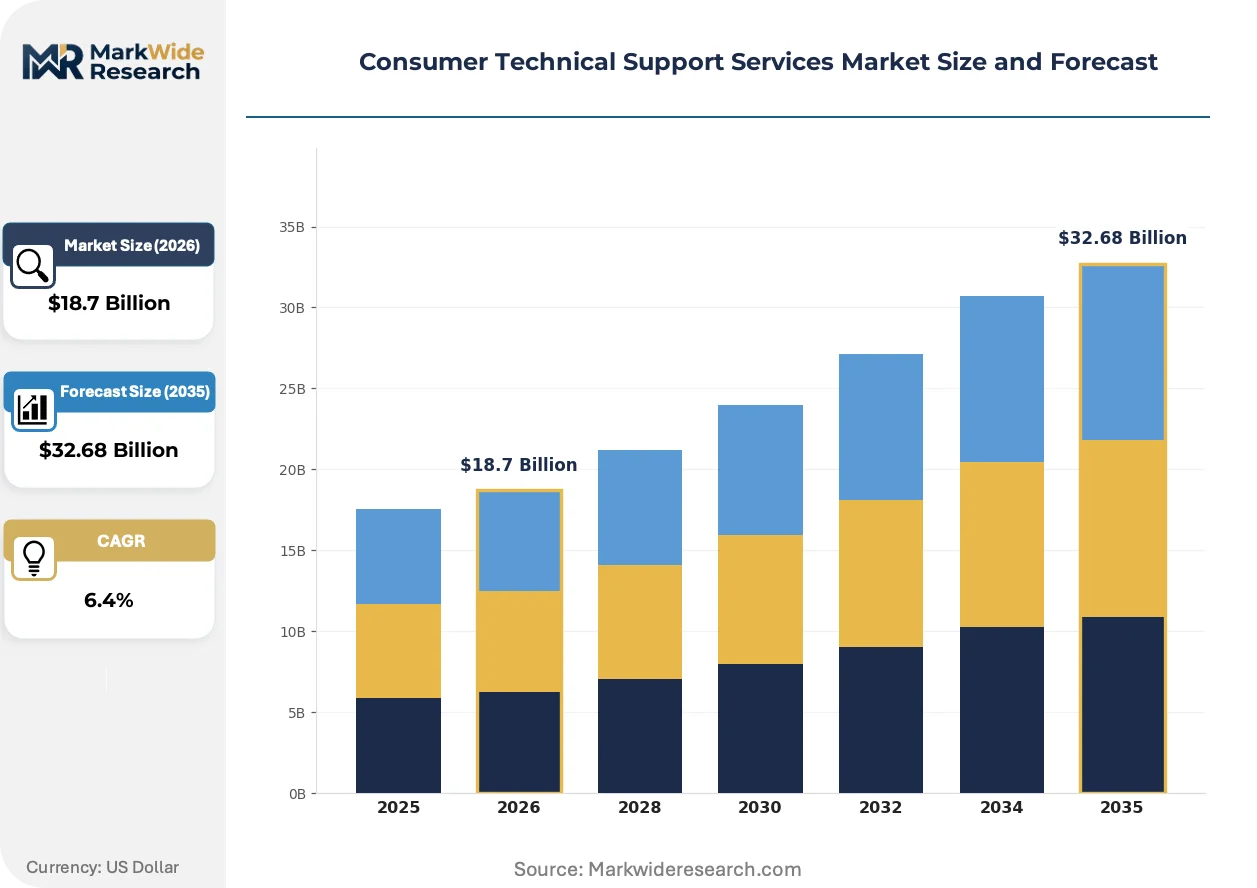
Consumer Technical Support Services Market Outlook
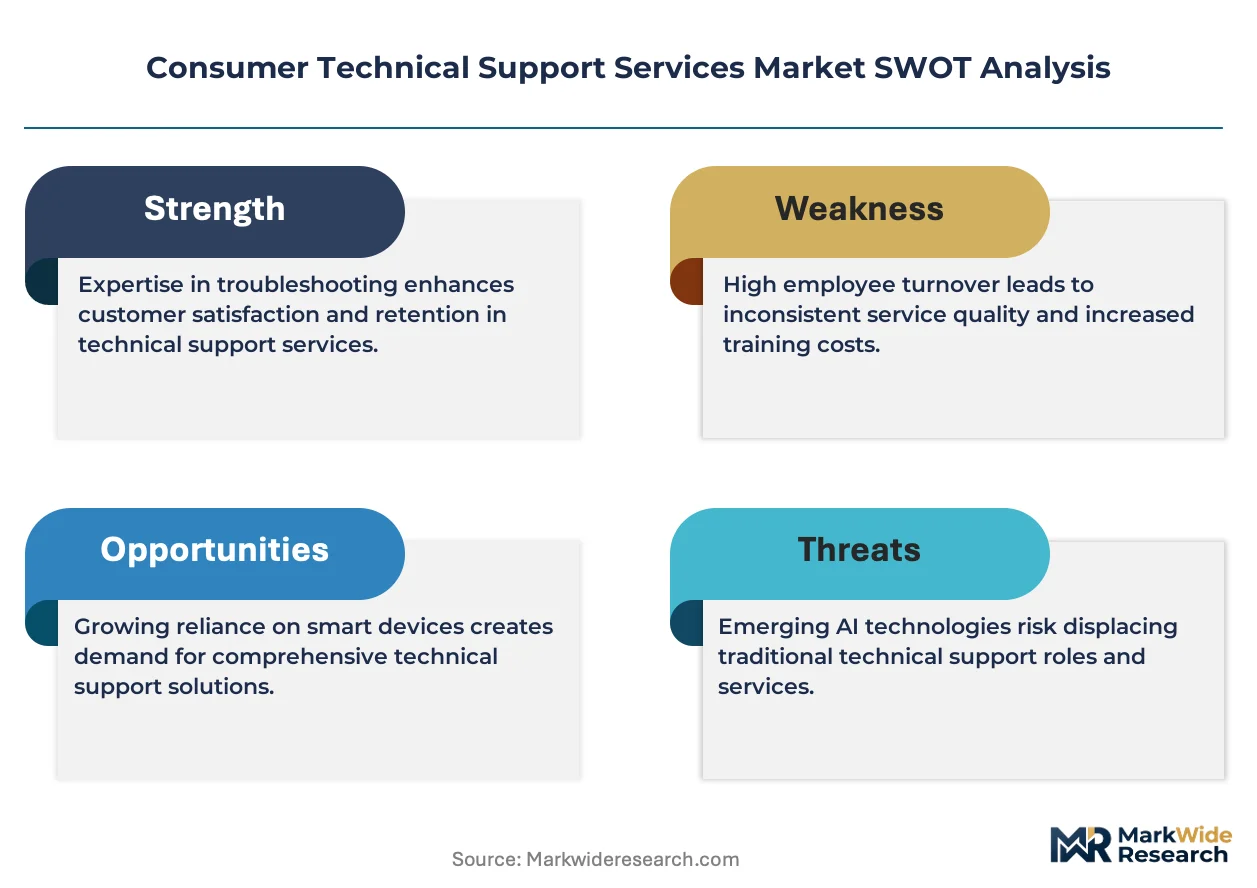
The EU Green Deal is expanding requirements for energy-efficient data centers that power remote technical support infrastructure. Teleperformance leverages its Philippines and Latin America footprint to sustain cost-competitive voice operations. Sutherland anchors its competitive position through AI-augmented agent platforms that reduce average handle times. Genpact differentiates by combining process automation with domain expertise in financial services support verticals.
Consumer technical support services encompass remote and on-site assistance for software configuration, hardware troubleshooting, and network connectivity delivered through voice, digital, and field channels. Resolution protocols typically employ tiered escalation structures with first-line agents handling password resets and connectivity checks while complex cases transfer to L2 specialists with direct OEM system access. Chat support and phone support together capture the majority of incident volume, though chat is gaining share among digital-native consumers who prefer asynchronous interaction. Subscription models dominate enterprise relationships by locking in predictable support costs, while pay-per-use arrangements appeal to seasonal small businesses with variable demand patterns.
FCC guidelines in the United States govern telemarketing and robocall restrictions that shape outbound support engagement protocols, while GDPR in Europe mandates explicit consent for customer data use in automated support analytics. India's TRAI regulations set quality-of-service benchmarks for telecom infrastructure that underpins offshore delivery centers. Stakeholders must monitor how emerging AI disclosure requirements across multiple jurisdictions reshape automation investment priorities and agent retraining obligations.
Market Dynamics
Cloud migration among small businesses is compressing demand cycles and forcing providers to retool legacy voice infrastructure for asynchronous digital channels. This structural shift redistributes margin pressure from labor arbitrage toward automation licensing costs.
Growth Catalysts
- EU AI Act:Mandatory documentation of automated decision logic is accelerating investment in explainable AI tooling for chatbot deployments across European delivery centers.
- India's PLI scheme:Telecom infrastructure incentives are expanding fiber connectivity to Bangalore and Hyderabad, reducing latency for offshore voice operations.
- Small business cloud adoption:SaaS migration is generating subscription-based support demand that locks in predictable recurring revenue streams.
Market Restraints
- Agent wage inflation in Philippines:BPO labor costs in Manila and Cebu are rising faster than automation savings can offset, squeezing voice operation margins.
- GDPR consent friction:Explicit customer authorization requirements for automated analytics are lengthening onboarding cycles and increasing compliance overhead.
- Legacy system entanglement:Tiered escalation protocols depend on OEM ticketing integrations that resist API modernization, trapping providers in maintenance contracts.
Strategic Opportunities
- L2 specialist automation:AI-augmented diagnostic tools are creating white space for providers to capture complex hardware troubleshooting previously reserved for OEM captive operations.
- EU Green Deal data center incentives:Energy-efficient infrastructure mandates are opening procurement advantages for providers with certified low-carbon delivery centers in the Netherlands and Ireland.
- Field channel digitization:Mobile technician dispatch platforms are converging with remote diagnostics to enable hybrid resolution models for on-site hardware failures.
Industry Challenges
- Multilingual AI training data scarcity:High-quality conversational datasets for Indic and Southeast Asian languages remain concentrated with a few annotation vendors, creating bottlenecks for regional chatbot rollout.
- FCC robocall compliance complexity:Evolving telemarketing restrictions require continuous protocol updates for outbound support engagement, demanding dedicated regulatory operations staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Technical Support Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Phone Support, Chat Support, Email Support, On-site Support Customer Type: Individual Consumers, Small Businesses, Enterprises, Educational Institutions Technology: Software Support, Hardware Support, Network Support, Mobile Support Service Model: Subscription Model, Pay-per-Use, Ad-hoc Services, Bundled Services |
| Companies Covered | TaskUs, Sutherland, Influx, Genpact, Alorica, Teleperformance, SupportNinja, Managed Solution, Concentrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Technical Support Services Market Strategic Shifts
Agent augmentation platforms are displacing pure labor arbitrage as the primary competitive lever. Providers now compete on diagnostic accuracy and first-contact resolution rates rather than hourly cost differentials alone.
Generative AI copilots are integrating real-time knowledge retrieval into agent desktops. Mid-market enterprises with 500-2,000 employees are adopting these tools fastest, compressing average handle times by surfacing OEM documentation without manual search. The technology is integrating L1 and L2 workflows into unified resolution interfaces that reduce escalation frequency.
The EU AI Act's risk classification framework is mandating human-in-the-loop protocols for automated support decisions. European delivery centers must now maintain audit trails of chatbot reasoning chains, increasing infrastructure costs but creating compliance service revenue streams. Financial services support verticals face the strictest documentation requirements and are responding by pre-positioning specialized AI governance teams.
Subscription pricing is displacing per-incident models among seasonal small businesses. Pay-per-use arrangements that once dominated variable demand patterns are losing share to flexible tiered contracts with usage floors. This shift is most visible in India, where digital-native SMBs prefer predictable monthly outlays over transaction-based billing.
Consumer Technical Support Services Market Segmentation
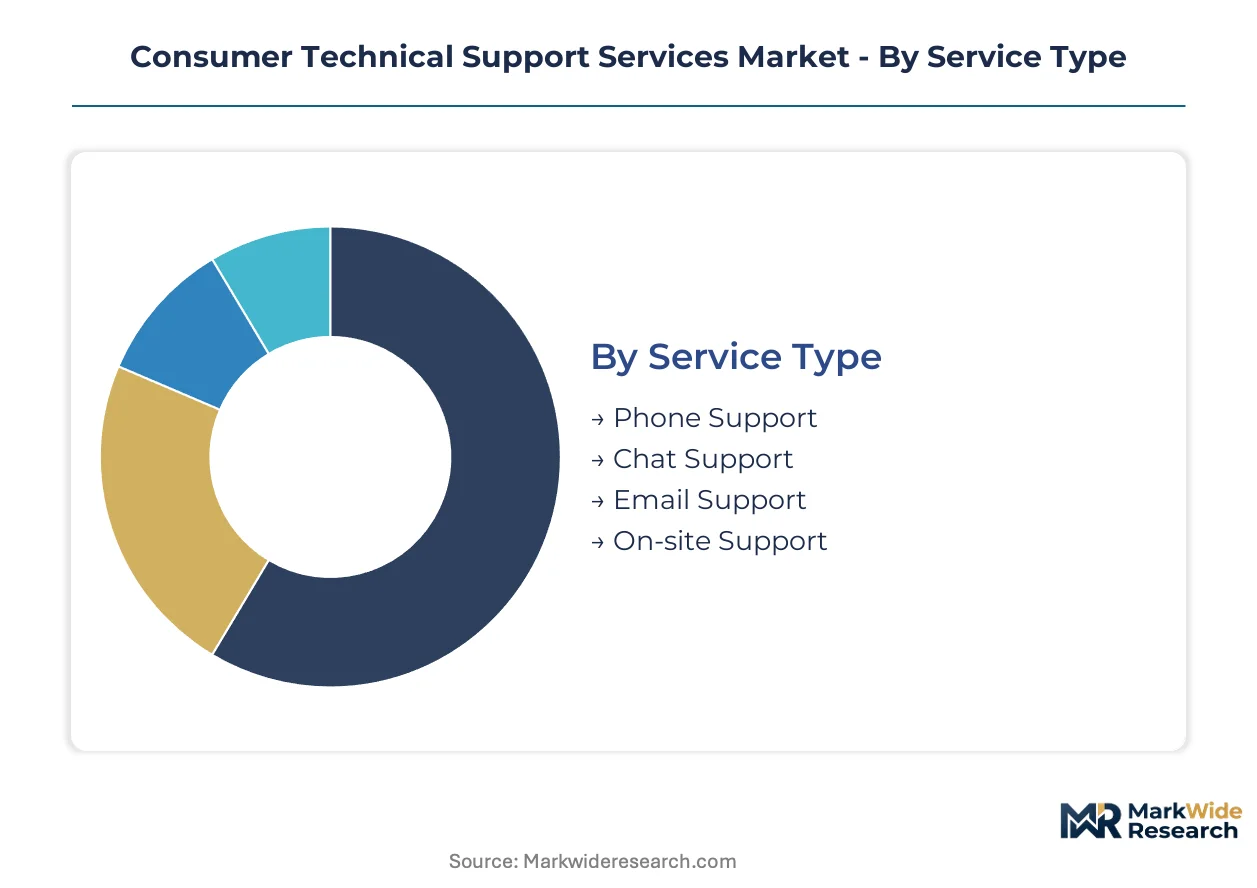
Consumer technical support services fragment across interaction modes, buyer scale, technology domains, and commercial structures. Each axis reveals distinct margin profiles and automation readiness. Providers must align capability investments with segment-specific resolution complexity and contract predictability.
Service Type:
Chat support commands premium pricing per interaction while phone support retains volume dominance in legacy enterprise contracts. The cost-to-resolution ratio separates high-frequency, low-complexity channels from specialized field interventions.
- Phone Support:Voice channels handle complex troubleshooting requiring real-time dialogue and emotional de-escalation. Demand concentrates among enterprises with aging user bases in Germany and Japan, where phone preference persists despite digital alternatives. TRAI quality benchmarks in India enforce latency standards that preserve offshore competitiveness for voice operations.
- Chat Support:Asynchronous text interfaces enable agent concurrency and AI-augmented response drafting. Digital-native consumers in India and Southeast Asia drive fastest adoption, compressing average handle times through scripted diagnostics and automated escalation triggers.
- Email Support:Ticket-based resolution serves non-urgent technical documentation and warranty claims with 24-48 hour SLAs.
- On-site Support:Field dispatch addresses hardware failures requiring physical component replacement or network infrastructure repair.
Today's leader: Phone Support. Tomorrow's challenger: Chat Support.
Customer Type:
Contract structure and price sensitivity diverge sharply between individual purchasers and institutional buyers with procurement leverage.
- Enterprises:Multi-year agreements with defined SLA tiers and dedicated account management. Financial services and healthcare verticals in the United States concentrate demand for compliant, auditable support workflows under HIPAA and SEC oversight.
- Small Businesses:Cloud migration is accelerating subscription adoption among 10-500 employee firms seeking predictable IT spend. India's digital-native SMBs represent the steepest expansion trajectory for flexible tiered contracts.
- Individual Consumers:Warranty-embedded and retail-purchased support with high churn and price elasticity.
- Educational Institutions:Seasonal demand patterns tied to academic calendars with volume spikes during enrollment periods.
Enterprise contracts anchor current revenue. Small business subscriptions are gaining share fastest.
Technology:
Resolution complexity and required agent certification depth vary across software, hardware, and infrastructure domains.
- Software Support:SaaS configuration and troubleshooting dominate incident volume with fastest resolution velocity. GDPR consent requirements in Europe lengthen onboarding for automated analytics tools, creating compliance differentiation for providers with pre-built data governance frameworks.
- Hardware Support:Physical device diagnostics and replacement logistics require OEM system access and inventory integration. Warranty-embedded contracts in the United States and Germany sustain captive operations for premium electronics brands.
- Network Support:Connectivity troubleshooting spans ISP coordination, router configuration, and security policy enforcement.
- Mobile Support:Smartphone and tablet assistance combines hardware warranty claims with app ecosystem navigation.
Software support delivers scale economics. Hardware support retains margin through OEM exclusivity.
Service Model:
Revenue predictability and customer lifetime value hinge on contract structure selection.
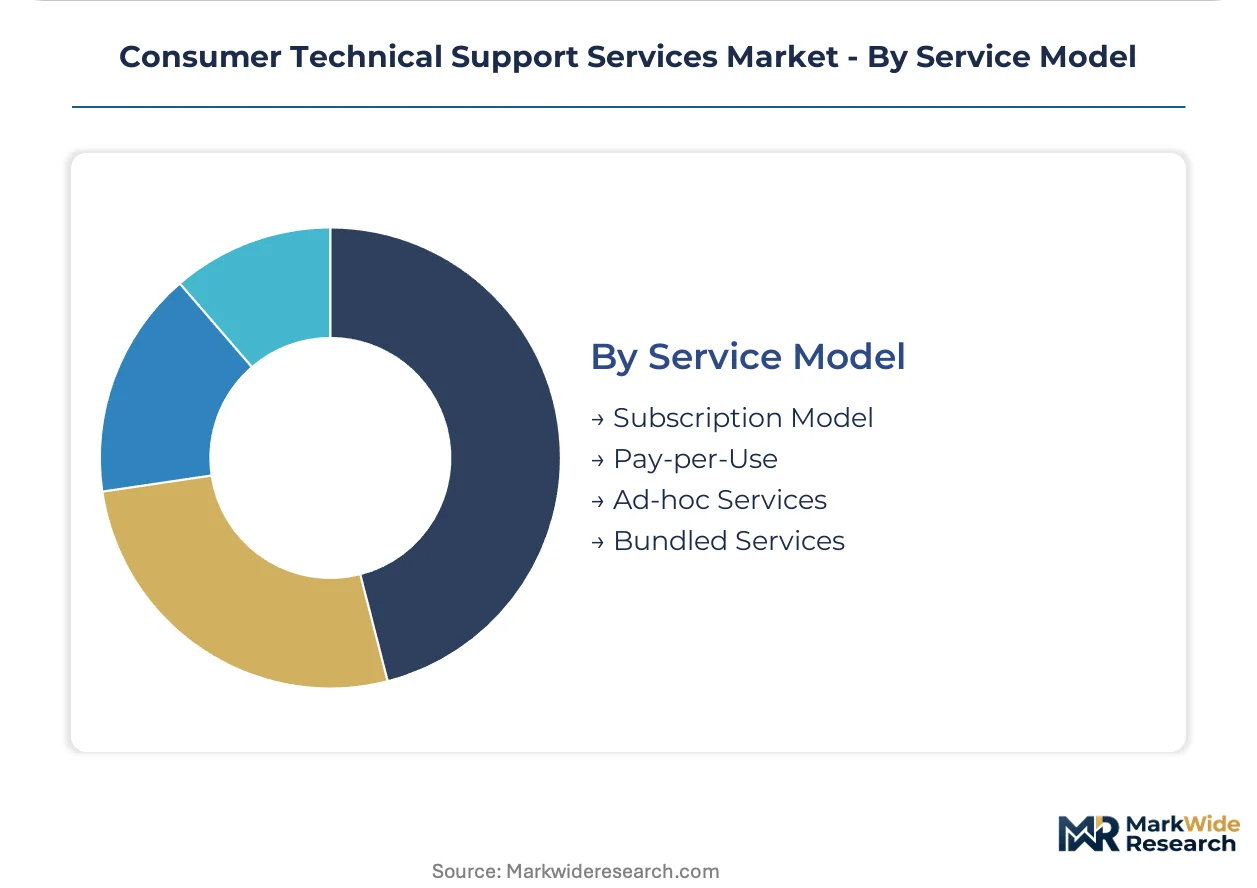
- Subscription Model:Fixed monthly or annual fees with defined usage tiers and overage penalties. India's PLI scheme beneficiaries in telecom infrastructure are expanding fiber connectivity that enables reliable delivery of subscription-based remote support to SMBs.
- Pay-per-Use:Transactional billing for incident volume without commitment. Seasonal retailers and event-driven businesses in the United States prefer this structure despite higher per-unit costs.
- Ad-hoc Services:Unscheduled, premium-priced interventions for critical failures outside warranty coverage.
- Bundled Services:Support packaged with hardware sales, software licenses, or telecom contracts at discounted blended rates.
Subscriptions lock in enterprise relationships. Pay-per-use defends position among variable-demand buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India pioneered offshore technical support at scale during the 1990s telecom liberalization, establishing the delivery model now replicated across emerging markets. The industry's geographic footprint now spans three continents with distinct regulatory and infrastructure profiles.
United States
Enterprise demand from financial services and healthcare verticals drives contract value, with HIPAA and SEC oversight mandating auditable support workflows. FCC robocall restrictions shape outbound engagement protocols. Delivery concentrates in Texas and Arizona secondary markets where operational costs undercut coastal metros.
India
Bangalore and Hyderabad host the largest voice and chat delivery centers, with TRAI quality benchmarks enforcing latency standards that preserve offshore competitiveness. The PLI scheme for telecom infrastructure expands fiber connectivity to tier-2 cities. Small business cloud adoption accelerates fastest among digital-native SMBs in Mumbai and Delhi-NCR.
Philippines
Manila and Cebu sustain cost-competitive voice operations for North American clients, though agent wage inflation outpaces automation savings. The national BPO regulatory framework enforces data localization requirements. Cebu City's emerging delivery cluster competes with capital-region congestion.
Germany
Aging enterprise user bases maintain phone preference despite digital alternatives, sustaining voice contract premiums. GDPR mandates explicit consent for automated analytics, lengthening onboarding cycles. Frankfurt and Berlin delivery centers focus on compliant financial services support under BaFin supervision.
Ireland
EU Green Deal data center incentives attract providers certifying low-carbon delivery infrastructure. Dublin's concentration of hyperscale facilities enables energy-efficient remote support operations. IDA Ireland investment programs target AI governance specialization for financial services verticals.
Consumer Technical Support Services Market Competitive Environment
Capital-heavy captive operations compete with asset-light third-party providers across tiered service levels. Market structure fragments across global outsourcers, regional specialists, and technology-enabled challengers. Three archetypes dominate: scale-driven voice operators, AI-augmented platform providers, and vertical-focused domain specialists. Consolidation pressure manifests through strategic partnerships and automation licensing rather than pure capacity expansion.
Among Philippines and Latin America-based operators, Teleperformance exemplifies geographic diversification strategy. Sutherland occupies a position within the AI-augmented tier, while Genpact anchors the vertical-specialist archetype through financial services domain concentration. TaskUs represents the digital-native challenger model targeting mid-market enterprises.
| Leading Market Players |
|---|
| TaskUs |
| Sutherland |
| Influx |
| Genpact |
| Alorica |
| Teleperformance |
| SupportNinja |
| Managed Solution |
| Concentrix |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement teams in financial services and healthcare verticals anchor contract value through multi-year subscription agreements with defined SLA tiers. This buyer concentration locks in predictable recurring revenue streams while compressing margin pressure onto providers managing offshore delivery center costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by resolution complexity and compliance certification. Premium tiers command rates for HIPAA-auditable workflows and EU AI Act documentation, while economy tiers serve basic password reset and connectivity check volumes. Pricing pressure stems from agent wage inflation in Manila and Cebu outpacing automation savings. Small businesses exhibit highest price sensitivity, gravitating toward flexible tiered contracts with usage floors over per-incident billing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale enterprise demand through captive operations in the United States and Germany, while third-party providers serve mid-market accounts via offshore delivery centers. Supply concentrates in India, the Philippines, and Ireland for voice and chat operations. Fiber connectivity infrastructure and GPU clusters for AI training constitute critical input dependencies. Single-source vulnerability in high-quality Indic language datasets creates bottlenecks for regional chatbot deployment. Distribution runs through subscription management platforms and OEM-embedded warranty contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation licensing costs are displacing labor arbitrage as the primary margin lever, rewarding providers who capture premium-tier pricing through compliance certification and AI governance specialization.
For Market Incumbents: Anticipate escalating EU AI Act documentation requirements by pre-positioning explainable AI tooling and audit trail infrastructure in European delivery centers. Consolidate position through backward integration into proprietary diagnostic platforms that reduce OEM ticketing dependency. Channel control through direct SMB subscription platforms defends against digital-native challengers. For New Entrants and Emerging Players: Capture white space in L2 specialist automation for hardware troubleshooting previously reserved for OEM captive operations. India's digital-native SMB segment offers the most penetrable geography for flexible tiered subscription contracts. Lead with mobile-first technician dispatch platforms converging remote diagnostics with field channel digitization. For Investors and Strategic Acquirers: Vertical software vendors with embedded support workflows are the most active acquirer in this space, seeking to own post-sale customer relationships. Long-term viability hinges on AI governance capabilities and energy-efficient delivery center certification. Monitor TRAI quality benchmark enforcement and EU Green Deal data center incentives as inflection indicators for offshore competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Specialization | EU AI Act documentation requirements create compliance service revenue streams for certified providers. |
| Energy-Efficient Delivery Center Certification | EU Green Deal incentives in Ireland and the Netherlands confer procurement advantages for low-carbon infrastructure. |
| Backward Integration into Diagnostic Platforms | Proprietary AI-augmented tools reduce OEM ticketing dependency and capture complex hardware troubleshooting margin. |
| Mobile Technician Dispatch Platform Launch | Hybrid resolution models converge remote diagnostics with on-site hardware failure response capabilities. |
| Indic Language Dataset Acquisition | High-quality conversational training data scarcity in Bangalore and Hyderabad creates competitive moats for regional chatbot rollout. |
Study Parameters
Coverage spans the United States, India, Germany, the Philippines, and Ireland, with primary inputs from each. The analysis combines structured interviews with BPO operations directors, AI platform engineering leads, enterprise IT procurement officers, and telecom infrastructure planners with secondary validation. Sources include TRAI quality-of-service reports, SEC 10-K filings from listed providers, EU AI Act implementation guidance, and hyperscaler data center capex disclosures. Bottom-up incident volume modeling and top-down contract value analysis were triangulated against regional labor cost benchmarks.
Rate-of-change decomposition across the analysis window isolates automation penetration effects from labor cost inflation and regulatory compliance cost accretion. The framework models segmentation dimensions including service type, customer scale, technology domain, and commercial structure. CAGRs were derived from trend extrapolation of cloud migration velocity and subscription contract adoption curves. Forecast inputs incorporate India's PLI scheme infrastructure rollout timelines and FCC robocall restriction evolution patterns.
Underlying measurement precision varies by segment; software support and chat operations carry tighter precision than on-site field services due to digital traceability. Forecasts reflect assumptions regarding AI tooling cost curves, wage trajectory persistence in offshore markets, and regulatory enforcement intensity across jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market