
 Cloud Enterprise Management Market | 2026-2036
Cloud Enterprise Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Enterprise Management Market Outlook
Enterprise-grade security certification is rotating from optional premium to baseline procurement requirement across Fortune 500 cloud migrations. Microsoft Corporation leverages its Azure Government portfolio to anchor highly regulated sectors including defense and healthcare. Oracle Corporation sustains database-centric workloads through aggressive bare-metal cloud infrastructure investments. SAP SE differentiates via deep ERP integration that locks manufacturing clients into vertically aligned subscription tiers.
Cloud Enterprise Management denotes the integrated orchestration of computing resources, application workloads, and organizational data across distributed infrastructure environments through policy-driven automation and real-time telemetry. Platforms enforce service-level agreements through container orchestration, identity federation protocols, and encrypted multi-tenant isolation boundaries that segregate customer environments at the kernel level. Software as a Service commands the dominant revenue share as vendors bundle analytics, collaboration, and compliance modules into unified per-seat contracts. Hybrid Cloud deployment is expanding fastest among mid-market manufacturers seeking to retain proprietary design data on-premises while bursting computational workloads to public infrastructure during peak demand cycles.
FDA 21 CFR Part 11 validation requirements shape pharmaceutical cloud procurement by mandating audit trails and electronic signature integrity for quality management systems. The SEC's cybersecurity disclosure rules and EU GDPR Article 28 processor obligations compel enterprises to document subprocessor chains and data localization commitments in vendor contracts. Stakeholders must evaluate sovereign cloud certifications and cross-border data transfer mechanisms before committing to multi-year platform agreements.
Market Dynamics
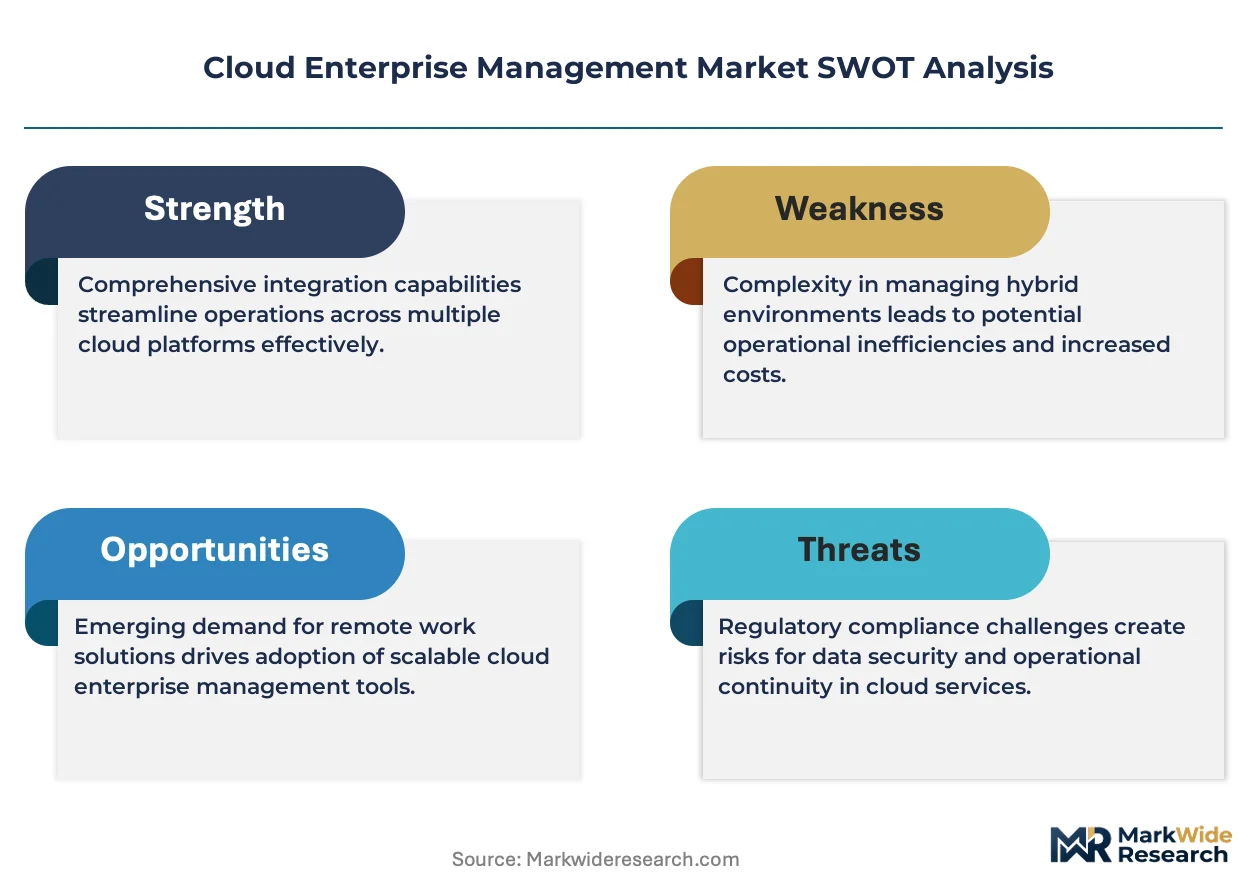
Sovereign cloud mandates from the EU AI Act and GDPR Article 28 are forcing enterprises to re-architect data residency controls, compressing vendor selection cycles and privileging certified domestic infrastructure operators over global hyperscalers.
Growth Catalysts
- EU AI Act compliance deadlines:German industrial conglomerates are consolidating vendor relationships around sovereign cloud architectures to satisfy processor obligations and subprocessor documentation requirements.
- Hybrid workload orchestration:Mid-market manufacturers are bursting computational loads to public infrastructure while retaining proprietary design data on-premises, creating demand for unified management platforms.
- Financial services digitization:Banks and insurers are accelerating adoption of cloud-based governance platforms to satisfy SEC cybersecurity disclosure rules and real-time audit trail mandates.
Market Restraints
- Cross-border data transfer friction:EU-US Data Privacy Framework uncertainties are extending legal review timelines for multi-year platform commitments and inflaming contractual negotiation costs.
- Specialized talent scarcity:Shortages of certified cloud architects and compliance engineers in Germany and France are delaying implementation timelines and inflating professional services rates.
- Kernel-level isolation complexity:Multi-tenant encryption and container orchestration at the hardware boundary require proprietary silicon investments that mid-market buyers struggle to amortize.
Strategic Opportunities
- India's sovereign cloud localization:RBI data localization directives and SEBI cybersecurity circulars are creating demand for domestic infrastructure operators with ISO 27001 certification.
- FDA 21 CFR Part 11 validation services:Pharmaceutical quality management systems require specialized audit trail and electronic signature integrity modules that generalist platforms underinvest in.
- Edge-to-cloud convergence:Industrial IoT telemetry combined with container orchestration is enabling predictive maintenance workloads that were previously uneconomical on centralized infrastructure.
Industry Challenges
- Legacy ERP integration complexity:Manufacturing clients with decades-old SAP deployments face data schema incompatibilities and custom code remediation costs that erode projected cloud migration savings.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audit cycles are extending from six to fourteen months as assessor backlogs accumulate, delaying revenue recognition for platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Enterprise Management Market |
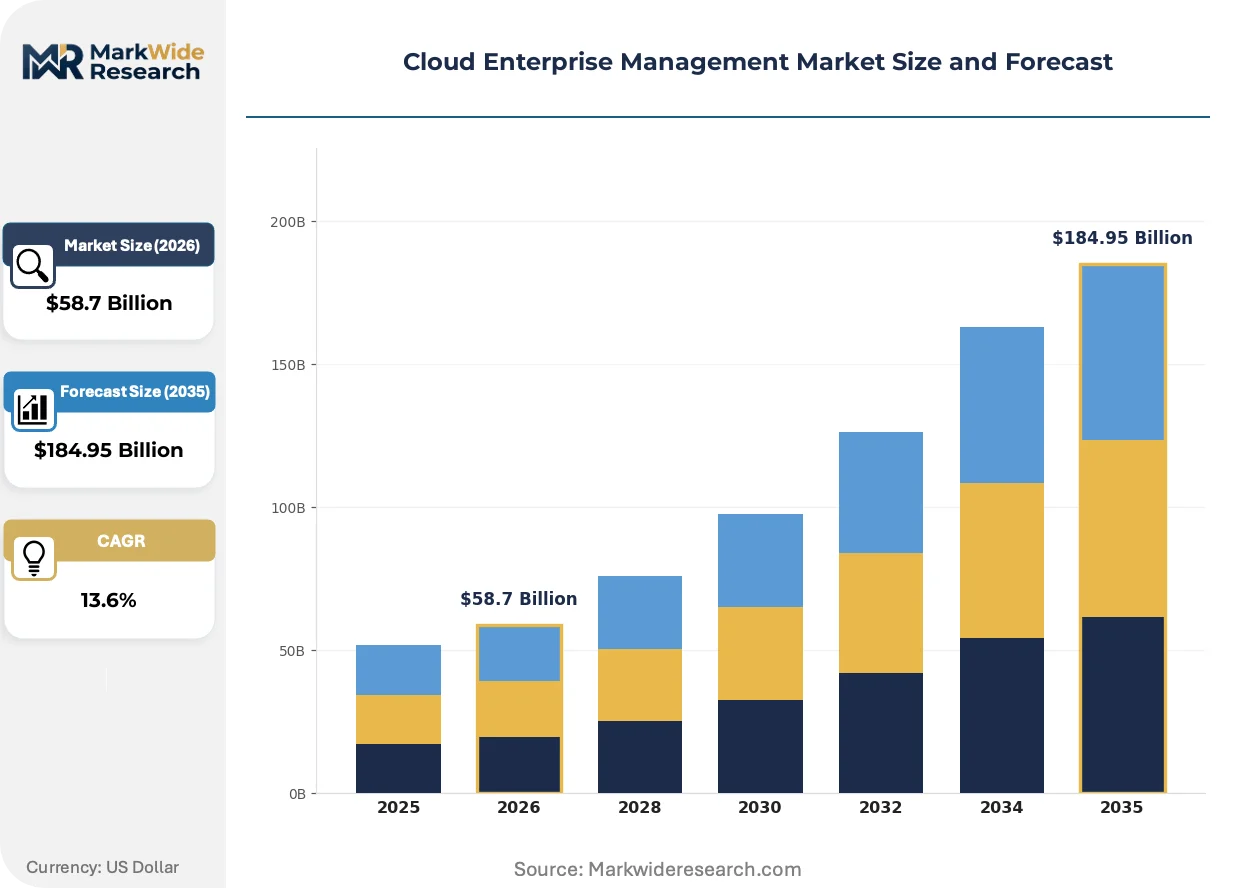
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $184.95 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: Infrastructure as Service, Platform as Service, Software as Service, Managed Services End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Application: Project Management, Resource Allocation, Financial Management, Performance Monitoring |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, IBM Corporation, Salesforce, ServiceNow, OpenText, Hyland, Box Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Enterprise Management Market Strategic Shifts
Bare-metal cloud provisioning is displacing virtualized infrastructure as the default for database-centric workloads, while regulatory fragmentation across the EU, US, and Asia-Pacific is fragmenting procurement patterns.
Confidential computing using hardware-based trusted execution environments is displacing software-only encryption for sensitive workloads in healthcare and defense sectors. German automotive suppliers and French pharmaceutical manufacturers are adopting Intel SGX and AMD SEV at twice the pace of general enterprise buyers. This hardware-rooted isolation is compressing liability exposure for processors handling GDPR-regulated data.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk AI systems deployed on cloud infrastructure. Providers must now document training data provenance and model drift monitoring capabilities in processor agreements. Financial services institutions in Frankfurt and Paris are demanding these attestations upfront, reshaping RFP evaluation criteria before contract signature.
Subscription bundling of analytics, collaboration, and compliance modules into per-seat contracts is displacing à-la-carte procurement in mid-market manufacturing. Buyers in Stuttgart's industrial cluster and Turin's automotive corridor are consolidating vendor relationships to reduce integration overhead. This preference compression favors vertically integrated platforms with native ERP connectors over best-of-breed point solutions.
Cloud Enterprise Management Market Segmentation
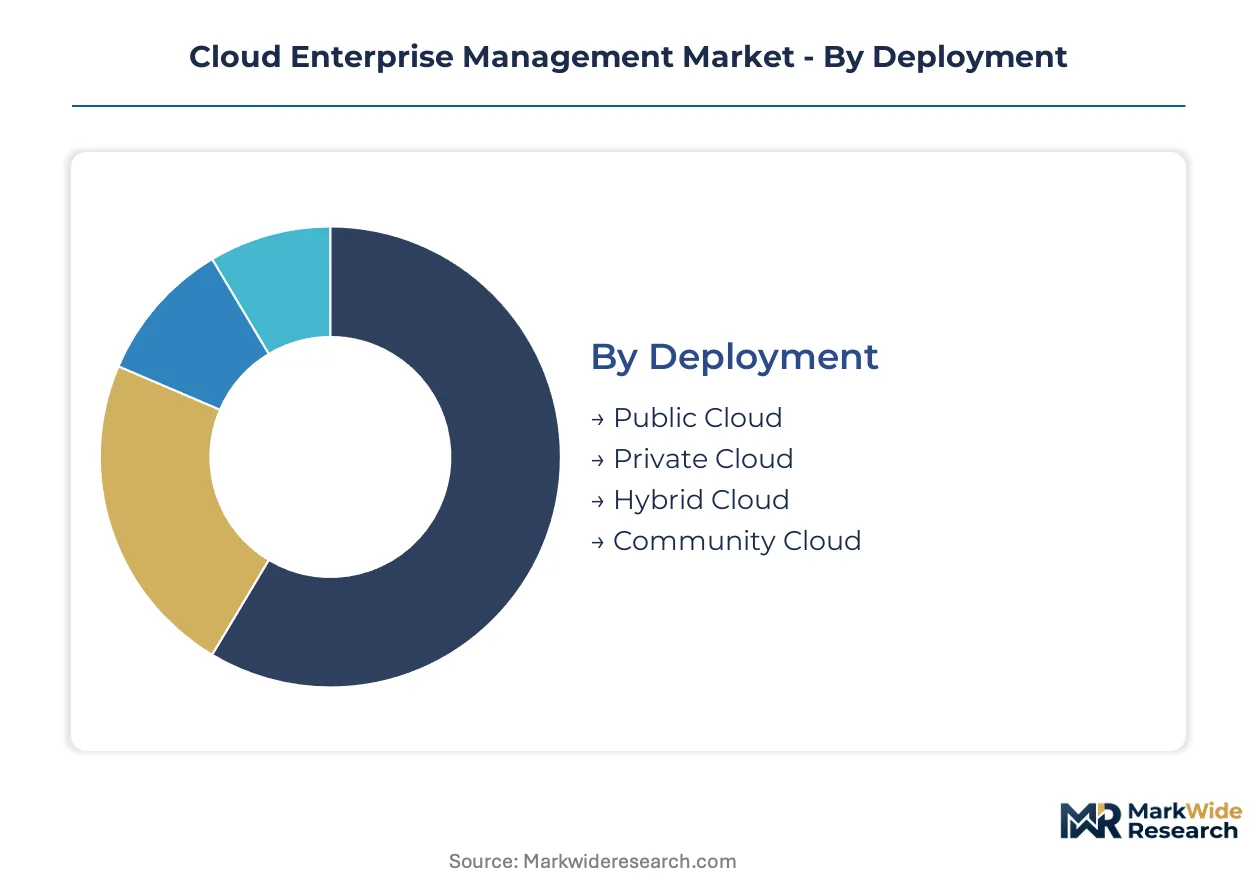
Cloud Enterprise Management procurement patterns fragment sharply across deployment architectures and service tiers, with regulatory compliance requirements dictating viable vendor shortlists before technical evaluation begins. Buyers segment their commitments based on data residency obligations, workload sensitivity, and integration depth with legacy ERP systems.
Deployment:
GDPR Article 28 processor obligations and the EU AI Act's risk-based classifications are compressing vendor selection cycles toward architectures with demonstrable data localization controls.
- Public Cloud:Multi-tenant infrastructure operated by hyperscale providers delivers elastic compute and storage through shared physical resources with logical isolation boundaries. Financial services institutions in Frankfurt and Paris are demanding enhanced subprocessor documentation and cross-border transfer mechanism attestations before committing to public infrastructure for customer-facing applications.
- Hybrid Cloud:Unified orchestration platforms span on-premises data centers and public cloud resources through containerized workload portability and policy-driven data placement. Mid-market manufacturers in Stuttgart's industrial cluster are retaining proprietary design data on-premises while bursting computational loads to public infrastructure during peak demand cycles, creating concentrated demand for seamless workload migration tools.
- Private Cloud:Dedicated single-tenant infrastructure provisioned within enterprise-controlled facilities or exclusive third-party data centers. Sovereign cloud mandates from German industrial conglomerates are privileging certified domestic operators with kernel-level isolation guarantees over global hyperscalers for sensitive operational technology workloads.
- Community Cloud:Shared infrastructure serving specific industry verticals or regulatory jurisdictions with common compliance requirements. Defense contractors and healthcare consortiums are consolidating procurement around FedRAMP and HIPAA-validated community architectures to amortize certification costs across member organizations.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
Service Type:
Cost tier differentiation separates commodity infrastructure from value-added platform capabilities, with bundled analytics and compliance modules commanding premium per-seat pricing.
- Infrastructure as Service:Raw compute, storage, and networking resources delivered through programmatic APIs with metered consumption billing. Bare-metal provisioning is displacing virtualized infrastructure for database-centric workloads in pharmaceutical quality management systems requiring FDA 21 CFR Part 11 validation.
- Software as Service:Fully managed application workloads accessed through web interfaces with vendor-maintained infrastructure and automatic feature updates. Unified per-seat contracts bundling collaboration, analytics, and compliance modules are displacing à-la-carte procurement in Turin's automotive corridor as buyers consolidate vendor relationships to reduce integration overhead.
- Platform as Service:Managed runtime environments abstracting infrastructure management while preserving developer control over application architecture and deployment pipelines.
- Managed Services:Outsourced operational responsibility for cloud infrastructure including monitoring, patching, backup, and incident response delivered through fixed-fee or consumption-based contracts.
Software as Service captures the dominant revenue concentration; Platform as Service is climbing the fastest as manufacturers modernize legacy application portfolios.
End User:
Customer maturity and procurement sophistication determine service tier selection, with certification requirements and professional services dependencies scaling inversely with internal cloud competency.
- Large Enterprises:Complex multi-cloud environments spanning dozens of business units with dedicated cloud centers of excellence and established FinOps practices. German automotive OEMs are mandating sovereign cloud certifications and hardware-rooted isolation through Intel SGX or AMD SEV for GDPR-regulated data processing.
- Medium Enterprises:Consolidated cloud strategies with limited dedicated personnel, relying on managed services and professional services partners for architecture design and compliance validation. ISO 27001 and SOC 2 Type II audit timeline extensions from six to fourteen months are delaying platform commitments and inflating professional services rates in France and Germany.
- Small Enterprises:Native cloud-first operations with minimal legacy infrastructure, prioritizing ease of deployment and predictable subscription pricing over customization depth.
- Government Agencies:Rigid procurement frameworks mandating specific security certifications, domestic data residency, and documented supply chain provenance.
Large Enterprises anchor current procurement volume; Medium Enterprises are gaining share fastest as cloud-native ERP replacement cycles accelerate.
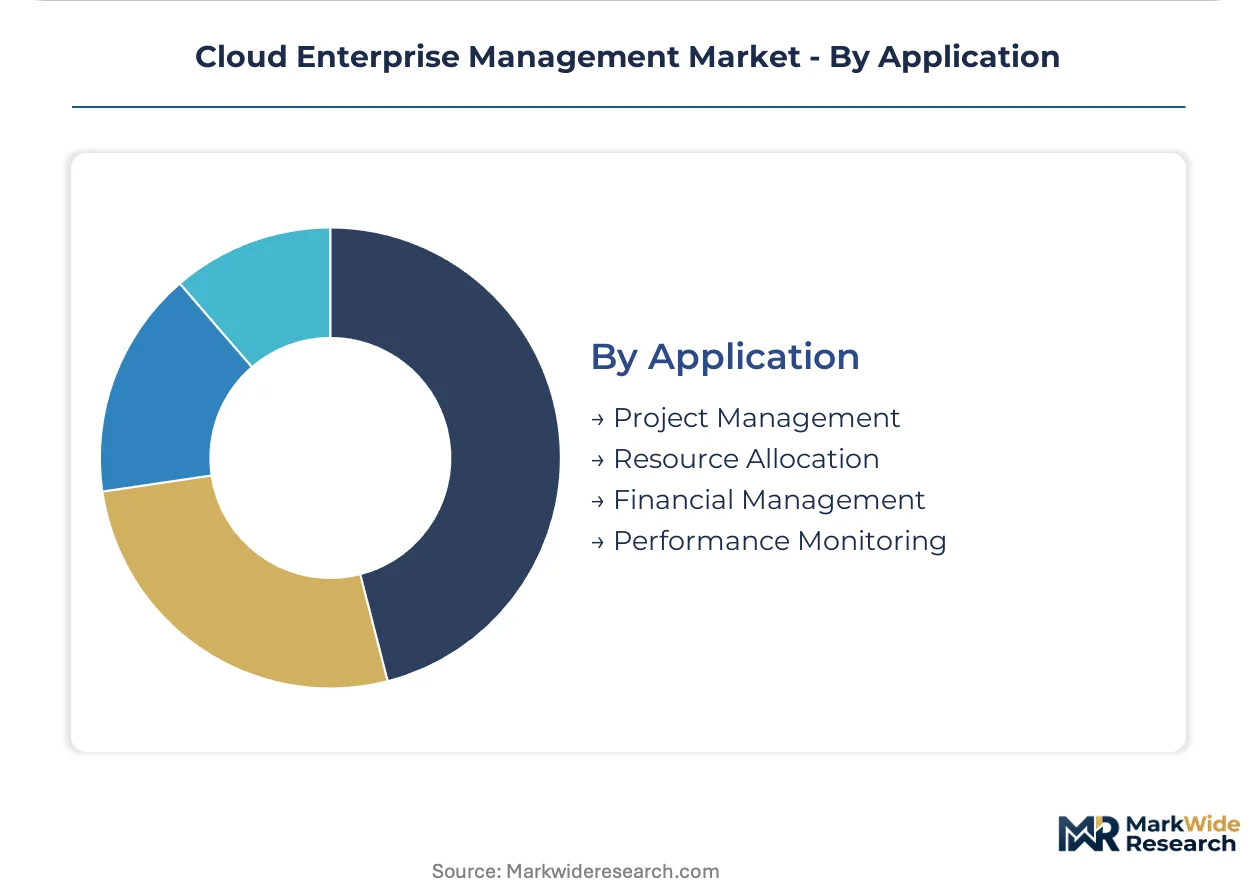
Application:
Functional workload characteristics dictate platform selection criteria, with audit trail intensity and real-time telemetry requirements separating suitable architectures.
- Financial Management:Integrated accounting, budgeting, forecasting, and compliance reporting with multi-entity consolidation and regulatory filing automation. SEC cybersecurity disclosure rules are compelling banks and insurers to document subprocessor chains and data localization commitments in vendor contracts before multi-year platform agreements.
- Performance Monitoring:Real-time telemetry collection, anomaly detection, and predictive analytics across distributed infrastructure and application workloads. Edge-to-cloud convergence with industrial IoT telemetry and container orchestration is enabling predictive maintenance workloads in manufacturing that were previously uneconomical on centralized infrastructure.
- Project Management:Task coordination, resource scheduling, and milestone tracking with collaboration tooling and portfolio visibility.
- Resource Allocation:Dynamic capacity planning, workload placement optimization, and cost attribution across multi-cloud and hybrid environments.
Financial Management commands the steepest expansion trajectory as regulatory disclosure requirements intensify; Performance Monitoring is displacing legacy monitoring point solutions through unified observability platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud enterprise management services flow disproportionately toward jurisdictions with stringent data localization mandates, creating import dependencies for compliant infrastructure in regulated economies while export opportunities concentrate among sovereign-certified domestic operators.
United States
Defense contractors and healthcare consortiums are consolidating procurement around FedRAMP-validated community cloud architectures. SEC cybersecurity disclosure rules compel financial institutions in New York and Chicago to document subprocessor chains before multi-year platform commitments. The Washington-Baltimore corridor anchors demand for hardware-rooted isolation through confidential computing deployments.
Germany
Industrial conglomerates in Stuttgart and Munich are mandating kernel-level isolation guarantees for operational technology workloads. GDPR Article 28 processor obligations and the EU AI Act's risk-based classifications compress vendor selection cycles toward certified domestic infrastructure operators. Baden-Württemberg's automotive suppliers are adopting Intel SGX and AMD SEV at twice the pace of general enterprise buyers.
India
RBI data localization directives and SEBI cybersecurity circulars are creating concentrated demand for ISO 27001-certified domestic infrastructure operators. Mumbai's financial institutions and Bangalore's technology services firms are re-architecting data residency controls to satisfy processor documentation requirements. Telangana and Maharashtra are emerging as preferred locations for sovereign cloud deployments.
France
Pharmaceutical manufacturers in the Île-de-France region require FDA 21 CFR Part 11 validation for quality management systems deployed on cloud infrastructure. ANSM and CNIL guidance on health data processing is privileging operators with hardware-based trusted execution environments. Paris-based financial services institutions are demanding EU AI Act conformity assessments upfront in RFP evaluation criteria.
Japan
METI industrial digitization incentives are accelerating cloud-native ERP replacement cycles among mid-market manufacturers. Osaka's industrial cluster and Nagoya's automotive corridor are consolidating vendor relationships around unified per-seat subscription contracts. PMDA electronic record requirements for pharmaceutical quality systems are shaping procurement toward platforms with specialized audit trail modules.
Cloud Enterprise Management Market Competitive Environment
Concentration sits with vertically integrated hyperscalers and database-centric infrastructure specialists that control both the orchestration layer and the underlying compute substrate. The vendor base stratifies across three tiers: full-stack platform operators with government security certifications, ERP-native cloud providers with deep manufacturing integration, and point-solution specialists in compliance automation. Dominant competitive moves include strategic partnerships with domestic sovereign cloud operators and portfolio diversification into confidential computing hardware.
Within the full-stack platform tier, Microsoft Corporation and Oracle Corporation exemplify divergent anchoring strategies for regulated sector capture. SAP SE occupies a distinctive position among ERP-native providers manufacturing clients find difficult to displace. IBM Corporation represents the legacy systems integrator archetype pivoting toward hybrid cloud orchestration services. These four entities collectively shape procurement standards that mid-tier competitors must satisfy to access Fortune 500 and government agency contracts.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Salesforce |
| ServiceNow |
| OpenText |
| Hyland |
| Box Inc. |
| Others |
Value Chain & Pricing Dynamics
EU AI Act conformity assessments and GDPR Article 28 processor certifications gate both vendor qualification and price differentiation simultaneously, compressing procurement timelines for domestic operators while inflating professional services premiums for compliance engineering. Mid-market manufacturers face amortization challenges for kernel-level isolation investments that hyperscalers absorb at scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle hardware-rooted isolation through Intel SGX or AMD SEV with sovereign cloud certifications. Pricing pressure stems from hyperscaler margin compression in bare-metal database workloads. Small enterprises exhibit highest price sensitivity; defense contractors show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for specialized silicon shipments. Supply concentrates in Taiwan for confidential computing chips, Ireland for EU data center infrastructure, and Germany for sovereign cloud certifications. Dependencies include proprietary encryption hardware, bare-metal orchestration software, and certified assessor capacity. Single-source vulnerability sits with Intel and AMD trusted execution environments. Distribution runs through direct enterprise sales with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud enterprise management sits at an inflection where EU AI Act risk classifications are forcing processor agreement renegotiations across installed bases. This regulatory compression creates asymmetric advantage for certified domestic operators.
For Market Incumbents: Secure sovereign cloud certifications in Germany and France before assessor backlogs extend audit timelines. Consolidate vendor relationships with Baden-Württemberg automotive suppliers through native ERP connectors. Threat substitution from confidential computing hardware specialists demands captive silicon partnerships. For New Entrants and Emerging Players: Differentiate on FDA 21 CFR Part 11 validation services for pharmaceutical quality management systems. Target India's domestic infrastructure operators under RBI data localization directives. Go-to-market through ISO 27001 certification partnerships with Telangana and Maharashtra data center developers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bare-metal cloud infrastructure deployments. Five-to-ten year viability favors vertically integrated platforms with government security certifications. Watch assessor capacity utilization as signal for certification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act processor obligations privilege domestic operators with demonstrable data localization controls. |
| Confidential Computing Hardware Partnership | Intel SGX and AMD SEV adoption by German automotive suppliers compresses liability exposure for GDPR-regulated data. |
| ERP-Native Integration Development | SAP-centric manufacturing clients in Stuttgart's industrial cluster resist dislocation from vertically aligned subscription tiers. |
| Pharmaceutical Validation Services | FDA 21 CFR Part 11 audit trail modules address quality management system requirements that generalist platforms underinvest in. |
| Domestic Infrastructure Localization | RBI and SEBI directives in India create demand for ISO 27001-certified operators with documented subprocessor chains. |
Study Parameters
Desk research of hyperscaler capex disclosures, sovereign cloud certification registries, and EU regulatory filings preceded structured interviews with cloud architects, compliance engineers, procurement officers at industrial conglomerates, and assessor firm audit leads. Primary fieldwork across Frankfurt, Stuttgart, and Paris validated secondary patterns. Bottom-up deployment forecasts triangulated against top-down market sizing.
Variance decomposition across the projection horizon isolates drivers by deployment architecture, service tier, and end-user maturity. Modeled dimensions span public-hybrid-private-community deployment, IaaS-PaaS-SaaS service types, and large-medium-small-government segments. CAGRs derived from analyst judgment on adoption curve inflections, incorporating EU AI Act implementation timelines and FDA validation service expansion.
Material uncertainties — regulatory interpretation shifts, cross-border data transfer framework instability, assessor capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline normalization and sovereign cloud demand concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Managed Services Market
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
Open Source ERP Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Field Service Management Market
Enterprise Services
Bring Your Own Device Market