
 Global Cloud Professional Services Market | 2026-2036
Global Cloud Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Professional Services Market Foresight
ISO 27001 certification cycles are redrawing competitive boundaries in cloud professional services. Accenture leverages its multi-cloud architecture practice to sustain premium positioning across Fortune 500 accounts. Deloitte anchors its market presence through deep industry vertical expertise in financial services and healthcare compliance. IBM competes through proprietary hybrid cloud platforms integrated with its consulting delivery model.
Cloud professional services encompass advisory, implementation, migration, and managed support engagements that architect, deploy, and optimize cloud infrastructure across public, private, and hybrid environments. These services require mastery of container orchestration, API governance, and zero-trust security frameworks to transform on-premises workloads into scalable, consumption-based IT operations. Cloud migration and cloud security command the largest margin pools as enterprises prioritize risk-mitigated transitions over experimental deployments. Managed cloud services represent the fastest-growing category as organizations shift from capital-intensive ownership to operational expenditure models with guaranteed SLAs.
FDA 21 CFR Part 11, EU GDPR, and SEC cybersecurity disclosure rules shape demand patterns by mandating audit-ready cloud configurations with immutable logging and geographic data residency. HIPAA and PCI-DSS compliance requirements further segment the addressable market, creating specialized consulting practices that command rate premiums over generalist providers. Stakeholders must monitor how NIS2 implementation across EU member states and state-level privacy laws in California and Virginia reshape cross-border service delivery architectures.
Market Dynamics
EU AI Act compliance deadlines and DORA operational resilience mandates are forcing financial institutions into accelerated cloud migration timelines, compressing traditional consulting sales cycles and elevating security-architecture expertise to a primary vendor selection criterion.
Growth Catalysts
- EU AI Act enforcement:Risk classification requirements for high-risk AI systems are mandating audit-ready cloud configurations, creating specialized advisory demand across Frankfurt and Paris financial centers.
- Container orchestration mastery:Kubernetes-native workload portability is enabling multi-cloud strategies that require implementation partners with certified platform engineering capabilities.
- India:PLI scheme incentives for data center infrastructure are attracting hyperscaler investment, generating downstream professional services demand for migration and managed operations.
Market Restraints
- Certified talent scarcity:ISO 27001 lead auditor and cloud security architect credentials command 40-60% wage premiums, constraining project scaling for mid-tier consultancies.
- Input cost volatility:GPU and specialized AI training hardware availability fluctuations are disrupting fixed-price implementation contracts and margin predictability.
- Regulatory fragmentation:Divergent state-level privacy laws across California, Virginia, and Texas are forcing redundant compliance architectures that inflate solution complexity.
Strategic Opportunities
- Germany operational resilience gap:DORA implementation deadlines in January 2025 are creating urgent demand for critical function mapping and third-party risk management services.
- FinOps convergence:Cloud cost optimization platforms integrated with sustainability tracking are opening advisory revenue streams tied to CSRD reporting obligations.
- Edge-to-cloud orchestration:Manufacturing IoT data pipelines requiring low-latency processing are expanding addressable market beyond traditional enterprise data center migration.
Industry Challenges
- Zero-trust architecture skills gap:Shortage of engineers proficient in identity-centric perimeter design is extending project timelines and elevating subcontractor dependence.
- Legacy mainframe integration complexity:COBOL-dependent core banking systems require specialized bridge architectures that few consultancies can deliver without partner ecosystems.
- Cross-border data residency enforcement:Schrems II ruling compliance is fragmenting cloud architectures and multiplying vendor management overhead for multinational engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Professional Services Market |
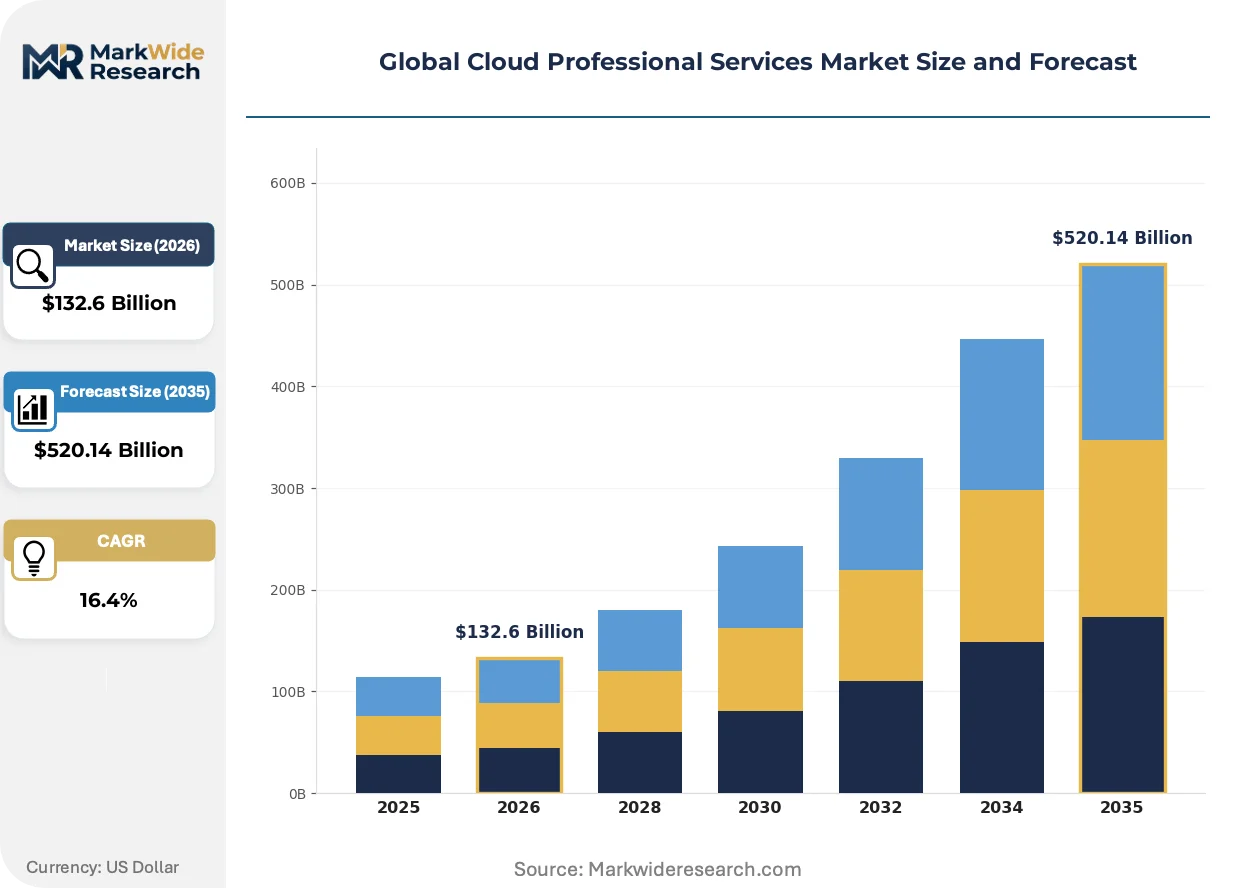
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $520.14 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Migration, Cloud Consulting, Managed Cloud Services, Cloud Security, Cloud Integration Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: BFSI, Telecommunications, Government, Manufacturing, Media & Entertainment Customer Type: Large Enterprises, Small & Medium Businesses, Startups, Non-Profit Organizations |
| Companies Covered | Accenture, Deloitte, IBM, PwC, EY, Capgemini, Microsoft Corporation, Amazon Web Services, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Professional Services Market Shifts & Advancements
Infrastructure-as-code methodologies are redrawing competitive boundaries between traditional system integrators and cloud-native engineering boutiques, while regulatory technology integration is becoming a mandatory capability layer across all service tiers.
Platform engineering teams are institutionalizing internal developer portals with golden path templates and self-service provisioning APIs. Financial services institutions in London and Singapore are deploying these capabilities at scale, compressing application deployment cycles from weeks to hours. This operational model is displacing ticket-based infrastructure requests and the managed service providers that built business models around them.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk AI deployments before market entry. Cloud service providers must now document technical specifications, data governance protocols, and human oversight mechanisms to avoid prohibited practice designation. Healthcare and credit scoring applications face the steepest compliance burden, driving demand for EU-established audit capabilities.
Consumption-based contracting is replacing fixed-fee implementation structures as buyers demand outcome accountability. Enterprise procurement functions in the United States are inserting gainshare clauses tied to realized cloud cost reduction or security incident reduction. This shift transfers performance risk to service providers while compressing upfront revenue recognition timelines.
Global Cloud Professional Services Market Segmentation
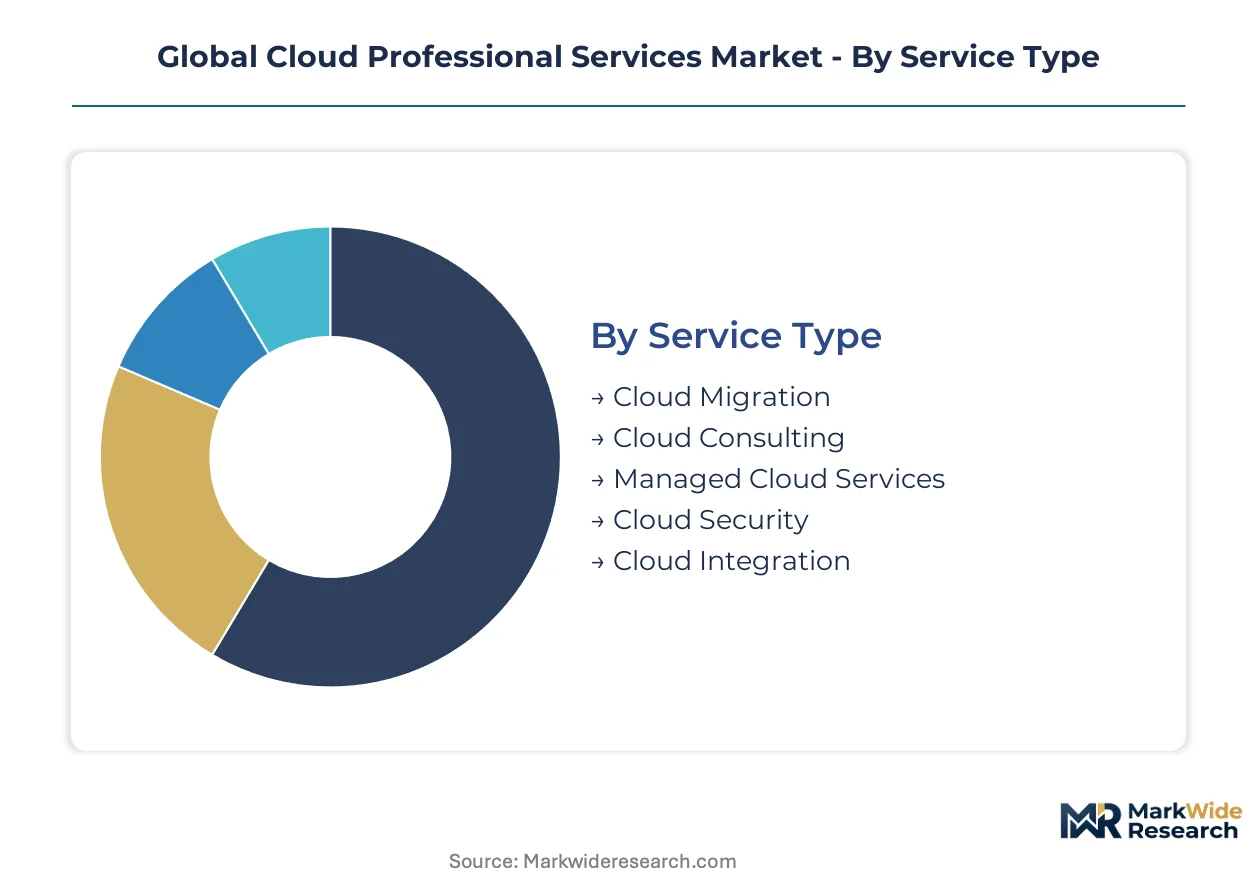
Cloud professional services segmentation reveals distinct margin profiles and substitution vulnerabilities across service delivery models. Deployment architecture choices and customer scale tiers determine pricing power and contract duration, while industry vertical specialization creates defensible advisory moats against platform-native competitors.
Service Type:
Substitution pressure from hyperscaler-managed offerings weighs heaviest on commoditized implementation tiers, while security-architecture and FinOps advisory segments maintain structural differentiation through credential scarcity and liability exposure.
- Cloud Migration:Workload assessment, replatforming, and data transfer engagements dominate project pipelines. Financial services institutions in Frankfurt and Singapore are compressing timelines to meet DORA and MAS operational resilience deadlines, elevating demand for risk-mitigated transition methodologies.
- Cloud Consulting:Strategic advisory spanning cloud economics, vendor selection, and governance framework design commands rate premiums. EU AI Act conformity assessments for high-risk AI deployments are creating specialized practices in Paris and Amsterdam that generalist competitors cannot replicate.
- Managed Cloud Services:24/7 infrastructure operations with guaranteed SLAs are displacing capital-intensive ownership models. India's PLI scheme for data center infrastructure is generating downstream managed services demand from Mumbai and Bangalore enterprise clusters.
- Cloud Security:Zero-trust architecture design, identity governance, and compliance automation address immutable logging mandates from SEC cybersecurity disclosure rules. HIPAA and PCI-DSS specialization creates rate premiums exceeding generalist security offerings.
- Cloud Integration:API governance, event-driven architecture, and legacy system connectivity bridge on-premises and cloud-native workloads. COBOL-dependent core banking systems in London and New York require specialized partner ecosystems that constrain supply.
Cloud Migration retains volume leadership; Cloud Security holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates commodity public workloads from premium private and sovereign cloud configurations, with hybrid architectures capturing mid-market budget allocations through phased migration flexibility.
- Public Cloud:Shared infrastructure with consumption-based pricing enables rapid scaling for variable workloads. Startups in Bangalore and Austin are defaulting to public-first strategies, though Schrems II compliance is fragmenting EU data residency architectures.
- Private Cloud:Dedicated single-tenant environments address regulated workload requirements with geographic control. German automotive manufacturers are deploying private cloud for engineering data sovereignty under CSRD supply chain disclosure obligations.
- Hybrid Cloud:Orchestrated workload portability between on-premises and cloud resources supports phased modernization. US healthcare systems are prioritizing hybrid architectures to maintain HIPAA-controlled data lakes while bursting analytics to public infrastructure.
- Multi-Cloud:Kubernetes-native portability across hyperscalers reduces vendor lock-in and optimizes regional performance. Singapore financial institutions are mandating multi-cloud resilience to satisfy MAS technology risk management guidelines.
Public Cloud dominates transaction volume; Multi-Cloud is climbing the fastest as procurement functions demand portability guarantees.
Industry Vertical:
Application-specific compliance burdens segment addressable markets, with financial services and government verticals commanding advisory premiums while manufacturing and media segments compete on implementation efficiency.
- BFSI:Core banking modernization, payment infrastructure, and regulatory reporting transformations absorb the largest professional services budgets. DORA implementation deadlines are forcing Frankfurt and London institutions into accelerated third-party risk management engagements.
- Telecommunications:5G network function virtualization and edge computing orchestration require low-latency cloud architectures. Indian carriers are investing in cloud-native billing systems under TRAI digital infrastructure mandates.
- Government:FedRAMP, StateRAMP, and EU GovCloud certifications create procurement barriers that favor established integrators. State-level digital service teams in California and Virginia are building internal platform engineering capabilities.
- Manufacturing:Industrial IoT data pipelines and digital twin deployments expand addressable market beyond traditional ERP migration. German Mittelstand firms are adopting edge-to-cloud architectures for predictive maintenance under Industry 4.0 investment programs.
- Media & Entertainment:Content supply chain modernization and direct-to-consumer platform engineering drive demand. Streaming services in Los Angeles and Seoul are optimizing cloud egress costs for global content delivery.
BFSI captures the largest revenue pool; Manufacturing is gaining share fastest through operational technology convergence.
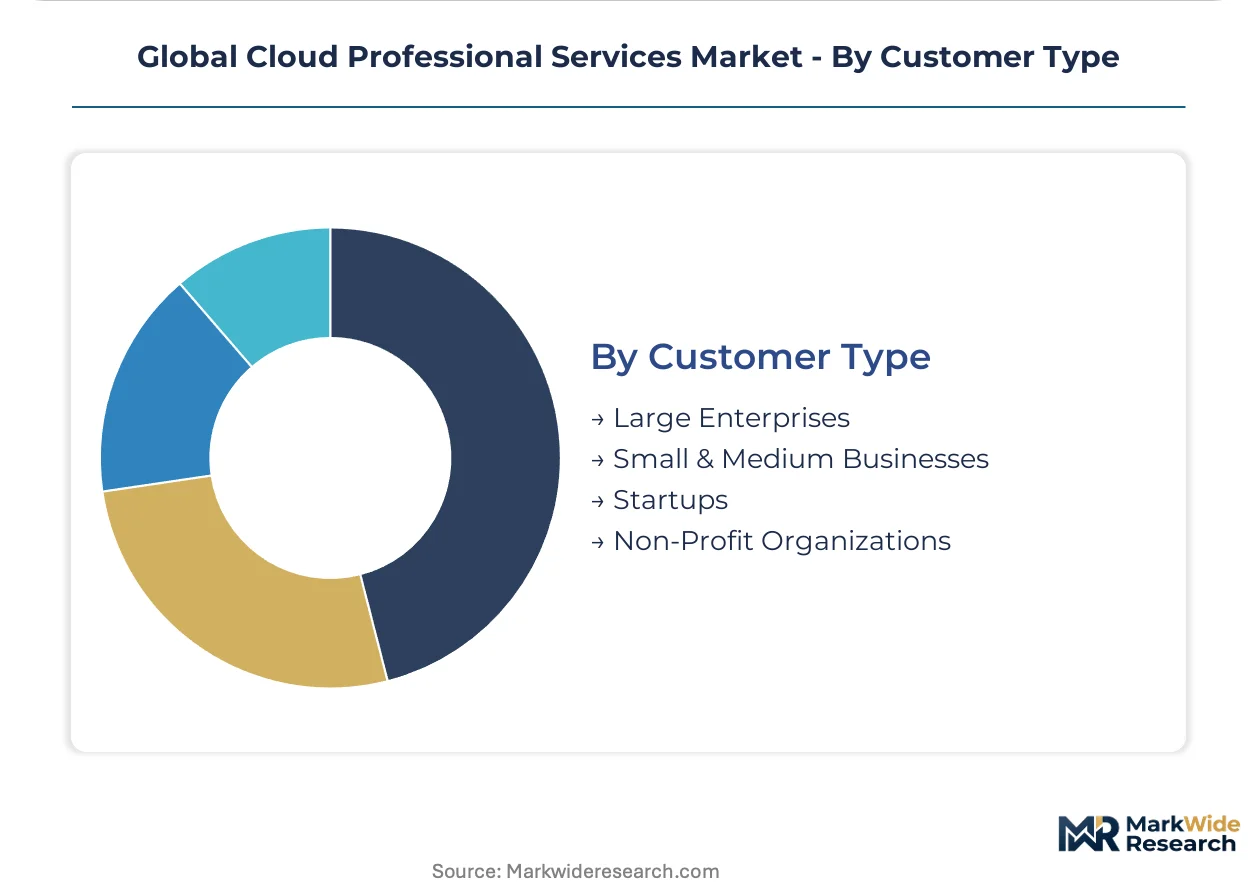
Customer Type:
Customer maturity and procurement sophistication determine service mix, with large enterprises purchasing integrated transformation programs while mid-market segments favor packaged migration accelerators.
- Large Enterprises:Multi-year transformation programs with dedicated delivery teams and outcome-based contracting structures. Fortune 500 procurement functions are inserting gainshare clauses tied to realized cloud cost reduction or security incident metrics.
- Small & Medium Businesses:Standardized migration packages with fixed pricing and accelerated deployment timelines. India's MSME sector is accessing cloud professional services through hyperscaler partner networks under Digital India initiatives.
- Startups:Cloud-native architecture design and DevOps automation for velocity-focused engineering teams. Venture-backed companies in Tel Aviv and Berlin are prioritizing platform engineering to compress deployment cycles.
- Non-Profit Organizations:Grant-funded digital transformation with compliance requirements from institutional donors. US healthcare non-profits are migrating to HIPAA-compliant cloud configurations under HRSA technology modernization programs.
Large Enterprises retain contract value leadership; Startups are expanding most quickly as venture deployment accelerates platform engineering adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landings at Mumbai, Chennai, and Cochin anchor India's data traffic exchange with global cloud regions. Frankfurt's DE-CIX internet exchange underwrites continental European cloud interconnection density. These infrastructure assets concentrate professional services demand in specific metropolitan clusters.
United States
Fortune 500 procurement functions in Chicago and New York are inserting gainshare clauses into cloud transformation contracts. SEC cybersecurity disclosure rules mandate immutable logging configurations that elevate security-architecture expertise to a primary vendor criterion. Silicon Valley enterprise clusters are deploying platform engineering teams with golden path templates at scale.
Germany
DORA operational resilience deadlines in January 2025 are compressing consulting sales cycles for Frankfurt financial institutions. CSRD supply chain disclosure obligations are forcing automotive manufacturers in Bavaria to deploy private cloud for engineering data sovereignty. Berlin-based digital service teams are building internal platform engineering capabilities under federal modernization programs.
India
PLI scheme incentives for data center infrastructure are attracting hyperscaler investment into Mumbai and Chennai corridors. RBI operational resilience guidelines for banks are accelerating third-party risk management engagements. Bangalore enterprise clusters are generating downstream managed services demand for migration and 24/7 operations.
United Kingdom
FCA operational resilience deadlines are forcing London financial institutions into accelerated cloud migration timelines. NHS digital transformation programs are prioritizing hybrid architectures for HIPAA-controlled data lakes. Manchester and Leeds manufacturing clusters are adopting edge-to-cloud architectures under Industry 4.0 investment programs.
Singapore
MAS technology risk management guidelines are mandating multi-cloud resilience for financial institutions. Submarine cable connectivity through Tuas anchors ASEAN cloud traffic exchange with global regions. Government digital service teams are deploying platform engineering capabilities at scale across the island's enterprise clusters.
Global Cloud Professional Services Market Competitive Landscape
Listed leaders compete with private specialists across credential scarcity and liability exposure dimensions. Tiered concentration persists between global system integrators with multi-cloud architecture practices and cloud-native engineering boutiques with Kubernetes-native capabilities. Two strategic archetypes dominate: full-service transformation partners with industry vertical depth, and platform-native specialists with hyperscaler certification density. Competitive moves center on M&A for ISO 27001 lead auditor talent and strategic partnerships for legacy mainframe bridge architectures.
Within the full-service transformation tier, Accenture and Deloitte exemplify archetypes differentiated by multi-cloud architecture depth versus regulatory compliance specialization. IBM occupies a position bridging proprietary hybrid cloud platforms with consulting delivery integration. These anchors sit within a vendor base where credential scarcity constrains project scaling for mid-tier consultancies.
| Leading Market Players |
|---|
| Accenture |
| Deloitte |
| IBM |
| PwC |
| EY |
| Capgemini |
| Microsoft Corporation |
| Amazon Web Services |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
Container orchestration expertise displacing traditional infrastructure labor pools is redrawing supply geography toward Bangalore and Hyderabad talent corridors while compressing rate premiums for commoditized migration services. This substitution simultaneously elevates project pricing for Kubernetes-certified architects and erodes margins for ticket-based managed service providers locked in legacy delivery models.
Pricing Analysis
Certification level creates the primary spread between rate tiers, with ISO 27001 lead auditor credentials commanding substantial premiums over generalist security offerings. Three-tier pricing structure across premium, standard, and economy levels segments engagements by liability exposure and compliance complexity. Cost compression in implementation tiers is intensifying because hyperscaler-managed offerings automate routine workload migrations. Mid-market enterprises exhibit highest price sensitivity, while Frankfurt and Singapore financial institutions prioritize risk-mitigated methodologies over unit economics.
Supply Chain Analysis
India and Germany anchor professional services delivery, with Mumbai and Chennai corridors feeding migration and managed operations demand while Frankfurt concentrates DORA compliance advisory. Talent pipelines draw from university partnerships, hyperscaler certification programs, and legacy system integrator alumni networks. Single-source vulnerability concentrates in ISO 27001 lead auditor pools where credential scarcity constrains project scaling. Distribution runs through direct enterprise sales, hyperscaler partner marketplaces, and systems integrator subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 27001 certification cycles and zero-trust architecture proficiency gaps are constraining supply elasticity, creating structural premiums for credentialed practices while marginalizing generalist competitors unable to bridge capability investments.
For Market Incumbents: Fortify multi-cloud architecture practices through acquisition of Kubernetes-native engineering boutiques in Tel Aviv and Berlin clusters. Deepen regulatory compliance specialization around EU AI Act conformity assessments to defend margin position against hyperscaler-managed service encroachment. Prioritize captive development of zero-trust architecture talent pipelines rather than subcontractor dependence. For New Entrants and Emerging Players: Fast-track ISO 27001 certification through accredited training partnerships offers entry into Frankfurt and London financial services procurement shortlists. Target mid-market manufacturing verticals in Bavaria and Manchester where edge-to-cloud orchestration demand outpaces established vendor capacity. Lead with FinOps advisory bundled with CSRD sustainability reporting to differentiate from implementation-focused competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-native specialists with hyperscaler certification density over generalist system integrators. Long-term viability hinges on regulatory technology integration capabilities spanning EU AI Act and DORA compliance automation. Watch for inflection in MAS and RBI operational resilience guideline enforcement as signal for Asia-Pacific services demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Creates procurement eligibility for Frankfurt and Singapore financial institutions under DORA and MAS guidelines. |
| Zero-Trust Architecture Practice Buildout | Addresses SEC cybersecurity disclosure mandates and HIPAA audit requirements with specialized advisory offerings. |
| Hyperscaler Partnership Tier Advancement | Unlocks co-sell mechanisms and managed service revenue sharing through AWS and Azure marketplace integration. |
| FinOps Platform Integration | Captures CSRD reporting obligations convergence with cloud cost optimization across German automotive supply chains. |
| Edge-to-Cloud Orchestration Capability | Expands addressable market into German Mittelstand predictive maintenance and UK manufacturing IoT deployments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud architects, CISOs, enterprise procurement officers, and hyperscaler partner program managers; and secondary validation against SEC cybersecurity disclosure filings, EU regulatory implementation timelines, hyperscaler capex and headcount disclosures, and RBI operational resilience guideline drafts. Bottom-up project pipeline analysis across Frankfurt, London, Mumbai, and Singapore enterprise clusters triangulated with top-down market sizing from service provider revenue disclosures.
Across the analysis window, projections model service type segmentation spanning migration, consulting, managed services, security, and integration; deployment architecture choices across public, private, hybrid, and multi-cloud; and industry vertical concentration in BFSI, telecommunications, government, manufacturing, and media. CAGRs derive from regression against historical professional services spending correlated with regulatory deadline enforcement patterns and hyperscaler infrastructure investment cycles. Forecast inputs incorporate PLI scheme incentive disbursement trajectories and DORA implementation compliance cost estimates.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and hyperscaler capacity expansion continuity; material deviation in EU AI Act penalty structures or GPU hardware availability would warrant model refresh. Recalibration cycles align with material shifts in central bank operational resilience guideline issuance and hyperscaler regional data center commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
North America Managed Services Market