
 Global Enterprise Data Integration Market | 2026-2036
Global Enterprise Data Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Data Integration Market Foresight
GDPR enforcement is repositioning the cost-of-entry calculus for enterprise data integration vendors, forcing substantial investments in consent-aware pipeline architecture and cross-border data governance. IBM Corporation leverages its mainframe heritage and cloud brokerage capabilities to anchor complex hybrid deployments for regulated financial institutions. Microsoft Corporation competes through deep Azure-native integration with productivity suites, sustaining enterprise lock-in across Office and Dynamics ecosystems. Oracle Corporation dominates in data replication and federation for large-scale ERP consolidation projects, extending its database-installed base into integration middleware.
Enterprise data integration encompasses the architectural discipline, software tooling, and operational processes required to unify disparate data sources across organizational boundaries through standardized APIs, semantic mediation layers, and real-time streaming protocols. The primary industrial purpose is to enable consistent analytics, automated decision workflows, and regulatory reporting by eliminating data silos and ensuring temporal consistency across operational and analytical systems. Cloud deployment now leads in new bookings as lift-and-shift fatigue gives way to API-first managed services, while hybrid configurations capture the strongest margin pools where governance complexity demands professional services attachment. Extract Transform Load remains mature with slowing growth, whereas data virtualization expands fastest by eliminating physical movement overhead for exploratory analytics workloads.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps by mandating explainable data lineage, audit-ready provenance, and automated risk classification across integration flows. HIPAA in the United States imposes additional encryption and access-control specifications for healthcare data pipelines, narrowing the vendor set qualified for provider networks. Stakeholders must monitor how emerging algorithmic accountability frameworks in Brussels and Washington redefine liability for data quality failures in automated decision chains.
Market Dynamics
The enterprise data integration market pivots on regulatory fragmentation between the EU AI Act and US SEC disclosure mandates, which compels vendors to architect dual-track compliance systems while preserving cross-border data fluidity for multinational banking and healthcare clients.
Growth Catalysts
- EU AI Act lineage requirements:Automated decision systems in European financial services now demand traceable data provenance, accelerating procurement of governed pipeline platforms that embed audit trails by design.
- Real-time streaming protocols:Capital markets firms deploy event-driven architectures to compress latency between transactional and analytical systems, eliminating batch-window bottlenecks for intraday risk calculations.
- Federal cloud mandates in the United States:US banking regulators push hybrid integration upgrades, creating immediate demand for API-first managed services that bridge on-premise mainframe estates with sovereign cloud instances.
Market Restraints
- Cross-border data localization:China's data security law and Russia's sovereign internet rules fragment global data flows, forcing redundant infrastructure deployment and inflating total cost of ownership for multinational deployments.
- Specialized talent scarcity:Pipeline engineering for HIPAA-compliant healthcare networks and GDPR-auditable financial systems requires rare combinations of domain expertise and cloud-native certification, constraining implementation velocity.
- Legacy system entrenchment:Decades-old ERP consolidations in manufacturing and energy sectors resist API abstraction, prolonging migration timelines and diluting return on integration investments.
Strategic Opportunities
- Data virtualization in exploratory analytics:Eliminating physical data movement for ad-hoc research workloads opens margin-rich service attachments in pharmaceutical and biotechnology R&D functions.
- India's digital public infrastructure:The country's account aggregator framework and open credit enablement network create greenfield demand for consent-aware integration layers in emerging fintech ecosystems.
- Convergence of semantic mediation with generative AI:Unified ontology layers that feed large language models with governed, context-rich data streams represent untapped architectural white space for vendor differentiation.
Industry Challenges
- Multi-framework compliance engineering:Simultaneous adherence to GDPR's right-to-explanation, HIPAA's minimum necessary standard, and SEC cybersecurity disclosure rules demands prohibitively complex policy orchestration layers.
- Technical debt in ETL estates:Thousands of undocumented batch processes in incumbent financial institutions resist cataloging, complicating cloud migration and lineage reconstruction efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Data Integration Market |
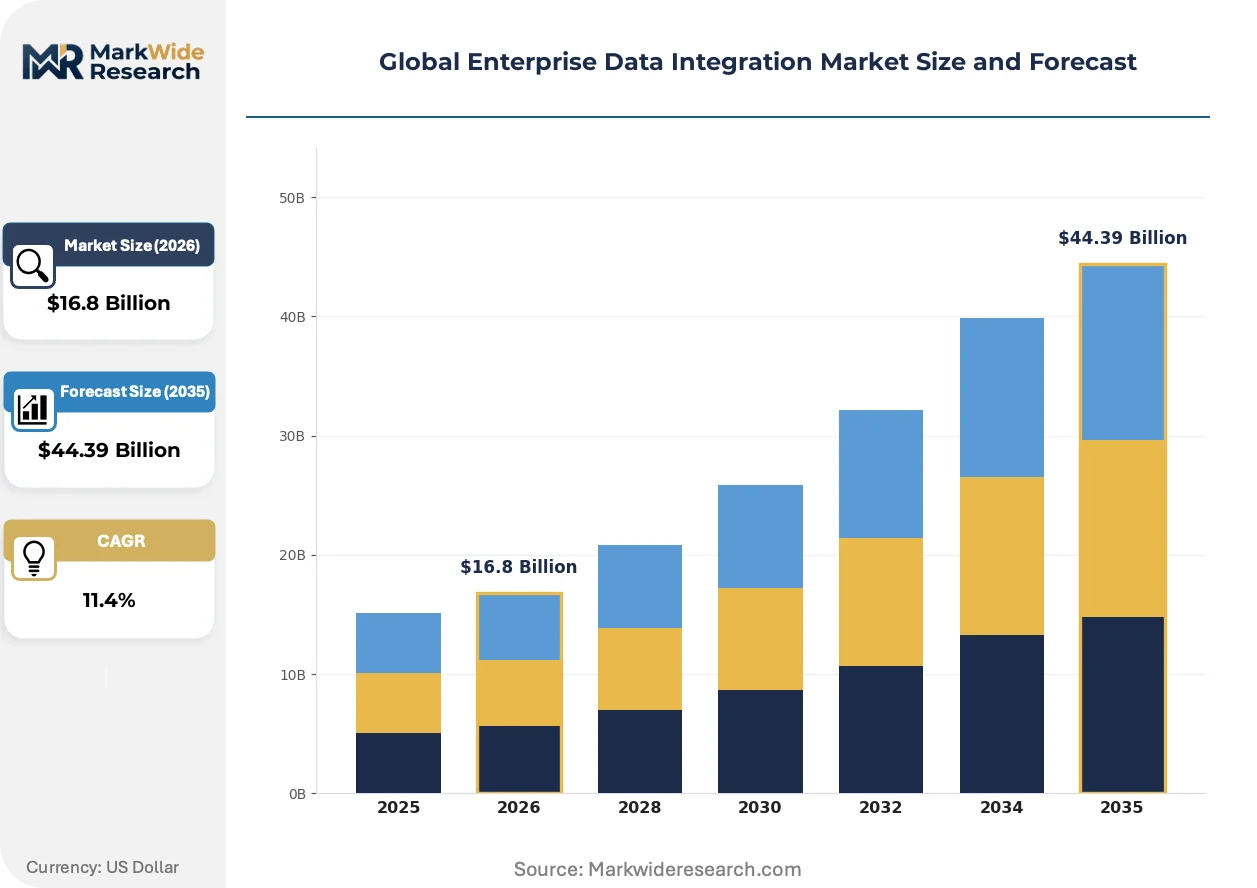
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $44.39 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Private Cloud, Public Cloud Solution/Offering: Data Replication, Data Federation, Data Virtualization, Extract Transform Load, Enterprise Service Bus Application: Customer Data Management, Supply Chain Optimization, Risk Management, Financial Reporting, Regulatory Compliance End User Industry: Banking, Telecommunications, Manufacturing, Government, Transportation |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Informatica Corporation, SAS Institute Inc., Talend Inc., Cisco Systems, Denodo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Data Integration Market Shifts & Advancements
Generative AI capabilities are compressing traditional data preparation timelines, forcing vendors to reposition integration platforms as intelligent orchestration layers rather than passive plumbing infrastructure.
Semantic knowledge graphs are automating entity resolution across fragmented enterprise datasets. Pharmaceutical manufacturers deploy these systems to harmonize clinical trial data with real-world evidence registries, collapsing months of manual curation into hours. The structural consequence is a shift from physical consolidation toward virtualized data fabrics that preserve source system autonomy.
The EU AI Act's risk classification framework imposes mandatory documentation burdens on high-risk automated decision systems. Financial institutions in Germany and France must now maintain immutable audit trails for credit scoring algorithms, driving procurement of integration platforms with embedded provenance capture. Vendors respond by embedding cryptographic attestation into pipeline metadata.
Buyers in the United States healthcare sector increasingly unbundle integration services from incumbent EHR contracts, seeking specialized vendors for population health analytics pipelines. This procurement fragmentation favors boutique firms with deep HIPAA expertise over generalist platforms, concentrating new bookings among certified healthcare interoperability specialists operating in Texas and California hospital networks.
Global Enterprise Data Integration Market Segmentation
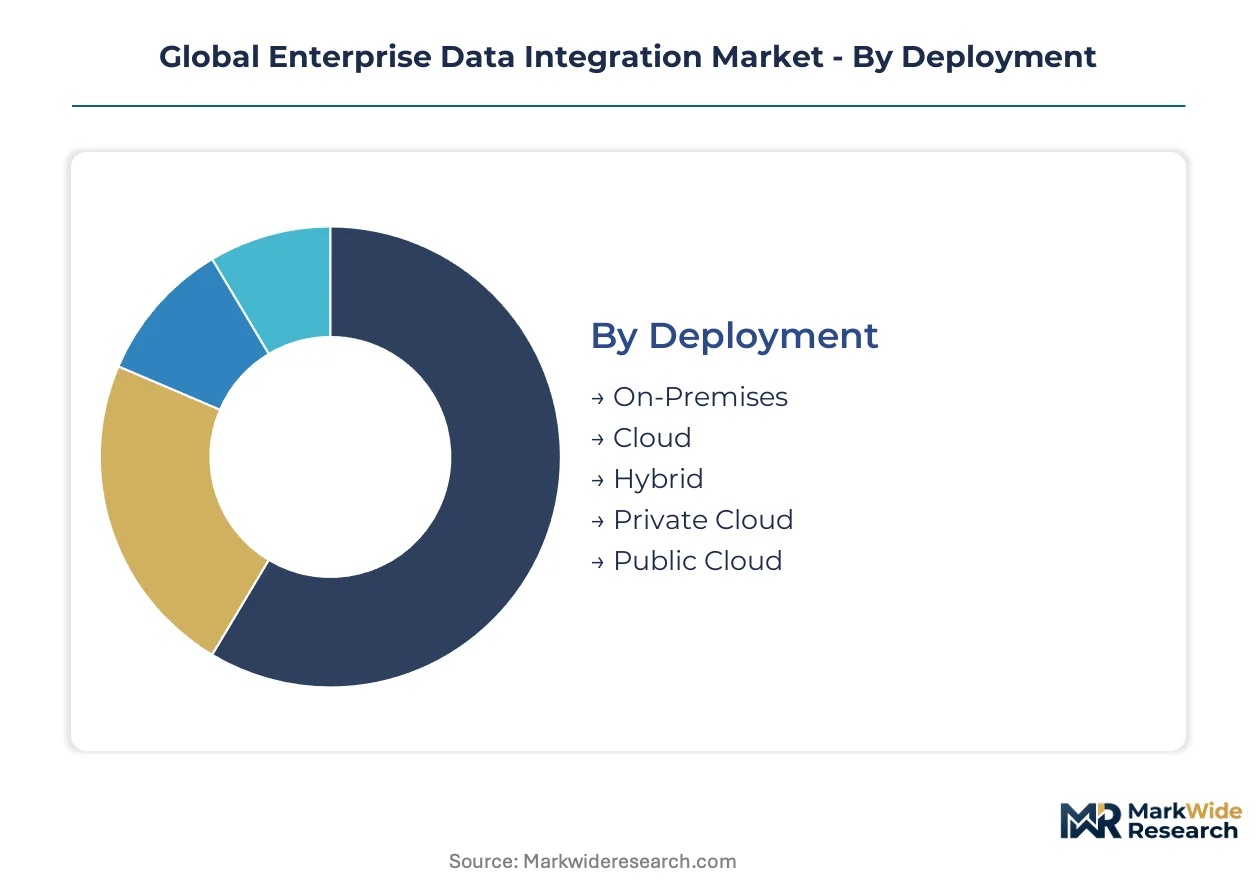
Deployment architecture determines compliance burden and margin structure across the enterprise data integration landscape. Solution maturity, application criticality, and end-user regulatory exposure collectively shape procurement patterns and vendor qualification requirements.
Deployment:
Cloud-native deployments face lighter certification overhead than on-premise estates, though hybrid configurations must satisfy dual-track audit regimes across sovereign jurisdictions.
- On-Premises:Legacy mainframe-connected pipelines retain dominance in German and French banking networks where GDPR data residency rules mandate physical control. Bundesbank and Banque de France supervisory guidance perpetuates this architecture despite higher operational overhead.
- Cloud:API-first managed services accelerate in United States federal contracting where FedRAMP authorization streamlines procurement. The SEC cybersecurity disclosure rules favor cloud-native audit logging that automates lineage capture for examiner review.
- Hybrid:Bridges sovereign cloud instances with on-premise data lakes, capturing strongest margin pools where governance complexity demands professional services attachment.
- Private Cloud:Isolated tenant environments satisfy China's data security law localization mandates for multinational manufacturers operating in Shanghai and Shenzhen industrial zones.
- Public Cloud:Shared infrastructure deployments concentrate in Indian fintech startups leveraging the account aggregator framework's consent-aware integration specifications.
On-Premises sits at the top of the volume ranking, with Cloud climbing the fastest.
Solution/Offering:
Solution selection correlates directly with data movement economics and query latency requirements, with virtualization commanding premium pricing against mature ETL alternatives.
- Data Replication:Physical copy creation across heterogeneous systems dominates Oracle-installed base extensions for large-scale ERP consolidation projects in Texas and California energy sectors.
- Data Federation:Distributed query processing without consolidation serves real-time risk aggregation in London and Singapore trading floors where latency tolerance measures in milliseconds.
- Data Virtualization:Eliminates physical movement overhead for exploratory analytics workloads, expanding most quickly in Swiss and Danish pharmaceutical R&D functions where source system autonomy preserves clinical trial integrity.
- Extract Transform Load:Batch-process consolidation of decades-old pipelines faces technical debt accumulation in incumbent financial institutions, constraining migration velocity.
- Enterprise Service Bus:Message-oriented middleware mediates service interactions across Italian and Spanish manufacturing ERP estates resisting API abstraction.
Extract Transform Load retains the largest installed base, while Data Virtualization gains share fastest among new procurement.
Application:
Application priority reflects regulatory enforcement intensity, with compliance and risk functions commanding budget precedence over operational optimization.
- Customer Data Management:Unified profiling across channels accelerates in Brazilian and Mexican retail banking where central bank open finance mandates drive consent-aware pipeline investment.
- Supply Chain Optimization:Multi-tier visibility platforms deploy across Vietnamese and Indonesian electronics manufacturing clusters seeking to diversify from single-source dependencies.
- Risk Management:Intraday calculation pipelines compress latency between transactional and analytical systems in New York and Chicago capital markets.
- Financial Reporting:Automated consolidation satisfies SEC disclosure timelines for accelerated filers in Delaware and Nevada corporate domiciles.
- Regulatory Compliance:Immutable audit trail construction addresses EU AI Act risk classification burdens for German and French credit scoring automation.
Regulatory Compliance anchors current spending priority, with Risk Management expanding most quickly among capital markets participants.
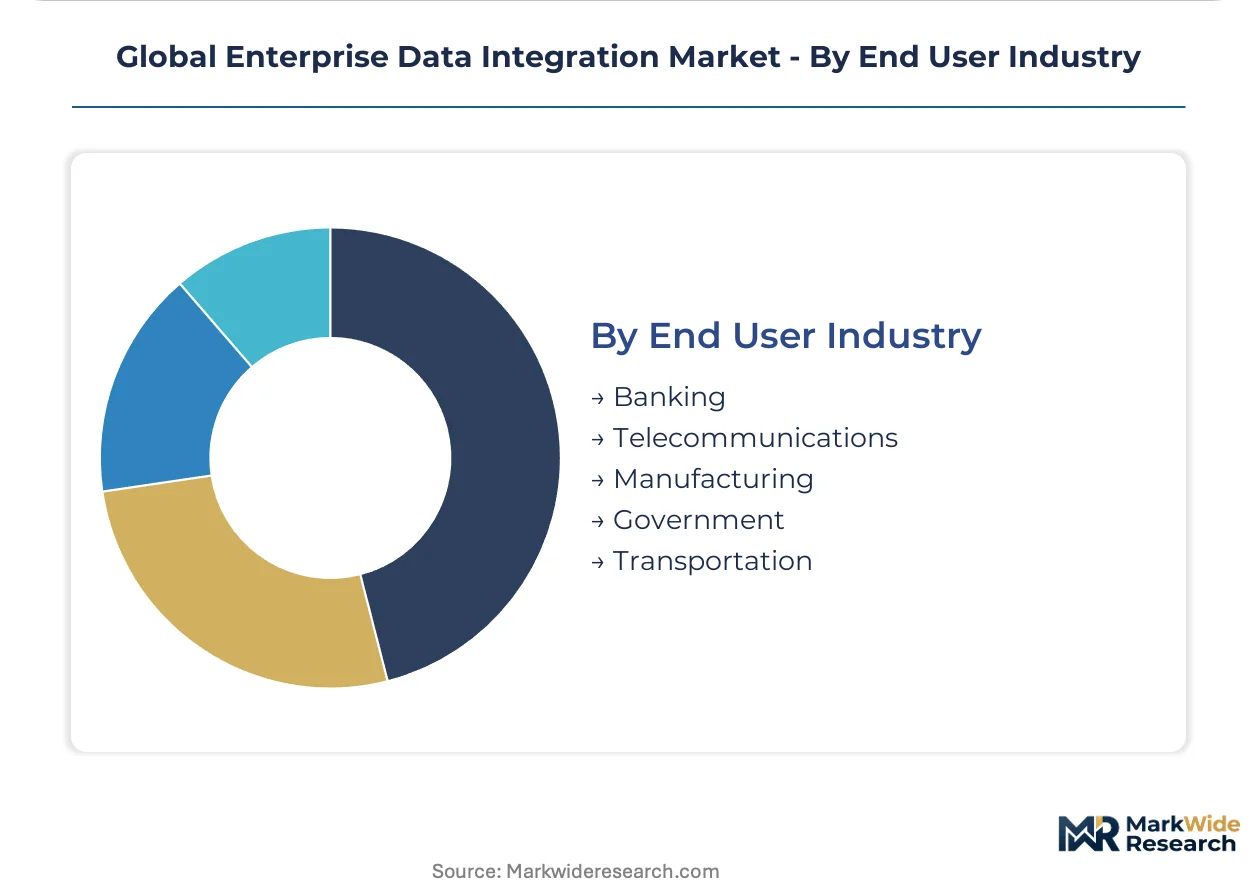
End User Industry:
Industry verticals exhibit divergent certification requirements, with HIPAA and GDPR dual exposure in healthcare-adjacent banking segments creating vendor qualification bottlenecks.
- Banking:Unified data platforms streamline Basel III liquidity reporting and customer analytics across Swiss, Dutch, and Swedish systemically important institutions.
- Telecommunications:Subscriber data unification supports churn prediction and network optimization in South Korean and Japanese 5G rollout markets.
- Manufacturing:ERP consolidation resistance prolongs migration timelines in German automotive and Japanese precision engineering supply chains.
- Government:Sovereign cloud integration mandates accelerate in United States federal agencies and Australian state-level digital transformation programs.
- Transportation:Fleet telematics harmonization proceeds in UAE and Saudi logistics corridors connecting port automation with customs modernization.
Banking occupies the dominant revenue position, with Government procurement climbing fastest under sovereign infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native architects and data governance specialists cluster in financial centers where regulatory complexity demands hybrid integration expertise. Talent density in these markets anchors procurement decisions for governed pipeline platforms.
United States
Federal cloud mandates and SEC cybersecurity disclosure rules drive hybrid architecture upgrades across Delaware and Nevada corporate domiciles. FedRAMP authorization streamlines procurement for API-first managed services bridging on-premise mainframes with sovereign cloud instances. New York and Chicago capital markets compress latency between transactional and analytical systems through event-driven architectures.
Germany
Bundesbank supervisory guidance perpetuates on-premise dominance in systemically important banking networks where GDPR data residency rules mandate physical control. The EU AI Act's risk classification framework imposes immutable audit trail requirements on credit scoring automation in Frankfurt and Munich. German automotive supply chains resist API abstraction, prolonging ERP consolidation timelines.
India
The account aggregator framework and open credit enablement network create greenfield demand for consent-aware integration layers in emerging fintech ecosystems. RBI oversight shapes pipeline architecture for unified customer profiling across Mumbai and Bengaluru digital banking platforms. Telangana and Karnataka host concentrated startup activity leveraging API-first specifications for financial data sharing.
Switzerland
Swissmedic-aligned pharmaceutical manufacturers deploy semantic knowledge graphs to harmonize clinical trial data with real-world evidence registries in Basel and Zurich R&D clusters. FINMA governance requirements anchor data lineage investments for private banking networks. Swiss data residency preferences sustain premium pricing for hybrid configurations with professional services attachment.
United Kingdom
FCA operational resilience directives accelerate procurement of real-time streaming protocols for London trading floors where latency tolerance measures in milliseconds. The UK Information Commissioner's Office enforces GDPR-aligned consent management for cross-border data flows. Edinburgh and Manchester financial services clusters drive demand for governed pipeline platforms with embedded provenance capture.
Global Enterprise Data Integration Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with legacy infrastructure footprints. Consolidation pressure favors vendors possessing both cloud-native orchestration capabilities and mainframe connectivity expertise. Three archetypes dominate: database-installed-base extenders, cloud brokerage platforms, and specialized virtualization specialists. Strategic moves concentrate on hybrid deployment certifications and vertical-specific compliance engineering rather than pure technology differentiation.
Within the database heritage tier, Oracle Corporation and IBM Corporation exemplify archetypes leveraging decades-old ERP relationships into integration middleware procurement decisions. Microsoft Corporation occupies a position bridging productivity suite lock-in with Azure-native managed services. Among pure-play alternatives, Denodo Technologies and Talend Inc. represent the virtualization-native and open-source-derived segments respectively, each anchoring distinct buyer psychographies around source system autonomy versus cost-engineered deployment.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Informatica Corporation |
| SAS Institute Inc. |
| Talend Inc. |
| Cisco Systems |
| Denodo Technologies |
| Others |
Supply & Pricing Matrix
Captive professional services integration anchors both supply positioning and pricing power for enterprise data integration vendors, with hybrid deployment complexity in German and French banking networks sustaining premium attach rates for compliance-engineered implementations. This vertical integration choice insulates margin pools from pure-play cloud-native competitors while tethering revenue growth to scarce pipeline engineering talent density in financial centers.
Pricing Analysis
The bundled-vs-unbundled service split separates legacy ERP-extender pricing from API-first managed service models. Subscription-tiered SaaS structures dominate cloud-native procurement, while project-based professional services capture premium tiers where GDPR and EU AI Act lineage requirements demand custom policy orchestration. Price differentiation rests on certification grade—FedRAMP-authorized vendors command 20-40% premiums over uncertified alternatives—and vertical integration depth, with mainframe-connected incumbents extracting higher margins from hybrid complexity. Pricing pressure stems from Indian fintech startups unbundling integration from core banking contracts, compressing entry-level tiers. Healthcare providers in Texas and California exhibit highest price sensitivity due to HIPAA compliance overhead, while Swiss private banking networks show lowest sensitivity given FINMA-driven non-negotiable lineage investments.
Supply Chain Analysis
Reverse-logistics flows for data integration center on cloud instance migration and legacy ETL estate decommissioning, with vendors offering automated cataloging tools to recover value from undocumented batch processes. Engineering talent supply concentrates in India, the United States, and Switzerland, where RBI oversight, FedRAMP authorization pathways, and FINMA governance requirements respectively shape certification pipelines. Raw material dependencies include sovereign cloud infrastructure, cryptographic attestation modules, and semantic ontology libraries. Single-source vulnerability runs through hyperscaler compute availability for API-first managed services. Distribution runs through direct enterprise sales teams for hybrid deployments and self-service marketplaces for cloud-native tiers, with channel partners dominating in manufacturing ERP consolidation resistant to API abstraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in enterprise data integration hinges on cost compression in cloud-native orchestration layers and premium-tier pricing power from EU AI Act compliance engineering. Automation of lineage capture and policy orchestration shifts cost structures downward while regulatory mandates sustain pricing floors.
For Market Incumbents: Lock in hybrid deployment dominance by embedding cryptographic attestation into pipeline metadata before pure-play virtualization specialists achieve FedRAMP authorization. Acquire boutique HIPAA compliance engineering teams in Texas and California hospital networks to defend against unbundling trends in US healthcare procurement. Prioritize mainframe connectivity IP as cloud brokerage capabilities face margin compression from hyperscaler-native alternatives.
For New Entrants and Emerging Players: API-first self-service marketplaces offer the lowest customer acquisition cost route into Indian fintech ecosystems leveraging RBI's account aggregator framework. Target consent-aware integration layers for Brazil and Mexico open finance mandates, where central bank regulations create greenfield procurement windows absent incumbent ERP lock-in. Lead with data virtualization for Swiss pharmaceutical R&D functions, where source system autonomy commands premium pricing and implementation complexity deters generalist competition.
For Investors and Strategic Acquirers: Roll-up economics work for healthcare interoperability specialists because HIPAA-GDPR dual certification scarcity creates persistent vendor qualification bottlenecks in banking-adjacent healthcare segments. Long-term viability favors platforms combining semantic knowledge graph capabilities with generative AI orchestration layers, as unified ontology feeding governed LLM data streams represents architectural white space with 5-10 year differentiation runway. Monitor EU AI Act enforcement intensity in German and French credit scoring automation as the inflection signal for provenance-capture platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Certification | FedRAMP authorization unlocks US federal procurement pipelines constrained by SEC cybersecurity disclosure mandates. |
| Semantic Knowledge Graph Integration | Swissmedic-aligned pharmaceutical manufacturers in Basel collapse clinical trial curation timelines from months to hours. |
| Acquisition of HIPAA Specialists | Texas and California hospital networks unbundle from incumbent EHR contracts, fragmenting procurement toward certified boutiques. |
| API-First Self-Service Marketplace | RBI account aggregator framework in Mumbai and Bengaluru enables consent-aware fintech integration without legacy overhead. |
| Embedded Provenance Capture | EU AI Act risk classification in Frankfurt and Munich mandates immutable audit trails for automated credit decisions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists at financial institutions, pharmaceutical manufacturers, and federal agencies with secondary validation through SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and EU regulatory implementation guidance. Bottom-up deployment modeling across cloud, hybrid, and on-premise architectures triangulated against top-down market sizing from vendor revenue disclosures and systems integrator booking data.
Segment-weighting approaches distributed value across deployment architecture, solution type, application priority, and end-user industry vertical, with regional adoption patterns further stratifying the model. CAGRs derived from regression analysis of historical booking growth rates against regulatory enforcement timelines and cloud migration velocity, incorporating inputs from pipeline engineering talent supply constraints and sovereign cloud infrastructure availability across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for generative AI-native data preparation would alter the outlook if autonomous orchestration displaces traditional ETL reconstruction efforts. Forecasts reflect assumptions about EU AI Act implementation consistency, HIPAA enforcement intensity in US healthcare networks, and hyperscaler pricing discipline for compute-intensive virtualization workloads. Practitioners should monitor Bundesbank and Banque de France supervisory guidance evolution, RBI fintech licensing velocity, and FedRAMP authorization queue backlogs for early signals of supply-side constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
HR Tech Consulting Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
United States Managed Services Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Supplier Management Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
IT Staffing Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Global AWS Managed Services Market