
 Middle East and Africa E-Commerce Market | 2026-2036
Middle East and Africa E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa E-Commerce Market Foresight
Product bundling across electronics and accessories is decoupling traditional single-item purchasing patterns across MEA digital storefronts. Jumia leverages its proprietary logistics network to sustain last-mile coverage in underpenetrated African cities. Amazon MENA anchors its fulfillment architecture around same-day delivery zones in Dubai and Riyadh. Noon competes aggressively on electronics pricing while building localized warehousing capacity.
Middle East and Africa e-commerce denotes digitally mediated retail transactions executed through web-based platforms and mobile applications, typically requiring secure payment gateways, inventory management systems, and multi-modal logistics orchestration to connect dispersed buyers with distributed seller networks. Fashion and electronics product types currently generate the highest transaction velocities, though beauty products represent the fastest-expanding margin pool as influencer-driven discovery reshapes purchase pathways. The B2C business model dominates transaction volume, while B2B procurement platforms are gaining structural traction among SMEs seeking industrial supply chain digitization across Gulf manufacturing clusters.
SAMR in Saudi Arabia, the UAE's TDRA digital transaction standards, and South Africa's FSCA consumer protection frameworks collectively impose escalating compliance burdens on cross-border payment processing and data localization. These regulatory architectures directly shape platform infrastructure investments, particularly around digital wallet certification and customer identity verification protocols. Stakeholders must monitor evolving Gulf data sovereignty requirements and African central bank digital currency pilots to anticipate payment method disruptions.
Market Dynamics
Product bundling across electronics and accessories is decoupling traditional single-item purchasing patterns, forcing platforms to reconfigure inventory management and fulfillment architectures around basket economics rather than individual SKU velocity.
Growth Catalysts
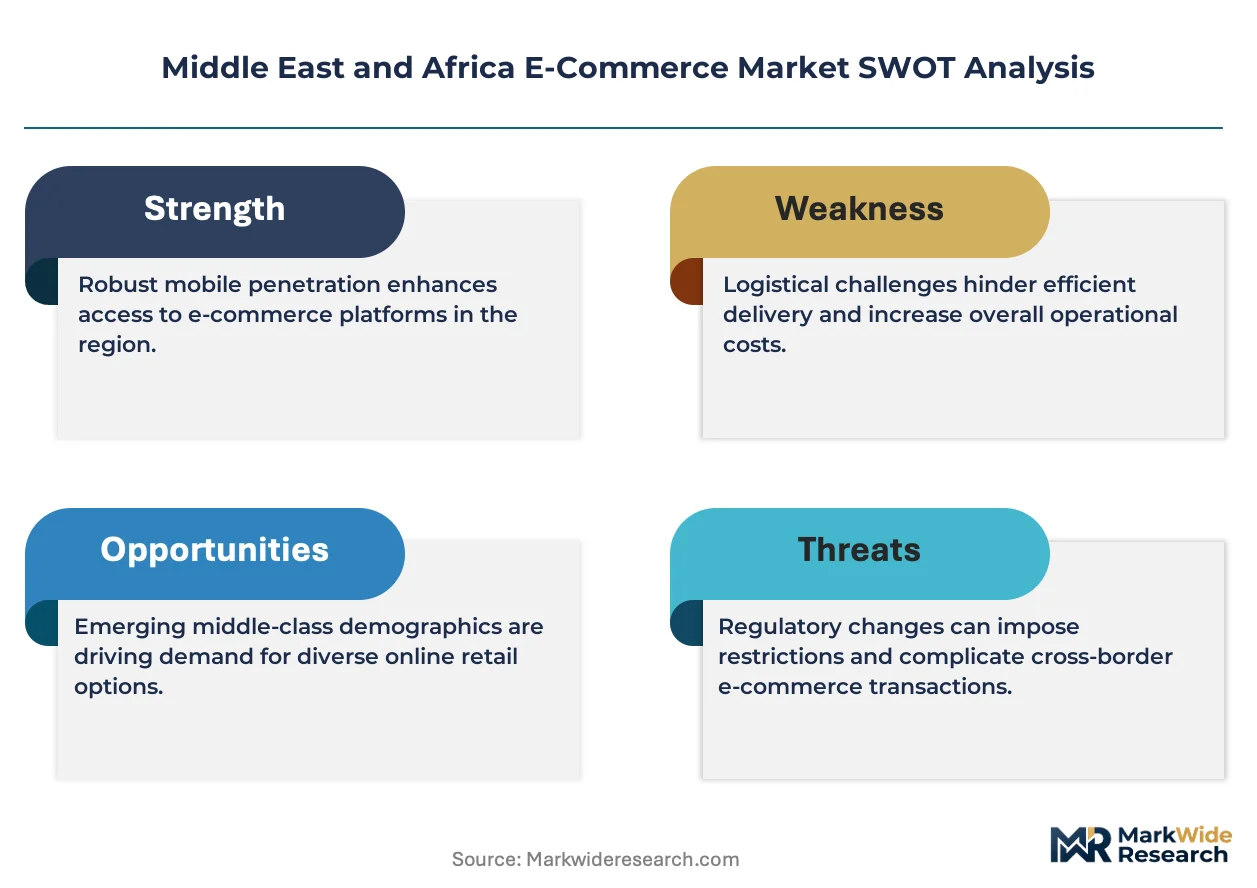
- Saudi SAMR Digital Commerce Standards:These certification requirements for payment gateways and data localization are accelerating platform infrastructure investments and elevating consumer trust in cross-border transactions.
- Urban Millennial Demand Concentration:Fashion and electronics adoption clusters in Gulf Cooperation Council cities are generating sufficient transaction density to justify same-day fulfillment network buildouts.
- CBDC Pilots:African central bank digital currency experiments are reshaping payment method availability and reducing friction in mobile-first commerce corridors.
Market Restraints
- Last-Mile Logistics Cost Volatility:Fuel price fluctuations and informal addressing systems in underpenetrated African cities compress margin structures for delivery operations.
- Cross-Border Data Localization Mandates:Gulf data sovereignty requirements fragment cloud infrastructure investments and multiply compliance certification timelines.
- Cash-on-Delivery Persistence:This payment method retains dominant share in Nigerian and Egyptian markets, limiting working capital efficiency and fraud exposure for platforms.
Strategic Opportunities
- Nigerian SME B2B Procurement Digitization:Industrial supply chain platforms targeting manufacturing clusters can capture procurement workflow migration from offline wholesale channels.
- Influencer-Driven Beauty Discovery:Social commerce integration creates direct purchase pathways from content to checkout, bypassing traditional search-based product discovery.
- UAE TDRA Digital Wallet Certification:Regulatory clarity on stored-value facilities enables fintech-platform partnerships that reduce payment abandonment rates.
Industry Challenges
- Digital Identity Verification Talent Scarcity:KYC/AML engineering expertise concentrates in Dubai and Riyadh, creating recruitment bottlenecks for platform expansion into secondary markets.
- Multi-Modal Logistics Integration Complexity:Synchronizing air freight, last-mile couriers, and locker networks across fragmented African urban infrastructure demands proprietary technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa E-Commerce Market |
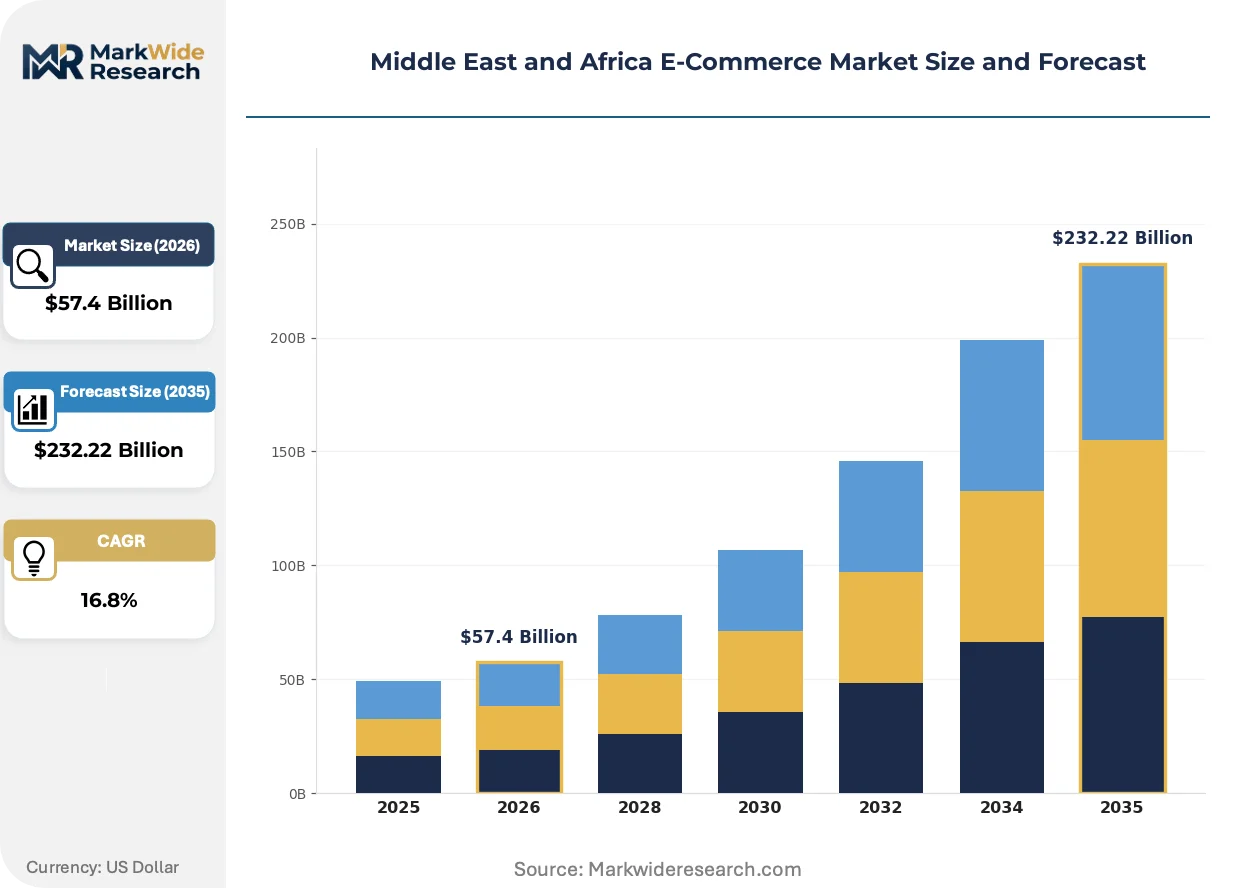
| Market Size in 2026 | $57.4 Billion |
| Market Size in 2035 | $232.22 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Appliances, Beauty Products Business Model: B2B, B2C, C2C, C2B Payment Method: Card Payments, Digital Wallets, Bank Transfers, Cash on Delivery Delivery Method: Same-Day Delivery, Standard Shipping, In-Store Pickup, Third-Party Logistics |
| Companies Covered | Noon, Jumia, Amazon MENA, Souq.com, Takealot, Namshi, Zando, AliExpress, Konga, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa E-Commerce Market Shifts & Advancements
Mobile-first discovery interfaces and embedded finance capabilities are compressing the traditional e-commerce funnel from awareness to transaction, collapsing multiple touchpoints into single-session purchase completion.
AI-powered visual search is consolidating product discovery behavior across fashion and beauty categories. Urban millennial shoppers in Dubai and Riyadh are adopting camera-based search at accelerating rates. This technology is consolidating catalog browsing into intent-driven sessions, reducing platform reliance on traditional keyword search infrastructure and affiliate traffic acquisition.
Saudi SAMR's digital commerce standards and the UAE's TDRA transaction frameworks are mandating tiered certification for payment processors and marketplace operators. These regulations are fragmenting technical architecture requirements across Gulf markets. Electronics and high-value goods categories face the steepest compliance burdens, driving platforms toward in-house payment gateway development rather than third-party reliance.
Social commerce unbundling is separating product discovery from transaction completion. Beauty and fashion discovery now concentrates on short-form video platforms, with checkout migrating to embedded storefronts rather than destination e-commerce sites. This behavioral shift is most pronounced among Gulf Cooperation Council urban consumers, where influencer attribution directly determines inventory procurement decisions for platform sellers.
Middle East and Africa E-Commerce Market Segmentation
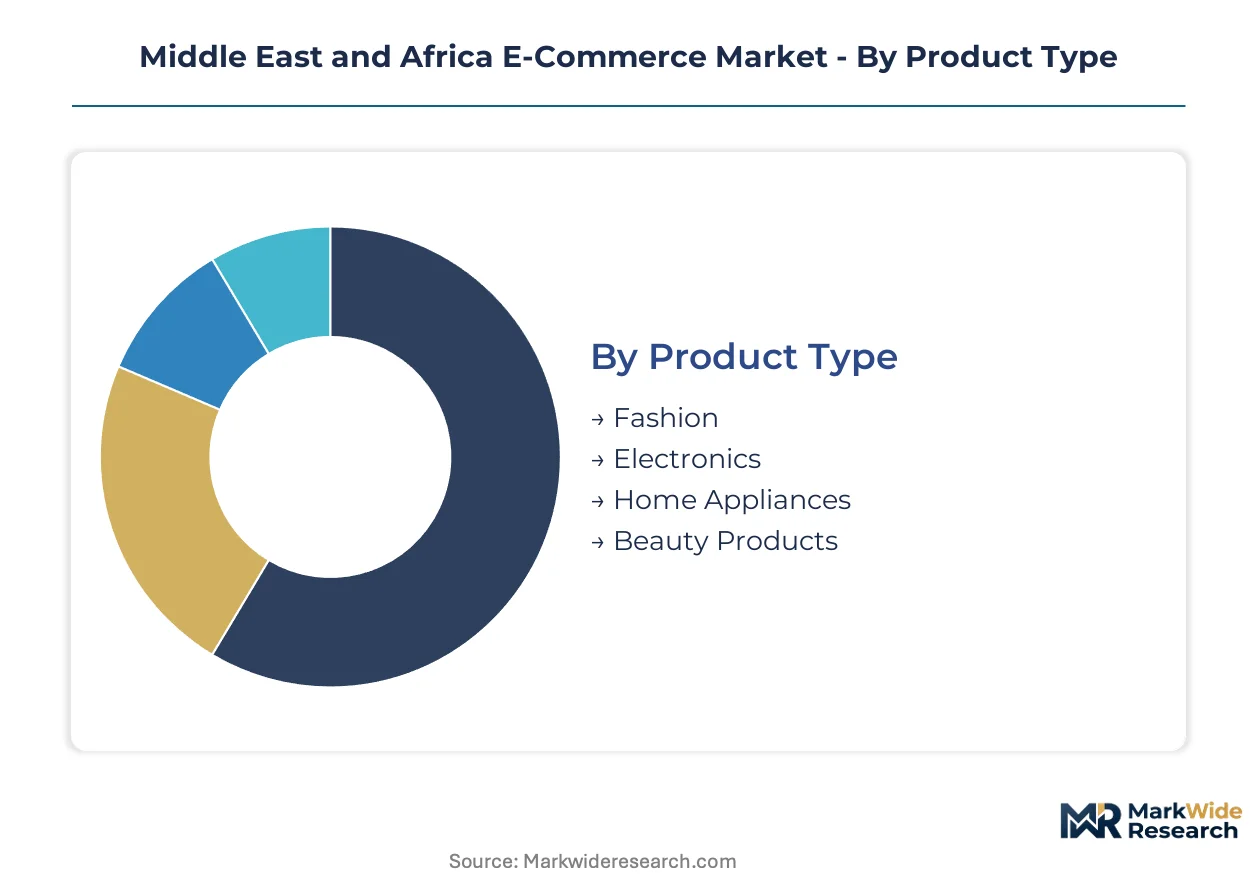
E-commerce platform architecture across the Middle East and Africa must accommodate radically divergent buyer behaviors, from Gulf urban millennials demanding instant fulfillment to African consumers navigating cash-based informal economies. Segmentation reveals where infrastructure investments concentrate and where regulatory compliance burdens multiply.
Product Type:
Buyer priorities shift between discretionary aspiration and functional necessity across income tiers and urban density gradients.
- Fashion:Apparel and accessories dominate transaction velocity in Dubai, Riyadh, and Lagos urban corridors, where influencer-driven discovery on short-form video platforms compresses the path from content engagement to purchase completion. Same-day fulfillment expectations are highest here, pressuring inventory localization.
- Electronics:Smartphones, laptops, and accessories generate the highest average order values but face steepest SAMR and TDRA certification requirements for cross-border payment processing and warranty fulfillment. Saudi Arabia and the UAE concentrate demand, with Nigerian cities emerging as secondary volume nodes.
- Home Appliances:Large-format goods require specialized last-mile handling and installation services, limiting platform participation to those with proprietary logistics or third-party partnerships.
- Beauty Products:Skincare and cosmetics climb fastest as Gulf millennials adopt K-beauty and halal-certified lines through social commerce channels.
Fashion leads on scale; beauty products lead on momentum.
Business Model:
Transaction architecture determines working capital intensity, customer acquisition cost structures, and regulatory exposure across the value chain.
- B2C:Direct-to-consumer platforms anchor the market, capturing urban millennial spend through mobile-optimized interfaces and embedded digital wallet checkout. Jumia and Amazon MENA compete on fulfillment speed, while Noon pressures margins with electronics pricing.
- B2B:Procurement digitization for Nigerian and Saudi manufacturing SMEs is gaining structural traction as offline wholesale channels fragment, though payment term negotiations and credit risk assessment remain workflow bottlenecks.
- C2C:Peer-to-peer marketplaces thrive in underbanked African cities where informal seller networks leverage mobile money for transaction settlement, but fraud exposure limits platform scalability.
- C2B:Reverse auctions and crowd-selling models remain nascent, concentrated in creative services and agricultural commodity aggregation.
B2C commands current volume; B2B offers the steepest expansion trajectory.
Payment Method:
Settlement infrastructure shapes geographic expansion feasibility and margin structure through fraud exposure and working capital efficiency.
- Digital Wallets:UAE TDRA certification and Saudi SAMR standards are accelerating platform-wallet partnerships, reducing abandonment rates in Gulf markets where smartphone penetration supports app-based payment adoption.
- Cash on Delivery:Retains dominant share in Nigerian and Egyptian markets, forcing platforms to absorb collection costs, delivery failure risk, and cash handling security overhead.
- Card Payments:Credit and debit transactions concentrate in South African and Gulf urban centers with established banking infrastructure, though cross-border processing fees compress margins.
- Bank Transfers:Direct account debits serve B2B procurement workflows and high-value consumer purchases, with settlement latency creating reconciliation complexity.
Digital wallets lead on momentum; cash on delivery retains scale dominance.
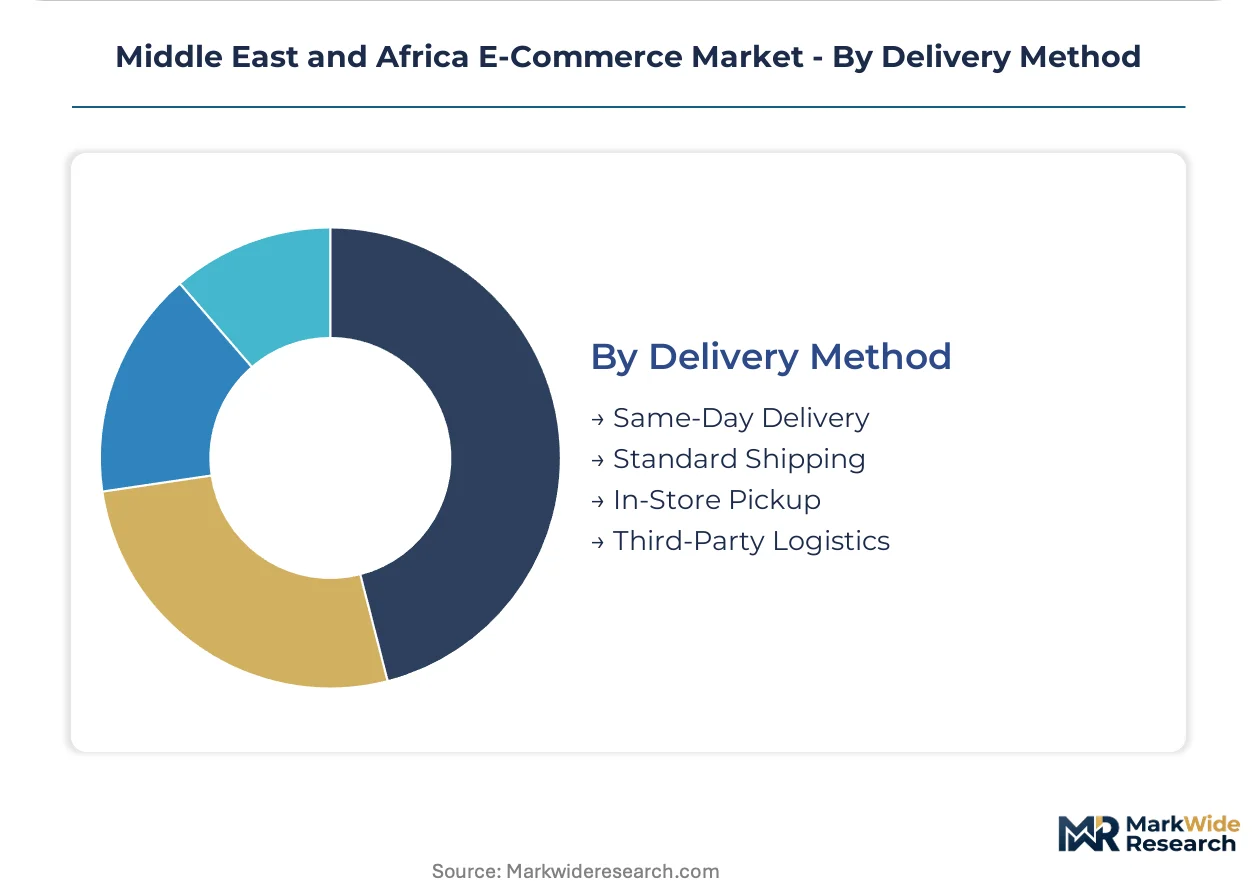
Delivery Method:
Fulfillment speed expectations diverge sharply between Gulf urban corridors and African secondary cities, determining logistics network architecture.
- Same-Day Delivery:Amazon MENA and Noon compete aggressively in Dubai and Riyadh zones, requiring hyperlocal warehousing and dense courier networks that exclude underpenetrated markets.
- Third-Party Logistics:Jumia's proprietary network sustains coverage in African cities with informal addressing systems, though fuel cost volatility and infrastructure gaps constrain margin structures.
- Standard Shipping:Cross-border parcel post and consolidated freight serve price-sensitive buyers in secondary markets, with customs clearance delays creating predictable friction.
- In-Store Pickup:Click-and-collect adoption remains limited to Gulf mall-based retail integrations, offering inventory pooling benefits but requiring physical footprint investments.
Same-day delivery leads on customer satisfaction; third-party logistics enables geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce infrastructure across the Middle East and Africa traces its commercial lineage to Dubai's early 2000s free zone digitization and South Africa's first online retail pilots, with contemporary platform architecture now diverging sharply between Gulf fulfillment corridors and African mobile-money corridors.
Saudi Arabia
Urban millennials in Riyadh and Jeddah drive electronics and fashion transaction velocity through mobile-first discovery. SAMR digital commerce standards mandate tiered certification for payment gateways and data localization protocols. The Riyadh logistics corridor anchors same-day fulfillment network buildouts as Amazon MENA and Noon compete on delivery speed.
United Arab Emirates
Dubai's hyperconnected consumer base generates the region's highest average order values across beauty and electronics categories. TDRA digital transaction standards regulate stored-value facilities and digital wallet partnerships. The Dubai South logistics zone concentrates automated warehousing investments serving Gulf Cooperation Council cross-border fulfillment.
Nigeria
Lagos and Abuja urban clusters sustain Africa's largest B2C transaction volume despite cash-on-delivery dominance. Central bank e-payment mandates accelerate mobile money integration and digital currency pilot programs. Jumia's proprietary last-mile network penetrates underaddressed secondary cities where informal commerce still prevails.
South Africa
Cape Town and Johannesburg retail corridors combine established banking infrastructure with mature third-party logistics ecosystems. FSCA consumer protection frameworks govern marketplace operator liability and refund protocols. Takealot anchors fulfillment architecture around automated distribution centers serving high-value electronics and appliance segments.
Egypt
Cairo's dense urban population sustains cash-on-delivery as the dominant settlement method, compressing platform working capital efficiency. Central bank payment system reforms gradually expand digital wallet availability beyond banked populations. The Greater Cairo corridor generates sufficient transaction density to justify localized warehousing despite infrastructure constraints.
Middle East and Africa E-Commerce Market Competitive Landscape
The competitive structure tilts toward platform-operators with captive logistics networks rather than pure marketplace models. Consolidation pressure concentrates among Gulf-based players with same-day fulfillment capabilities, while African markets sustain fragmentation due to last-mile infrastructure gaps. Three archetypes dominate: vertically integrated logistics-platform hybrids, pure marketplace aggregators dependent on third-party delivery, and social-commerce enablers leveraging influencer attribution. Capacity expansion in automated warehousing and strategic partnerships with fintech payment processors represent the primary competitive moves reshaping positioning.
Among Middle East and Africa-based operators, Noon, Jumia, and Amazon MENA exemplify the logistics-platform hybrid archetype. Noon occupies a position anchored in Gulf electronics pricing competition and localized warehousing buildout. Jumia represents African market penetration through proprietary last-mile coverage in cities with informal addressing systems. Amazon MENA sits within the premium fulfillment tier, leveraging Dubai and Riyadh same-day zones to compress delivery expectations.
| Leading Market Players |
|---|
| Noon |
| Jumia |
| Amazon MENA |
| Souq.com |
| Takealot |
| Namshi |
| Zando |
| AliExpress |
| Konga |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council urban millennials anchor pricing power for platforms serving electronics and fashion categories, compressing margin structures through same-day fulfillment expectations while elevating willingness-to-pay for premium service tiers. SAMR certification requirements and TDRA digital wallet standards fragment pricing models across Saudi Arabia and the UAE, forcing tiered service differentiation that separates certified payment corridors from cash-dependent markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates platform revenue architecture, with premium tiers capturing Gulf urban consumers demanding same-day delivery and certified payment gateways while economy tiers serve price-sensitive African markets. Price differentiation hinges on fulfillment speed certification and payment method risk exposure, with digital wallet checkout commanding service premiums over cash-on-delivery. Pricing pressure stems from Noon's aggressive electronics discounting in Dubai and Riyadh, compressing gross margins for inventory-heavy categories. Nigerian and Egyptian consumers exhibit highest price sensitivity, while UAE and Saudi urban millennials demonstrate lowest elasticity for convenience-embedded transactions.
Supply Chain Analysis
Air freight and last-mile courier costs concentrate platform infrastructure investments around Dubai, Riyadh, and Johannesburg logistics corridors, with fuel price volatility in African secondary cities amplifying working capital strain. Inventory sourcing draws from China, Turkey, and India for electronics and fashion categories, while halal-certified beauty lines increasingly feed from South Korea and domestic Gulf manufacturers. Single-source vulnerability concentrates in cross-border payment gateway certification, where SAMR and TDRA mandates create regulatory chokepoints. Distribution runs through proprietary logistics-platform hybrids in Gulf markets and third-party courier networks across African urban clusters with informal addressing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa e-commerce market operates as a regulatory compounder, where SAMR digital commerce standards and UAE TDRA certification frameworks continuously elevate platform infrastructure requirements while simultaneously expanding addressable market trust. Central bank digital currency pilots across Nigeria and Egypt promise to reshape payment method availability and reduce cash-handling friction over the projection horizon.
For Market Incumbents: Deploy captive logistics capacity as the primary defensive lever, deepening same-day fulfillment zones in Dubai and Riyadh while extending proprietary last-mile coverage to underpenetrated African secondary cities. Noon's electronics pricing aggression and Amazon MENA's fulfillment speed investments threaten margin structures for platform-dependent third-party logistics models. Certification investment in SAMR Tier 2 payment gateway standards creates switching costs that lock in high-value merchant relationships across Saudi manufacturing clusters. For New Entrants and Emerging Players: SAMR's data localization mandates in Saudi Arabia open a window for specialized cloud infrastructure providers and identity verification technology vendors to capture platform compliance spending. Nigerian SME B2B procurement digitization represents the most penetrable white-space target, with offline wholesale fragmentation creating workflow migration opportunities for industrial supply chain platforms. A go-to-market angle anchored in embedded finance partnerships with TDRA-certified digital wallets reduces payment abandonment rates in Gulf consumer segments. For Investors and Strategic Acquirers: Logistics-platform hybrids with proprietary last-mile networks are the most active acquirer category in this space, consolidating fragmented African courier markets and Gulf warehousing capacity. Long-term viability favors operators with backward integration into payment processing certification and automated fulfillment infrastructure rather than pure marketplace aggregators dependent on third-party delivery. The signal to watch is central bank digital currency pilot expansion beyond Nigeria into Egypt and Kenya, which would trigger payment method disruption and platform infrastructure reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Payment Gateway Certification | Tiered certification requirements in Saudi Arabia elevate consumer trust and cross-border transaction velocity. |
| Proprietary Last-Mile Network Expansion | Jumia's logistics infrastructure sustains coverage in African cities with informal addressing and fuel cost volatility. |
| Automated Warehousing Investment | Dubai South logistics zone concentration enables same-day fulfillment for Amazon MENA and Noon in Gulf corridors. |
| Digital Wallet Partnership Formation | TDRA certification clarity enables fintech-platform collaboration reducing payment abandonment in UAE markets. |
| Influencer Commerce Integration | Social commerce unbundling creates direct purchase pathways from short-form video to embedded checkout. |
Research Methodology
Multiple input streams — primary interviews with platform operations executives, logistics network managers, and regulatory compliance officers; secondary validation through SAMR filings, TDRA transaction standards documentation, and central bank digital currency pilot announcements; plus customs and mobile money transaction data — were reconciled to construct market estimates. Bottom-up merchant and transaction volume modeling was cross-checked against top-down GDP e-commerce penetration benchmarks across Saudi Arabia, UAE, Nigeria, South Africa, and Egypt.
Historical platform revenue trajectories were cross-referenced against panel input from payment processors and third-party logistics providers to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, business model, payment method, and delivery method dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for infrastructure investment cycles and certification timeline impacts, with mobile penetration curves and digital wallet adoption rates serving as key forecast inputs.
Revisions become necessary when central bank digital currency pilots achieve production deployment, SAMR or TDRA standards undergo tier recalibration, or fuel price volatility structurally alters last-mile economics in African markets. Forecasts reflect assumptions about regulatory stability and infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context and regional exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
E-Tailing Solutions Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
North America Automotive E-Commerce Market