
 Open Source ERP Market | 2026-2036
Open Source ERP Market Size, Share, and Industry Trends Forecast 2026-2036
Open Source ERP Market Outlook
Healthcare and education are recalibrating their software procurement priorities, shifting from legacy on-premise systems toward modular open source ERP stacks. Odoo leverages its app-store ecosystem to anchor European mid-market demand. ERPNext sustains strong penetration among Asian manufacturing SMEs through its low-code customization framework. iDempiere competes in complex, multi-entity deployments where Java-based extensibility dominates technical selection criteria.
Open source ERP denotes enterprise resource planning software distributed under licenses permitting source-code modification, redistribution, and community-driven development, typically built on modular architectures with REST API layers and relational database backends such as PostgreSQL or MariaDB. The primary commercial purpose is to eliminate per-seat licensing costs while permitting organizations to customize workflows for inventory, accounting, HR, and supply chain operations without vendor lock-in. Cloud-based solutions and SaaS solutions are capturing the fastest expansion as channel partners build managed-service wrappers around raw community editions, while on-premise solutions retain residual demand in regulated sectors where data residency requirements override cost considerations. Hybrid solutions concentrate margin pools where systems integrators orchestrate multi-tenant public cloud front-ends with single-tenant private database instances.
FDA 21 CFR Part 11 in the United States imposes electronic record integrity requirements that shape validation protocols for open source ERP deployments in pharmaceutical and medical device manufacturing. EMA's MDR and GDPR in Europe enforce audit trail granularity and cross-border data localization standards that filter which community editions qualify for regulated healthcare and financial services use. Stakeholders must monitor how ISO 27001 certification gaps in community-maintained modules create liability exposure that commercial support vendors are positioning to underwrite.
Market Dynamics
Mid-sized manufacturers across Germany, France, and the United States are abandoning perpetual-license ERP contracts in favor of API-first, cloud-native platforms that modularize core functions like inventory and HR across separate microservices.
Growth Catalysts
- GDPR and the EU AI Act:European data sovereignty mandates are disqualifying proprietary SaaS ERP vendors that cannot guarantee localized data residency, opening procurement windows for self-hosted open source alternatives.
- Industrie 4.0 manufacturing protocols:German automotive and machinery producers require MES-ERP integration through standardized OPC UA interfaces, which open source stacks with native Python and Java extensibility satisfy more readily than closed platforms.
- Low-code customization frameworks:Asian manufacturing SMEs deploy ERPNext and similar platforms to build proprietary workflow automations without vendor dependency or per-seat licensing accumulation.
Market Restraints
- ISO 27001 certification gaps:Community-maintained modules in healthcare and financial services verticals lack centralized security attestation, creating liability exposure that slows enterprise adoption.
- PostgreSQL and MariaDB talent scarcity:Organizations struggle to source database administrators capable of optimizing relational backends at scale, inflating implementation timelines and total cost of ownership.
- FDA 21 CFR Part 11 validation overhead:Pharmaceutical and medical device manufacturers face extended compliance timelines for electronic record integrity, compressing the addressable market for unvalidated community editions.
Strategic Opportunities
- Managed service wrappers around raw community editions:Systems integrators in France and Spain are building multi-tenant public cloud front-ends with single-tenant private database instances, capturing margin pools in hybrid deployments.
- EMA MDR audit trail requirements:European medical device regulation mandates granular transaction logging that open source ERPs with transparent codebases can demonstrate more readily than black-box proprietary systems.
- API-first architecture convergence with IoT sensor networks:Manufacturing plants in Bavaria and Baden-Württemberg are integrating shop-floor telemetry directly into ERP inventory modules through REST layers, bypassing traditional SCADA middleware.
Industry Challenges
- Multi-entity consolidation complexity:Organizations operating across German, Austrian, and Swiss legal entities struggle to harmonize chart-of-accounts structures and tax reporting workflows within single ERP instances.
- Python and JavaScript developer scarcity in industrial regions:Manufacturing hubs in the American Midwest and Northern England lack sufficient technical talent to customize and maintain open source codebases without external contractor dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Source ERP Market |
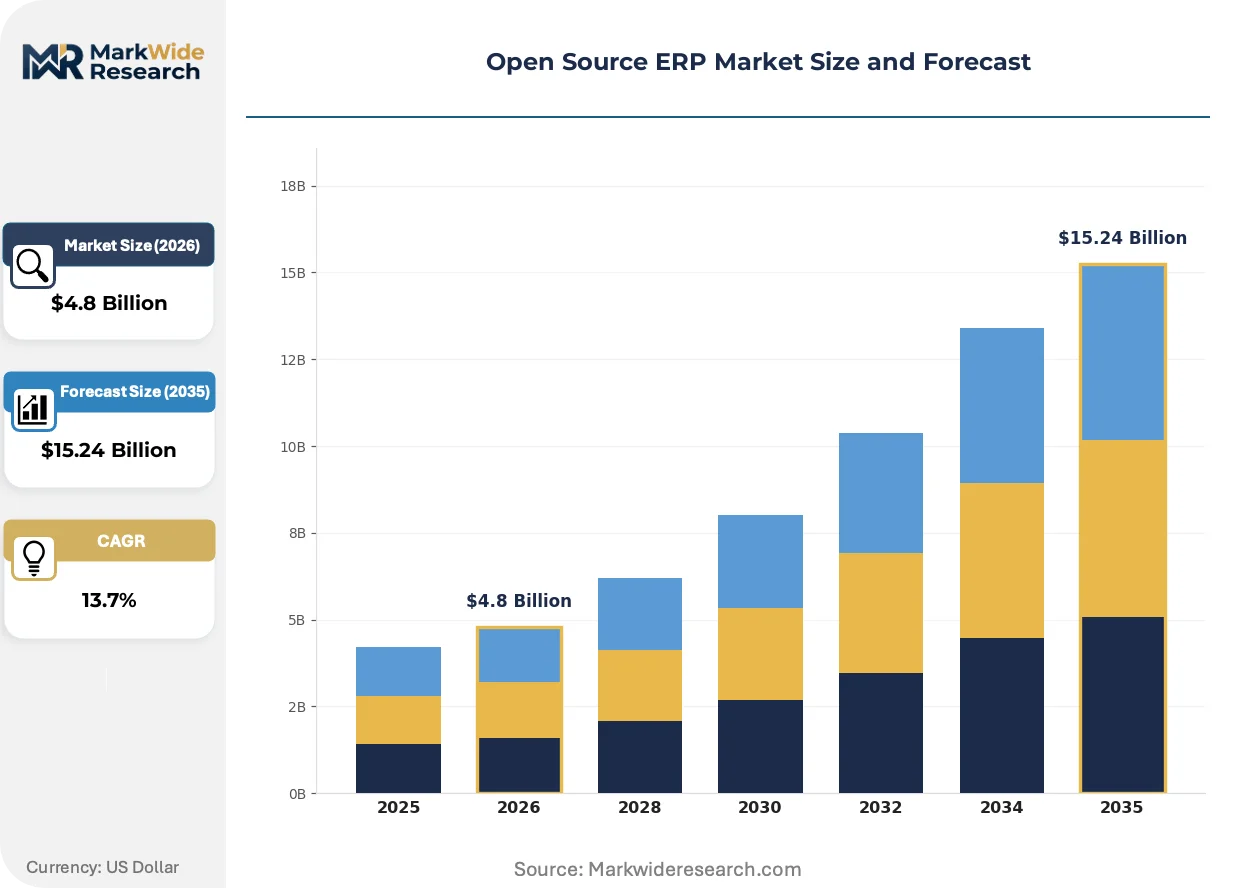
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, SaaS Solutions Deployment Model: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant End User: Small Enterprises, Medium Enterprises, Large Enterprises, Non-Profit Organizations Industry Vertical: Manufacturing, Retail, Healthcare, Education |
| Companies Covered | iDempiere, Onfinity ERP, Odoo, Acumatica, MixERP, ERPNext, Scipio ERP, Priority Software, Dolibarr ERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Source ERP Market Strategic Shifts
Containerized deployment patterns and headless API architectures are fragmenting how ERP functionality is consumed, unbundling monolithic suites into composable services that organizations assemble through internal platform teams rather than vendor roadmaps.
Headless ERP architectures with decoupled front-end layers are overtaking traditional all-in-one platforms. Automotive suppliers in Stuttgart and Wolfsburg adopt React-based custom interfaces that query Odoo or ERPNext backends through GraphQL endpoints. This pattern compresses user-interface development cycles from quarters to weeks while locking organizations into specific technical stacks.
REACH chemical substance tracking requirements and the EU Green Deal's digital product passport mandates are forcing ERP vendors to embed materials traceability modules. German chemical processors and Italian textile manufacturers must now track substance volumes across supply tiers. Open source platforms with transparent data models adapt faster to these evolving disclosure schemas than proprietary alternatives with fixed field structures.
Subscription-based commercial support contracts are displacing traditional perpetual-license maintenance models. Mid-market manufacturers in France and the Netherlands now procure ERP functionality through annual subscriptions that bundle hosting, security patching, and regulatory update management. This shift concentrates buyer power with systems integrators who orchestrate multi-vendor service stacks rather than single-vendor relationships.
Open Source ERP Market Segmentation
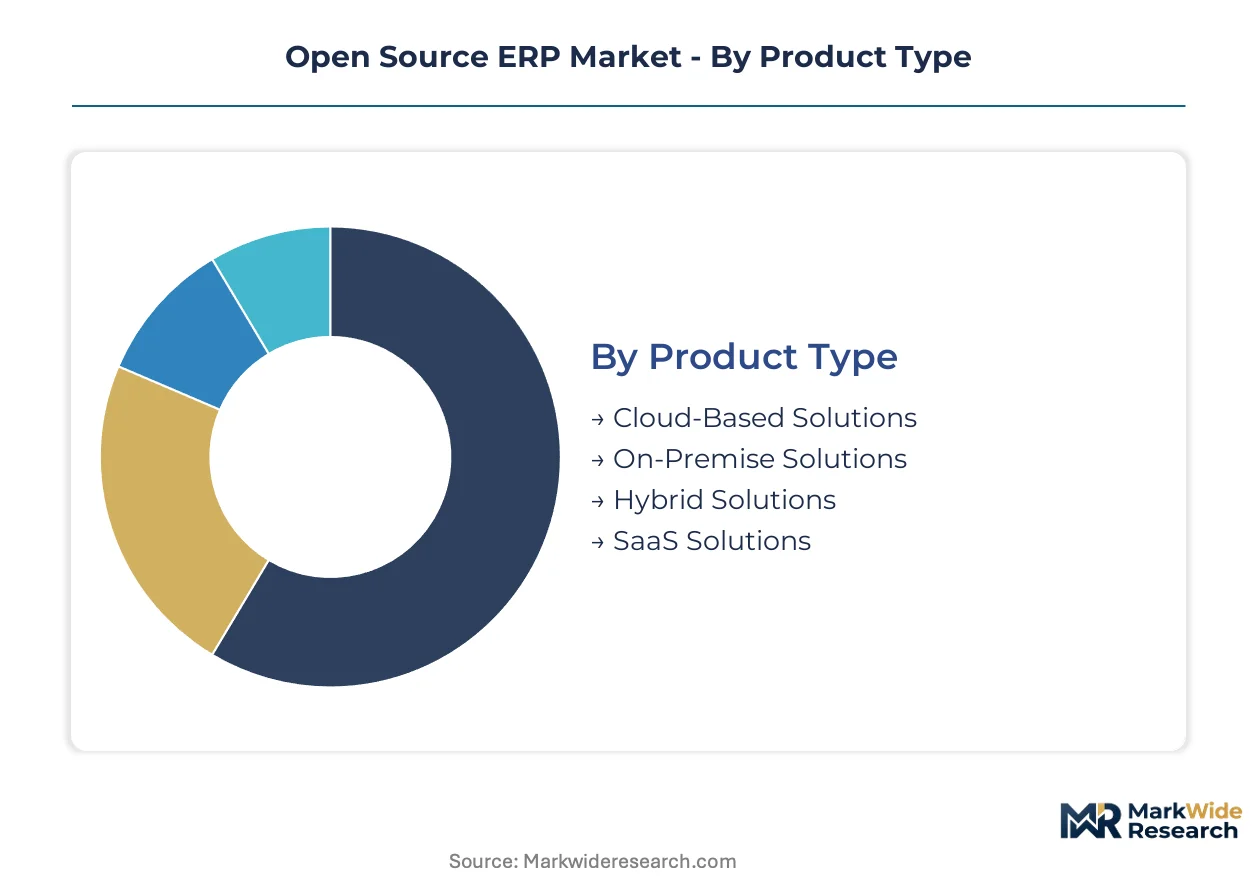
Open source ERP procurement patterns diverge sharply across deployment models and enterprise scale, with upgrade cycles from legacy on-premise systems to API-first architectures driving replacement demand. Segmentation reveals where systems integrators capture margin and where community editions face certification barriers.
Product Type:
Replacement cycles for legacy ERP installations are accelerating as organizations confront end-of-support deadlines for aging on-premise stacks.
- Cloud-Based Solutions:Architectures deploy through managed service providers with PostgreSQL or MariaDB backends, eliminating per-seat licensing. German automotive suppliers in Baden-Württemberg favor these for OPC UA integration with shop-floor systems.
- On-Premise Solutions:Self-hosted installations on bare metal or private virtualization layers persist where GDPR data residency requirements override cost considerations. French healthcare institutions maintain these for ANSM audit trail compliance.
- Hybrid Solutions:Multi-tenant public cloud front-ends route to single-tenant private database instances. Spanish systems integrators build these configurations for mid-market manufacturers seeking regulatory flexibility.
- SaaS Solutions:Subscription bundles combine hosting, security patching, and update management. Dutch procurement teams prefer these for predictable annual budgeting without capital expenditure spikes.
Cloud-Based Solutions sits at the top of the volume ranking, with Hybrid Solutions climbing the fastest.
Deployment Model:
Cost tier differentiation separates commodity public cloud offerings from premium single-tenant configurations with dedicated infrastructure.
- Public Cloud:Shared infrastructure pools reduce per-organization hosting overhead. Asian manufacturing SMEs deploy ERPNext on these tiers for low-code workflow customization without capital investment.
- Private Cloud:Dedicated virtualized environments isolate compute resources within third-party data centers. Italian textile manufacturers select these for REACH substance tracking compliance.
- Multi-Tenant:Single codebase instances serve multiple organizations with data segregation at the database layer. French channel partners dominate this segment for mid-market annual subscriptions.
- Single-Tenant:Isolated application and database instances per customer satisfy EMA MDR requirements for medical device manufacturers in Germany and Switzerland.
Public Cloud commands the largest installed base, while Single-Tenant configurations expand most quickly in regulated verticals.
End User:
Customer maturity determines whether organizations self-implement community editions or procure managed commercial support wrappers.
- Small Enterprises:Limited IT staffing drives preference for SaaS bundles with minimal customization. These organizations prioritize Odoo app-store ecosystems over bespoke development.
- Medium Enterprises:Sufficient technical capacity enables low-code framework deployment for proprietary workflow automation. German Industrie 4.0 initiatives concentrate demand here.
- Large Enterprises:Complex multi-entity consolidation requirements favor iDempiere Java-based extensibility for chart-of-accounts harmonization across German, Austrian, and Swiss legal entities.
- Non-Profit Organizations:Budget constraints and grant compliance needs align with transparent open source codebases for donor reporting and fund tracking.
Medium Enterprises generate the highest transaction volume, with Large Enterprises gaining share fastest as consolidation complexity drives platform migration.
Industry Vertical:
Application-specific regulatory burdens filter which open source editions qualify for deployment in audited environments.
- Manufacturing:MES-ERP integration through REST APIs and OPC UA interfaces dominates technical selection. Bavarian plants embed IoT sensor telemetry directly into inventory modules.
- Retail:Omnichannel order management and supplier portal requirements favor headless architectures with React front-ends querying Odoo backends.
- Healthcare:FDA 21 CFR Part 11 and EMA MDR impose electronic record integrity and audit trail granularity requirements that slow community edition adoption without commercial validation support.
- Education:Modular student information systems and grant management modules align with open source customization capabilities and elimination of per-seat licensing for fluctuating enrollment.
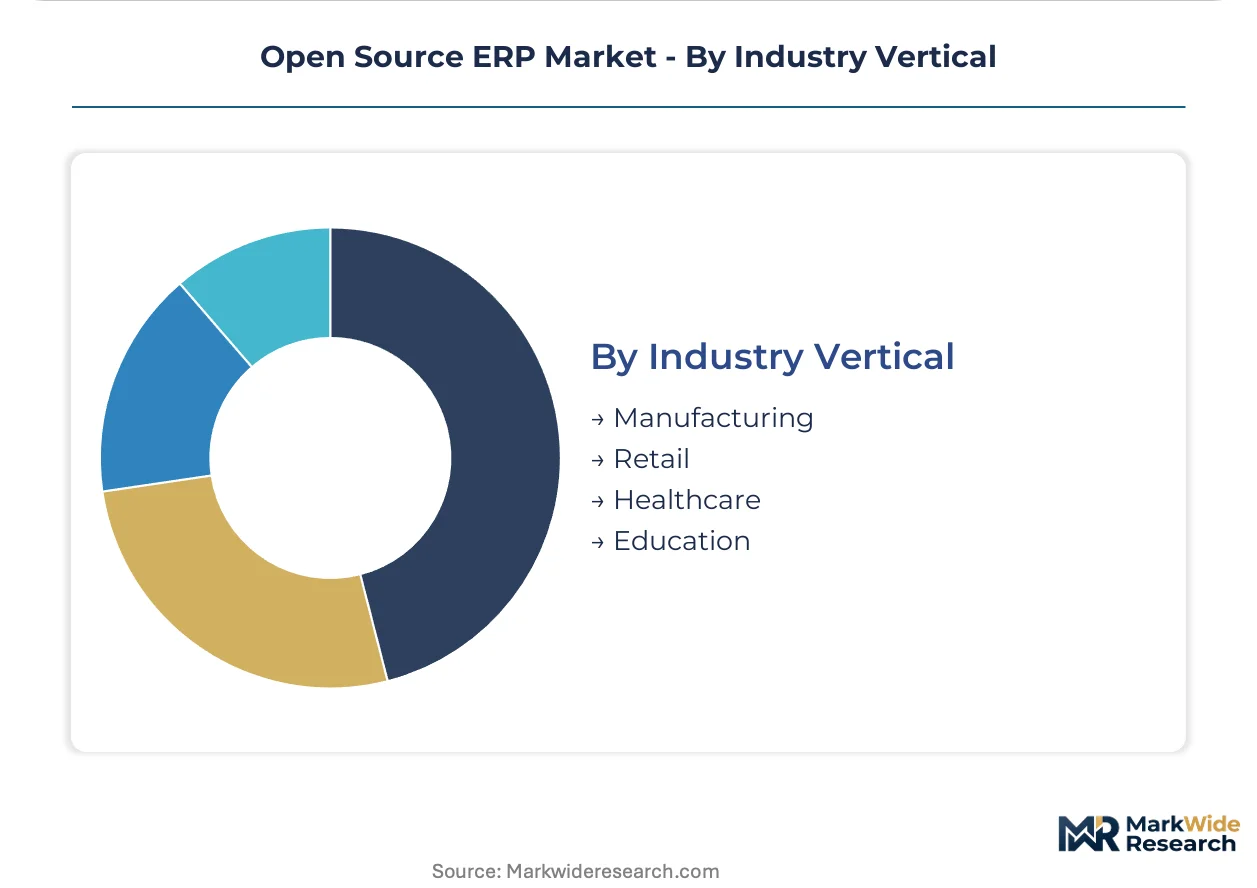
Manufacturing leads vertical deployment, with Healthcare expanding most slowly due to ISO 27001 certification gaps in community-maintained modules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity is shifting toward jurisdictions where data sovereignty compliance costs less than proprietary SaaS licensing premiums, with German automotive suppliers and Asian manufacturing SMEs driving divergent regional adoption patterns.
Germany
Industrie 4.0 manufacturing protocols and OPC UA integration requirements dominate procurement decisions. The EU AI Act and GDPR impose strict data localization mandates that disqualify non-EU cloud providers. Bavarian automotive plants in Munich and Ingolstadt embed IoT sensor telemetry directly into ERP inventory modules through REST API layers.
United States
FDA 21 CFR Part 11 validation requirements filter pharmaceutical and medical device manufacturer adoption toward commercially supported distributions. Midwest manufacturing hubs in Michigan and Ohio struggle with Python developer scarcity when customizing open source codebases. The EPA's electronic reporting standards for chemical facilities shape audit trail specifications in process industries.
France
ANSM audit trail compliance for healthcare institutions sustains on-premise deployment preferences over public cloud alternatives. Systems integrators in Paris and Lyon build multi-tenant public cloud front-ends with single-tenant private database instances for mid-market manufacturers. The CNIL's GDPR enforcement actions accelerate procurement of self-hosted alternatives to US-based SaaS ERP.
India
Low-code customization frameworks attract manufacturing SMEs in Gujarat and Maharashtra seeking workflow automation without vendor lock-in. The country's national pharmaceutical regulator drives serialization requirements that open source traceability modules address. Bengaluru-based systems integrators wrap managed services around ERPNext community editions for regional deployment.
Japan
METI's digital transformation incentives for small manufacturers accelerate cloud migration from legacy on-premise stacks. JIS standards for quality management systems shape module certification requirements in automotive supply chains. Osaka and Nagoya industrial clusters favor API-first architectures that integrate with existing MES investments.
Open Source ERP Market Competitive Environment
Strategic partnerships and managed service wrapper development dominate the current landscape as systems integrators capture margin pools between raw community editions and enterprise buyers. The vendor base clusters around three archetypes: full-suite platform providers with app-store ecosystems, modular specialists targeting vertical compliance requirements, and regional systems integrators building localization layers. M&A activity concentrates among European channel partners consolidating multi-country support capabilities, while technology licensing agreements proliferate between core platform maintainers and managed hosting providers.
Within the full-suite platform tier, Odoo and ERPNext occupy positions that exemplify divergent geographic anchoring strategies, with the former concentrating European mid-market demand through its app-store ecosystem and the latter sustaining Asian manufacturing SME penetration through low-code frameworks. iDempiere represents the Java-based extensibility archetype for complex multi-entity deployments where chart-of-accounts harmonization across legal entities drives technical selection.
| Leading Market Players |
|---|
| iDempiere |
| Onfinity ERP |
| Odoo |
| Acumatica |
| MixERP |
| ERPNext |
| Scipio ERP |
| Priority Software |
| Dolibarr ERP |
| Others |
Value Chain & Pricing Dynamics
PostgreSQL and JavaScript developer scarcity in Bavaria and Baden-Württemberg inflates implementation labor costs, widening the spread between self-hosted community editions and fully managed commercial subscriptions across European deployment tiers.
Pricing Analysis
Systems integrator margin layers dominate final customer pricing, with French and Spanish channel partners capturing 40-60 point spreads between raw ERPNext community editions and wrapped SaaS bundles. Price differentiation rests on ISO 27001 certification status and GDPR compliance attestation, with validated single-tenant configurations commanding premiums over unvalidated multi-tenant alternatives. Pricing pressure stems from Asian manufacturing SMEs bypassing European integrators to deploy ERPNext directly on Indian public cloud tiers. Small enterprises exhibit highest price sensitivity, while German automotive suppliers prioritize OPC UA integration capabilities over per-seat cost.
Supply Chain Analysis
Single-source vulnerability sits with Bengaluru-based systems integrators who control managed service wrapper development for ERPNext deployments across Gujarat and Maharashtra manufacturing clusters. Core platform development concentrates in Belgium, India, and Germany, with PostgreSQL and MariaDB relational backends drawing from global open source maintenance pools. Supply chain risk centers on regulatory restriction: EMA MDR audit trail requirements in Germany and Switzerland disqualify community editions lacking commercial validation support. Distribution runs through regional channel partners who localize compliance layers for ANSM, FDA, and GDPR frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as data sovereignty mandates in Europe and Asia permanently expand the addressable base for self-hosted alternatives to proprietary SaaS ERP.
For Market Incumbents: Hedge against margin compression in commodity public cloud tiers by deepening backward integration into certification services, acquiring ISO 27001 validation capabilities for healthcare verticals. Counter Python developer scarcity in Midwest US manufacturing hubs through partnerships with Indian systems integrators who maintain ERPNext customization talent pools. For New Entrants and Emerging Players: French healthcare institutions represent the most penetrable white-space target, with ANSM compliance requirements sustaining on-premise deployment preferences that US-based SaaS vendors cannot satisfy. Pursue white-label partnerships with Paris and Lyon systems integrators who already command mid-market manufacturer relationships. Position around GDPR data residency guarantees that disqualify non-EU cloud providers from public sector procurement. For Investors and Strategic Acquirers: European channel partners consolidating multi-country support capabilities are the most active acquirer in this space, with M&A activity concentrating among French and Spanish integrators building cross-border GDPR compliance layers. Target acquisition archetypes include regional systems integrators with existing ANSM or FDA validation relationships. Monitor EMA MDR enforcement actions as the inflection signal for accelerated commercial support contract adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Wrapper Development | Captures margin pools between raw community editions and enterprise buyers requiring GDPR compliance. |
| ISO 27001 Certification Investment | Opens procurement pathways in French healthcare and German medical device manufacturing verticals. |
| OPC UA Integration Partnership | Locks in Bavarian automotive suppliers embedding IoT sensor telemetry into inventory modules. |
| Multi-Tenant Public Cloud Front-End | Enables Spanish systems integrators to serve mid-market manufacturers with regulatory flexibility. |
| Low-Code Framework Localization | Addresses Python scarcity in Midwest US through Indian systems integrator talent partnerships. |
Study Parameters
Multiple input streams — primary interviews with CTOs and IT procurement officers, technical validation with platform engineers, and channel partner discussions — were reconciled against secondary sources including SEC filings from publicly traded systems integrators, EMA regulatory submission databases, and hyperscaler capex disclosures for European data center expansion. Bottom-up deployment model sizing was triangulated with top-down market aggregation across cloud, on-premise, hybrid, and SaaS solution categories.
Historical growth trajectories were cross-referenced against panel input from integration specialists to anchor projections across the modeling period. Segmentation dimensions included deployment model, organization scale, industry vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of replacement cycle acceleration and compliance-driven procurement windows. Forecast inputs incorporated GDPR enforcement action timelines and FDA 21 CFR Part 11 validation backlog estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementation rigor and PostgreSQL talent pipeline expansion in industrial regions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Middle East and Africa Enterprise Software Market