
 GCC Managed Service Market | 2026-2036
GCC Managed Service Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Managed Service Market Analysis
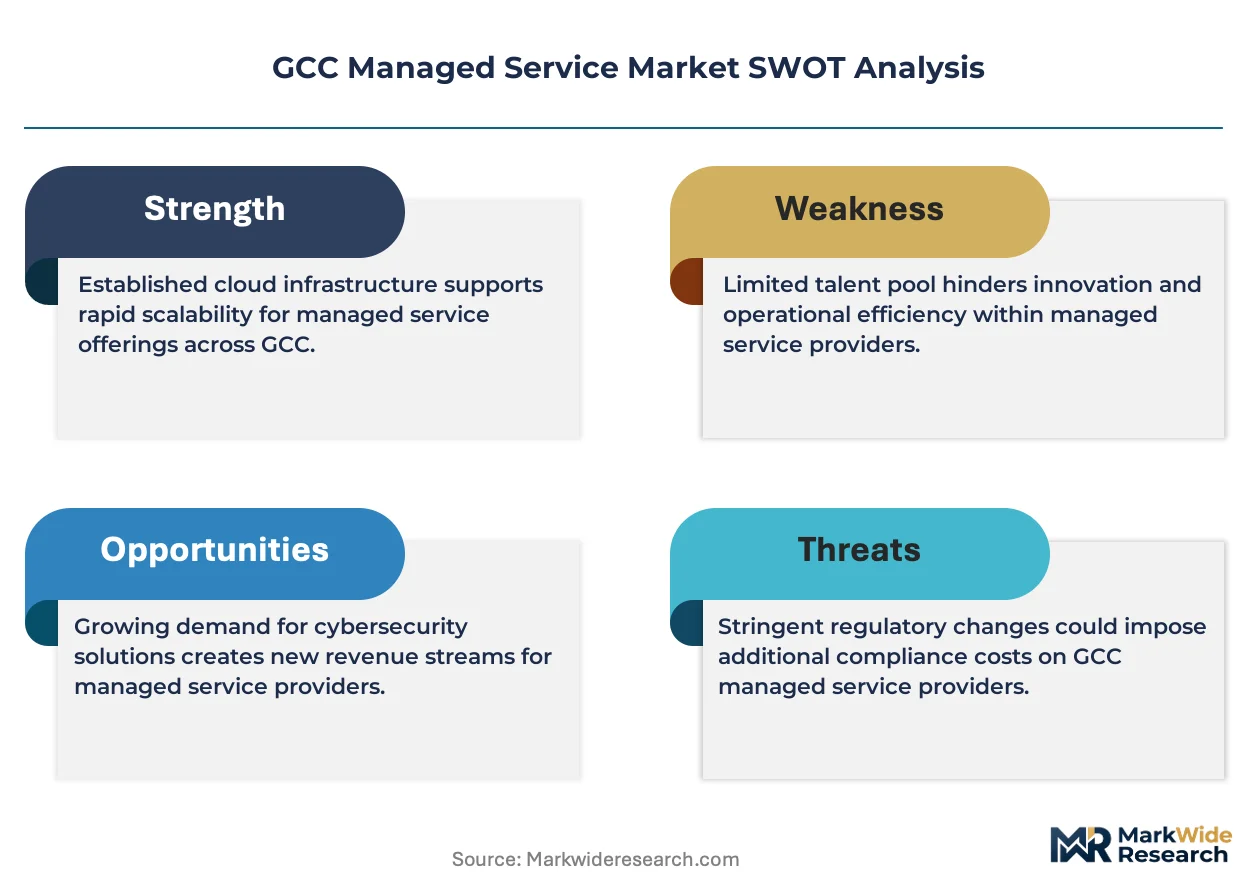
Cloud architecture expertise is rotating toward the top constraint for GCC enterprise expansion, with local talent pools unable to match deployment velocity. Saudi Telecom Company leverages its sovereign data center footprint to anchor government and finance contracts across the Kingdom. IBM Corporation competes through hybrid cloud management platforms that bridge legacy on-premises stacks with multi-cloud environments. Accenture differentiates via industry-vertical specialization, embedding compliance workflows into managed security offerings for regional banking clients.
GCC managed services encompass the ongoing delegation of IT infrastructure oversight, cybersecurity monitoring, cloud resource optimization, and network operations to third-party providers, typically governed by service-level agreements specifying uptime thresholds, incident response windows, and data residency protocols. Cloud Management services lead segment value as Saudi and Emirati enterprises migrate ERP and customer platforms to Microsoft Azure and AWS Riyadh regions. Security Services represent the fastest-expanding category, driven by NCA Saudi and UAE NESA mandates for continuous threat detection and zero-trust architecture implementation across critical infrastructure operators.
SAMA, UAE NESA, and Qatar's NCSA shape procurement standards by mandating in-country data processing, certified encryption protocols, and quarterly third-party security audits for financial and energy sector operators. Compliance complexity elevates managed service contracts from cost-cutting instruments to strategic risk-transfer mechanisms. Stakeholders must monitor evolving certification requirements and sovereign cloud localization rules to sustain contract renewals and avoid disqualification from public sector tenders.
Market Dynamics
AI-driven automation platforms are compressing contract renewal cycles across Saudi and Emirati enterprises, forcing incumbent providers to restructure pricing models around outcome metrics rather than headcount-based fees. Sovereign data localization mandates from SAMA and UAE NESA are rewriting procurement specifications, elevating in-country infrastructure ownership from preference to disqualification threshold.
Growth Catalysts
- SAMA Data Sovereignty Mandates:Saudi financial institutions must process customer data within Kingdom borders, driving demand for locally-hosted managed infrastructure and continuous compliance monitoring.
- Zero-Trust Architecture Deployment:Critical infrastructure operators across the UAE are retrofitting network perimeters with continuous verification protocols, expanding managed security service contracts.
- Riyadh Smart City Budgets:Municipal digitization programs are channeling IT outsourcing spend toward integrated network and security operations centers.
Market Restraints
- Specialized Cloud Talent Scarcity:Saudi Arabia and the UAE face acute shortages of certified Azure and AWS architects, inflating service delivery costs and extending deployment timelines.
- Sovereign Data Center Concentration:STC and Etisalat dominate certified facility supply in Riyadh and Dubai, limiting buyer negotiating leverage and creating single-source dependencies.
- Legacy ERP Integration Friction:On-premises Oracle and SAP systems in regional banks resist seamless cloud migration, forcing expensive middleware layers and extended parallel-run periods.
Strategic Opportunities
- Qatar Financial Sector Expansion:NCSA compliance deadlines for Doha-based banks and wealth managers remain underserviced by established Saudi-UAE provider networks.
- Kuwait Energy Sector Digitization:Oilfield IoT deployments and downstream automation projects lack mature managed service ecosystems, creating first-mover positioning for hybrid cloud specialists.
- Converged AI-Security Operations:Machine learning threat detection layered atop SOAR platforms enables predictive incident response, differentiating premium service tiers.
Industry Challenges
- Multi-Cloud Certification Burden:Engineers must maintain concurrent Azure, AWS, and GCP credentials to serve heterogeneous client environments, stretching training budgets and retention.
- Quarterly Audit Cycle Intensity:SAMA and NESA-mandated third-party security assessments require dedicated compliance teams, consuming operational bandwidth without direct revenue attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Managed Service Market |
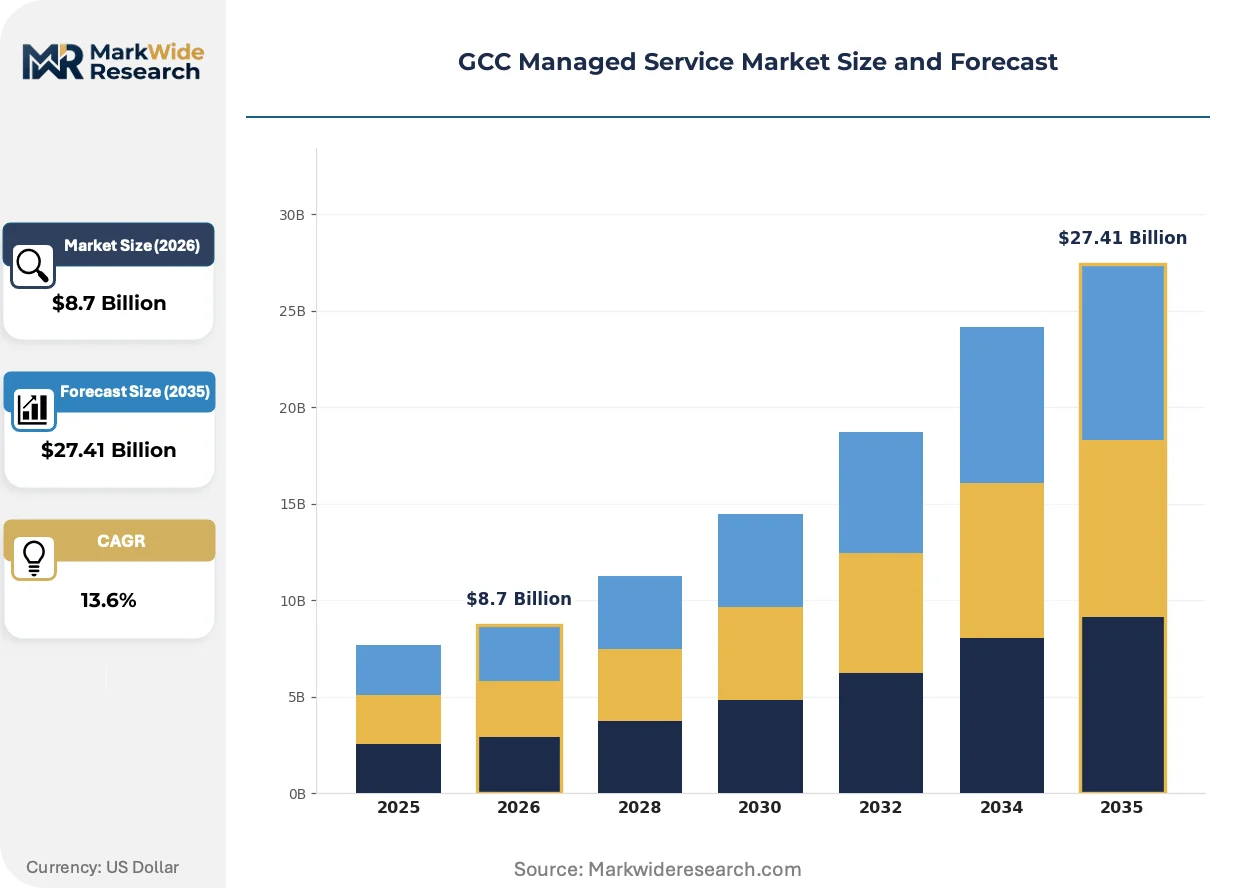
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Support, Cloud Management, Network Management, Security Services Client Type: SMBs, Enterprises, Startups, Government Agencies Deployment Model: On-premises, Cloud-based, Hybrid, Multi-Cloud Industry Vertical: Healthcare, Retail, Finance, Education |
| Companies Covered | Saudi Telecom Company, Etihad Etisalat Co. (Mobily), IBM Corporation, EITC Group (du), Wipro, Accenture, Cisco Systems, Inc., AGC Networks, Fortinet, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Managed Service Market Emerging Trajectories
Automation and policy convergence are restructuring how GCC enterprises consume infrastructure services. Providers are racing to embed sovereign compliance into platform architectures while buyers demand measurable security outcomes over hardware provisioning.
Agentic AI operations is supplanting tier-one human helpdesk functions across Saudi banking and UAE healthcare networks. Emirates NBD and King Faisal Specialist Hospital have deployed autonomous ticket resolution for password resets and access provisioning. This compression of routine support labor is redirecting provider investment toward higher-margin security analytics and cloud optimization engineering.
UAE NESA's Enhanced Cybersecurity Framework now mandates continuous threat monitoring and 72-hour incident reporting for all critical infrastructure operators. Financial services and energy sector contracts now embed quarterly penetration testing and zero-trust architecture roadmaps as standard deliverables. Providers without certified local security operations centers are exiting competitive tenders for federal and semi-government entities.
Consumption-based pricing models are displacing fixed-fee managed service agreements in Dubai's enterprise segment. CIOs at Emirates Group and DP World now negotiate cloud management contracts tied to actual compute utilization and detected threat volume. This shift transfers infrastructure risk to providers while compressing margins for those lacking granular cost-to-serve visibility.
GCC Managed Service Market Segmentation
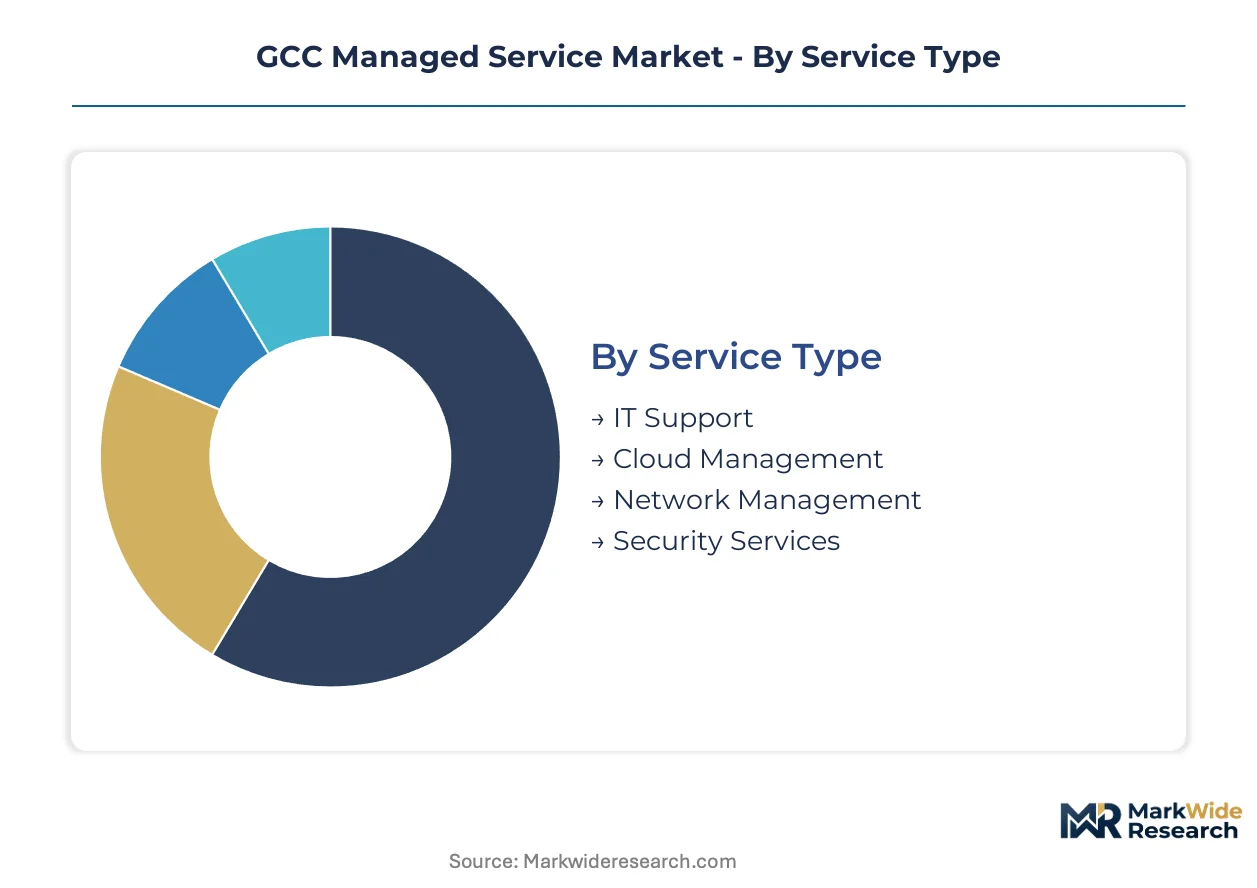
Service differentiation in the GCC managed service market follows regulatory pressure and cloud migration velocity rather than traditional IT support hierarchies. Procurement teams now weight sovereign data residency and AI-augmented response capabilities above historical uptime metrics when segmenting vendor capabilities.
Service Type:
Cloud Management and Security Services face the most intense substitution pressure as AI-driven automation platforms displace legacy human-staffed operations across Saudi and Emirati enterprises.
- Cloud Management:Orchestration of multi-tenant environments across Microsoft Azure and AWS Riyadh regions with automated cost optimization and compliance tagging. Saudi financial institutions migrating ERP systems to sovereign cloud zones drive concentrated demand in Riyadh and Jeddah as SAMA data localization deadlines approach.
- Security Services:Continuous threat detection, zero-trust architecture implementation, and quarterly penetration testing mandated by UAE NESA and NCA Saudi frameworks. Critical infrastructure operators in Dubai's energy corridor and Riyadh's financial district are retrofitting network perimeters with machine-learning-driven SOAR platforms.
- IT Support:Tiered helpdesk functions including password resets, access provisioning, and endpoint troubleshooting. Agentic AI systems at Emirates NBD and King Faisal Specialist Hospital now autonomously resolve routine tickets.
- Network Management:SD-WAN deployment, bandwidth optimization, and latency monitoring for distributed branch operations. Retail chains across the UAE and Kuwait prioritize this segment for POS system reliability.
Cloud Management anchors the volume base while Security Services gains share at the steepest rate.
Client Type:
Margin structures diverge sharply across client tiers, with government contracts commanding premium pricing for sovereign compliance certification while SMBs squeeze providers on standardized cloud management bundles.
- Enterprises:Multi-year contracts exceeding five million dollars annually with bespoke SLA architectures and dedicated account teams. Saudi Aramco and ADNOC subsidiaries in the energy sector negotiate outcome-based pricing tied to threat detection accuracy.
- Government Agencies:Federal and municipal entities requiring in-country data processing, certified encryption protocols, and quarterly third-party audits. Riyadh Smart City budgets channel spend toward integrated network and security operations centers.
- SMBs:Standardized service packages with limited customization and shared security operations center resources. Dubai's SME sector favors consumption-based pricing models over fixed-fee arrangements.
- Startups:Elastic cloud management with pay-as-you-scale terms and minimal compliance overhead. Fintech ventures in Bahrain and the UAE prioritize rapid provisioning over sovereign certification.
Enterprises dominate contract value while Government Agencies expand most quickly as federal digitization programs accelerate.
Deployment Model:
Application complexity determines deployment architecture selection, with hybrid configurations proliferating where legacy ERP systems resist full cloud migration.
- Hybrid:Bridged environments connecting on-premises Oracle and SAP systems with public cloud workloads via dedicated interconnects. Regional banks face extended parallel-run periods due to middleware integration friction.
- Cloud-based:Fully outsourced infrastructure on Microsoft Azure, AWS, or GCP with managed Kubernetes and serverless functions. Saudi healthcare networks favor this model for patient data platforms requiring elastic scaling.
- Multi-Cloud:Distributed workloads across two or more hyperscale providers to mitigate vendor lock-in and optimize regional latency. Advanced enterprises in the UAE deploy this architecture for resilience against single-provider outages.
- On-premises:Legacy managed infrastructure in client-owned data centers with remote monitoring and break-fix support. Declining share concentrated in classified government and defense applications.
Hybrid deployments anchor the installed base while Multi-Cloud configurations climb the fastest as risk diversification priorities intensify.
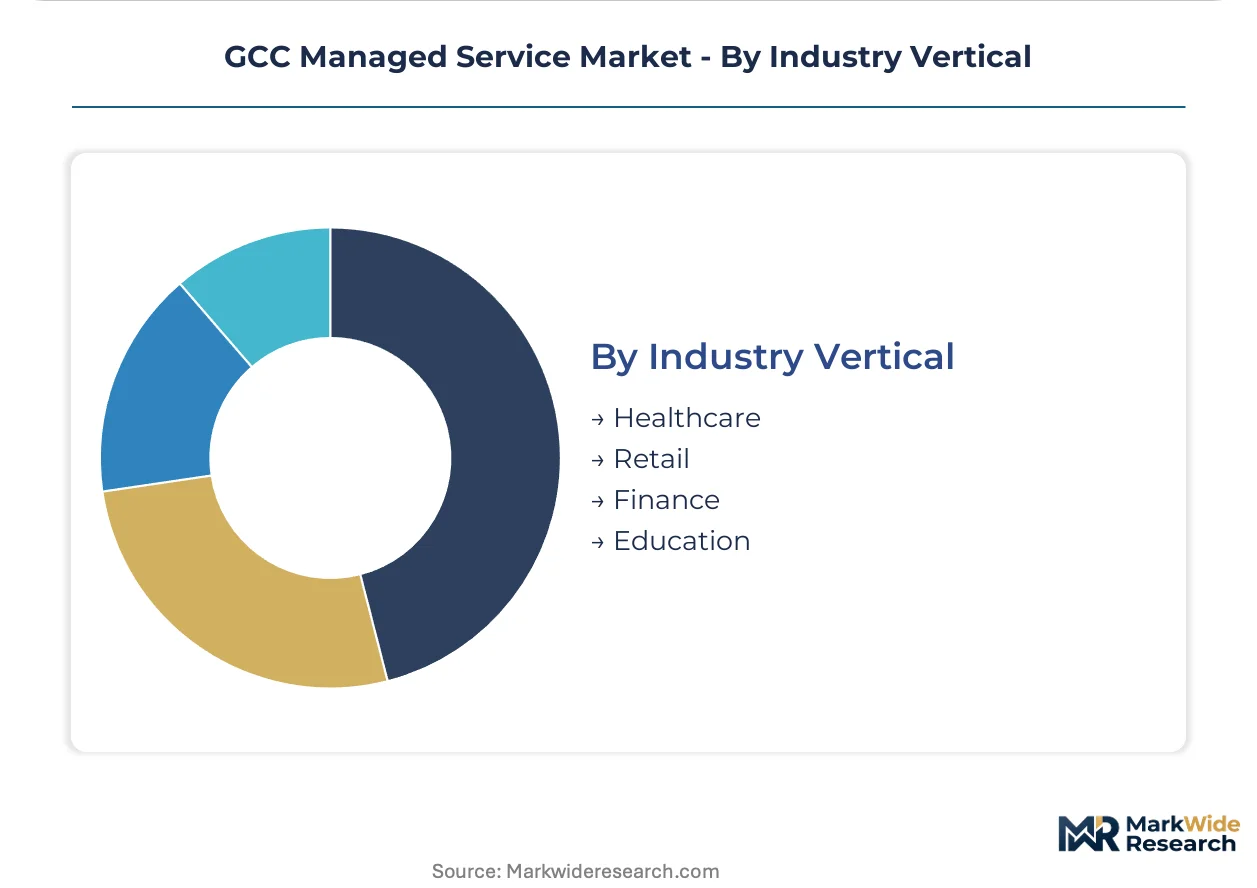
Industry Vertical:
Customer concentration varies by compliance burden, with Finance and Healthcare showing the tightest vendor relationships due to specialized regulatory knowledge requirements.
- Finance:Banking, insurance, and wealth management operations governed by SAMA, UAE Central Bank, and Qatar Central Bank mandates. Continuous compliance monitoring and zero-trust roadmaps are embedded in standard contracts.
- Healthcare:Hospital networks, diagnostic chains, and telemedicine platforms requiring HIPAA-aligned data protection and 24/7 critical system availability. King Faisal Specialist Hospital exemplifies AI-augmented managed service adoption.
- Retail:Omnichannel commerce infrastructure with seasonal elasticity demands and POS security requirements. Mall operators in Dubai and Riyadh prioritize network uptime during peak trading periods.
- Education:University and K-12 learning management systems with hybrid classroom technology support. Saudi Vision 2030 educational reforms are expanding this segment's addressable market.
Finance commands the deepest vendor relationships while Healthcare demonstrates the steepest expansion trajectory as hospital digitization accelerates across the Kingdom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes managed services through sovereign data center mandates while the UAE emphasizes multi-cloud resilience, creating divergent procurement patterns across the Gulf.
Saudi Arabia
SAMA data sovereignty rules require financial institutions to host customer data within Kingdom borders. The National Cybersecurity Authority mandates continuous threat monitoring for critical infrastructure operators. Riyadh concentrates demand as Saudi Telecom Company anchors government and banking contracts through its certified sovereign facilities.
United Arab Emirates
Dubai enterprises prioritize consumption-based pricing tied to actual compute utilization and detected threat volumes. UAE NESA's Enhanced Cybersecurity Framework mandates 72-hour incident reporting for all critical infrastructure operators. Abu Dhabi hosts specialized security operations centers serving federal and semi-government entities.
Qatar
Doha-based banks and wealth managers face NCSA compliance deadlines that remain underserviced by established Saudi-UAE provider networks. The Qatar Financial Centre regulatory environment shapes procurement specifications for wealth management technology. Lusail's smart city infrastructure channels IT outsourcing budgets toward integrated network operations.
Kuwait
Oilfield IoT deployments and downstream automation projects lack mature managed service ecosystems. The country's energy sector digitization programs create first-mover positioning for hybrid cloud specialists. Kuwait City anchors demand as state oil companies retrofit legacy infrastructure with remote monitoring capabilities.
Bahrain
Fintech ventures prioritize rapid cloud provisioning over sovereign certification requirements. The Central Bank of Bahrain's regulatory sandbox attracts startup financial technology firms with elastic infrastructure needs. Manama's financial district concentrates demand for pay-as-you-scale managed service arrangements.
GCC Managed Service Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with telecommunications incumbents leveraging sovereign data center ownership against global technology consultancies. Saudi Telecom Company and Etihad Etisalat Co. anchor the infrastructure-heavy segment through certified facility portfolios. IBM Corporation and Accenture occupy the advisory-integration tier with hybrid cloud management platforms. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and vertical specialization around financial services compliance workflows.
Within the telecommunications infrastructure tier, Saudi Telecom Company and Etihad Etisalat Co. exemplify sovereign facility ownership as a competitive anchor. IBM Corporation occupies a position bridging legacy on-premises stacks with multi-cloud orchestration capabilities. Accenture represents the industry-vertical specialization archetype, embedding compliance workflows into managed security offerings for regional banking clients.
| Leading Market Players |
|---|
| Saudi Telecom Company |
| Etihad Etisalat Co. (Mobily) |
| IBM Corporation |
| EITC Group (du) |
| Wipro |
| Accenture |
| Cisco Systems, Inc. |
| AGC Networks |
| Fortinet, Inc. |
| Others |
Supply Flow & Price Mechanics
Certified sovereign data center capacity utilization rates above eighty percent in Riyadh and Dubai anchor price floors across the GCC managed service market. Scale economies at STC and Etisalat facilities create supply concentration that elevates entry barriers for smaller providers while compressing margins for mid-tier competitors lacking comparable infrastructure ownership.
Pricing Analysis
Long-term managed service contracts spanning three to five years dominate enterprise procurement in Saudi Arabia and the UAE, though consumption-based arrangements gain traction in Dubai's mid-market segment. Price differentiation hinges on SAMA compliance certification tier and dedicated security operations center availability, with sovereign-certified providers commanding thirty to fifty percent premiums over uncertified rivals. Pricing pressure stems from AI-driven automation platforms displacing headcount-based fee structures, forcing incumbent providers toward outcome-linked arrangements. SMB buyers in Bahrain and Kuwait exhibit acute price sensitivity, while Saudi government agencies prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Saudi Arabia and the UAE anchor certified data center supply across the GCC, with Qatar and Bahrain dependent on cross-border infrastructure partnerships for sovereign-compliant hosting. Raw material inputs center on specialized server hardware from Taiwan and South Korea, plus encryption modules meeting NCA Saudi and UAE NESA specifications. Single-source vulnerability concentrates in Etisalat's Dubai facility cluster and STC's Riyadh campus, where certification bottlenecks create months-long provisioning delays. Distribution runs through direct enterprise sales teams for large contracts and hyperscale cloud marketplaces for standardized SMB packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Azure and AWS solution architect scarcity across the Kingdom and Emirates constrains service delivery velocity, elevating talent acquisition and retention to strategic priority status for all market participants.
For Market Incumbents: Fortify sovereign data center ownership advantages through capacity expansion in Jeddah and Abu Dhabi before NCA Saudi and UAE NESA tighten certification requirements. Incumbent providers must accelerate AI-augmented security platform deployment to defend against pure-play automation vendors eroding tier-one support margins. Vertical integration into specialized compliance consulting creates stickier client relationships and reduces churn risk in government segments. For New Entrants and Emerging Players: Anchor in Qatar's underserviced financial sector where NCSA compliance deadlines outpace established Saudi-UAE provider network expansion. New entrants should target Kuwait's energy sector digitization programs, where oilfield IoT deployments lack mature managed service ecosystems. A compliance-first go-to-market positioning—embedding quarterly audit preparation and zero-trust roadmap development—differentiates against commodity cloud management offerings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid cloud specialists with proven sovereign facility integration capabilities over pure advisory consultancies. Long-term viability across the five-to-ten year horizon rests on AI-security convergence expertise and hyperscale partnership depth. Acquisition targets should demonstrate certified local security operations centers and active SAMA or UAE NESA audit support contracts. The signal to watch is regulatory acceleration around data localization mandates in secondary GCC markets.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Certification | STC's Riyadh campus expansion locks in SAMA-mandated financial sector contracts against regional competitors. |
| AI-Security Platform Integration | Machine learning threat detection layered atop SOAR platforms enables predictive incident response differentiation. |
| Hyperscale Cloud Partnership | AWS Riyadh region and Microsoft Azure UAE North access determines enterprise migration velocity and contract capture. |
| Vertical Compliance Specialization | Embedding NCA Saudi and UAE NESA workflows into managed security offerings creates banking sector switching costs. |
| Geographic Expansion into Qatar | NCSA compliance deadlines for Doha-based wealth managers remain underserved by established provider networks. |
Methodological Framework
The analysis maps cloud management, security services, IT support, and network operations segments, each validated through chief technology officers, IT procurement directors, managed service provider account executives, and regulatory compliance officers across Saudi Arabia, the UAE, Qatar, and Kuwait. Primary fieldwork combined structured interviews with secondary validation against SAMA circulars, UAE NESA framework documents, hyperscaler regional capex disclosures, and enterprise RFP databases. Bottom-up contract value aggregation and top-down market sizing triangulated segment estimates.
Consistency checks validated volume and value outputs against hyperscaler regional revenue disclosures and certified data center capacity announcements across the projection horizon. The analytical framework modeled service type, client tier, deployment architecture, and industry vertical dimensions, with CAGRs derived from segment-level growth driver intensity scoring. Forecast inputs incorporated sovereign cloud localization rule evolution and AI automation adoption curves specific to GCC banking and energy sectors.
Decision-makers should treat outputs as directional under assumptions of continued SAMA and UAE NESA enforcement intensity; material regulatory relaxation or geopolitical disruption would warrant model refresh. Forecasts reflect base-case assumptions around talent pipeline expansion and hyperscale regional capacity buildout schedules. Recalibration cycles align with material shifts in data sovereignty mandate scope or AI-security platform substitution velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Africa Managed Services Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Proactive Services Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Telecom Enterprise Services Market