
 Field Service Management Market | 2026-2036
Field Service Management Market Size, Share, and Industry Trends Forecast 2026-2036
Field Service Management Market Intelligence
Enterprise buyer concentration in telecommunications is consolidating around integrated platform providers with proven scale. ServiceMax leverages its asset-centric architecture to anchor long-term contracts with utility and industrial clients. Salesforce Field Service competes through native CRM connectivity that unifies customer records with dispatch operations. Oracle Field Service sustains its position through deep ERP integration and manufacturing-sector specialization.
Field service management encompasses software systems that coordinate workforce dispatch, work order lifecycle tracking, inventory synchronization, and customer communication through centralized platforms, typically requiring real-time GPS telemetry, offline mobile resilience, and API interoperability with enterprise resource planning systems. Cloud-based deployment leads adoption as organizations retire legacy on-premises installations, while mobile-native architectures represent the fastest-expanding configuration due to field technician demand for offline-capable applications. Work order management and scheduling solutions capture the largest margin pools because they sit at the core of every operational workflow and command premium integration fees.
Regulatory frameworks including HIPAA in US healthcare field operations, GDPR across European customer data handling, and FCC equipment authorization for connected fleet hardware shape product requirements and market access conditions. The US national telecommunications regulator enforces workforce safety standards that filter into platform feature roadmaps. Stakeholders must evaluate whether their technology stack satisfies emerging AI transparency obligations and cross-border data residency rules before committing to multi-year deployment contracts.
Market Dynamics
Telecommunications carriers are consolidating vendor relationships around cloud-native platforms that unify work order management with real-time asset tracking, compressing procurement cycles from multi-year RFPs to single-platform commitments.
Growth Catalysts
- GDPR-mandated data residency:European utilities must store customer and operational data within regional boundaries, accelerating demand for EU-hosted cloud deployments with localized encryption and audit trails.
- 5G network densification:Tower maintenance and small-cell installation workloads are surging across Germany and India, requiring dispatch platforms that coordinate thousands of daily technician movements.
- Mobile-native architecture:Field technicians now refuse applications without offline functionality, forcing platform providers to engineer SQLite-backed mobile databases with automatic synchronization upon connectivity restoration.
Market Restraints
- Input cost volatility in semiconductor components:GPS modules and cellular modems embedded in fleet tracking hardware face price instability from concentrated Taiwanese foundry capacity.
- Supply concentration in hyperscale cloud infrastructure:Three providers dominate sovereign cloud hosting for European FSM deployments, creating single-point-of-failure risk for compliance-critical customers.
- Technical limitation in legacy ERP interoperability:Decades-old SAP and Oracle ERP installations in industrial manufacturing lack modern API layers, requiring expensive middleware development for FSM integration.
Strategic Opportunities
- Underpenetrated Indian state-level utilities:Maharashtra and Gujarat distribution companies are modernizing grid infrastructure, creating first-mover advantage for FSM providers with Hindi-language mobile interfaces and local implementation partners.
- Regulatory tailwind from FCC workforce safety mandates:US telecommunications carriers must now document technician location and safety compliance in real-time, mandating platform upgrades that embed OSHA-aligned incident reporting workflows.
- Technology convergence of AI dispatch optimization with digital twin asset modeling:Predictive maintenance algorithms that anticipate equipment failure before dispatch are creating premium pricing tiers for integrated platform bundles.
Industry Challenges
- Skill scarcity in API architecture engineering:Platform providers struggle to hire developers capable of building resilient bidirectional synchronization between field mobile applications and enterprise ERP systems.
- Certification timeline compression for HIPAA-aligned healthcare deployments:US home health agencies require FSM platforms with documented Business Associate Agreements and encryption protocols, extending sales cycles by six to nine months.
- Integration complexity with proprietary fleet telematics:Large logistics operators operate mixed vehicle fleets with incompatible OEM data protocols, forcing custom adapter development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Service Management Market |
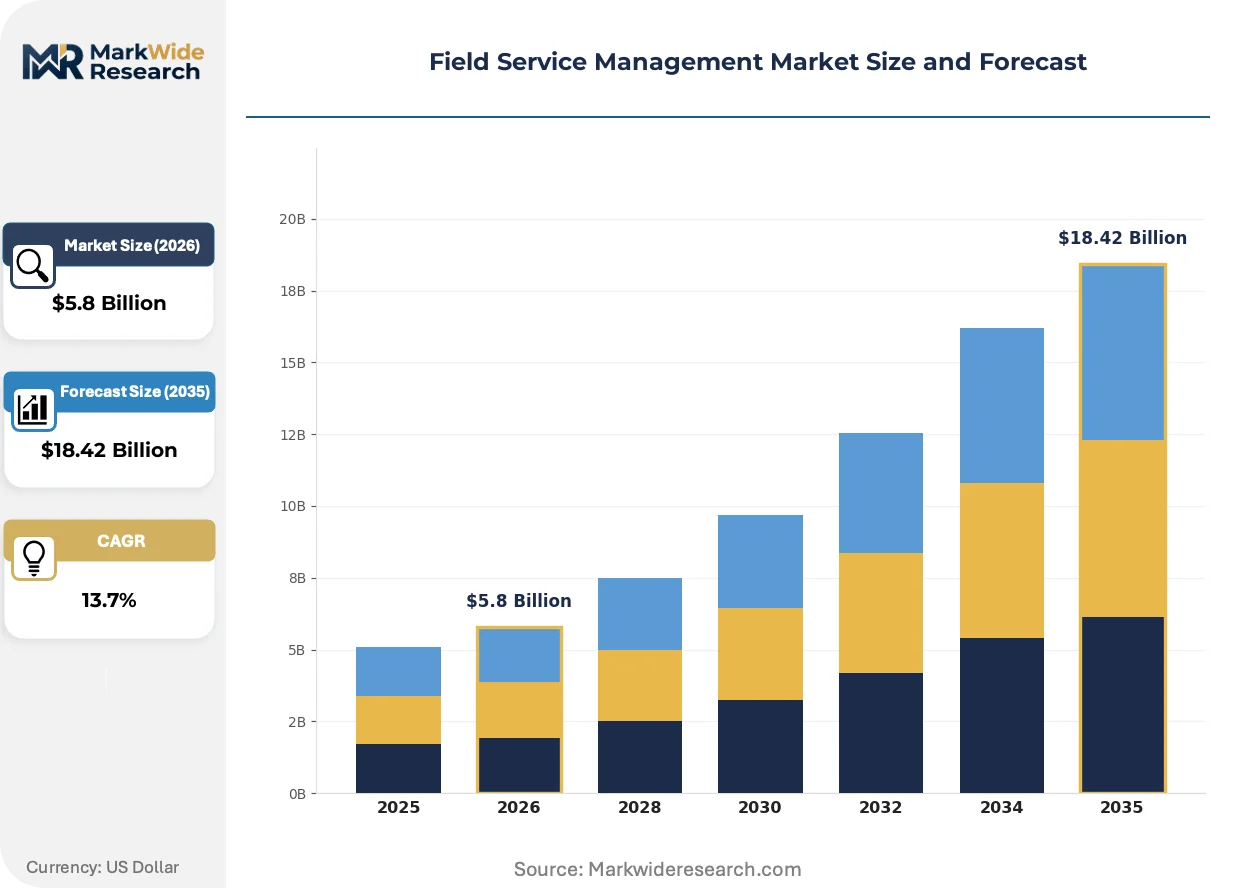
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Telecommunications, Healthcare, Manufacturing, Energy Solution: Work Order Management, Scheduling, Inventory Management, Asset Tracking Service Type: Installation, Maintenance, Repair, Support |
| Companies Covered | Microsoft Dynamics 365 Field Service, ServiceMax, ServiceTitan, ServiceNow Field Service Management, Jobber, Salesforce Field Service, Oracle Field Service, Zuper, IFS Field Service Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Service Management Market Strategic Shifts & Innovations
Artificial intelligence is rewriting dispatch logic from rule-based scheduling to predictive optimization, while regulatory pressure on data sovereignty and technician safety is hardening platform requirements faster than legacy architectures can adapt.
Edge computing infrastructure is modularizing field service architectures by pushing processing from centralized clouds to regional nodes and ultimately to technician handheld devices. German automotive service networks are deploying TensorFlow Lite models directly on ruggedized tablets to predict parts failure without cloud round-trips. This distributed intelligence is modularizing what was once monolithic platform software into composable microservices that customers license selectively.
EU AI Act transparency obligations are forcing FSM vendors to document algorithmic decision-making in automated dispatch systems. French and Dutch regulators now require explainable outputs when AI systems assign technicians to emergency repair calls. Healthcare field service providers in Germany face the strictest scrutiny, as patient-facing dispatch decisions fall under high-risk AI system classification with mandatory human-in-the-loop overrides.
Telecommunications procurement officers are consolidating vendor relationships around outcome-based service level agreements rather than per-seat software licenses. Verizon and Deutsche Telekom now negotiate contracts tied to mean-time-to-repair reduction and first-visit resolution rates. This metric-driven purchasing is most advanced in the United States, where carrier procurement teams have hired former McKinsey operations specialists to structure performance-guarantee clauses with penalty mechanisms for platform underperformance.
Field Service Management Market Segmentation
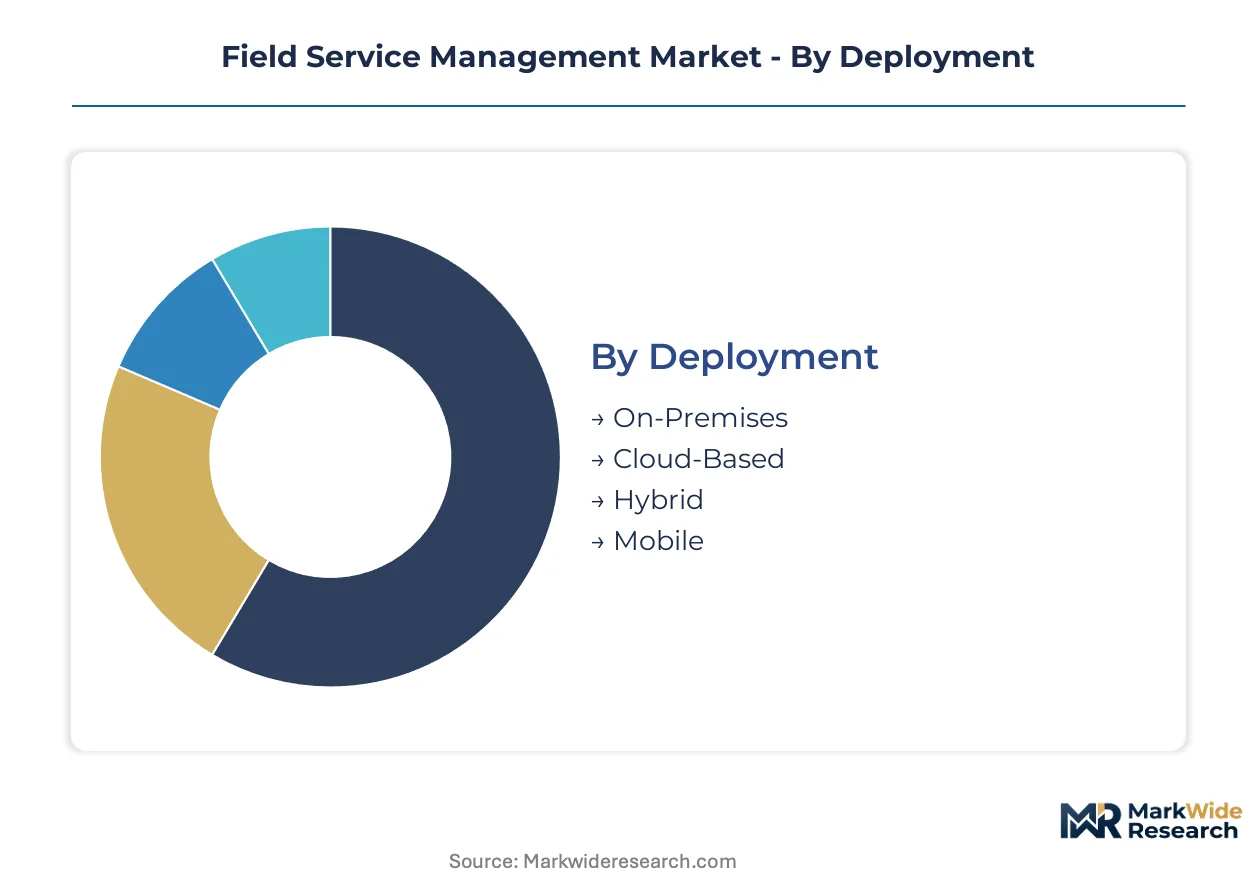
Segmentation in field service management reflects divergent infrastructure maturity and compliance requirements across industries. Procurement patterns cluster around deployment architecture preferences and solution integration depth rather than traditional vertical boundaries.
Deployment:
Platform replacement cycles now center on cloud migration timelines as organizations retire legacy server installations and consolidate data center footprints.
- Cloud-Based:Multi-tenant architectures with automatic scaling and regional data residency controls dominate new procurement. German utilities and US telecommunications carriers mandate EU-hosted or FedRAMP-authorized instances to satisfy GDPR and federal contracting requirements.
- Mobile:SQLite-backed offline applications with automatic synchronization upon connectivity restoration are displacing browser-based field tools. Indian tower maintenance contractors now specify ruggedized Android deployments with Hindi-language interfaces as baseline requirements.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure sectors with classified operational data.
- Hybrid:Edge-node processing with centralized analytics appeals to automotive service networks managing sensitive diagnostic data.
Cloud-based deployments sit at the top of the volume ranking, with mobile configurations climbing the fastest.
End User:
Customer concentration patterns reveal which sectors command premium pricing through compliance complexity and operational criticality.
- Telecommunications:5G densification and fiber rollout programs generate the largest contract values. Verizon and Deutsche Telekom negotiate outcome-based agreements tied to mean-time-to-repair metrics rather than per-seat licensing.
- Healthcare:HIPAA Business Associate Agreements and encryption protocols extend sales cycles by six to nine months. US home health agencies require documented audit trails for every technician location ping and patient interaction.
- Manufacturing:Decades-old SAP and Oracle ERP installations force expensive middleware development for platform integration.
- Energy:Predictive maintenance algorithms that anticipate transformer failure before dispatch create premium pricing tiers for integrated platform bundles.
Telecommunications captures the largest contract values, while healthcare commands the steepest expansion trajectory through regulatory-mandated platform upgrades.
Solution:
Functional modules compete for integration priority based on workflow centrality and API interoperability demands.
- Work Order Management:Core workflow engine governing technician dispatch, status tracking, and customer notification. Captures premium integration fees due to mandatory ERP connectivity requirements.
- Scheduling:AI-driven optimization replacing rule-based dispatch logic. French and Dutch regulators now mandate explainable outputs for emergency repair assignments under EU AI Act transparency obligations.
- Inventory Management:Real-time parts availability synchronization with warehouse systems.
- Asset Tracking:GPS telemetry and digital twin modeling for predictive maintenance applications.
Work order management anchors the largest margin pools, with scheduling solutions gaining share fastest through AI differentiation.
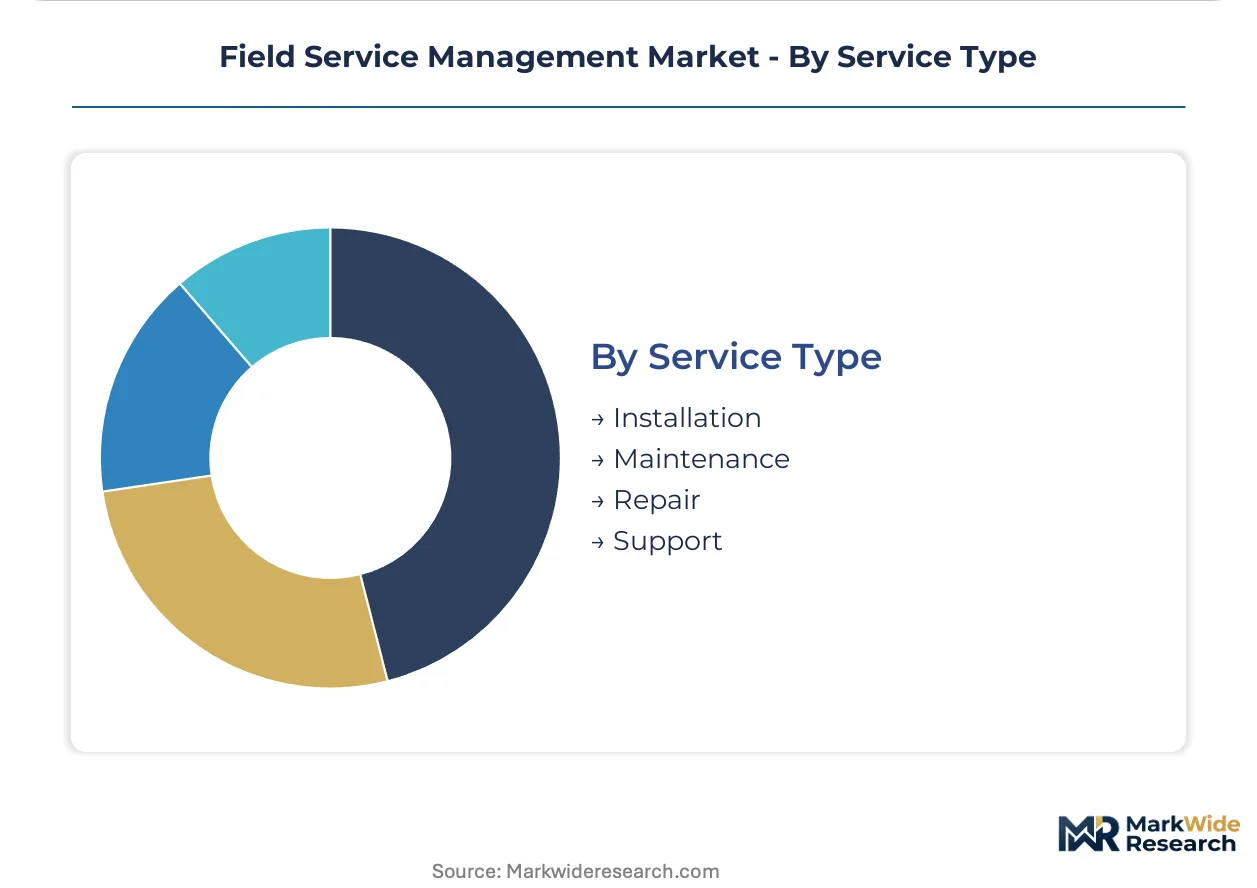
Service Type:
Operational intensity and technician skill requirements shape platform configuration complexity across service categories.
- Maintenance:Recurring preventive schedules with IoT-triggered condition-based interventions. German automotive networks deploy TensorFlow Lite models on ruggedized tablets to predict parts failure without cloud round-trips.
- Repair:Emergency response workflows with SLA penalty structures and real-time customer communication. FCC workforce safety mandates now require OSHA-aligned incident reporting for US telecommunications technicians.
- Installation:Project-based dispatch with material staging and quality verification checkpoints.
- Support:Remote diagnostics integration and knowledge base access for field troubleshooting.
Maintenance generates the most predictable recurring revenue, with repair services expanding most quickly through emergency response premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform architects concentrate in Seattle, San Francisco, and Bengaluru, anchoring cloud-native development centers that feed deployment pipelines across telecommunications and utility sectors. Technical talent density in these clusters shapes product roadmaps and localization priorities.
United States
Verizon and AT&T consolidate procurement around outcome-based contracts tied to mean-time-to-repair metrics. FCC workforce safety mandates require real-time technician location documentation and OSHA-aligned incident reporting. Dallas-Fort Worth anchors tower maintenance dispatch centers coordinating 5G small-cell installations across Texas.
Germany
Deutsche Telekom negotiates performance-guarantee clauses with penalty mechanisms for platform underperformance. GDPR-mandated data residency forces EU-hosted cloud deployments with localized encryption and audit trails. Munich automotive service networks deploy TensorFlow Lite models on ruggedized tablets for edge-based parts failure prediction.
India
Maharashtra and Gujarat distribution companies modernize grid infrastructure, creating first-mover advantage for providers with Hindi-language mobile interfaces. TRAI regulations on telecommunications infrastructure quality filter into platform feature requirements. Bengaluru technical talent pools drive SQLite-backed offline mobile development for tower maintenance contractors.
United Kingdom
BT Group and Virgin Media O2 compress procurement cycles from multi-year RFPs to single-platform commitments. GDPR cross-border data residency rules complicate deployments serving Northern Ireland and Republic of Ireland technician fleets. London financial services sector demand pulls hybrid edge-node architectures for sensitive diagnostic data handling.
France
Orange SA structures vendor consolidation around integrated asset tracking and work order management bundles. EU AI Act transparency obligations mandate explainable outputs when automated systems assign technicians to emergency repair calls. Lyon industrial maintenance clusters drive predictive maintenance algorithm development for transformer failure anticipation.
Field Service Management Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered pricing and deployment complexity segments. Enterprise software conglomerates leverage ERP integration depth and manufacturing-sector specialization against cloud-native challengers betting on mobile-first architectures. Three strategic archetypes dominate: asset-centric industrial platforms, CRM-native field service extensions, and vertical-specific contractor tools. Competitive moves concentrate on M&A for API talent acquisition and outcome-based contract structuring with penalty mechanisms.
Within the asset-centric tier, ServiceMax and IFS Field Service Management exemplify industrial-specialist positioning with deep equipment lifecycle management. Salesforce Field Service and Oracle Field Service occupy the enterprise-integrated vector, leveraging native CRM and ERP connectivity respectively. ServiceTitan and Jobber anchor the contractor-focused end, representing vertical specialization for trades-specific workflows. Zuper sits within the emerging mobile-native challenger category, exemplifying SQLite-backed offline architecture development for technician-centric deployment scenarios.
| Leading Market Players |
|---|
| Microsoft Dynamics 365 Field Service |
| ServiceMax |
| ServiceTitan |
| ServiceNow Field Service Management |
| Jobber |
| Salesforce Field Service |
| Oracle Field Service |
| Zuper |
| IFS Field Service Management |
| Others |
Cost & Logistics Intelligence
EU AI Act transparency obligations gate qualified supply for automated dispatch platforms and premium-tier pricing access for vendors with documented algorithmic decision-making capabilities. GDPR-mandated data residency requirements in Germany and France further stratify vendor tiers, as only cloud providers with EU-hosted infrastructure can bid for utility and telecommunications contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates outcome-based contracts from modular SaaS licensing. Telecommunications carriers negotiate performance-guarantee clauses tied to mean-time-to-repair metrics, while mid-market contractors purchase per-seat subscriptions for work order management alone. Price differentiation hinges on AI dispatch optimization depth and FedRAMP or GDPR compliance certification. Pricing pressure stems from hyperscale cloud infrastructure concentration, compressing margins for providers without sovereign hosting capabilities. Healthcare field service buyers exhibit highest price sensitivity due to extended HIPAA-aligned sales cycles, whereas energy utilities demonstrate lowest sensitivity given operational criticality.
Supply Chain Analysis
GPS module supply rests on Taiwanese semiconductor foundries, SQLite mobile database engines on US West Coast software clusters, and ruggedized Android hardware on Shenzhen electronics manufacturers. Cloud infrastructure draws from hyperscale providers in the United States, Germany, and India. Single-source vulnerability concentrates in sovereign cloud hosting for European compliance deployments. Distribution runs through direct enterprise sales teams for telecommunications carriers, value-added resellers for mid-market contractors, and systems integrators for SAP and Oracle ERP-embedded deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Field Service Management Market functions as a regulatory compounder, with FCC workforce safety mandates and EU AI Act transparency obligations forcing platform upgrades that expand addressable demand.
For Market Incumbents: Extend API interoperability depth to defend against mobile-native challengers eroding mid-market share. Acquire SQLite architecture engineering talent to close skill scarcity gaps in bidirectional ERP synchronization. Cement long-term contracts with outcome-based SLA structures that embed penalty mechanisms for platform underperformance.
For New Entrants and Emerging Players: Direct-to-virtual channel routes through Salesforce AppExchange and Oracle Cloud Marketplace bypass incumbent sales team scale advantages. Maharashtra and Gujarat state-level utilities in India represent the most penetrable geography, with Hindi-language mobile interfaces and local implementation partnerships as the critical go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for mobile-native challenger platforms because telecommunications procurement consolidation compresses viable independent vendor counts. Target specialists with proven TensorFlow Lite edge deployment capabilities and existing FCC or GDPR compliance documentation. Watch for AI transparency enforcement timelines as the inflection indicator triggering premium-multiple repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM connectivity unifies customer records with dispatch operations for Verizon-scale carriers. |
| Acquisition of Specialist Firm | API architecture engineering talent scarcity makes SQLite synchronization developers prime targets. |
| Geographic Expansion | Hindi-language mobile interfaces unlock Maharashtra and Gujarat distribution company modernization budgets. |
| Strategic Partnership | Systems integrators bridge decades-old SAP installations to modern FSM architectures for manufacturers. |
| Product Launch | TensorFlow Lite edge models on ruggedized tablets enable predictive maintenance without cloud round-trips. |
Research Approach
Coverage spans the United States, Germany, India, the United Kingdom, and France, with primary inputs from each market cluster. Field service management platform executives, telecommunications procurement officers, utility operations directors, and systems integration specialists provided structured interviews. Secondary validation drew from FCC equipment authorization filings, GDPR enforcement actions by national data protection authorities, TRAI infrastructure quality circulars, and hyperscaler cloud region expansion disclosures. Bottom-up deployment counts triangulated against top-down enterprise software spending estimates.
Rate-of-change decomposition separates cloud migration velocity from mobile-native replacement cycles and AI feature adoption curves across the projection horizon. Segmentation dimensions include deployment architecture, end-user vertical, solution module, and service type, with regional regulatory cluster as an additional modeled layer. CAGRs derive from installed base growth adjusted for platform replacement timing and pricing tier mix shifts. Forecast inputs incorporate 5G small-cell installation run rates and EU AI Act implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for edge-based predictive maintenance would alter the outlook. Forecasts reflect assumptions about telecommunications carrier consolidation pace and healthcare HIPAA certification timeline compression. A small set of named triggers—semiconductor input cost volatility, sovereign cloud provider concentration events, and legacy ERP API layer development—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Shared Services Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market