
 United States Non-Dairy Milk Market | 2026-2036
United States Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
United States Non-Dairy Milk Market Insights
Asset-light contract manufacturing and third-party co-packing arrangements is reconfiguring capital requirements for new entrants in the United States non-dairy milk sector. Blue Diamond Growers leverages its integrated almond supply chain from California's Central Valley to control raw material costs. Danone North America sustains broad retail distribution through its legacy dairy infrastructure repurposed for plant-based lines. Califia Farms specializes in barista-formulated products that command premium placement in specialty coffee channels.
Non-dairy milk denotes plant-based liquid beverages engineered to replicate the functional properties of bovine milk through homogenization, enzymatic processing, and fortification with calcium, vitamin D, and stabilizers; these formulations serve as direct substitutes in beverage, bakery, and food service applications where emulsion stability and foamability determine utility. Oat milk leads volume growth due to its superior foaming characteristics and neutral flavor profile in coffee applications. Almond milk occupies the most mature position with established household penetration but faces water-usage scrutiny. The beverage industry segment captures concentrated margin pools as on-premise operators adopt non-dairy defaults.
The FDA governs plant-based milk labeling standards and nutrient fortification claims, while USDA organic certification shapes premium positioning and price architecture. State-level clean-label mandates in California and New York are tightening additive disclosure requirements. Stakeholders must monitor evolving federal standards on protein equivalence claims and emerging state legislation on water-intensive crop sourcing that could reshape supplier geography.
Market Dynamics
Specialty coffee chains are converting oat milk from alternative option to default standard, compressing procurement timelines and forcing upstream suppliers to reconfigure formulation priorities around foam stability and neutral flavor profiles rather than cost minimization.
Growth Catalysts
- California's clean-label statutes:State-level additive disclosure mandates are accelerating reformulation toward shorter ingredient decks, creating competitive separation for brands with transparent supply chains.
- Barista-grade foamability engineering:Enzymatic processing advances are enabling oat milk to replicate dairy's micro-foam performance, locking in placement across Pacific Northwest café networks.
- Central Valley almond infrastructure:Mature processing clusters in California's agricultural belt concentrate raw material access, lowering logistics costs for established operators.
Market Restraints
- Almond water intensity:One gallon of almond milk requires approximately 15 gallons of water input, exposing producers to drought-related supply shocks and ESG scrutiny.
- FDA protein equivalence friction:Pending federal guidance on comparative nutrition claims creates labeling uncertainty that slows new product pipeline decisions.
- Soy milk residual demand erosion:Former category leader soy milk faces accelerated displacement as oat and pea alternatives capture health-conscious switchers.
Strategic Opportunities
- Food service direct distribution:Bypassing retail slotting fees through institutional supply contracts with college and corporate dining operators unlocks volume at lower customer acquisition cost.
- USDA organic certification premium tier:Certified organic positioning commands shelf price premiums of 40-60% above conventional plant-based alternatives in natural channel placements.
- Pea-protein functional convergence:Blending pea isolate with oat base improves amino acid completeness while maintaining foam performance, opening sports nutrition adjacencies.
Industry Challenges
- Enzyme specialist talent scarcity:Formulation chemistry expertise at the intersection of food science and barista-performance requirements commands premium compensation and extends R&D timelines.
- Co-packer capacity bottlenecks:Asset-light entrants face 12-18 month queue times for aseptic processing capacity at qualified third-party facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Non-Dairy Milk Market |
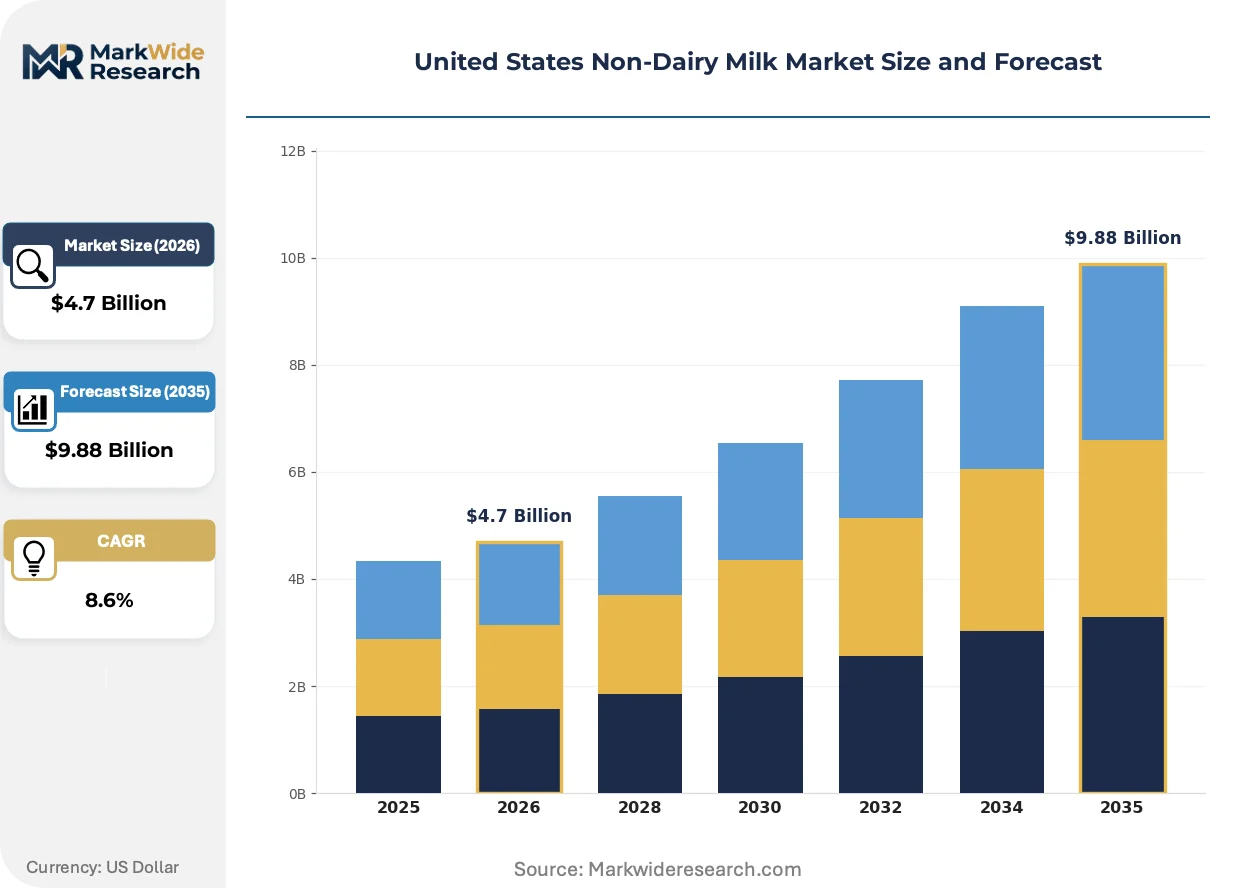
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Consumer Type: Health-Conscious Individuals, Vegan Consumers, Lactose-Intolerant Individuals, Flexitarians Packaging Type: Cartons, Bottles, Pouches, Tetra Packs End Use: Household, Food Service, Beverage Industry, Bakery Applications |
| Companies Covered | Blue Diamond Growers, Danone North America, Califia Farms, Oatly Group AB, Ripple Foods, Chobani, Hain Celestial Group, SunOpta, Pacific Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Non-Dairy Milk Market Trends and Innovations
Formulation science is converging with café operational requirements to create a new product category defined by functional performance rather than ingredient mimicry.
High-pressure homogenization combined with lipid micro-encapsulation is digitizing texture engineering in oat milk production. Pacific Northwest roaster chains are adopting these precision-processed variants within six-month qualification windows. The technology is digitizing how suppliers model mouthfeel parameters, compressing iteration cycles from 18 months to 90 days.
FDA's updated plant-based milk labeling guidance is tightening comparative claim standards. Manufacturers must now substantiate protein, calcium, and vitamin equivalence against dairy benchmarks or carry disqualifying disclaimers. Barista-formulated sub-segments face the steepest compliance costs as they balance performance additives against clean-label positioning.
Café operators are consolidating supplier relationships around single-source oat milk contracts with guaranteed foam-performance specifications. Independent roasters in Portland and Seattle are displacing rotating alternative menus with locked-in default partnerships. This consolidation pattern concentrates most visibly in urban markets where labor training costs favor simplified inventory management.
United States Non-Dairy Milk Market Segmentation
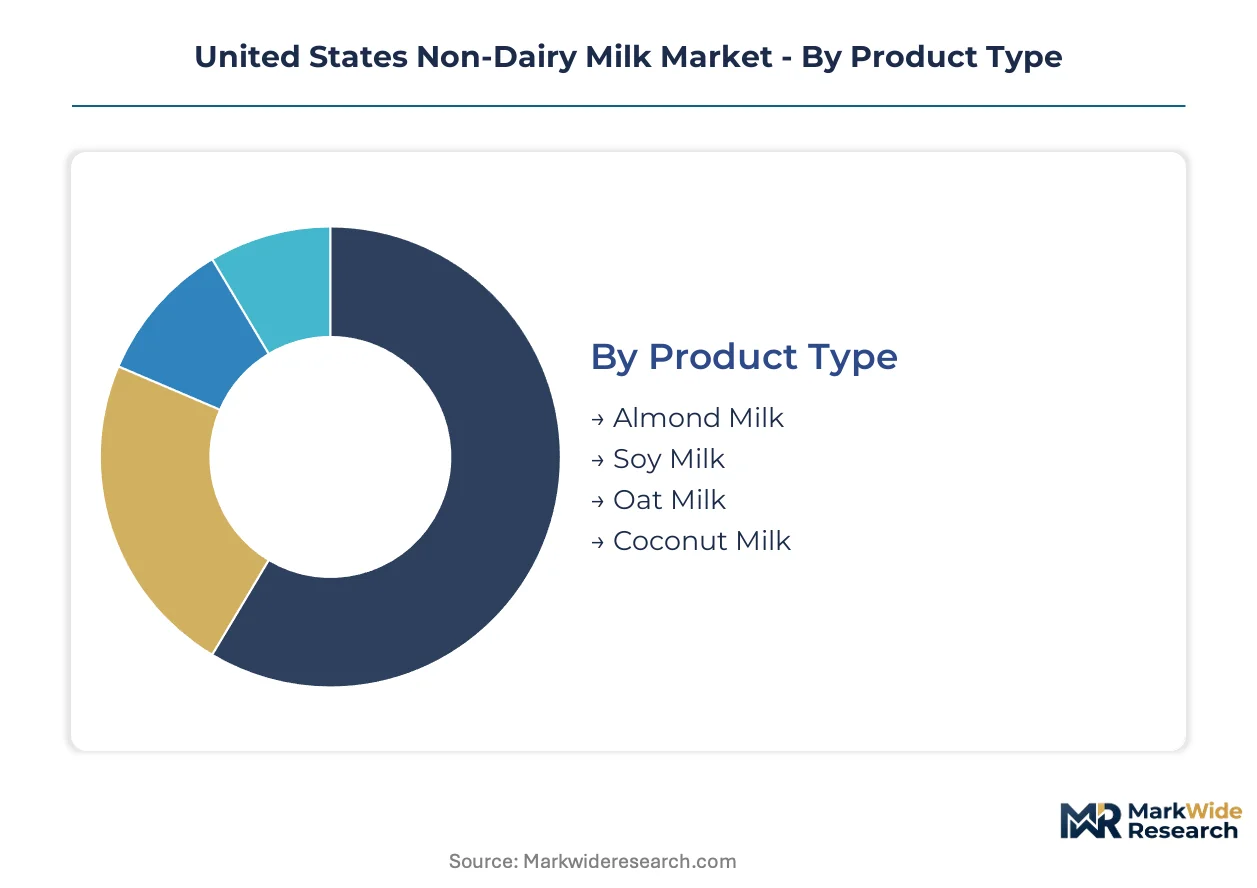
Non-dairy milk segmentation reveals distinct performance requirements across consumption contexts. Product formulation priorities diverge sharply between retail shelf stability and food service foam engineering, while packaging economics reshape channel access for emerging brands.
Product Type:
After-sales intensity in this category manifests through barista technical support and formulation troubleshooting rather than traditional service contracts—suppliers win on responsiveness to café operator complaints about foam collapse or flavor drift.
- Oat Milk:Enzymatically processed oat bases achieve micro-foam stability through lipid encapsulation and protein structuring. Pacific Northwest specialty coffee chains have converted this format to default status, compressing supplier qualification windows and demanding guaranteed performance specifications rather than batch-to-batch variability tolerance.
- Almond Milk:Mature processing infrastructure in California's Central Valley delivers cost advantages through integrated supply chains from orchard to aseptic packaging. Established household penetration faces water-intensity scrutiny under state-level sustainability disclosure mandates, pressuring suppliers toward drought-resilient sourcing or alternative base formulations.
- Soy Milk:Former category leader retains processing scale advantages but faces accelerated displacement as flavor-neutral alternatives capture switchers.
- Coconut Milk:Tropical sourcing dependencies and pronounced flavor profile limit mainstream penetration outside specific culinary applications.
By volume, almond milk leads. By growth pace, oat milk is expanding most quickly.
Consumer Type:
Cost tier stratification separates premium-positioned organic certifications from conventional alternatives, with price gaps of forty to sixty percent shaping purchase frequency and brand loyalty patterns.
- Health-Conscious Individuals:Protein equivalence claims and fortification transparency drive selection criteria, with FDA comparative nutrition guidance reshaping permissible label assertions.
- Vegan Consumers:Ethical sourcing verification and supply chain transparency command sustained price premiums in natural channel placements.
- Lactose-Intolerant Individuals:Functional substitution needs prioritize digestive tolerance over flavor replication, sustaining demand for established formats.
- Flexitarians:Occasional dairy replacement occasions favor neutral-flavor options with broad recipe compatibility and minimal preparation adjustment.
By volume, health-conscious individuals dominate. By growth pace, flexitarians are gaining share fastest.
Packaging Type:
Application-specific requirements separate shelf-stable retail distribution from refrigerated fresh formats, with aseptic technology investments determining channel access breadth.
- Cartons:Standard retail format with established recycling infrastructure and efficient palletization for mass-market distribution.
- Bottles:Premium positioning vehicle in refrigerated sections, signaling freshness and justifying price elevation through visual differentiation.
- Pouches:Emerging format for single-serve and on-the-go consumption occasions, with lower material costs offset by limited shelf presence.
- Tetra Packs:Aseptic processing compatibility enables ambient distribution without refrigeration infrastructure, unlocking food service and institutional volume.
By volume, cartons lead. By growth pace, tetra packs show steepest expansion trajectory.
End Use:
Customer type concentration separates household occasional consumption from institutional procurement scale, with contract terms and technical service requirements diverging accordingly.
- Food Service:Barista-performance specifications lock in supplier relationships through guaranteed foam stability and neutral flavor profiles. Portland and Seattle café networks consolidate around single-source contracts with simplified inventory management.
- Beverage Industry:Formulation integration into ready-to-drink products demands batch consistency and scalable supply commitments for co-manufacturing partnerships.
- Household:Retail channel placement competes on price positioning and clean-label ingredient deck transparency under tightening state-level disclosure mandates.
- Bakery Applications:Functional properties around emulsion stability and moisture retention determine utility in commercial baking operations.
By volume, household leads. By growth pace, food service is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated plant-based milk labeling guidance and California's clean-label statutes are accelerating reformulation investments across state boundaries. Demand clusters concentrate where ingredient sourcing infrastructure and specialty coffee culture intersect.
California
Central Valley almond orchards supply integrated processors with captive raw material access. State-level additive disclosure mandates under California's clean-label statutes are forcing shorter ingredient decks. Los Angeles and San Francisco café networks are consolidating procurement around single-source oat milk contracts with guaranteed foam specifications.
Pacific Northwest
Portland and Seattle roaster chains have converted oat milk to default status, compressing supplier qualification windows. Oregon and Washington state regulations on organic certification enforcement shape premium positioning requirements. The region's barista-forward culture drives enzymatic processing innovation for micro-foam stability.
New York Metro
Corporate dining contracts and institutional food service operators generate concentrated volume demand. New York State clean-label mandates parallel California's disclosure requirements, tightening additive transparency rules. Brooklyn and Manhattan specialty coffee density supports premium placement for barista-formulated products.
Texas
Dallas and Houston food service distributors are expanding refrigerated distribution capacity for plant-based alternatives. State agricultural policy incentives for drought-resistant crop research indirectly pressure almond-dependent suppliers. Austin's specialty coffee scene replicates Pacific Northwest default-oat procurement patterns.
Midwest
Chicago's central logistics position anchors national distribution networks for shelf-stable formats. Illinois and Ohio food manufacturing infrastructure supports co-packing capacity for emerging brands. Minneapolis-St. Paul retail channels show elevated organic certification penetration relative to national averages.
United States Non-Dairy Milk Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates between legacy agricultural cooperatives with captive supply chains and asset-light brands dependent on third-party manufacturing. Three archetypes dominate: integrated orchard-processor hybrids, dairy-legacy repurposers, and barista-performance specialists. Competitive moves concentrate on co-packer capacity locking and direct food service distribution bypassing retail slotting fees.
Within the integrated supply tier, Blue Diamond Growers exemplifies orchard-to-package vertical control. Danone North America occupies the dairy-legacy repurposer position, leveraging existing cold-chain infrastructure. Califia Farms anchors the barista-specialist archetype, commanding premium placement through foam-performance formulation. These three represent distinct capital structure approaches to the same end-market.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Danone North America |
| Califia Farms |
| Oatly Group AB |
| Ripple Foods |
| Chobani |
| Hain Celestial Group |
| SunOpta |
| Pacific Foods |
| Others |
Pricing and Supply Chain Analysis
Aseptic processing undercapacity across the Pacific Northwest and California Central Valley compresses supplier margins while elevating spot pricing for co-packer slots. This utilization squeeze forces emerging brands toward long-term capacity commitments or captive facility investments, reshaping capital deployment across conventional and organic product tiers.
Pricing Analysis
Certification level creates the primary spread between conventional and USDA organic positioning, with the latter commanding shelf premiums through additive-free ingredient decks and transparent sourcing verification. Three-tier pricing structure across premium barista-formulated, standard retail, and economy private-label levels reflects performance specification differentiation rather than base ingredient cost. Pricing pressure stems from co-packer queue bottlenecks extending lead times and forcing expedited processing premiums. Food service buyers exhibit lowest price sensitivity due to locked-in foam-performance contracts, while mass-market retail channels drive aggressive private-label negotiation.
Supply Chain Analysis
California export-control scrutiny on water-intensive agricultural commodities indirectly constrains almond milk production scaling through drought-related supply allocation mechanisms. Raw material sourcing draws from California Central Valley orchards, Midwest oat processing clusters, and Pacific Northwest enzymatic ingredient specialists. Single-source vulnerability concentrates in aseptic packaging substrate supply, where qualified domestic manufacturers face sustained order backlogs. Distribution runs through refrigerated cold-chain networks for fresh formats and ambient logistics for shelf-stable tetra pack variants, with direct food service contracts bypassing traditional retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oat milk's displacement of almond and soy alternatives forces incumbents to defend formulation expertise and channel relationships against barista-performance specialists capturing default-placement contracts.
For Market Incumbents: Insulate core retail shelf space through exclusive distribution partnerships with college and corporate dining operators, locking in volume commitments before specialty coffee chains consolidate procurement around single-source oat milk suppliers. Accelerate backward integration into California Central Valley oat processing infrastructure to reduce co-packer dependency and capture margin compression from queue bottlenecks. Counter pea-protein blend entrants by investing in enzymatic lipid encapsulation R&D to maintain foam-performance differentiation. For New Entrants and Emerging Players: Establish a beachhead in Texas and Midwest food service channels where Pacific Northwest procurement patterns are replicating but supplier relationships remain unsettled. Target institutional dining contracts in Dallas, Houston, and Chicago corporate campuses where direct distribution bypasses retail slotting barriers. Lead with USDA organic certification and clean-label positioning to exploit California and New York additive disclosure mandates that disadvantage legacy formulations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barista-formulated sub-segments as enzymatic processing equipment and in-house R&D capabilities replace asset-light co-packing models. Prioritize acquisition targets with captive oat processing infrastructure or locked-in Pacific Northwest café network contracts rather than pure brand plays dependent on third-party manufacturing. Monitor FDA protein equivalence guidance finalization as the signal to watch for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Processing | Captive supply from Midwest grain elevators reduces co-packer queue exposure and stabilizes input costs. |
| Barista-Performance Certification Program | Foam-stability guarantees lock in Pacific Northwest café default placements against commodity alternatives. |
| Direct Food Service Distribution Expansion | Bypassing retail slotting fees unlocks college and corporate dining volume at lower customer acquisition cost. |
| USDA Organic Supply Chain Repositioning | Clean-label compliance with California and New York disclosure mandates creates regulatory arbitrage against conventional competitors. |
| Enzymatic Processing R&D Partnership | Collaboration with lipid micro-encapsulation specialists accelerates texture engineering iteration cycles from months to weeks. |
Research Methodology
Cross-validation between primary interviews with oat milk formulators, specialty coffee chain procurement directors, and co-packer operations managers anchors the qualitative findings against secondary validation from FDA labeling guidance documents, USDA organic certification databases, and state-level clean-label statute filings. Plant-based beverage trade association publications and aseptic processing equipment manufacturer technical specifications provided additional triangulation points. Bottom-up volume estimates from individual brand production capacities and top-down category sizing from retail channel audit data were reconciled through iterative adjustment.
Calibration against historical volume trajectories in adjacent plant-based categories informed growth assumption boundaries across the projection horizon. Segmentation modeling incorporated product type, packaging format, end-use channel, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth contributions across these segments, with specific inputs including Pacific Northwest café network expansion rates, Central Valley water allocation policy shifts, and enzymatic processing technology adoption curves.
Stress conditions across drought-related almond supply disruptions, FDA protein equivalence claim restrictions, and co-packer capacity expansion delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding oat cultivation yield stability and specialty coffee chain default-switching velocity. Cross-checking against Nielsen retail velocity data and food service distributor shipment records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
India Dairy Alternatives Market