
 Sesame Milk Market | 2026-2036
Sesame Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Sesame Milk Market Analytics
Skilled food technologists with sesame protein extraction expertise is collapsing across North American manufacturing hubs, constraining production scale-up for emerging brands. Hope & Sesame leverages its dedicated sesame supply chain to secure raw material consistency. Califia Farms anchors its plant-based portfolio diversification through sesame milk R&D investment. Elmhurst 1925 differentiates via its patented HydroRelease milling method applied to sesame processing.
Sesame milk denotes an aqueous emulsion produced from ground sesame seeds, typically containing 2-4% protein, 3-5% fat, and functional lignans such as sesamin, with commercial formulations homogenized for beverage stability and barista-grade foaming performance. The unsweetened variant dominates household purchase patterns due to clean-label positioning and recipe versatility. Flavored SKUs occupy the fastest-expanding margin pool as manufacturers target Gen Z trial through vanilla and chocolate extensions. Tetra Pack formats lead shelf-stable distribution through supermarkets and health food stores, while bottle packaging concentrates in refrigerated premium channels.
FDA labeling standards for plant-based dairy alternatives directly shape sesame milk shelf placement and nutritional claim permissibility. EFSA novel food assessments govern European market entry pathways for sesame protein isolates. Organic certification under USDA National Organic Program and EU Organic Regulation creates tiered pricing architecture across retail channels. Stakeholders must monitor evolving protein content thresholds that regulators may mandate for plant-based milk equivalence claims.
Market Dynamics
The FDA's updated plant-based milk labeling standards are compressing shelf placement options and forcing reformulation investments across the category. This regulatory pivot is reshaping competitive positioning by rewarding brands with compliant protein fortification and penalizing marginal players.
Growth Catalysts
- Specialty Coffee Channel Expansion:Barista-grade foaming performance specifications from third-wave coffee shops are pulling formulation upgrades. Equipment manufacturers now calibrate steam wands for sesame milk viscosity profiles.
- EFSA Novel Food Pathway:Streamlined assessments for sesame protein isolates are accelerating European market entry timelines. Manufacturers gain equivalence claims faster than competing novel proteins.
- Oat Milk Fatigue Rotation:German consumers are redirecting trial budgets toward sesame-derived alternatives as oat milk reaches saturation in organic retail channels.
Market Restraints
- Protein Extraction Talent Collapse:Skilled food technologists with sesame-specific expertise are scarce across North American manufacturing hubs, constraining production scale-up.
- Raw Material Concentration Risk:Dedicated sesame supply chains cluster in specific growing regions, exposing processors to climate volatility and geopolitical friction.
- HydroRelease Patent Thickets:Milling method IP held by incumbent processors creates licensing barriers for emerging brands seeking clean-label positioning.
Strategic Opportunities
- USDA Organic Certification Arbitrage:Tiered pricing architecture under the National Organic Program allows premium positioning in conventional retail alongside mass-market SKUs.
- Flavored SKU Margin Expansion:Vanilla and chocolate extensions targeting Gen Z trial represent underexploited margin pools beyond unsweetened baseline products.
- Tetra Pack Channel Innovation:Shelf-stable formats enable distribution through pharmacy and convenience channels currently underserved by refrigerated alternatives.
Industry Challenges
- Protein Content Threshold Uncertainty:Pending FDA equivalence claim standards require speculative fortification investments ahead of final rulemaking.
- Homogenization Equipment Backlogs:Beverage stability specifications demand specialized capital equipment with extended procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sesame Milk Market |
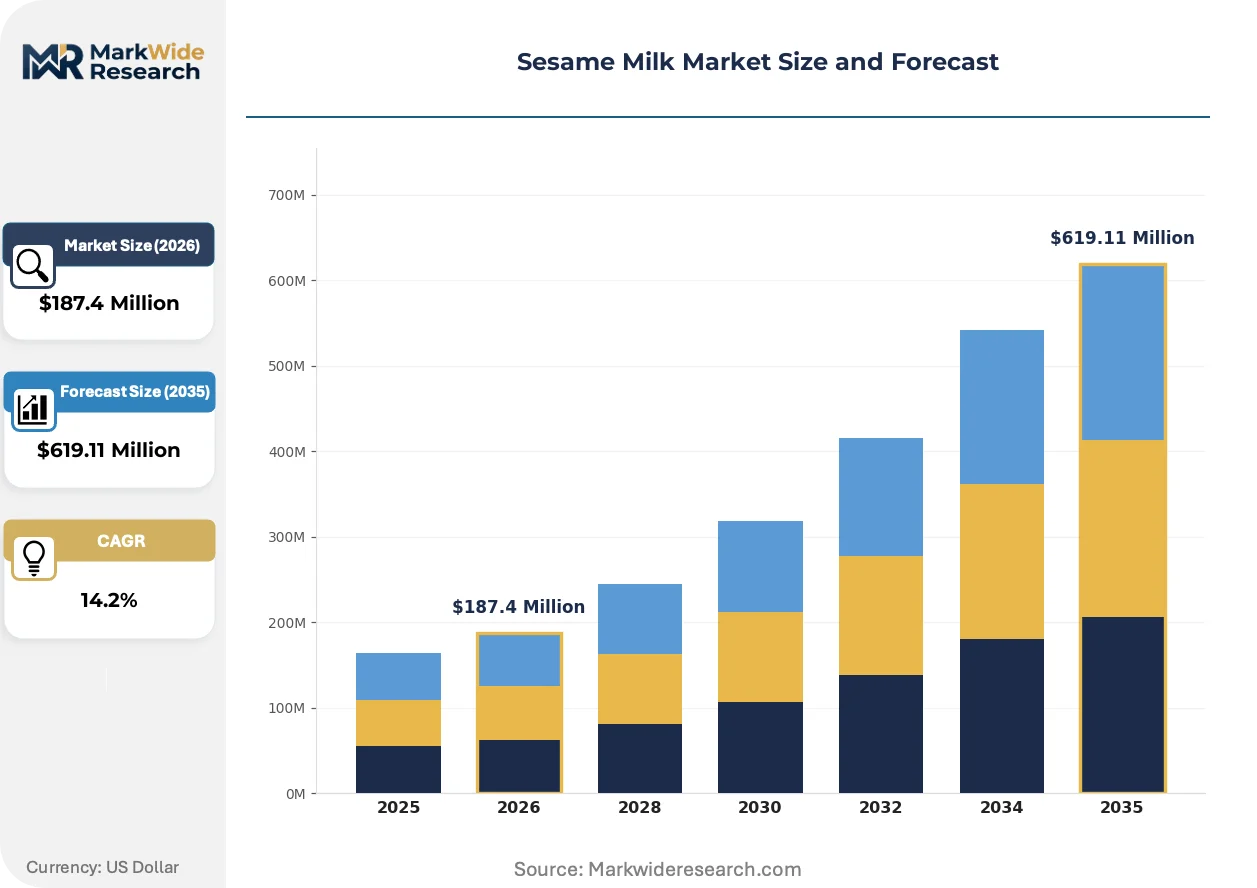
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original, Unsweetened, Flavored, Organic End User: Households, Restaurants, Cafes, Food Manufacturers Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Online, Supermarkets, Convenience Stores, Health Food Stores |
| Companies Covered | Hope & Sesame, Sesamilk Foods Co., Ltd, Ecomil, Elmhurst 1925, So Delicious Dairy Free, Califia Farms, Alpro, Pacific Foods, Good Karma Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sesame Milk Market Evolving Landscape
Processing technology and regulatory compliance are diverging into parallel innovation tracks. Manufacturers must simultaneously advance extraction efficiency while navigating evolving labeling permissibility.
HydroRelease milling methods are bifurcating the competitive landscape. This patented aqueous processing technology eliminates stabilizers and gums. Premium barista-grade producers are adopting it aggressively. Conventional homogenization equipment users face margin compression as clean-label positioning becomes table stakes.
EFSA novel food assessments are tightening documentation requirements for sesame protein isolates. European entrants must now submit comprehensive digestibility studies. German and Dutch regulators are applying these standards most stringently. Brands are pre-emptively commissioning clinical trials to accelerate approval timelines.
Clean-label procurement preferences are compressing formulation complexity. Retail buyers now mandate single-digit ingredient counts for shelf placement. Specialty grocery channels in Germany and the United States are rejecting SKUs with added gums or emulsifiers. Manufacturers are reformulating around native sesame lignan stability rather than additive-dependent solutions.
Sesame Milk Market Segmentation
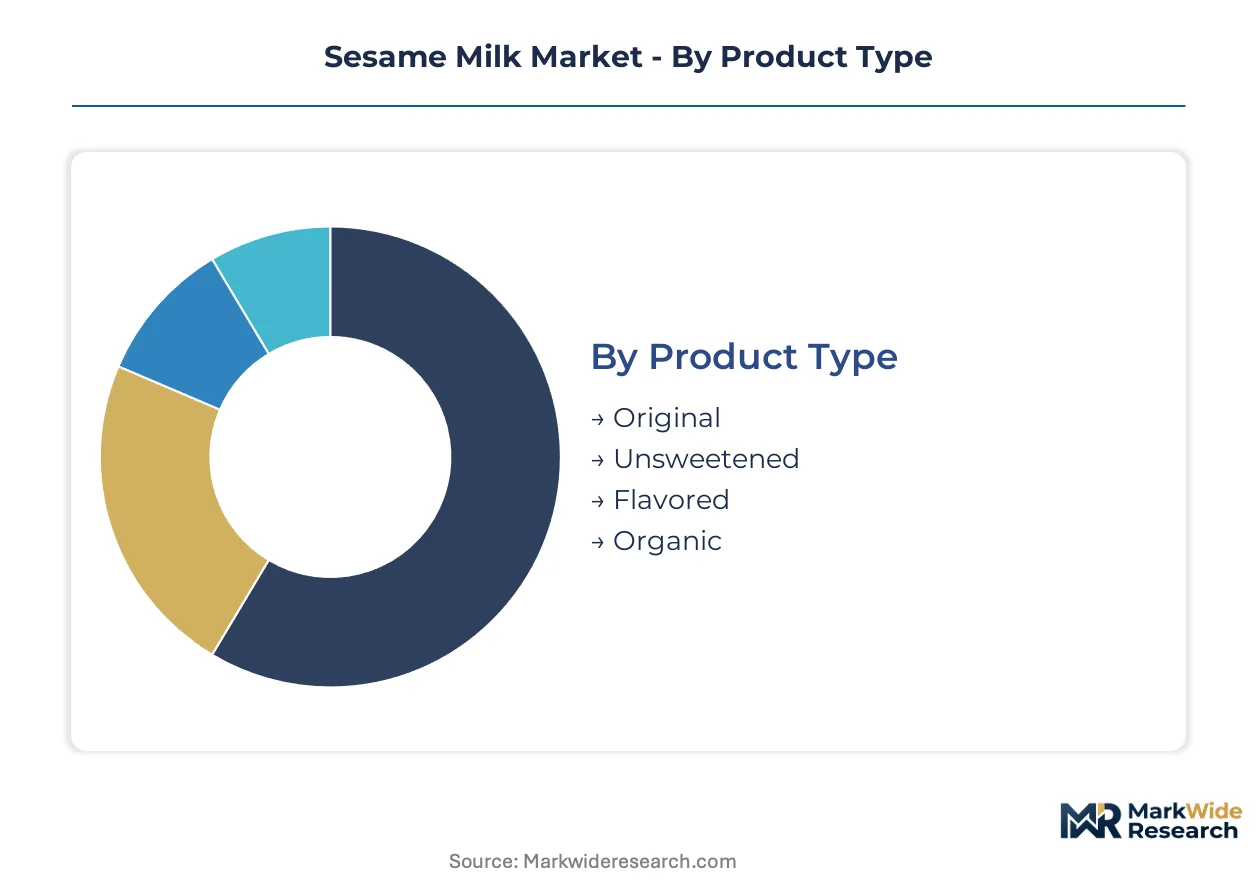
Sesame milk segmentation reveals how formulation choices and channel access determine competitive vulnerability. Substitution pressure from oat, almond, and emerging legume milks varies sharply across product tiers and end-use applications.
Product Type:
Unsweetened variants face the strongest substitute threat from private-label oat milks in German organic retail, forcing brands to differentiate through protein fortification and barista-grade performance claims.
- Unsweetened:Contains 2-4% native sesame protein with no added sweeteners, positioned for recipe versatility and clean-label household consumption. Demand concentrates in German organic supermarkets where oat milk fatigue redirects trial toward sesame alternatives with superior lignan profiles.
- Flavored:Vanilla and chocolate extensions targeting Gen Z trial through sensory differentiation. Specialty coffee chains in Berlin and Hamburg are pulling chocolate SKUs for menu integration, though margin compression from cocoa cost volatility constrains expansion.
- Original:Standard formulations with minimal processing retain cost competitiveness in conventional retail.
- Organic:USDA National Organic Program and EU Organic Regulation certification creates tiered pricing architecture across premium channels.
Unsweetened retains volume leadership; Flavored holds the steepest expansion curve.
End User:
Cost tier stratification separates premium extraction capabilities from commodity processing, with food manufacturers commanding lowest unit economics and highest volume stability.
- Cafes:Third-wave coffee shops specify barista-grade foaming performance with steam wand calibration for sesame milk viscosity profiles. Equipment manufacturers now optimize for this segment's technical requirements.
- Households:Refrigerated bottle purchases concentrate in urban centers with established plant-based trial behavior, particularly in German metropolitan markets.
- Restaurants:Menu integration lags behind cafes due to inventory complexity and shorter shelf-life requirements for fresh formats.
- Food Manufacturers:Industrial buyers source sesame protein isolates for bakery and confectionery applications, with EFSA novel food assessments governing European procurement decisions.
Food Manufacturers anchor volume; Cafes climb the fastest on equipment co-development investments.
Packaging Type:
Margin structure diverges sharply between ambient-stable and refrigerated formats, with Tetra Pack commanding shelf placement premiums in pharmacy and convenience channels.
- Tetra Packs:Shelf-stable aseptic cartons enable distribution through supermarkets and health food stores without cold chain dependency. German retailers prioritize this format for organic channel expansion.
- Bottles:Refrigerated premium positioning concentrates in urban specialty grocery with shorter shelf life and higher per-unit margins.
- Cans:Limited adoption for export markets and food service bulk applications.
- Pouches:Emerging format for single-serve convenience and on-the-go consumption trials.
Tetra Packs retain volume leadership; Bottles hold the steepest expansion curve in premium urban channels.
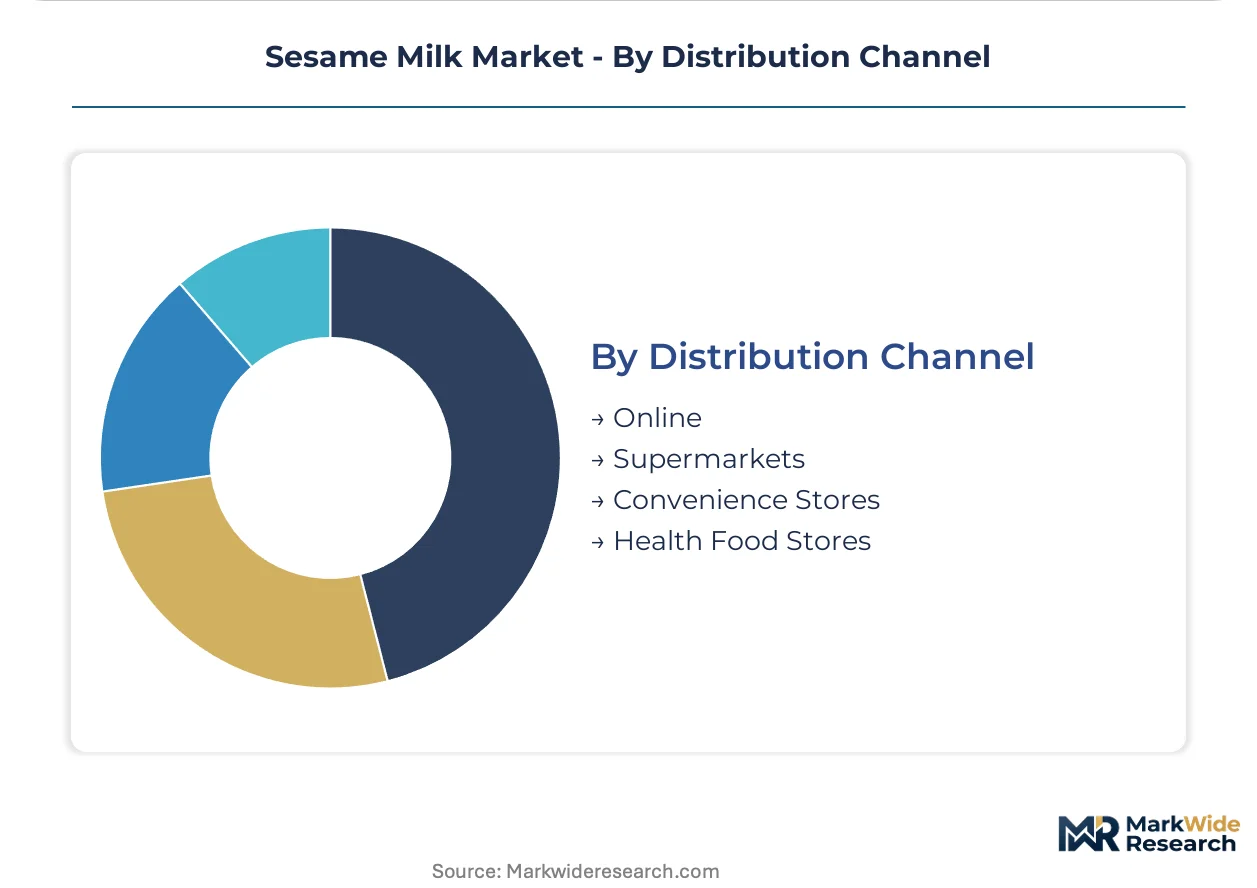
Distribution Channel:
Supply concentration in German retail clusters shapes channel priority, with health food stores anchoring organic certification premiums and online direct-to-consumer capturing trial-driven repurchase.
- Health Food Stores:Organic certification and clean-label positioning command shelf placement premiums. German chains reject SKUs with added gums or emulsifiers, forcing native lignan stability formulations.
- Supermarkets:Conventional retail access requires competitive pricing against established oat and almond alternatives, with FDA labeling standards directly shaping nutritional claim permissibility.
- Online:Direct-to-consumer subscription models capture repeat purchase from trial converters, particularly in US metropolitan markets with established plant-based consumption patterns.
- Convenience Stores:Shelf-stable Tetra Pack formats enable placement in underserved pharmacy and convenience channels currently lacking refrigerated alternatives.
Supermarkets retain volume leadership; Health Food Stores gain share fastest on certification-driven premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling standards anchor United States market dynamics, while EFSA novel food pathways govern European entry. German consumer rotation from oat milk creates concentrated demand pull.
Germany
Oat milk saturation redirects consumer trial toward sesame-derived alternatives in organic retail channels. EFSA novel food assessments apply stringent digestibility documentation for protein isolates. Berlin and Hamburg specialty coffee chains drive chocolate SKU menu integration, though cocoa cost volatility compresses margins.
United States
Third-wave coffee shops specify barista-grade foaming performance with steam wand calibration for sesame milk viscosity. FDA updated plant-based milk labeling standards reshape shelf placement and nutritional claim permissibility. Skilled food technologists with sesame protein extraction expertise are scarce across manufacturing hubs, constraining production scale-up.
United Kingdom
Health food store chains mandate single-digit ingredient counts, rejecting SKUs with added gums or emulsifiers. EU Organic Regulation certification creates tiered pricing architecture across premium channels. London metropolitan markets concentrate refrigerated bottle purchases among established plant-based trial households.
Netherlands
Specialty grocery buyers prioritize clean-label procurement with native lignan stability formulations. EFSA streamlined assessments accelerate European market entry timelines for sesame protein isolates. Rotterdam and Amsterdam distribution clusters enable shelf-stable Tetra Pack channel expansion into pharmacy and convenience retail.
France
Organic certification premiums command shelf placement in conventional supermarket channels. ANSM and DGCCRF apply national implementation of EU novel food standards with additional labeling scrutiny. Paris Île-de-France anchors flavored SKU trial among Gen Z consumers through vanilla and chocolate extensions.
Sesame Milk Market Competitive Landscape
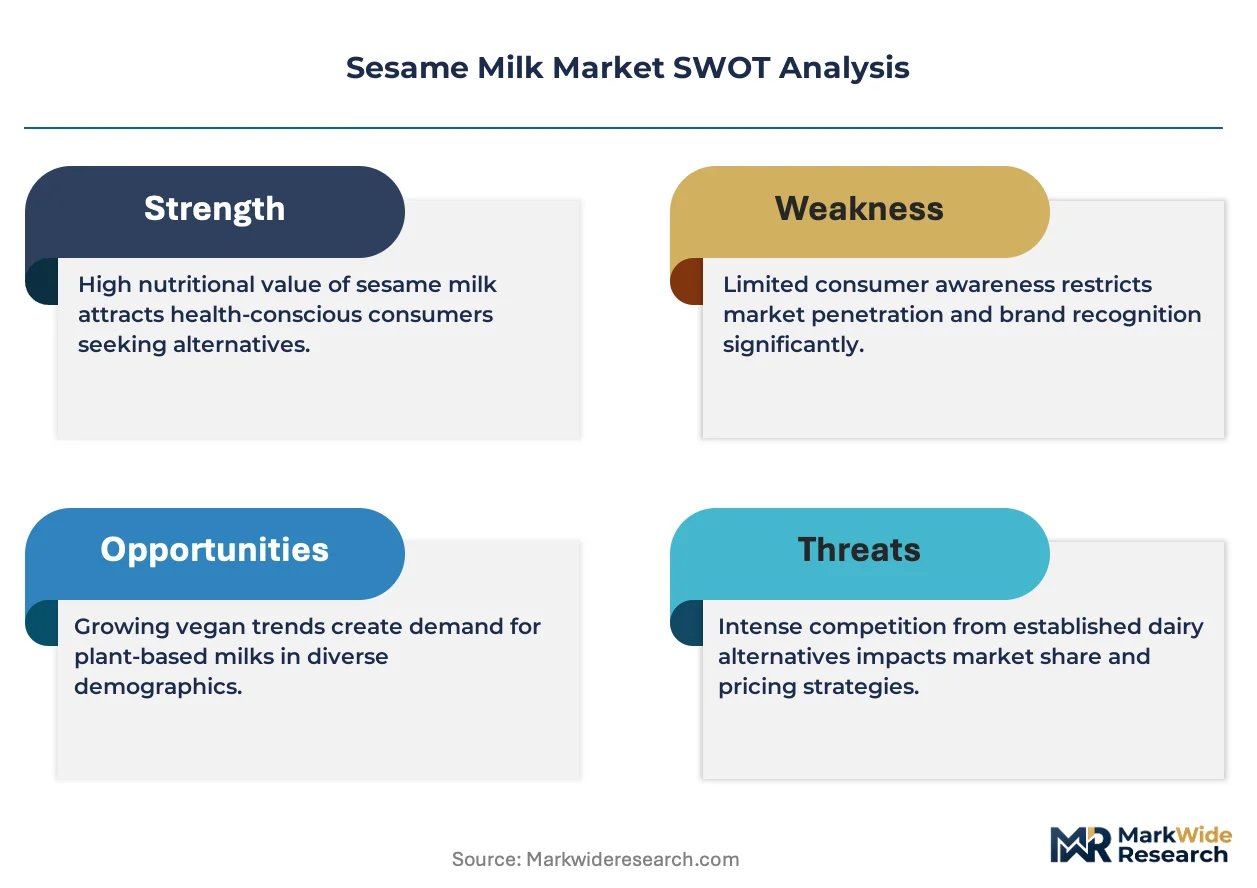
A small set of integrated leaders sits above a broader specialist tier, with supply chain control and extraction technology separating competitive positions. The category rewards dedicated sesame sourcing and patented processing methods. Three archetypes dominate: vertically integrated seed-to-beverage operators, diversified plant-based portfolio holders, and clean-label technology licensors. Capacity expansion and strategic portfolio diversification represent the primary competitive moves as brands position for regulatory compliance thresholds.
Within the integrated supply chain archetype, Hope & Sesame and Sesamilk Foods Co., Ltd exemplify seed-to-beverage control. Califia Farms occupies a position among diversified plant-based portfolio holders extending into sesame R&D. Elmhurst 1925 anchors the clean-label technology tier with patented milling expertise applied to sesame processing.
| Leading Market Players |
|---|
| Hope & Sesame |
| Sesamilk Foods Co., Ltd |
| Ecomil |
| Elmhurst 1925 |
| So Delicious Dairy Free |
| Califia Farms |
| Alpro |
| Pacific Foods |
| Good Karma Foods |
| Others |
Value Network & Pricing Analysis
Ninety-day procurement lead times for specialized homogenization equipment compress margin flexibility across North American manufacturing hubs, tethering pricing power to equipment availability and locking smaller processors into contract manufacturing arrangements. German organic retail channels command shelf placement premiums through USDA National Organic Program and EU Organic Regulation certification tiers, while Tetra Pack formats in pharmacy and convenience channels trade at lower per-unit margins but anchor volume stability.
Pricing Analysis
German metropolitan markets exhibit the widest price spreads between refrigerated bottle premiums and shelf-stable Tetra Pack baselines, with Berlin and Hamburg specialty grocers extracting certification-driven markups. Three-tier pricing structure across premium organic, standard conventional, and private-label economy levels stratifies consumer access, with vanilla and chocolate flavored SKUs capturing the steepest premium multiples. Cost compression in unsweetened variants intensifies as private-label oat milk alternatives force protein fortification investments. Food manufacturers sourcing industrial sesame protein isolates demonstrate lowest price sensitivity due to long-term offtake contracts, while household trial purchasers in urban centers show highest elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Rotterdam and Hamburg elevate inbound logistics costs for sesame seed processors dependent on Ethiopian, Sudanese, and Indian origin crops. Dedicated sesame supply chains cluster in Ethiopia's Humera region, Sudan's Gedaref state, and India's Gujarat and Rajasthan, exposing processors to climate volatility and geopolitical friction in the Horn of Africa. HydroRelease milling equipment and aseptic Tetra Pack filling lines constitute critical capital dependencies with extended procurement backlogs. Single-source vulnerability concentrates in Ethiopian white sesame grades prized for clean-label positioning. Distribution runs through German health food store chains and US third-wave coffee equipment co-development channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sesame milk market is cycling through a recovery phase as oat milk saturation in German organic retail redirects consumer trial budgets toward alternative plant proteins, with specialty coffee channel expansion providing cyclical momentum through equipment co-development investments.
For Market Incumbents: Consolidate control over dedicated sesame supply chains through backward integration into Ethiopian and Indian origin regions, securing grade consistency for clean-label positioning. Lock in long-term homogenization equipment procurement contracts to preempt capacity constraints as FDA protein content thresholds crystallize. Defend against HydroRelease patent thicket barriers by licensing clean-label milling technology or acquiring specialist processors with established IP portfolios.
For New Entrants and Emerging Players: Anchor in the flavored SKU segment targeting Gen Z trial through vanilla and chocolate extensions, where margin pools remain underexploited relative to unsweetened baselines. Exploit pharmacy and convenience channel white space with shelf-stable Tetra Pack formats currently underserved by refrigerated alternatives. Pursue direct-to-consumer subscription models in US metropolitan markets with established plant-based consumption patterns to bypass conventional retail slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barista-grade processing capacity as equipment manufacturers calibrate steam wands for sesame milk viscosity profiles. Five-to-ten year viability favors vertically integrated seed-to-beverage operators with captive supply chains and patented extraction capabilities. Acquisition target archetype: mid-cap specialists with EFSA novel food approval traction and German health food store shelf placement. Signal to monitor: FDA final rulemaking on protein equivalence claims, which would trigger speculative fortification investment waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Regions | Captive supply from Ethiopia's Humera region secures grade consistency for clean-label procurement mandates. |
| EFSA Novel Food Pre-Approval Investment | Clinical trial commissioning ahead of sesame protein isolate submissions accelerates European market entry timelines. |
| Equipment Co-Development with Coffee Chains | Steam wand calibration for sesame milk viscosity profiles locks in third-wave coffee channel specification. |
| Flavored SKU Pipeline Expansion | Vanilla and chocolate extensions target Gen Z trial with sensory differentiation beyond unsweetened baselines. |
| Tetra Pack Channel Diversification | Shelf-stable formats enable pharmacy and convenience placement without cold chain dependency. |
Research Methodology
Operator-level perspectives from food technology R&D directors, specialty coffee chain procurement managers, German health food store category buyers, and sesame protein extraction specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA guidance documents, EFSA novel food assessment records, USDA National Organic Program certification databases, and German organic retail audit data. Bottom-up volume modeling across product type, end user, packaging format, and distribution channel segments triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across protein content threshold scenarios, equipment procurement delay assumptions, and origin region climate volatility inputs. The analytical framework modeled unsweetened, flavored, original, and organic product types; cafe, household, restaurant, and food manufacturer end users; Tetra Pack, bottle, can, and pouch packaging formats; and health food store, supermarket, online, and convenience store channels. CAGRs derived from segment-level volume trajectories and price realization trends, with barista-grade foaming performance specifications and EFSA approval timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of steady FDA rulemaking progression and sustained German oat milk fatigue; material deviation would warrant model refresh. Forecasts embed assumptions regarding EFSA streamlined assessment continuity and specialty coffee equipment co-development momentum. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Low Fat Coconut Milk Market