
 Middle East and Africa Compressed Natural Gas Dispenser Market | 2026-2036
Middle East and Africa Compressed Natural Gas Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Compressed Natural Gas Dispenser Market Insights
Market Context
Egypt's Suez Canal Economic Zone is fragmenting legacy fuel infrastructure assumptions as CNG corridors take shape. Censtar Science & Technology Corp anchors its regional position through manufacturing scale advantages across North African markets. Dover Fuelling Solutions competes on technology leadership in high-flow dispensing systems suited to heavy-duty fleet applications. Gilbarco Veeder-Root extends its installed base through channel control over established petroleum retail networks converting to dual-fuel service.
Technical Definition and Segment Structure
A compressed natural gas dispenser is a pressure-rated fueling terminal engineered to deliver methane-based fuel at 200-250 bar through calibrated mass-flow meters into vehicle storage cylinders. Fast fill dispensers dominate current revenue pools where transit agencies require throughput parity with conventional diesel, while time fill systems occupy fleet depot applications where overnight refueling cycles eliminate compression bottlenecks. Among end users, public transportation agencies represent the most mature procurement channel, whereas industrial users represent the fastest-growing segment as manufacturing facilities seek captive fuel solutions independent of grid volatility.
Regulatory Framework and Outlook
Egypt's Ministry of Petroleum and Mineral Resources enforces CNG conversion mandates for state vehicle fleets, while South Africa's Department of Mineral Resources and Energy advances gas master plan implementation that shapes dispenser certification requirements. The region's national standards bodies coordinate with ISO 14469 refueling nozzle specifications to ensure equipment interoperability across cross-border transport routes. Stakeholders must monitor how Gulf Cooperation Council harmonization efforts on gas quality specifications reshape equipment procurement criteria and aftermarket service obligations.
Market Dynamics
Egypt's state fleet conversion mandates are compressing procurement timelines and forcing dispenser manufacturers to localize assembly capacity ahead of domestic content requirements.
Growth Catalysts
- Petroleum Regulator Frameworks:Nigeria's domestic gas utilization policies create direct procurement obligations for downstream infrastructure, accelerating dispenser deployment at transport hubs.
- Fleet Operator Commitments:South African logistics operators are binding multi-year fuel diversification contracts that lock in CNG corridor investments across the Cape-Durban freight axis.
- Suez Canal Industrial Zones:Manufacturing clusters adjacent to Egypt's canal corridor are installing captive refueling infrastructure to insulate operations from grid instability.
Market Restraints
- Compression Equipment Import Dependence:High-pressure compressor assemblies concentrate in European and East Asian supply bases, exposing projects to currency volatility and extended lead times.
- Liquefied Natural Gas Competition:LNG bunkering infrastructure at South African ports diverts capital from CNG dispenser networks targeting overlapping heavy-duty segments.
- Gas Quality Specification Friction:Gulf Cooperation Council harmonization delays on methane purity standards force manufacturers to maintain multiple certification tracks for cross-border equipment.
Strategic Opportunities
- Ethiopia Transport Corridors:The Addis Ababa-Djibouti rail and road links remain unserved by organized CNG infrastructure, presenting first-mover positioning for depot-based time-fill systems.
- Dual-Fuel Retrofit Integration:Convergence of diesel-CNG conversion kits with smart dispenser protocols enables unified fleet management platforms that captive fuel users seek.
- Morocco Green Hydrogen Pivot:The country's renewable gas blending mandates will require dispenser architecture capable of handling variable methane-hydrogen mixtures.
Industry Challenges
- Pressure Systems Certification Bottlenecks:ISO 14469 nozzle compliance testing lacks accredited facilities within the region, forcing manufacturers to ship prototypes to European laboratories.
- Legacy Petroleum Network Conversion Complexity:Established retail operators resist site reconfiguration for CNG islands due to petroleum supply contract lock-ins and space constraints at urban stations.
Report Scope
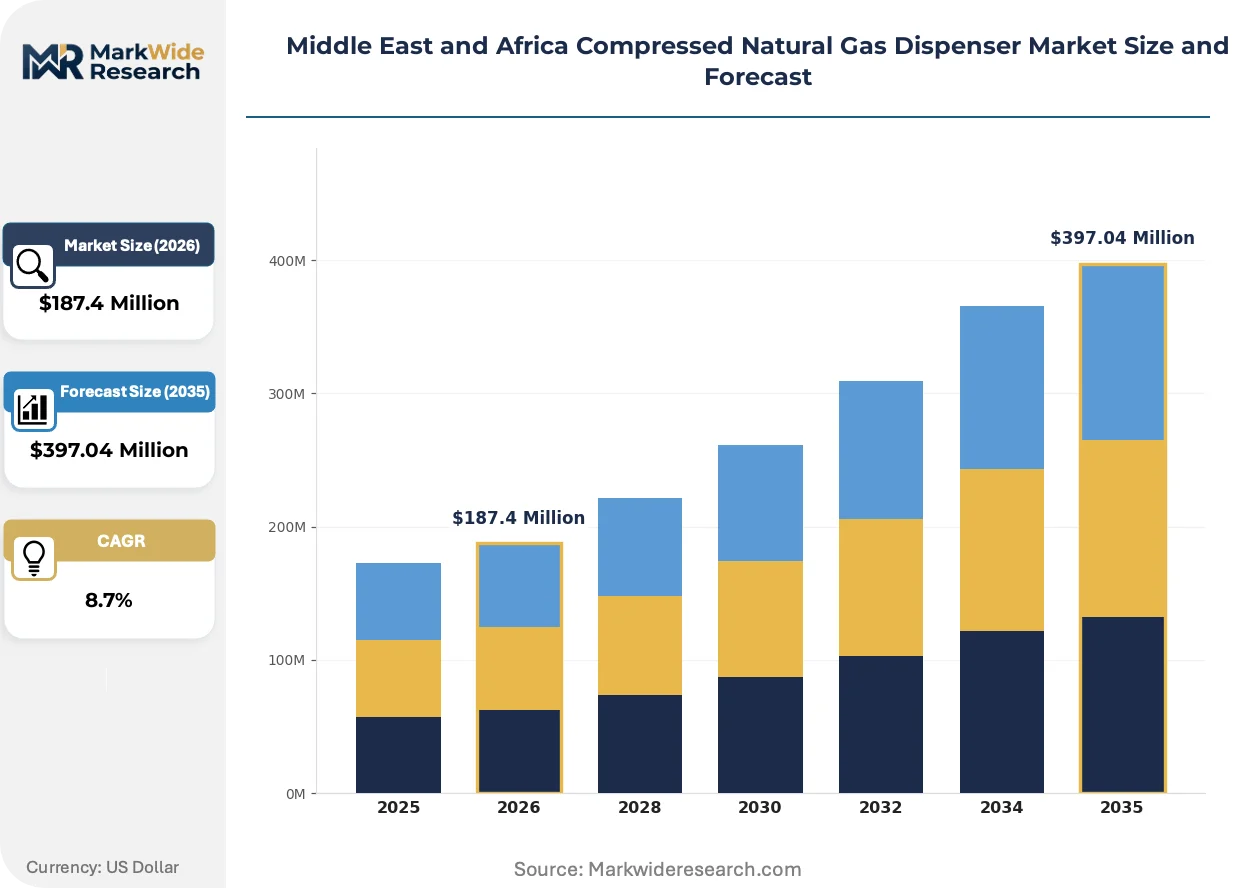
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Compressed Natural Gas Dispenser Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time Fill Dispensers, Fast Fill Dispensers, Bi-Fuel Dispensers, Portable Dispensers End User: Public Transportation, Gas Utilities, Industrial Users, Fleet Operators Installation Type: On-Site Installation, Mobile Installation, Permanent Installation, Temporary Installation Distribution Channel: Direct Sales, Retail Sales, Online Sales, Distributors |
| Companies Covered | Emerson Electric Co, IHI Corporation, Censtar Science & Technology Corp, Chart Industries, Inc, Gilbarco Veeder-Root, Tatsuno Corporation, Landi Renzo S.p.A, Dover Fuelling Solutions, FTI Group Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Compressed Natural Gas Dispenser Market Trends and Innovations
Dispenser architecture is pivoting from mechanical metering to integrated data platforms that enable predictive maintenance and real-time fuel quality verification across distributed fleets.
Mass-flow meter technology is digitizing transaction accuracy and diagnostic transparency. Transit agencies in Egypt's Greater Cairo region are specifying dispensers with embedded cellular modems for remote calibration monitoring. This connectivity layer is digitizing service intervals and compressing warranty claim resolution from weeks to days.
South Africa's Department of Mineral Resources and Energy is enforcing gas master plan certification timelines that synchronize with equipment procurement cycles. Manufacturers must pre-qualify dispensers against evolving pressure vessel standards before tender participation. Heavy-duty fleet operators are responding by consolidating procurement around suppliers with established local technical service presence.
Service contract unbundling is fragmenting traditional vendor relationships. Fleet operators in Nigeria's Lagos-Ibadan corridor are separating dispenser hardware acquisition from aftermarket maintenance, sourcing compression and calibration services from independent providers. This disaggregation is most visible among cement and mining transport fleets with in-house mechanical capabilities.
Middle East and Africa Compressed Natural Gas Dispenser Market Segmentation
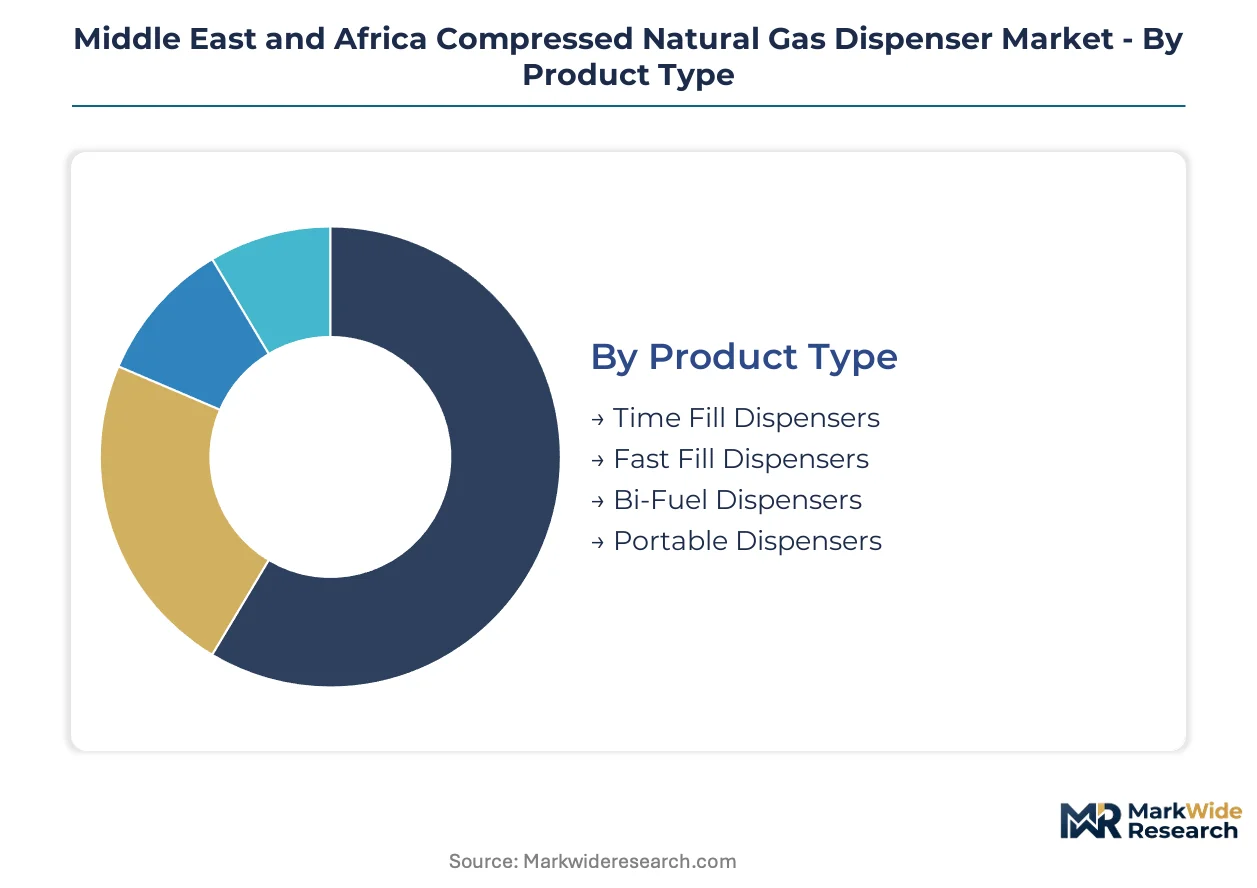
Segmentation in the Middle East and Africa CNG dispenser market reveals how procurement patterns diverge between transit agencies demanding throughput velocity and industrial users prioritizing captive fuel security. Equipment specifications, installation permanence, and channel economics each reshape vendor positioning across Egypt's state fleet programs and South Africa's logistics corridors.
Product Type:
Cost tier differentiation separates depot-based systems from high-throughput terminals capable of matching diesel refueling velocity.
- Time Fill Dispensers:These systems deliver fuel at lower pressure rates over extended cycles, typically 6-8 hours, suited to overnight fleet depot operations. Demand concentrates in Nigeria's cement transport corridors where Lagos-Ibadan fleet operators install captive infrastructure to bypass compression bottlenecks.
- Fast Fill Dispensers:Engineered for 3-5 minute refueling cycles through high-pressure storage cascades, these terminals replicate conventional fueling throughput. Egypt's Greater Cairo transit agencies specify these systems for state bus fleets subject to Ministry of Petroleum conversion mandates.
- Bi-Fuel Dispensers:Dual-nozzle architecture accommodates simultaneous gasoline and CNG dispensing at converted petroleum retail sites.
- Portable Dispensers:Skid-mounted mobile units serve temporary construction camps and mining operations across remote African transport corridors.
Fast fill dispensers command the established base. The steepest expansion runs through time fill systems in captive industrial applications.
End User:
Application maturity varies sharply between subsidized public transit procurement and self-financed industrial fuel switching.
- Public Transportation:State-owned bus and taxi fleets drive volume procurement through centralized tender processes. Egypt's Suez Canal Economic Zone transit links anchor regional demand as authorities convert diesel fleets under enforced mandates.
- Industrial Users:Manufacturing facilities adjacent to Egypt's canal corridor install captive refueling to insulate operations from grid instability. This segment gains share fastest as energy-intensive industries seek fuel cost predictability independent of petroleum price volatility.
- Fleet Operators:South African logistics operators binding multi-year diversification contracts across the Cape-Durban freight axis.
- Gas Utilities:Distribution companies extending pipeline networks into transport fueling infrastructure.
Public transportation commands the established base. The steepest expansion runs through industrial users deploying captive fuel solutions.
Installation Type:
Permanence requirements reflect asset ownership structures and land tenure security across the region's varied commercial environments.
- Permanent Installation:Fixed concrete foundations with buried high-pressure piping and dedicated electrical infrastructure. Egypt's state fleet conversion programs require this specification for warranty compliance and safety certification.
- On-Site Installation:Integrated compression and dispensing systems deployed at fleet depots with dedicated maintenance bays. South African mining transport operators favor this configuration for 24-hour operational control.
- Mobile Installation:Trailer-mounted systems repositioned across construction phases or seasonal agricultural harvests.
- Temporary Installation:Short-term leased equipment for pilot programs and route feasibility studies.
Permanent installation commands the established base. The steepest expansion runs through on-site configurations in heavy-duty fleet depots.
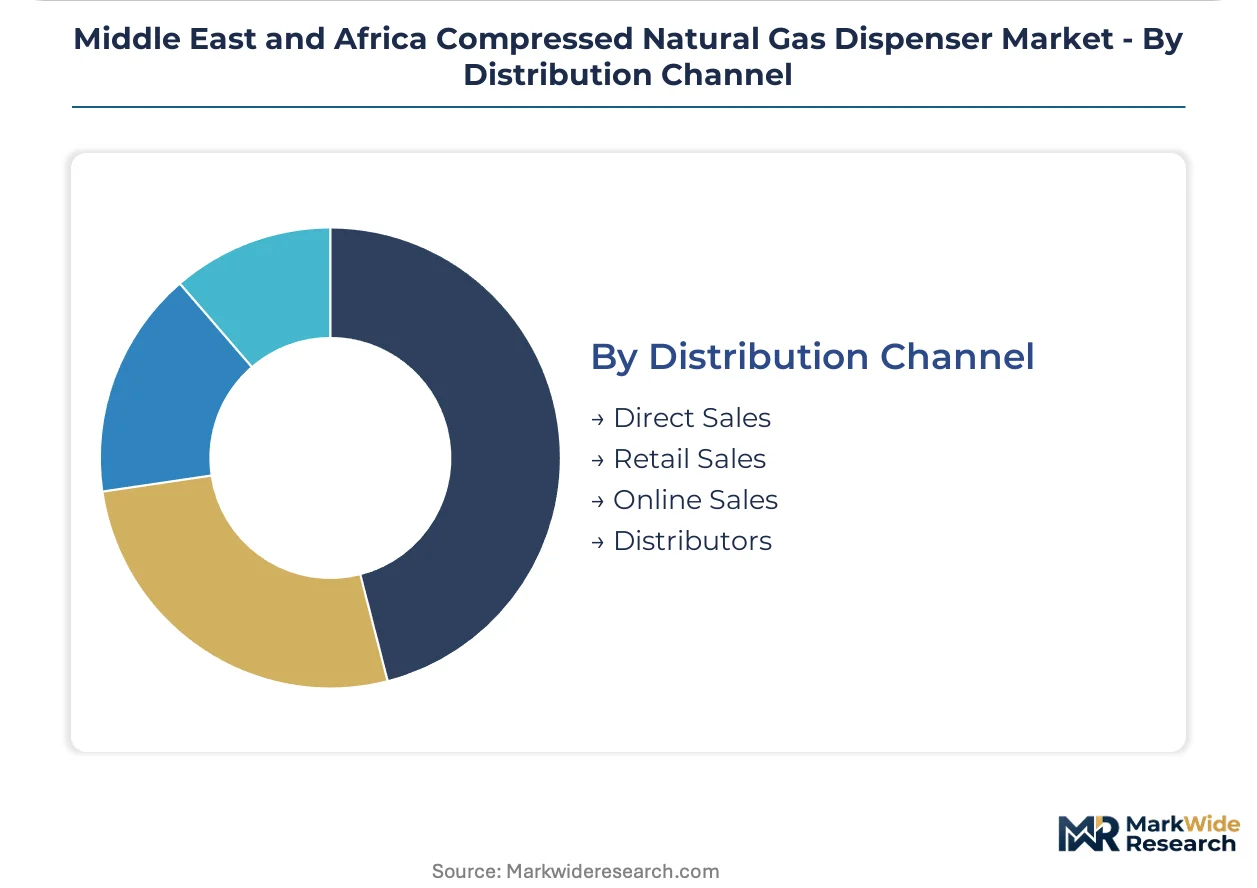
Distribution Channel:
Channel economics fragment as fleet operators unbundle hardware acquisition from aftermarket service obligations.
- Direct Sales:Manufacturer-to-operator contracts for large fleet deployments with integrated service agreements. Egypt's Ministry of Petroleum tenders require direct vendor qualification against domestic content thresholds.
- Distributors:Regional stocking and technical service networks covering multiple countries. These intermediaries dominate in markets lacking accredited ISO 14469 testing facilities.
- Retail Sales:Petroleum equipment dealers converting legacy pump installations to dual-fuel service.
- Online Sales:Digital procurement platforms for replacement components and calibration equipment.
Direct sales commands the established base. The steepest expansion runs through distributors building technical service presence across fragmented national markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates where state conversion mandates intersect with industrial corridor development. Egypt's Suez Canal zone and South Africa's freight axes anchor near-term deployment volumes. Regulatory fragmentation across national gas quality standards forces manufacturers to maintain multiple certification tracks.
Egypt
Transit agencies in Greater Cairo drive fast-fill dispenser procurement under Ministry of Petroleum fleet conversion mandates. The country's petroleum regulator enforces domestic content thresholds that accelerate local assembly partnerships. Manufacturing clusters adjacent to the Suez Canal Economic Zone install captive refueling infrastructure to isolate operations from grid instability.
South Africa
Logistics operators binding multi-year fuel diversification contracts lock in CNG corridor investments across the Cape-Durban freight axis. The Department of Mineral Resources and Energy advances gas master plan implementation that shapes dispenser certification timelines. Mining transport operators in the Northern Cape and Mpumalanga favor on-site depot configurations for 24-hour operational control.
Nigeria
Cement and mining transport fleets in the Lagos-Ibadan corridor deploy time-fill systems to bypass compression bottlenecks at transport hubs. The country's petroleum regulator has advanced domestic gas utilization frameworks that create direct procurement obligations for downstream infrastructure. Fleet operators with in-house mechanical capabilities are unbundling hardware acquisition from aftermarket maintenance services.
Morocco
Renewable gas blending mandates will require dispenser architecture capable of handling variable methane-hydrogen mixtures. The country's energy transition programs prioritize transport sector decarbonization through alternative fuel corridors. Industrial zones near Casablanca and Tangier-Med port complex are evaluating pilot installations for captive fleet applications.
Ethiopia
The Addis Ababa-Djibouti rail and road links remain unserved by organized CNG infrastructure, presenting first-mover positioning for depot-based time-fill systems. The country's transport corridor development programs prioritize freight efficiency improvements. Construction and agricultural seasonal demand patterns favor mobile and temporary installation configurations.
Middle East and Africa Compressed Natural Gas Dispenser Market Competitive Landscape
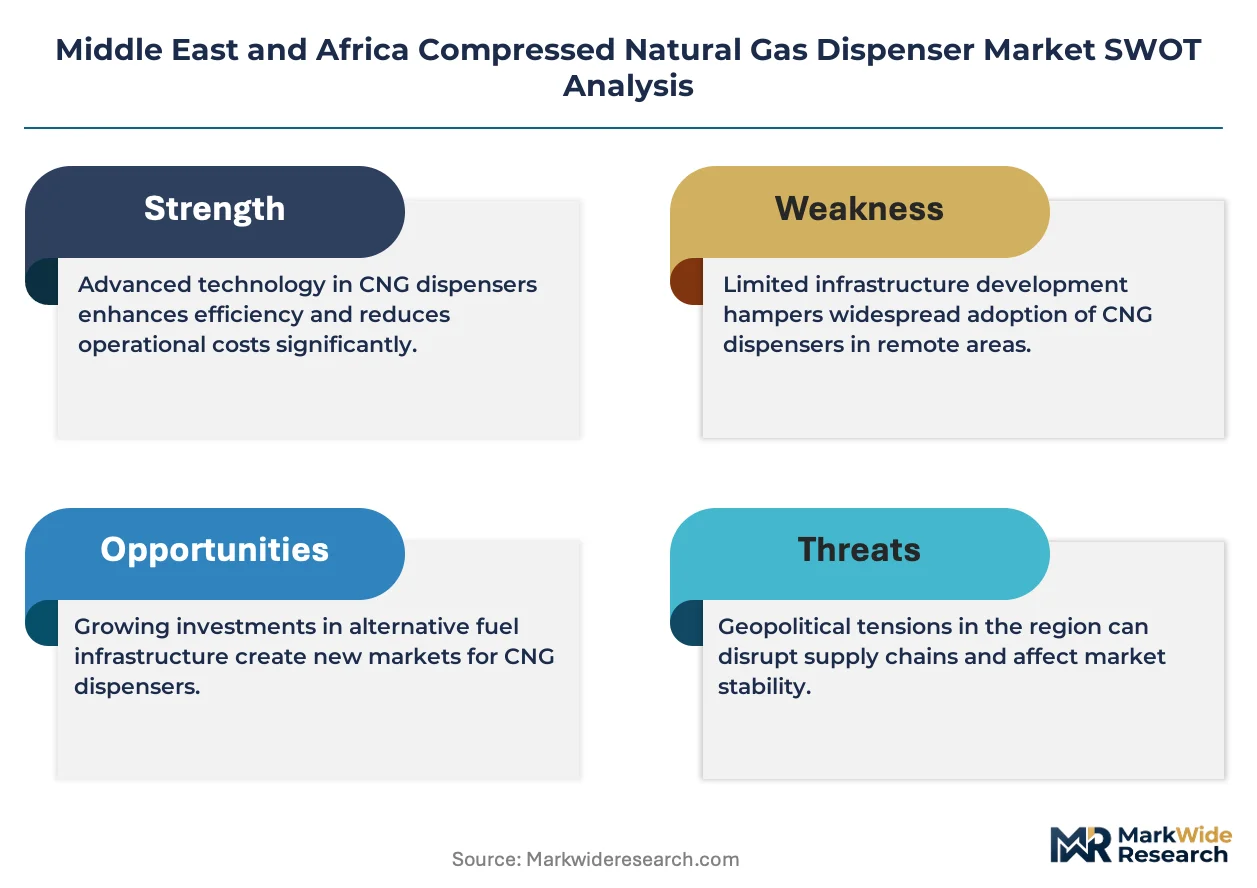
Scale-driven manufacturers and technology-specialized system integrators split the market across divergent procurement channels. State fleet tenders favor vendors with localized assembly capacity and established technical service networks. Industrial captive fuel users prioritize equipment interoperability and predictive maintenance platforms. Consolidation pressure intensifies as certification complexity and domestic content requirements raise barriers for pure import-dependent suppliers.
Among Asia-Pacific headquartered conglomerates with diversified energy portfolios, IHI Corporation and Tatsuno Corporation exemplify the integrated industrial archetype that leverages cross-sector compression expertise. Within the specialized fueling infrastructure tier, Censtar Science & Technology Corp and Dover Fuelling Solutions occupy positions shaped by manufacturing scale advantages and technology leadership in high-flow systems respectively. Gilbarco Veeder-Root represents the incumbent petroleum equipment channel seeking conversion of established retail networks to dual-fuel service.
| Leading Market Players |
|---|
| Emerson Electric Co |
| IHI Corporation |
| Censtar Science & Technology Corp |
| Chart Industries, Inc |
| Gilbarco Veeder-Root |
| Tatsuno Corporation |
| Landi Renzo S.p.A |
| Dover Fuelling Solutions |
| FTI Group Ltd |
| Others |
Pricing and Supply Chain Analysis
European and East Asian compressor assembly concentration funnels margin capture toward high-pressure component manufacturers, while downstream dispenser integrators in Egypt and South Africa compete on localization credits and service bundling.
Pricing Analysis
Egypt's domestic content thresholds dictate the pricing tier structure across equipment procurement. Pricing stratifies across premium-certified, standard-compliant, and economy-unbundled tiers based on ISO 14469 nozzle certification level and after-sales service bundling. Cost compression in the economy tier is intensifying because fleet operators in Nigeria's Lagos-Ibadan corridor are separating hardware acquisition from maintenance contracts. Industrial captive fuel users show the lowest price sensitivity, prioritizing predictive maintenance platforms over unit cost.
Supply Chain Analysis
Extended payment terms from South African mining transport operators are reshaping supplier working capital requirements across the Cape-Durban freight axis. High-pressure compressor assemblies draw from Germany, China, and South Korea, while mass-flow meter electronics feed from Japanese and Taiwanese component bases. Single-source vulnerability concentrates in European-certified pressure vessel testing facilities. Distribution runs through regional distributors with accredited technical service networks covering multiple national markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is crossing into platform economics as smart dispenser protocols enable unified fleet management systems that lock in aftermarket revenue streams through predictive maintenance subscriptions.
For Market Incumbents: Harden technical service presence in Egypt before domestic content thresholds tighten procurement qualification. Acquire or partner with local calibration facilities to bypass ISO 14469 testing bottlenecks. Compress warranty resolution timelines through embedded cellular diagnostics to defend against unbundling pressure from fleet operators with in-house mechanical capabilities.
For New Entrants and Emerging Players: Ethiopia's Addis Ababa-Djibouti transport corridor represents the most penetrable entry point for depot-based time-fill systems with minimal incumbent saturation. Morocco's renewable gas blending mandates create specification white-space for hydrogen-capable dispenser architecture. Lead with mobile installation configurations to bypass permanent infrastructure capital intensity.
For Investors and Strategic Acquirers: Capital is best deployed toward distributors with established regional technical service networks and pre-qualified certification tracks across multiple national standards. The five-to-ten year viability window favors asset-light service platforms over manufacturing-dependent suppliers exposed to compressor import volatility. Monitor Gulf Cooperation Council methane purity harmonization progress as the signal for cross-border equipment standardization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership | Egypt's domestic content thresholds require local assembly capacity for tender participation. |
| Certification Pre-Qualification | South Africa's gas master plan timelines synchronize equipment procurement with evolving pressure vessel standards. |
| Smart Dispenser Integration | Embedded cellular modems enable predictive maintenance platforms that transit agencies in Greater Cairo specify. |
| Service Contract Unbundling | Nigerian fleet operators with in-house capabilities separate hardware acquisition from aftermarket maintenance. |
| Hydrogen-Ready Architecture | Morocco's renewable gas blending mandates require variable methane-hydrogen mixture handling. |
Research Methodology
A spread of perspectives from fleet operations managers, petroleum regulator technical officers, dispenser manufacturer sales directors, and aftermarket service technicians converged on the working assumptions. Primary field engagement combined with secondary validation from national gas master plan documentation, ISO certification registry data, Suez Canal Economic Zone infrastructure disclosures, and customs import records for compression equipment. Bottom-up deployment tracking across Egypt, South Africa, Nigeria, Morocco, and Ethiopia triangulated against top-down market sizing.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included dispenser product type, end-user application, installation permanence, and distribution channel structure. CAGRs derived from equipment procurement cycle analysis and fleet conversion mandate timelines. Industry-specific inputs incorporated domestic content threshold implementation schedules and Gulf Cooperation Council gas quality harmonization progress.
Practitioners should monitor regulatory enforcement consistency, currency volatility in compressor-importing economies, and hydrogen blending mandate acceleration for early signals. Forecasts reflect documented assumptions about state fleet conversion pace and industrial corridor development timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Mobile Fuel Delivery Market
Fuels
Tire Derived Fuel Market
Fuels
Biobutanol Market
Fuels
LPG Gas Cylinder Market
Fuels
North America Bunker Fuel Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Singapore Bunker Fuel Market
Fuels
North America Aviation Fuel Market
Fuels
North America Wood Pellet Market
Fuels
Global Butane Gas Cartridges Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
India Bunker Fuel Market
Fuels
China LNG Bunkering Market
Fuels
Heavy Fuel Oil Market
Fuels
High Octane Racing Fuel Market
Fuels
Oil Dispenser Market