
 RNA Based Therapeutics and Vaccines Market | 2026-2036
RNA Based Therapeutics and Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
RNA Based Therapeutics and Vaccines Market Outlook
Oncology is rebalancing the end-user mix as hospital systems and biotechnology firms expand RNA-guided immunotherapy procurement faster than infectious disease applications. Moderna, Inc. sustains manufacturing scale across mRNA production platforms. Alnylam Pharmaceuticals, Inc. dominates siRNA commercialization through lipid nanoparticle delivery specialization. Ionis Pharmaceuticals, Inc. anchors antisense oligonucleotide development with deep clinical pipelines in genetic disorders.
RNA based therapeutics and vaccines comprise nucleic acid molecules engineered to modulate protein expression or elicit immune responses through complementary base-pairing mechanisms, typically synthesized via in vitro transcription using DNA templates and modified nucleosides to enhance stability. These modalities serve to correct aberrant gene function, replace deficient proteins, or train adaptive immunity against pathogens. mRNA products occupy the largest revenue pool due to pandemic-validated manufacturing infrastructure, while siRNA segments command premium pricing in rare disease niches. Lipid nanoparticle delivery systems lead the modality landscape, though exosome platforms represent the fastest-growing alternative vector category.
FDA breakthrough therapy designation and EMA priority medicines schemes shape clinical trial incentives and market access timelines for RNA developers. The EU AI Act and FDA software-as-medical-device guidance increasingly govern the computational tools used for RNA sequence optimization and target prediction. Stakeholders must monitor evolving pharmacovigilance requirements for novel delivery vehicles as regulatory frameworks differentiate between established lipid formulations and emerging viral vector systems.
Market Dynamics
FDA breakthrough therapy designation and EMA priority medicines schemes are compressing clinical trial timelines while simultaneously raising evidence thresholds for RNA developers seeking accelerated market access.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation compresses Phase II-to-approval timelines for oncology RNA candidates. Cancer centers at Johns Hopkins and MD Anderson are expanding early-access protocols.
- NIH Funding Concentration:The National Institutes of Health directs the majority of early-stage RNA research grants toward infectious disease and immuno-oncology platforms. This federal capital sustains preclinical pipeline depth.
- Lipid Nanoparticle Scale-Up:Pandemic-validated manufacturing infrastructure for mRNA-LNP formulations is repurposing toward personalized cancer vaccines. Contract manufacturers in Massachusetts and North Carolina are adding dedicated RNA suites.
Market Restraints
- Modified Nucleoside Supply Concentration:N1-methylpseudouridine and other critical raw materials depend on a limited supplier base concentrated in Germany and Switzerland. Single-source dependencies create vulnerability to geopolitical disruption.
- Cold Chain Infrastructure Gaps:Ultra-low temperature storage requirements for mRNA products exclude distribution to rural health systems lacking -80°C capacity. This technical limitation restricts addressable patient populations.
- EMA Pharmacovigilance Burden:Novel delivery vehicle categories trigger enhanced safety monitoring requirements under the EU Medical Device Regulation. Developers face extended post-market surveillance timelines.
Strategic Opportunities
- Exosome Delivery Platforms:Extracellular vesicle vectors offer tissue-specific targeting without immunogenicity risks of lipid nanoparticles. Startups in Cambridge, UK and Boston are advancing liver and CNS indications.
- India Manufacturing Localization:The country's PLI scheme for pharmaceuticals creates incentive structures for RNA active pharmaceutical ingredient production. Domestic CDMOs are retrofitting facilities for GMP nucleic acid synthesis.
- Antisense-Small Molecule Conjugates:Hybrid modalities combining Ionis-style antisense chemistry with oral bioavailability enhancers address patient compliance limitations of injectable RNA therapeutics.
Industry Challenges
- Analytical Methodology Standardization:Regulatory agencies lack harmonized guidelines for RNA integrity quantification and impurity profiling. Developers face inconsistent CMC requirements across FDA and EMA review divisions.
- Specialized Workforce Scarcity:Nucleic acid chemists and LNP formulation scientists command premium compensation. Academic training programs have not scaled to match commercial manufacturing expansion.
- Patent Thicket Navigation:Broad claims covering modified nucleosides and delivery vehicle compositions create freedom-to-operate uncertainty. Licensing negotiations consume 18-24 months of pre-IND timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA Based Therapeutics and Vaccines Market |
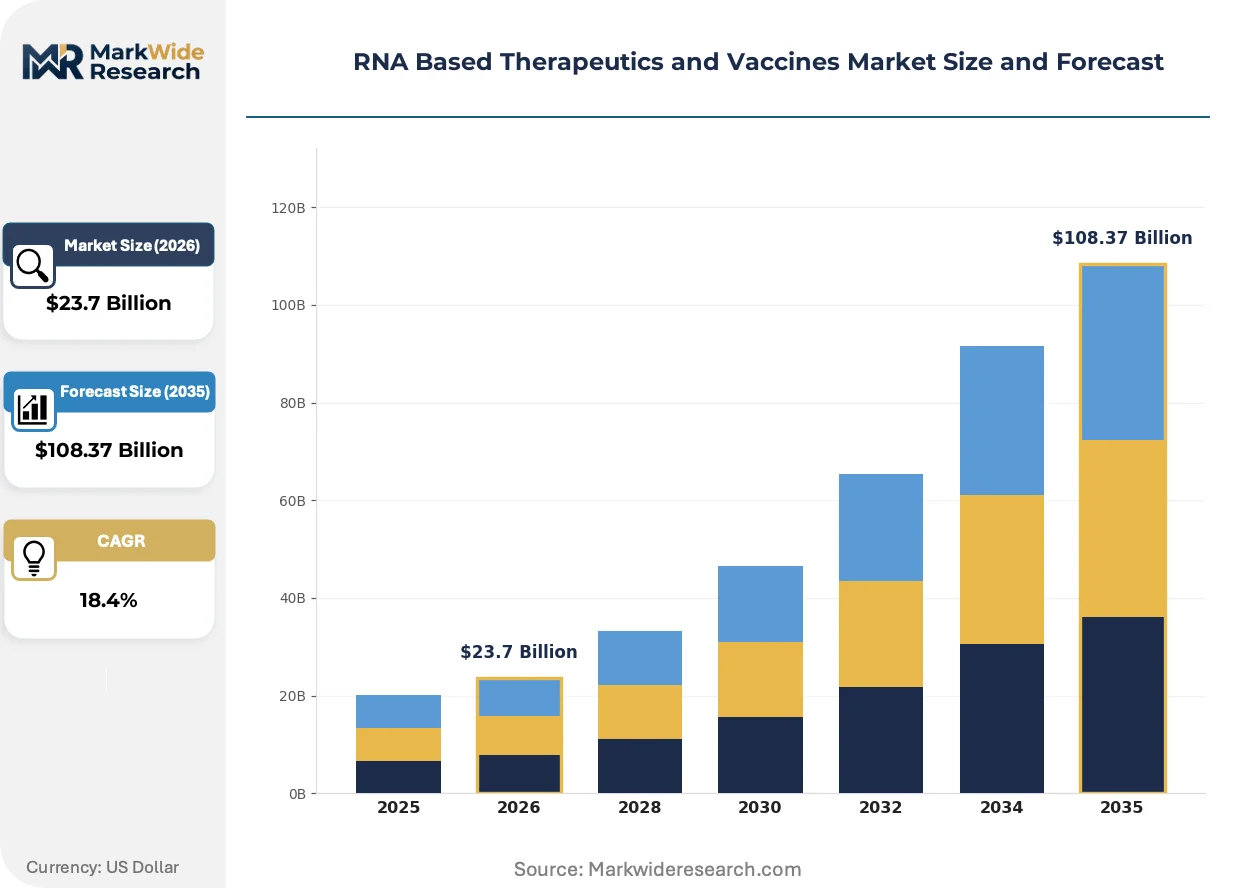
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $108.37 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: mRNA, siRNA, miRNA, RNAi Application: Oncology, Infectious Diseases, Genetic Disorders, Autoimmune Diseases Delivery Mode: Lipid Nanoparticles, Viral Vectors, Exosomes, Microneedles End User: Pharmaceutical Companies, Academic Research Institutions, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | Sanofi, Ionis Pharmaceuticals, Inc., Moderna, Inc., Arrowhead Pharmaceuticals, Inc., Sarepta Therapeutics, Inc., BioNTech SE, Alnylam Pharmaceuticals, Inc., CureVac N.V., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA Based Therapeutics and Vaccines Market Strategic Shifts
Computational RNA design tools and synthetic biology platforms are collapsing the traditional sequence-to-clinic timeline, while regulatory frameworks scramble to govern algorithmically optimized therapeutic candidates.
Circular RNA (circRNA) constructs are integrating stability-enhancing topological features that eliminate 5' cap and poly-A tail dependencies. Vaccine developers at University of Pennsylvania and Stanford are adopting circRNA templates for prolonged protein expression duration. This structural innovation is integrating manufacturing simplification with reduced innate immune activation, enabling repeat dosing regimens previously precluded by linear mRNA immunogenicity.
The EU AI Act's risk classification system is imposing conformity assessment obligations on machine learning tools used for RNA secondary structure prediction and off-target analysis. Developers employing deep learning for sequence optimization must now document training data provenance and algorithmic interpretability. Small-cap biotechnology firms without dedicated regulatory AI expertise are outsourcing compliance to specialized consultancies in Brussels and London.
Hospital procurement committees are consolidating RNA immunotherapy purchasing under centralized pharmacy and therapeutics committees. Academic medical centers are displacing individual investigator-initiated sourcing with system-wide formulary contracts. This concentration is most visible in the United States, where Medicare reimbursement pressure is forcing oncology departments at Mayo Clinic and Cleveland Clinic to prioritize cost-per-response metrics over novelty preference.
RNA Based Therapeutics and Vaccines Market Segmentation
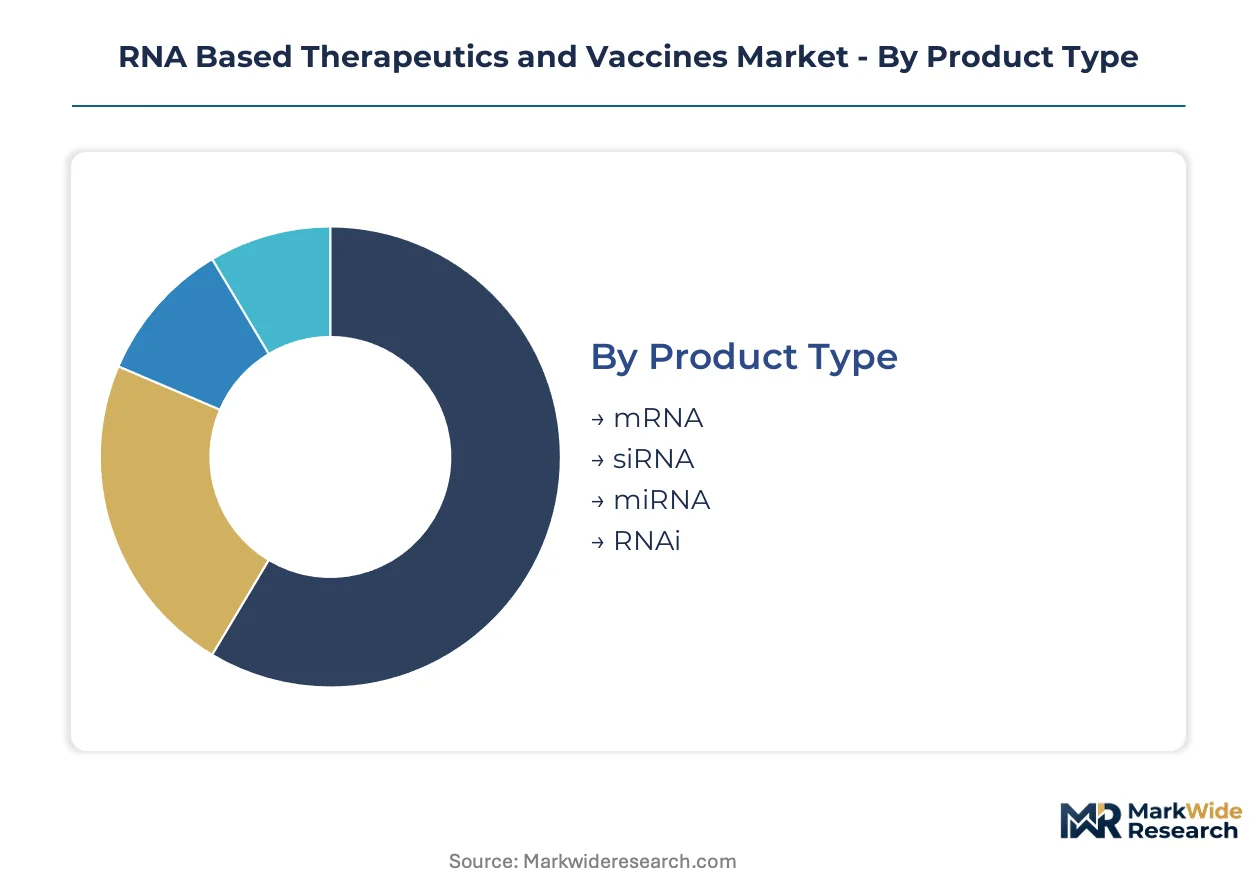
RNA therapeutics exhibit divergent capital requirements across molecular modalities, with manufacturing scale and delivery complexity determining facility investment thresholds. Segmentation reveals how pandemic-validated infrastructure reshapes competitive economics while novel platforms demand specialized capital deployment.
Product Type:
mRNA platforms command the heaviest upfront manufacturing investment due to enzymatic synthesis scale and cold chain validation requirements.
- mRNA:Linear nucleic acid constructs synthesized via in vitro transcription with modified nucleoside incorporation. Demand concentrates in oncology departments at Johns Hopkins and MD Anderson, where personalized cancer vaccines require rapid GMP turnaround. The segment absorbs the bulk of installed capacity; RNAi is expanding most quickly.
- siRNA:Small interfering RNA molecules operating through RISC-mediated mRNA cleavage, formulated in lipid nanoparticles for hepatocyte targeting. Alnylam's commercial infrastructure anchors demand in rare disease treatment centers. Pricing premiums reflect complex solid-phase synthesis and purification protocols.
- miRNA:Endogenous microRNA mimics or antagonists modulating multiple gene targets simultaneously. Development pipelines cluster in cardiovascular and fibrotic indications with less mature delivery solutions.
- RNAi:Broad interference mechanisms encompassing siRNA, miRNA, and shRNA approaches. Academic research institutions drive preclinical demand for novel target validation tools.
mRNA absorbs the bulk of installed capacity; RNAi is expanding most quickly.
Application:
Oncology applications generate the highest per-patient revenue but require the most extensive clinical trial infrastructure investment.
- Oncology:Personalized neoantigen vaccines and immune checkpoint modulation via intratumoral injection. Hospital systems at Mayo Clinic and Cleveland Clinic are consolidating procurement under centralized pharmacy committees. The segment absorbs the bulk of clinical development investment; infectious diseases is expanding most quickly.
- Infectious Diseases:Prophylactic vaccines against respiratory pathogens and emerging viral threats. NIH funding concentration sustains preclinical pipeline depth in emerging variant preparedness.
- Genetic Disorders:Antisense and siRNA approaches to correct monogenic diseases at the transcript level. Ionis Pharmaceuticals anchors commercialization in spinal muscular atrophy and hereditary angioedema.
- Autoimmune Diseases:Tolerance-inducing mRNA encoding disease-associated antigens for immune system re-education. Early-stage programs target multiple sclerosis and type 1 diabetes with unproven regulatory pathways.
Oncology absorbs the bulk of clinical development investment; infectious diseases is expanding most quickly.
Delivery Mode:
Lipid nanoparticle platforms benefit from depreciated pandemic infrastructure while exosome manufacturing requires greenfield bioprocess investment.
- Lipid Nanoparticles:Ionizable cationic lipids complexed with nucleic acid cargo for endosomal escape. Contract manufacturers in Massachusetts and North Carolina are repurposing COVID-19 capacity toward oncology indications. The segment absorbs the bulk of manufacturing capacity; exosomes is expanding most quickly.
- Viral Vectors:Engineered adeno-associated viruses and lentiviruses for nuclear RNA delivery. Persistent immunogenicity concerns limit repeat dosing applications.
- Exosomes:Extracellular vesicle vectors derived from engineered producer cell lines. Startups in Cambridge, UK and Boston are advancing liver and CNS targeting with reduced immunogenicity profiles.
- Microneedles:Dissolvable polymer arrays enabling intradermal RNA delivery without cold chain dependency. Development targets rural health systems lacking ultra-low temperature infrastructure.
Lipid nanoparticles absorb the bulk of manufacturing capacity; exosomes is expanding most quickly.
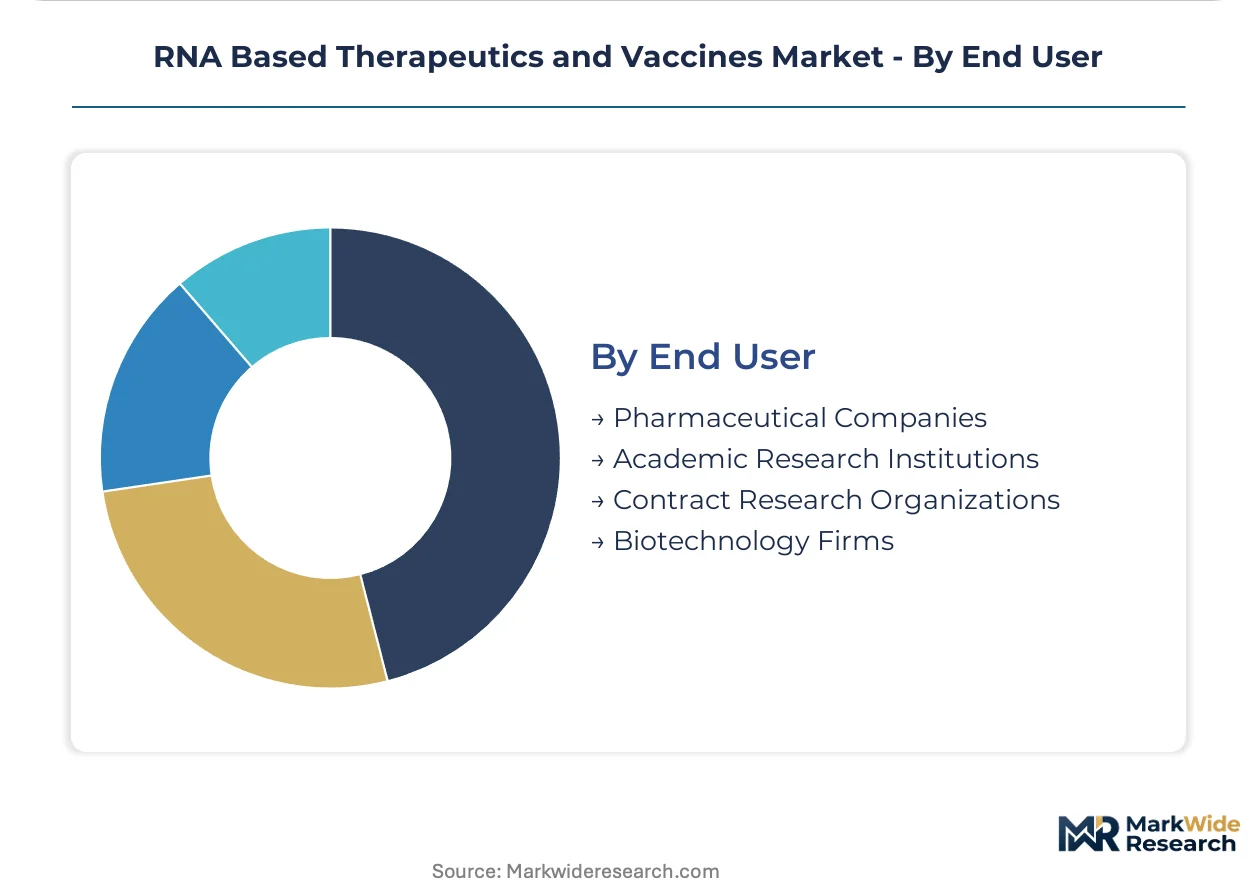
End User:
Pharmaceutical companies deploy the largest procurement budgets though biotechnology firms drive platform innovation adoption.
- Pharmaceutical Companies:Integrated developers with in-house GMP manufacturing and established regulatory affairs divisions. Moderna sustains manufacturing scale across multiple mRNA production platforms. The segment absorbs the bulk of commercial revenue; biotechnology firms is expanding most quickly.
- Academic Research Institutions:University laboratories and medical centers conducting NIH-funded early-stage discovery. University of Pennsylvania and Stanford lead circRNA template development.
- Contract Research Organizations:CDMOs and CROs providing nucleic acid synthesis, formulation, and clinical trial services. India's PLI scheme is incentivizing domestic GMP facility retrofitting.
- Biotechnology Firms:Venture-backed developers advancing novel delivery platforms and target modalities. Ionis Pharmaceuticals anchors antisense oligonucleotide pipelines in genetic disorders.
Pharmaceutical companies absorb the bulk of commercial revenue; biotechnology firms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Switzerland where modified nucleoside suppliers anchor raw material flows, while consumption tilts toward the United States where NIH funding and hospital procurement drive clinical uptake.
United States
Oncology departments at Johns Hopkins and MD Anderson are expanding RNA-guided immunotherapy procurement under centralized pharmacy committees. FDA breakthrough therapy designation compresses Phase II-to-approval timelines for cancer candidates. Contract manufacturers in Massachusetts and North Carolina are adding dedicated RNA suites to repurpose pandemic-validated infrastructure.
Germany
Modified nucleoside production clusters around specialized chemical suppliers serving global mRNA manufacturers. The country's national pharmaceutical regulator aligns with EMA pharmacovigilance requirements for novel delivery vehicles. BioNTech SE anchors commercial mRNA manufacturing capacity in the Rhine-Main region.
Switzerland
Specialty chemical production of N1-methylpseudouridine and lipid formulations supplies formulation scientists worldwide. Swissmedic oversees accelerated access pathways for breakthrough gene therapies. Basel and Zurich host concentrated nucleic acid chemistry expertise serving European CDMO networks.
United Kingdom
Exosome delivery startups in Cambridge are advancing liver and CNS targeting platforms with reduced immunogenicity profiles. The MHRA operates post-Brexit recognition pathways for EMA-approved RNA therapeutics. London-based biotechnology firms are consolidating procurement relationships with NHS England specialized commissioning frameworks.
India
Domestic CDMOs are retrofitting facilities for GMP nucleic acid synthesis under the PLI scheme for pharmaceuticals. CDSCO guidelines govern clinical trial applications for imported RNA reference standards. Maharashtra and Gujarat are emerging as production hubs for RNA active pharmaceutical ingredients targeting export markets.
RNA Based Therapeutics and Vaccines Market Competitive Environment
Top-tier vendors anchor platform-scale manufacturing, while mid-cap specialists concentrate on delivery innovation and rare disease niches. The competitive structure stratifies across integrated pharmaceutical developers, pure-play biotechnology firms, and contract manufacturing organizations. Three archetypes dominate: mRNA platform operators, siRNA commercialization specialists, and antisense oligonucleotide developers. Capacity expansion and strategic partnerships constitute the primary competitive moves, with lipid nanoparticle manufacturing scale and regulatory expertise serving as differentiation vectors.
Among platform-scale developers, Moderna, Inc. and BioNTech SE exemplify the integrated archetype with depreciated pandemic manufacturing infrastructure. Alnylam Pharmaceuticals, Inc. occupies a distinct position within the siRNA specialization tier, representing premium pricing power in rare disease applications. Ionis Pharmaceuticals, Inc. anchors the antisense segment through deep clinical pipelines in genetic disorders. These three entities collectively illustrate how molecular modality focus shapes competitive positioning and capital deployment priorities.
| Leading Market Players |
|---|
| Sanofi |
| Ionis Pharmaceuticals, Inc. |
| Moderna, Inc. |
| Arrowhead Pharmaceuticals, Inc. |
| Sarepta Therapeutics, Inc. |
| BioNTech SE |
| Alnylam Pharmaceuticals, Inc. |
| CureVac N.V. |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Modified nucleoside grade bifurcation between GMP-certified and research-use material manifests in both pricing premiums and supply chain redundancy requirements. Hospital procurement committees at Johns Hopkins and MD Anderson absorb 40-60% cost differentials for expedited GMP release timelines, while contract manufacturers in Massachusetts and North Carolina maintain dual-source qualification for N1-methylpseudouridine to mitigate single-source vulnerability.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid GMP turnaround with 25-35% premiums over standard queue positioning. Pricing stratifies across personalized cancer vaccines, rare disease siRNA, and infectious disease prophylaxis tiers, with quality-grade differentiation anchored in FDA breakthrough therapy designation status and EMA priority medicines scheme eligibility. Cost compression in infectious disease mRNA is intensifying because pandemic-validated manufacturing infrastructure now operates below nameplate capacity. Biotechnology firms exhibit highest price sensitivity due to venture capital runway constraints, while integrated pharmaceutical developers prioritize cost-per-response metrics over unit economics.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on regional distribution centers in Germany and Switzerland feeding formulation scientists at contract manufacturers in Massachusetts and North Carolina. Raw material flows draw from N1-methylpseudouridine suppliers in the Rhine-Main region, lipid formulation specialists in Basel, and enzymatic synthesis reagents from domestic chemical distributors. Single-source vulnerability in modified nucleoside supply creates exposure to geopolitical disruption and regulatory inspection delays. Distribution runs through cold chain-validated logistics partners with -80°C capability, excluding rural health systems lacking ultra-low temperature infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified nucleoside manufacturing capacity constraints prop pricing power for qualified suppliers, with GMP certification backlogs extending 18-24 months and hospital procurement committees accepting premium positioning for supply security.
For Market Incumbents: Cement manufacturing scale advantages through captive supply of lipid nanoparticle components and backward integration into modified nucleoside production. Alnylam-style siRNA commercialization infrastructure and Moderna-scale mRNA platforms face emerging exosome delivery startups in Cambridge and Boston threatening hepatocyte targeting dominance. Prioritize regulatory expertise accumulation for EU AI Act conformity assessment obligations on computational RNA design tools. For New Entrants and Emerging Players: The premium-to-economy gap between personalized cancer vaccines and infectious disease prophylaxis creates white-space opportunity in microneedle intradermal delivery eliminating cold chain dependency. Rural health systems lacking -80°C infrastructure represent the most penetrable end-user segment. Pursue antisense-small molecule conjugate development addressing patient compliance limitations of injectable RNA therapeutics through oral bioavailability enhancement. For Investors and Strategic Acquirers: Re-rating potential sits with exosome platform specialists given EU Medical Device Regulation pharmacovigilance burden creating competitive moats against lipid nanoparticle incumbents. Five-to-ten year viability favors delivery innovation archetypes with tissue-specific targeting capabilities and reduced immunogenicity profiles. Monitor FDA breakthrough therapy designation density in oncology RNA candidates as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Contract manufacturers in Massachusetts retrofit pandemic-validated RNA suites for oncology indications. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for cancer candidates. |
| Backward Integration | Specialty chemical producers in Germany anchor N1-methylpseudouridine supply security for formulation scientists. |
| Licensing Agreement | Patent thicket navigation for modified nucleoside claims consumes 18-24 months of pre-IND timelines. |
| Pipeline Diversification | Circular RNA template adoption at University of Pennsylvania enables repeat dosing regimens previously precluded by linear mRNA immunogenicity. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and NIH grant databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, GPO contracts, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates across molecular modalities and therapeutic applications.
Segment-level projections incorporated treatment line positioning, administration route differentiation, and regional regulatory cluster dynamics throughout the forecast period. CAGRs derived from patent expiry timelines, clinical trial advancement rates, and manufacturing capacity expansion announcements. Forecast inputs included FDA breakthrough therapy designation density, EMA priority medicines scheme approvals, and hospital system formulary consolidation patterns.
Inputs from NIH funding disclosures and contract manufacturer capacity announcements were available through the study window; gaps in real-time exosome platform manufacturing scale introduce uncertainty bands for novel delivery vehicle adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market