
 Lithium Nitrate Market | 2026-2036
Lithium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Nitrate Market Foresight
Specialty chemical distribution networks serving battery material buyers is rewriting procurement geography for lithium nitrate suppliers. HUIZHI LITHIUM ENERGY leverages its position in China's lithium salt corridor to dominate regional electrolyte-grade supply. Parad Chem Corporation anchors North American availability through specialized chemical distribution partnerships. FMC sustains its historical presence in high-purity lithium compounds despite portfolio streamlining elsewhere.
Lithium nitrate is an inorganic lithium salt with the formula LiNO₃, typically produced through neutralization of nitric acid with lithium carbonate or lithium hydroxide, yielding a white crystalline solid soluble in water and organic solvents. The compound serves primarily as a thermal stabilizer and additive in lithium-ion battery electrolytes, where it suppresses aluminum corrosion and extends cell cycling life at elevated voltages. Battery grade material commands premium positioning due to stringent purity thresholds below 50 ppm transition metals, while industrial grade applications in heat transfer fluids retain volume leadership across the analysis window. Reagent grade supply concentrates in pharmaceutical and analytical laboratory channels where lot-to-lot consistency determines supplier selection.
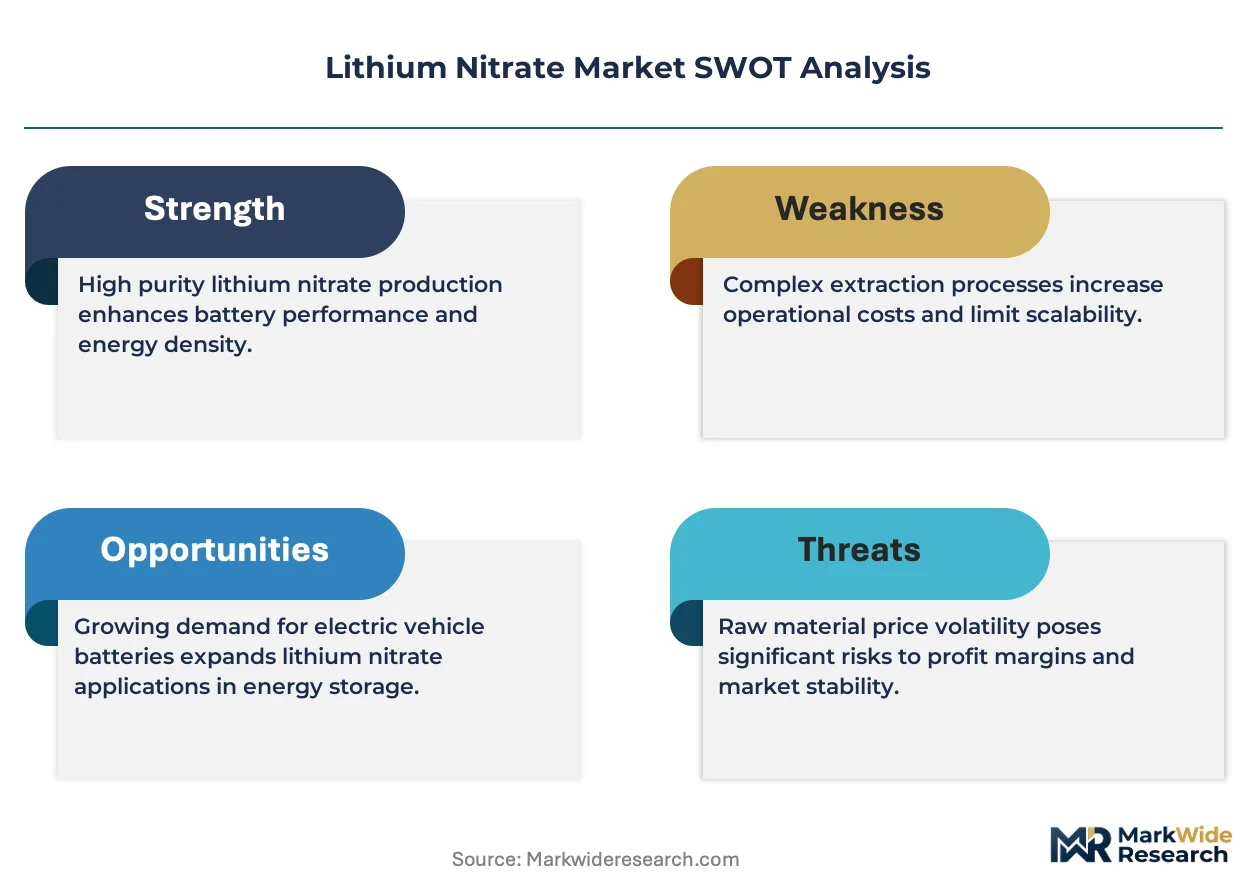
China's SAMR enforces GB standards for battery material purity, while REACH registration requirements in Europe constrain non-compliant import volumes. The EPA oversees hazardous substance reporting for lithium nitrate handlers in the United States under TSCA provisions. Stakeholders must monitor evolving electrolyte formulation patents and regional cathode chemistry transitions to align grade-specific capacity investments with downstream specification trajectories.
Market Dynamics
Electrolyte formulation patents and cathode chemistry transitions are forcing grade-specific capacity investments to align with downstream specification trajectories. Battery manufacturers now specify sub-50 ppm transition metal thresholds, compressing supplier qualification timelines and concentrating procurement among certified producers.
Growth Catalysts
- China's dual carbon goals:National mandates for carbon neutrality by 2060 accelerate battery material purity requirements, tightening supply standards for electrolyte-grade lithium nitrate across Jiangsu province's processing cluster.
- High-nickel cathode chemistry:NMC 811 and beyond formulations require enhanced aluminum corrosion suppression, elevating lithium nitrate loading in electrolyte blends for extended cycling life.
- GB standards enforcement:SAMR mandates for battery material purity create compliance-driven demand pull, disqualifying uncertified suppliers from domestic EV supply chains.
Market Restraints
- Lithium carbonate feedstock volatility:Raw material price swings transmit directly to lithium nitrate production economics, squeezing margin stability for non-integrated processors.
- Jiangsu corridor concentration:Over 70% of battery-grade capacity sits within a 200-kilometer radius, exposing buyers to localized disruption risks from environmental inspections or power rationing.
- Fluoroethylene carbonate substitution:Alternative electrolyte additives demonstrate comparable aluminum passivation, threatening lithium nitrate's incumbent position in cost-sensitive cell designs.
Strategic Opportunities
- Solid-state electrolyte convergence:Hybrid solid-liquid systems under development at Korean and Japanese battery labs specify lithium nitrate as an interfacial stabilizer, opening premium application channels.
- North American IRA alignment:Domestic content credits for EV tax incentives create qualification pathways for localized lithium nitrate production serving US battery gigafactories.
- Direct-to-cathode producer distribution:Bypassing traditional chemical distributors through long-term offtake contracts reduces working capital burdens and locks in specification alignment.
Industry Challenges
- Electrolyte formulation IP complexity:Patent thickets around additive combinations and concentration ranges constrain formulation freedom, forcing licensing negotiations or design-around investments.
- Multi-grade certification timelines:Simultaneous qualification for battery, industrial, and reagent grades stretches analytical laboratory capacity and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Nitrate Market |
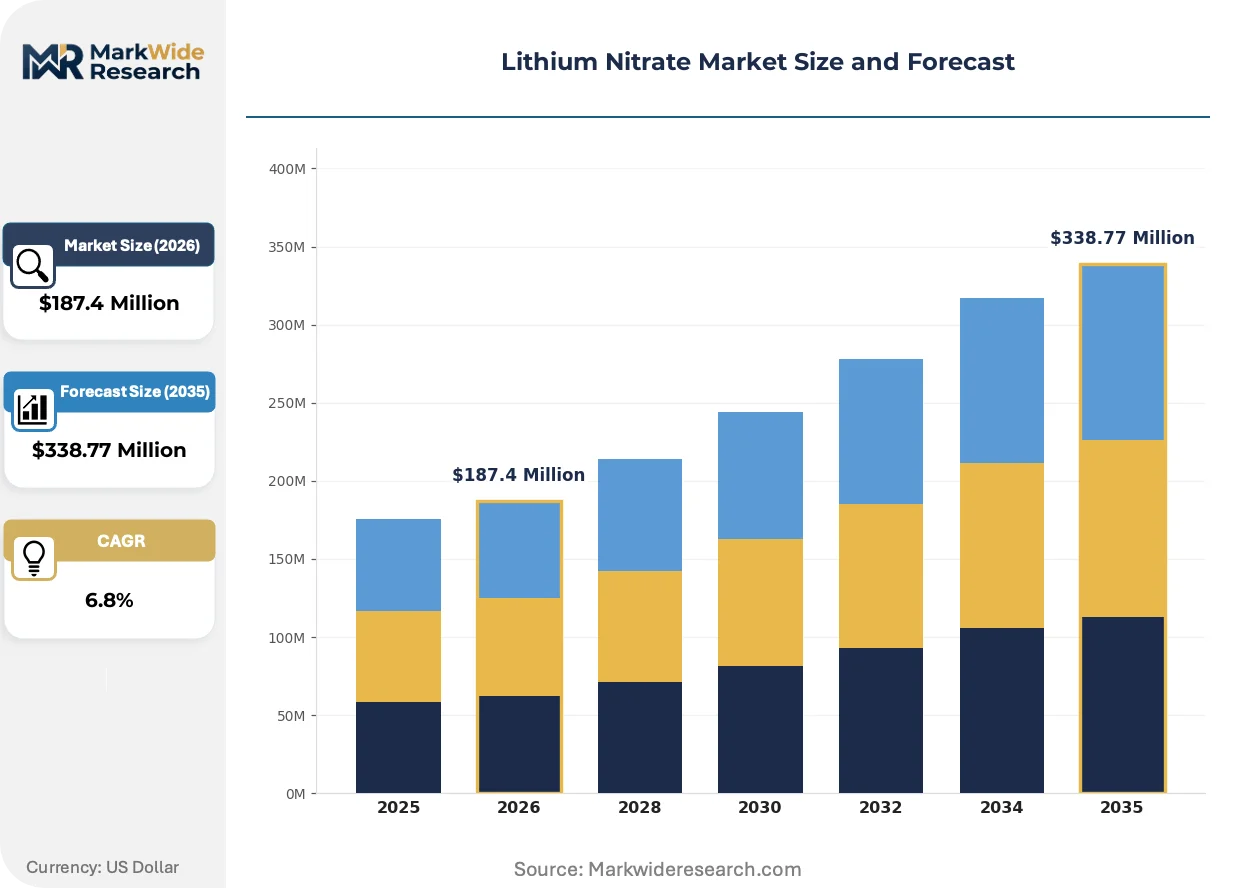
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electrolytes, Chemical Synthesis, Heat Transfer Fluids, Pharmaceuticals Grade: Industrial Grade, Battery Grade, Reagent Grade, Food Grade Packaging Type: Bags, Drums, Bulk Containers, Pallets End User: Automotive, Aerospace, Electronics, Construction |
| Companies Covered | HUIZHI LITHIUM ENERGY, Parad Chem Corporation, FMC, Morre Tec Industries, Sontara Organo Industries, Leverton Clarke, HAOXIN LIYAN, Sichuan State Lithium Materials, BRIVO LITHIUM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Nitrate Market Shifts & Advancements
Electrolyte additive architectures are undergoing rapid recombination as cell manufacturers pursue higher voltage operation and faster charging protocols. Three interconnected developments are compressing traditional supply relationships and redefining technical specifications.
Dry electrode coating is collapsing solvent-based processing requirements across cylindrical and prismatic cell lines. Tesla's 4680 production ramp and CATL's pilot installations eliminate N-methyl-2-pyrrolidone from electrode manufacturing, reducing electrolyte additive compatibility testing burdens. This process shift accelerates supplier qualification cycles from 18 months toward 9-month windows.
REACH registration requirements for lithium salts are constraining non-compliant import volumes into European battery supply chains. ECHA substance evaluation dossiers now demand full toxicological profiles for tonnage band upgrades, favoring incumbent registrants with completed data packages. German and Hungarian cell plants are prioritizing pre-registered suppliers to avoid formulation disruption.
Cathode producers are consolidating electrolyte additive procurement through direct specification authority rather than delegating to cell manufacturers. LG Chem and Umicore now issue approved supplier lists for lithium nitrate purity grades, shifting bargaining power upstream. This pattern concentrates most visibly in South Korea's cathode material cluster around Gwangyang and Ochang.
Lithium Nitrate Market Segmentation
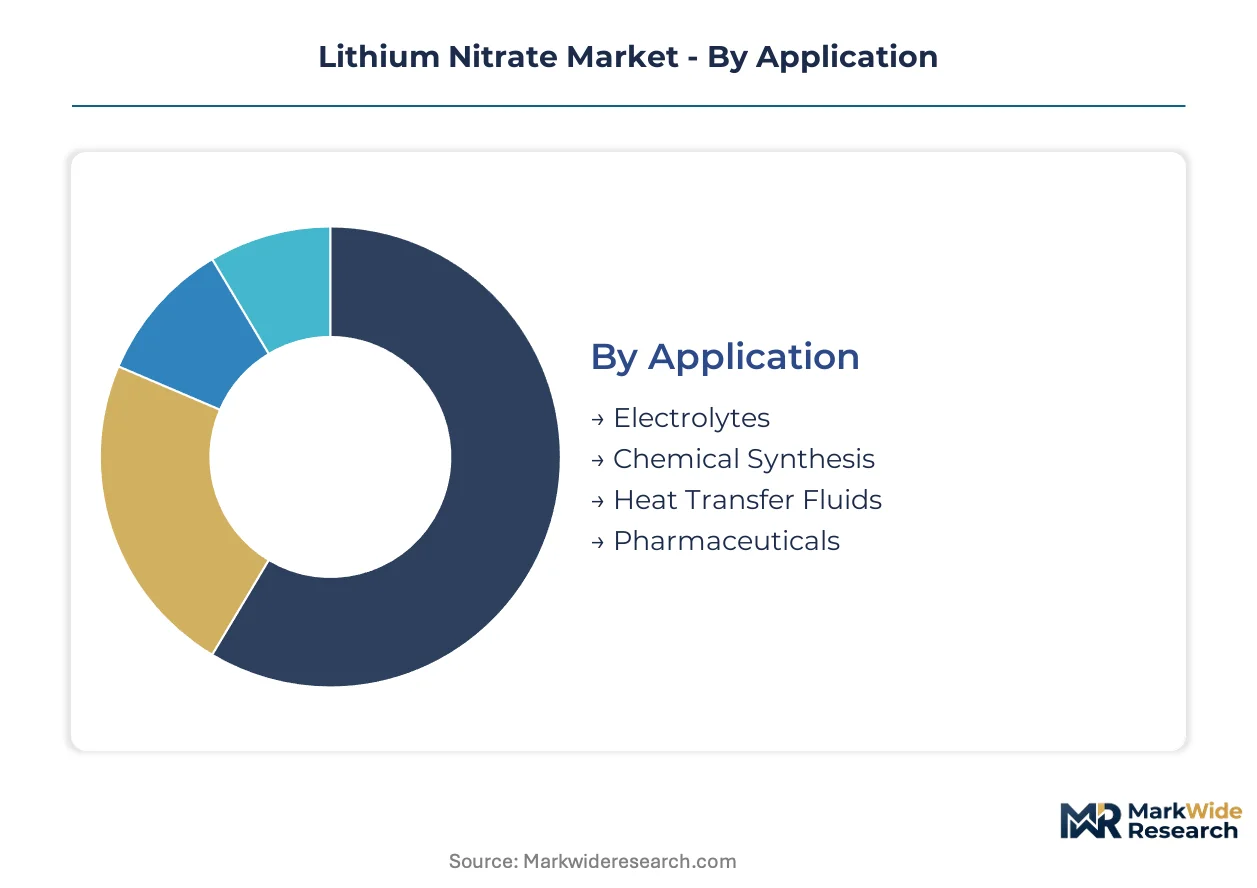
Segmentation in lithium nitrate markets reveals how purity thresholds and packaging logistics fragment procurement patterns across end-use verticals. Battery-grade specifications command premium positioning while industrial volumes sustain baseline capacity utilization. Understanding these divides exposes where specification investments align with downstream pricing power.
Application:
Application segmentation tracks how functional requirements split demand across thermal management, electrochemical stability, and chemical reactivity use cases.
- Electrolytes:Lithium nitrate suppresses aluminum corrosion at high voltages in lithium-ion cell electrolytes, with NMC 811 cathode chemistries driving loading concentration increases. Demand concentrates in Jiangsu province's battery material cluster where SAMR purity mandates enforce sub-50 ppm transition metal thresholds.
- Heat Transfer Fluids:Industrial-grade material serves concentrated solar power installations and thermal storage systems requiring high specific heat capacity and low vapor pressure. Procurement clusters in China's northwest solar corridor where MEE environmental inspections constrain localized chemical processing.
- Chemical Synthesis:Reagent-grade supply supports organic synthesis catalysts and nitrate salt precursors for specialty ceramics. Laboratory channels in Japan and Germany prioritize lot-to-lot consistency over volume scale.
- Pharmaceuticals:GMP-compliant production for lithium salt therapeutic formulations faces stringent pharmacopeial monograph requirements. FDA and EMA inspection histories determine supplier qualification status.
Electrolytes holds installed capacity. Heat Transfer Fluids is rotating up the share rankings.
Grade:
Grade stratification reflects how purity certification tiers separate pricing bands and customer qualification barriers.
- Battery Grade:Sub-50 ppm transition metal content and controlled moisture specifications qualify material for EV electrolyte formulations. Chinese SAMR GB standards and Korean KATS certification create dual compliance burdens for export-oriented producers.
- Industrial Grade:Standard purity tolerances serve heat transfer fluid and general chemical synthesis applications where cost sensitivity dominates specification rigor. Volume leadership persists across the analysis window despite margin compression.
- Reagent Grade:ACS or ISO 6353 compliance enables analytical laboratory and pharmaceutical precursor applications. Japanese JIS K 9007 and USP monograph alignment command 40-60% price premiums over industrial material.
- Food Grade:FCC and E 252 additive specifications for processed meat preservation and color retention. Regulatory divergence between FDA GRAS listings and EFSA reauthorization timelines fragments market access.
Battery Grade captures specification-driven margin expansion. Reagent Grade is climbing the fastest as laboratory outsourcing concentrates procurement.
Packaging Type:
Packaging configuration determines logistics economics and contamination risk exposure across shipment distances and storage durations.
- Bulk Containers:ISO tank and flexitank configurations serve cathode producer direct offtake contracts with dedicated fleet arrangements. Moisture ingress controls during trans-Pacific routes favor sealed systems with nitrogen padding.
- Drums:200-liter steel or fiber drums dominate mid-volume chemical distributor channels serving specialty synthesis and pharmaceutical compounders. UN-certified stacking strength requirements add 12-18% packaging cost overhead.
- Bags:Multi-layer laminated sacks with aluminum foil barriers protect hygroscopic material for industrial-grade shipments to solar thermal installations. Palletization standards vary between Chinese GB/T 16471 and European EN 13698-1.
- Pallets:Unitized loading for automated warehouse handling in Korean and German battery material hubs. ISPM-15 heat treatment compliance for wood packaging disrupts intra-Asian shipment scheduling.
Bulk Containers holds installed capacity. Drums is rotating up the share rankings.
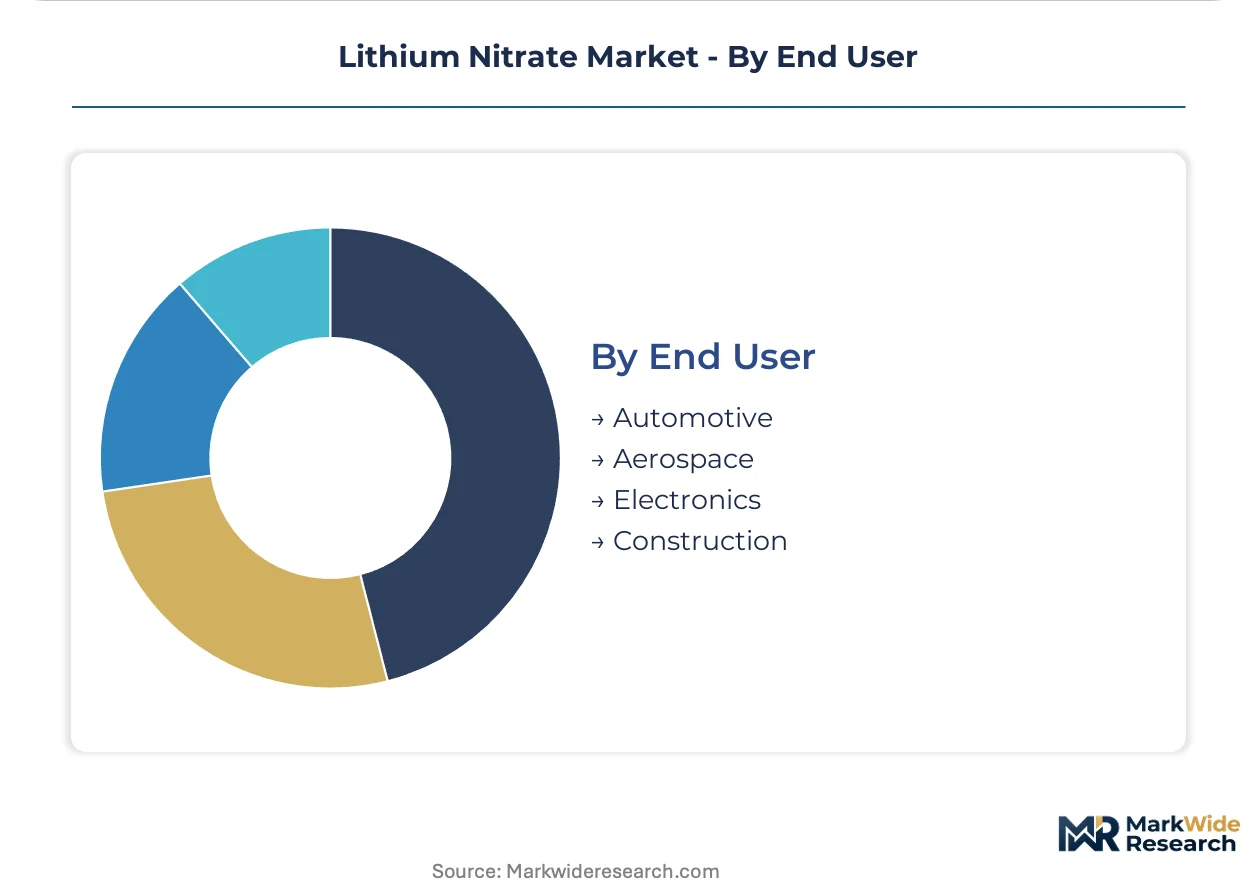
End User:
End-user segmentation maps how downstream industry concentration shapes procurement specification authority and contract duration preferences.
- Automotive:Cell manufacturer direct procurement of electrolyte-grade material for EV battery production. IRA domestic content requirements in the US and EU Battery Regulation critical raw material traceability mandates reshape supplier qualification.
- Electronics:Consumer lithium-ion cell production for power tools, laptops, and energy storage systems. Japanese and Taiwanese contract manufacturers specify narrower particle size distributions than automotive counterparts.
- Aerospace:Thermal management fluid applications in satellite and aircraft systems requiring extreme temperature stability. AS9100 quality system certification and NADCAP chemical processing accreditation constrain supplier pools.
- Construction:Phase change material admixtures for concrete temperature control and geothermal heat pump brines. Price sensitivity favors industrial-grade sourcing with minimal certification overhead.
Automotive holds installed capacity. Electronics is gaining share fastest as energy storage system production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA domestic content credits and EU Battery Regulation traceability mandates are redrawing procurement geography for lithium nitrate suppliers. Battery gigafactory construction in multiple jurisdictions is forcing grade-specific capacity localization.
China
Jiangsu province's lithium chemical processing cluster concentrates over 70 percent of battery-grade capacity within a 200-kilometer radius. SAMR enforces GB standards for battery material purity, disqualifying uncertified suppliers from domestic EV supply chains. Environmental inspections and power rationing in the Yangtze River Delta expose buyers to localized disruption risks.
United States
IRA tax incentives for domestic content create qualification pathways for localized production serving battery gigafactories in Texas and the Midwest. EPA oversees hazardous substance reporting under TSCA provisions for lithium nitrate handlers. The Southeast automotive corridor is emerging as a demand anchor for electrolyte-grade supply.
Germany
ECHA REACH registration requirements constrain non-compliant import volumes into European battery supply chains. EMA substance evaluation dossiers demand full toxicological profiles for tonnage band upgrades. Hungarian and German cell plants prioritize pre-registered suppliers to avoid formulation disruption.
South Korea
KATS certification and MFDS oversight create dual compliance burdens for export-oriented producers supplying the Gwangyang and Ochang cathode material cluster. LG Chem and domestic cathode producers now issue approved supplier lists for lithium nitrate purity grades. Direct specification authority is shifting bargaining power upstream from cell manufacturers.
Japan
METI industrial policy and JIS K 9007 standards govern reagent-grade supply for analytical laboratory and pharmaceutical precursor applications. Japanese contract manufacturers specify narrower particle size distributions than automotive counterparts for consumer lithium-ion cell production. Lot-to-lot consistency determines supplier selection in laboratory channels.
Lithium Nitrate Market Competitive Landscape
On the supply side, the industry is consolidating around integrated lithium salt processors and specialized chemical distributors with regional certification depth. Three archetypes dominate: upstream-integrated lithium compound producers, electrolyte-grade specialists with SAMR/GB compliance, and diversified chemical distributors with REACH registration. Capacity expansion and direct-to-cathode offtake contracting represent the dominant competitive moves as qualification timelines compress.
Within the integrated processor tier, HUIZHI LITHIUM ENERGY occupies a position exemplifying China's lithium salt corridor dominance, while Sichuan State Lithium Materials represents the upstream-integrated archetype with provincial resource access. Parad Chem Corporation anchors North American availability through specialized chemical distribution partnerships, sitting within the regional compliance-focused tier that leverages pre-built regulatory dossiers.
| Leading Market Players |
|---|
| HUIZHI LITHIUM ENERGY |
| Parad Chem Corporation |
| FMC |
| Morre Tec Industries |
| Sontara Organo Industries |
| Leverton Clarke |
| HAOXIN LIYAN |
| Sichuan State Lithium Materials |
| BRIVO LITHIUM |
| Others |
Supply & Pricing Matrix
Single-source dependency on Jiangsu province's lithium salt corridor compresses pricing tier spreads while amplifying supply chain fragility across electrolyte-grade procurement channels. SAMR environmental enforcement actions and power rationing events in the Yangtze River Delta simultaneously widen spot-market premiums and force buyers toward multi-source qualification investments.
Pricing Analysis
Certification level creates the primary spread across battery, industrial, and reagent grades, with SAMR GB compliance and Korean KATS certification commanding 15-25% premiums over uncertified material. Contract-based long-term offtake agreements dominate cathode producer procurement, insulating qualified suppliers from lithium carbonate feedstock volatility while squeezing non-integrated processors. Cost compression in industrial-grade supply is intensifying because solar thermal installations prioritize volume scale over purity thresholds. Automotive cell manufacturers exhibit least price sensitivity due to specification lock-in, while construction-phase change material buyers favor economy sourcing with minimal certification overhead.
Supply Chain Analysis
Tariff exposure between China and North American battery gigafactories dominates supply chain risk calculus for electrolyte-grade distributors. Production gravity centers on China, South Korea, and Japan, with Jiangsu province hosting over 70% of battery-grade capacity within a 200-kilometer radius. The supply chain draws from lithium carbonate, nitric acid, and specialized purification equipment as critical inputs. Distribution runs through cathode material clusters in Gwangyang, Ochang, and emerging North American gigafactory corridors rather than traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified laboratory capacity for multi-grade certification represents the binding constraint on supplier expansion, with simultaneous battery-industrial-reagent qualification timelines stretching analytical resources and delaying revenue recognition for aspirant producers.
For Market Incumbents: Pre-empt fluoroethylene carbonate substitution threats by locking cathode producers into direct specification authority relationships through dedicated technical service teams. Pursue backward integration into lithium carbonate feedstock to insulate margin stability from raw material volatility. Prioritize capacity addition in Texas and the US Southeast to capture IRA domestic content credit alignment before qualification windows compress further. For New Entrants and Emerging Players: North American electrolyte-grade supply represents the most penetrable white space, with IRA incentives creating qualification pathways for localized production serving battery gigafactories. Target reagent-grade laboratory channels in Japan and Germany where lot-to-lot consistency requirements favor specialist producers over commodity-scale competitors. Pursue toll-manufacturing partnerships with established SAMR-certified processors to bypass 18-month qualification timelines. For Investors and Strategic Acquirers: EU Battery Regulation traceability mandates reshape the acquisition landscape toward pre-registered REACH suppliers with completed ECHA toxicological dossiers. Long-term viability hinges on exposure to solid-state electrolyte convergence timelines, where hybrid solid-liquid systems specify lithium nitrate as interfacial stabilizer. Watch Korean and Japanese battery lab patent filings for formulation architecture shifts signaling premium application channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Jiangsu corridor additions align with SAMR GB enforcement and NMC 811 chemistry loading increases. |
| Backward Integration | Lithium carbonate feedstock control insulates processors from spot-market volatility transmission. |
| Long-term Supply Agreement | Direct-to-cathode offtake contracts reduce working capital burdens and lock specification alignment. |
| Joint Venture | Korean-Japanese battery lab partnerships accelerate solid-state electrolyte interfacial stabilizer qualification. |
| Green Manufacturing Transition | Dry electrode coating compatibility eliminates N-methyl-2-pyrrolidone solvent testing burdens. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SAMR regulatory filings, ECHA registration dossiers, and SEC chemical processor disclosures. Plant managers at Jiangsu lithium salt facilities, procurement leads at Korean cathode producers, electrolyte formulation directors, and distribution channel partners provided operating data. Bottom-up capacity assessments triangulate against top-down demand modeling from EV production forecasts.
Forecast inputs include grade-specific purity thresholds, cathode chemistry transition timelines, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions span application function, certification tier, packaging configuration, and end-user industry concentration. CAGRs derive from elasticity-adjusted demand curves incorporating electrolyte additive substitution risks and solid-state technology convergence scenarios.
Practitioners should monitor ECHA substance evaluation timelines, IRA domestic content rule refinements, and dry electrode coating adoption rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Global Linear Alkyl Benzene Market