
 Global Bio Based Platform Chemicals Market | 2026-2036
Global Bio Based Platform Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Based Platform Chemicals Market Intelligence
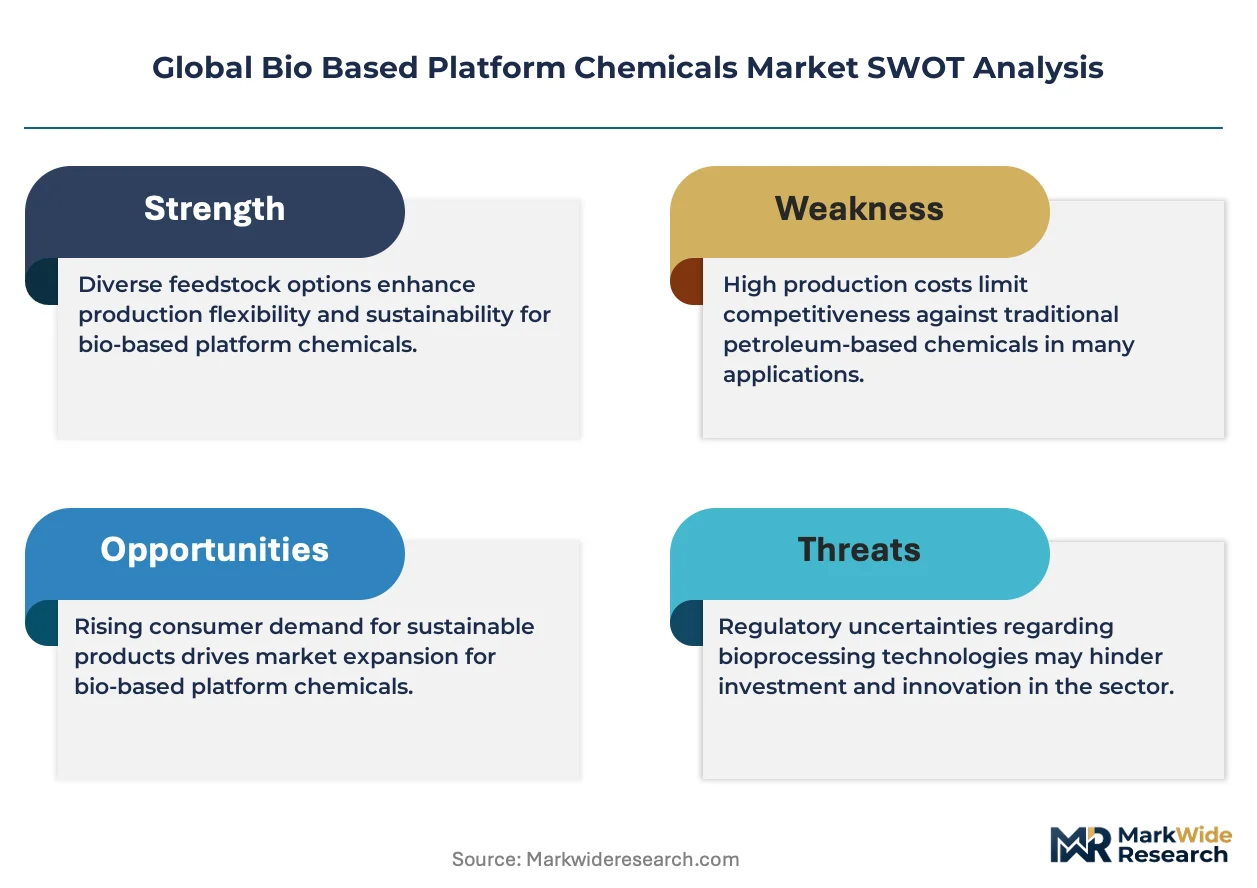
The European Union's REACH framework, which scrutinizes petroleum-based inputs, is consolidating the market around producers with certified bio-based supply chains. BASF SE leverages its extensive chemical engineering expertise to develop new bio-based intermediates. DuPont de Nemours, Inc. competes on the performance of its bio-polymers, while Corbion N.V. specializes in lactic acid and its derivatives for food and material applications.
Bio-based platform chemicals are fundamental molecules derived from renewable biomass sources such as corn or sugarcane. These compounds, produced through methods like fermentation and chemical catalysis, act as sustainable precursors for a wide array of high-value chemical products. Lactic acid represents a mature product segment, serving as a key input for bioplastics. The plastics and coatings applications drive significant volume, with fermentation technology remaining a dominant production pathway.
Regulatory frameworks including the US EPA's BioPreferred Program and the EU Green Deal create market pull through procurement mandates. In parallel, China's dual carbon goals incentivize investment in non-fossil fuel-based chemical production. Securing cost-competitive and sustainable biomass feedstock will determine long-term viability and competitive advantage for market participants.
Market Dynamics
The market's central dynamic is the push to reconcile sustainability mandates with the economic realities of feedstock competition. Regulatory frameworks in Europe and China create demand, but securing cost-competitive biomass against food and fuel sectors remains a primary structural challenge for producers.
Growth Catalysts
- Regulatory Pull:The EU Green Deal and the US BioPreferred Program create dedicated markets and procurement incentives for certified bio-based chemicals, particularly in public contracts and consumer goods.
- Packaging Sector Demand:Brand owners in the food, beverage, and consumer goods industries are actively seeking bio-based plastics and coatings to meet corporate sustainability goals and consumer preferences for sustainable packaging.
- Process Technology:Continuous improvements in fermentation efficiency and catalytic conversion pathways are lowering production costs and expanding the range of molecules that can be economically derived from biomass.
Market Restraints
- Feedstock Competition:Biomass inputs like corn and sugarcane face price volatility due to competing demand from the food, animal feed, and biofuels industries, impacting cost predictability for chemical producers.
- Capital Intensity:The construction of new, large-scale biorefineries requires substantial upfront capital investment, posing a significant barrier to entry compared to modifying existing petrochemical assets.
- Performance Parity:While improving, some bio-based chemicals still face challenges in matching the performance specifications or processing characteristics of their petroleum-derived counterparts in demanding applications.
Strategic Opportunities
- Geographic Expansion:Establishing production hubs in Southeast Asian nations like Thailand and Malaysia allows for leveraging abundant, non-food biomass resources and serving growing regional chemical demand.
- High-Value Applications:Moving beyond commodity bioplastics into specialty markets such as bio-based lubricants, solvents, and adhesives offers higher margin potential and less direct competition with petrochemicals.
- Digital Process Optimization:Applying AI and machine learning algorithms to bioreactor control and metabolic engineering can accelerate the development of new bio-pathways and significantly improve production yields.
Industry Challenges
- Supply Chain Logistics:Developing resilient and efficient supply chains for collecting, storing, and transporting diverse and often perishable biomass feedstocks presents a major operational hurdle for biorefineries.
- Certification Complexity:Navigating the fragmented landscape of bio-content certifications across different regions, such as the USDA BioPreferred program versus European norms, adds cost and complexity for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Based Platform Chemicals Market |
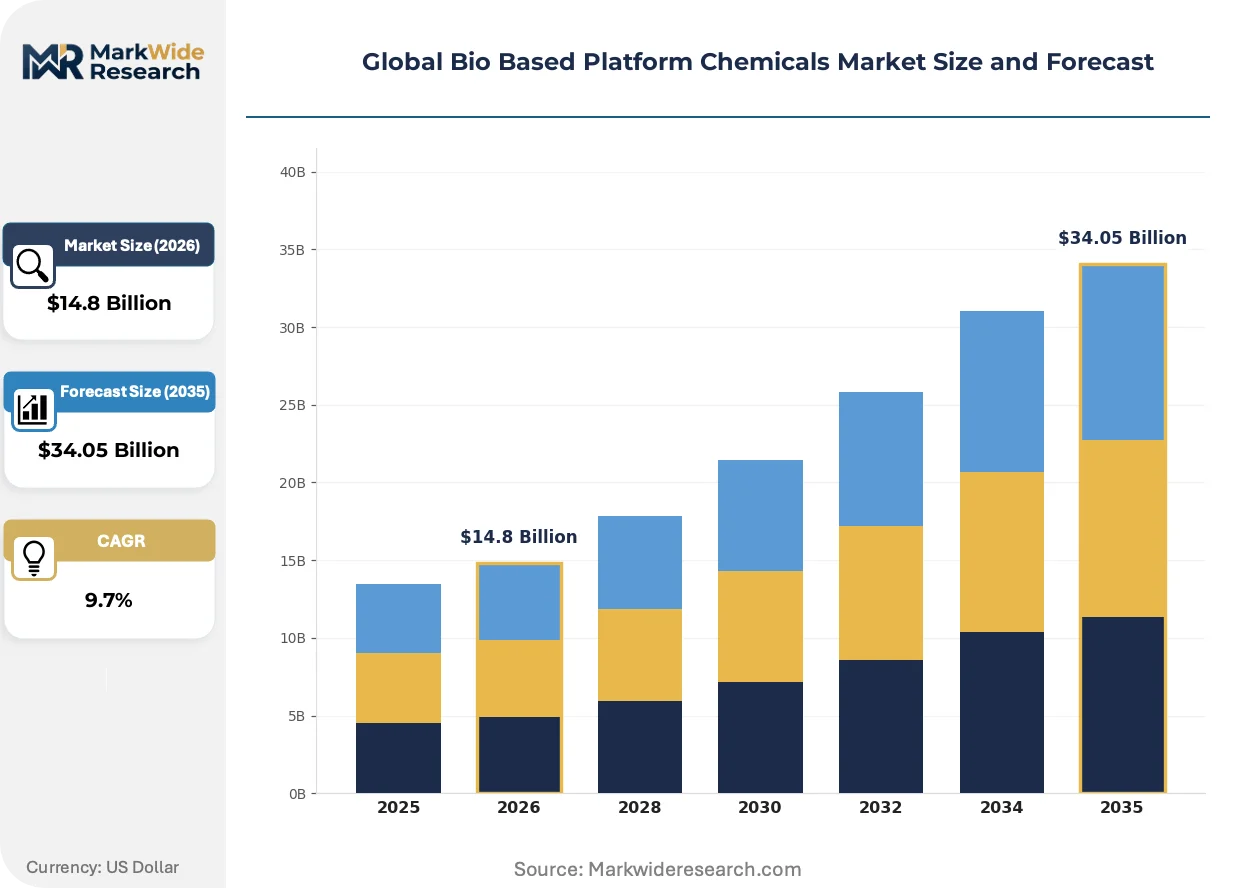
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butanol, Ethanol, Lactic Acid, Glycolic Acid Application: Adhesives, Coatings, Plastics, Personal Care End User: Automotive, Packaging, Agriculture, Pharmaceuticals Technology: Fermentation, Chemical Catalysis, Bioconversion, Thermochemical |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Braskem S.A., Genomatica, Inc., Novozymes A/S, Corbion N.V., Roquette Frères, Avantium N.V., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Based Platform Chemicals Market Strategic Shifts & Innovations
The evolution from niche specialty products to mainstream industrial inputs defines the current market trajectory. This transition is driven by a convergence of production technology breakthroughs and assertive carbon-reduction policies that are fundamentally altering the chemical industry's manufacturing logic.
Advanced electrocatalysis is emerging as a key production technology. This process uses electricity to drive chemical reactions at ambient temperatures and pressures, offering higher selectivity. Chemical producers are adopting it to create platform chemicals like furfural from biomass with greater energy efficiency, and this shift is electrifying the conversion pathway away from heat-intensive methods.
China's "dual carbon" policy framework is a powerful force for market development. It creates strong incentives for domestic production of non-fossil fuel chemicals through subsidies and mandates. The policy most directly impacts the synthetic fibers and plastics industries, compelling manufacturers to incorporate bio-based feedstocks like bio-glycols to align with national emissions targets.
A significant shift in purchasing criteria is taking place, led by brand owners in consumer-facing sectors. They are increasingly requiring suppliers to provide bio-content verification from bodies like TÜV AUSTRIA or certification under the USDA BioPreferred program. This is most visible in the European and North American markets for packaging and cosmetics, where sustainability claims are a key product differentiator.
Global Bio Based Platform Chemicals Market Segmentation
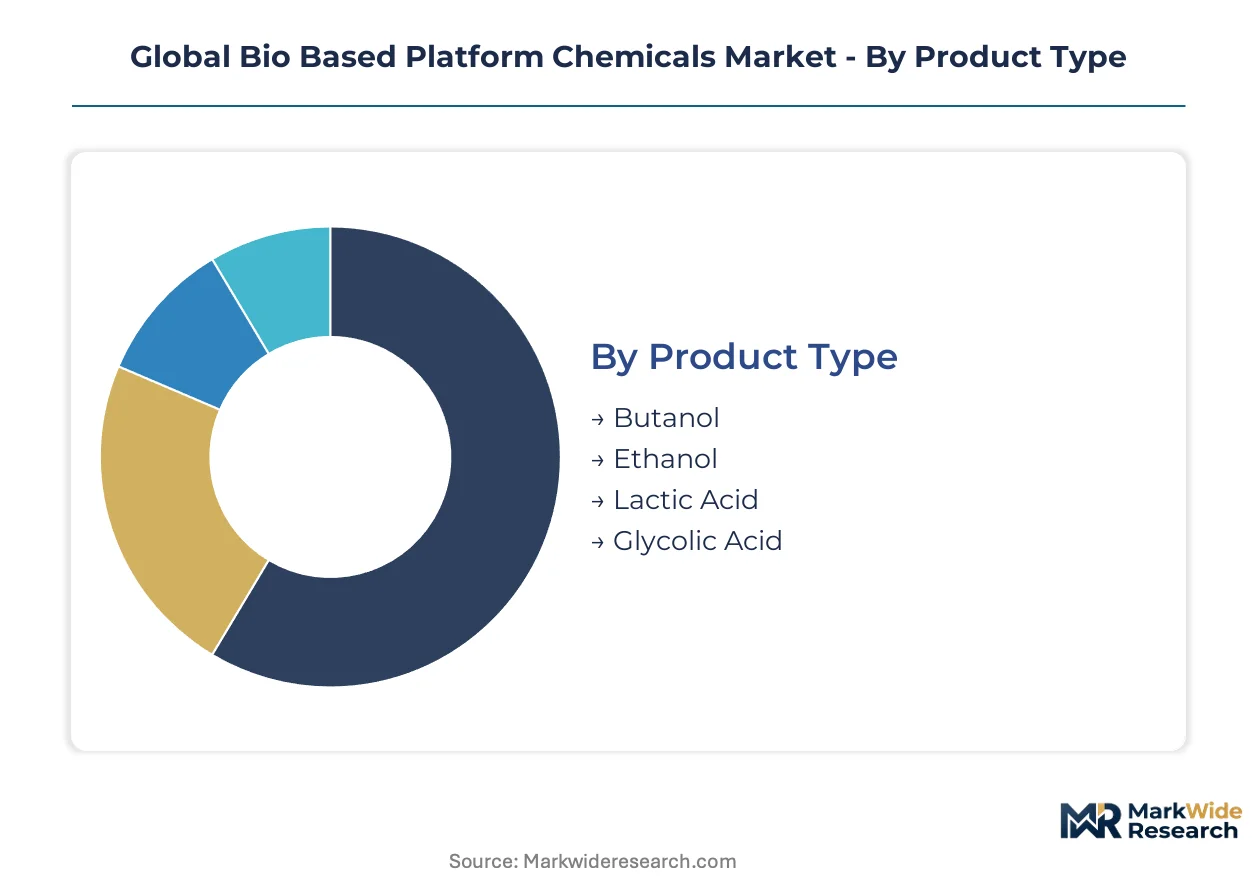
Understanding market segmentation is crucial for identifying specific growth pockets and competitive arenas within the global bio-based platform chemicals industry. This analysis categorizes the market by critical dimensions, revealing where value creation is concentrated and where innovation is driving new applications. Each segment possesses distinct characteristics influencing production methods, end-use requirements, and market dynamics.
Product Type:
The market for bio-based platform chemicals is undergoing a significant upgrade cycle as producers replace traditional petrochemical inputs with renewable alternatives.
- Lactic Acid:This alpha-hydroxy acid, produced primarily through fermentation of carbohydrates, serves as a fundamental building block for polylactic acid (PLA) bioplastics. Demand for lactic acid is concentrating in the packaging sector, driven by brand owners seeking certified compostable and bio-based material solutions.
- Ethanol:Bio-ethanol, typically derived from corn or sugarcane fermentation, functions as a solvent, fuel additive, and chemical intermediate. Its demand is significantly influenced by regulatory mandates for renewable fuels in regions like the United States and Brazil, alongside its use in industrial solvents.
- Butanol:Bio-butanol is a four-carbon alcohol, offering superior energy density and lower volatility compared to ethanol, finding application as a biofuel or solvent.
- Glycolic Acid:This smallest alpha-hydroxy acid is derived from renewable sources and is widely used in personal care products and industrial cleaning formulations due to its excellent exfoliating and chelating properties.
Volume placements concentrate in Ethanol; the faster expansion belongs to Lactic Acid.
Application:
Specific application areas dictate the performance requirements and commercial viability of bio-based platform chemicals, influencing material selection and processing. The plastics and coatings applications drive significant volume, with fermentation technology remaining a dominant production pathway.
- Plastics:Bio-based platform chemicals are directly converted into bioplastics such as PLA, bio-PET, and bio-PE, offering sustainable alternatives to fossil-derived polymers. The automotive and packaging industries are major consumers, seeking lighter weight and reduced carbon footprint materials.
- Coatings:Bio-based inputs enhance the sustainability profile of paints, varnishes, and protective coatings, improving properties like durability and reduced VOC emissions. European manufacturers are increasingly incorporating these chemicals to meet stringent environmental regulations and consumer preferences.
- Adhesives:Bio-based chemicals provide sustainable components for various adhesive formulations, including those used in packaging, construction, and woodworking.
- Personal Care:Ingredients derived from bio-based platform chemicals are integrated into cosmetics, skincare, and hygiene products, appealing to consumers seeking natural and environmentally friendly formulations.
The Plastics application drives significant demand, while Coatings demonstrates robust expansion.
End User:
End-user industries represent distinct consumption patterns and regulatory landscapes for bio-based platform chemicals, shaping market opportunities and product development. Demand from the packaging sector for sustainable materials is a primary contributor.
- Packaging:The packaging industry utilizes bio-based platform chemicals to produce bioplastics and bio-coatings for food and beverage containers, films, and consumer goods packaging. Brand owners in Europe and North America are actively seeking these materials to meet corporate sustainability goals.
- Automotive:Bio-based chemicals contribute to the production of lightweight components, interior materials, and bio-lubricants for the automotive sector. Manufacturers are integrating these materials to reduce vehicle weight and improve overall environmental performance.
- Agriculture:Bio-based platform chemicals find use in agricultural applications such as bio-pesticides, biodegradable mulches, and soil enhancers.
- Pharmaceuticals:The pharmaceutical sector employs bio-based chemicals as excipients, intermediates, and active pharmaceutical ingredients, driven by increasing focus on sustainable manufacturing processes.
Demand from Packaging end-users underpins stability, with Automotive end-users exhibiting dynamic expansion.
Technology:
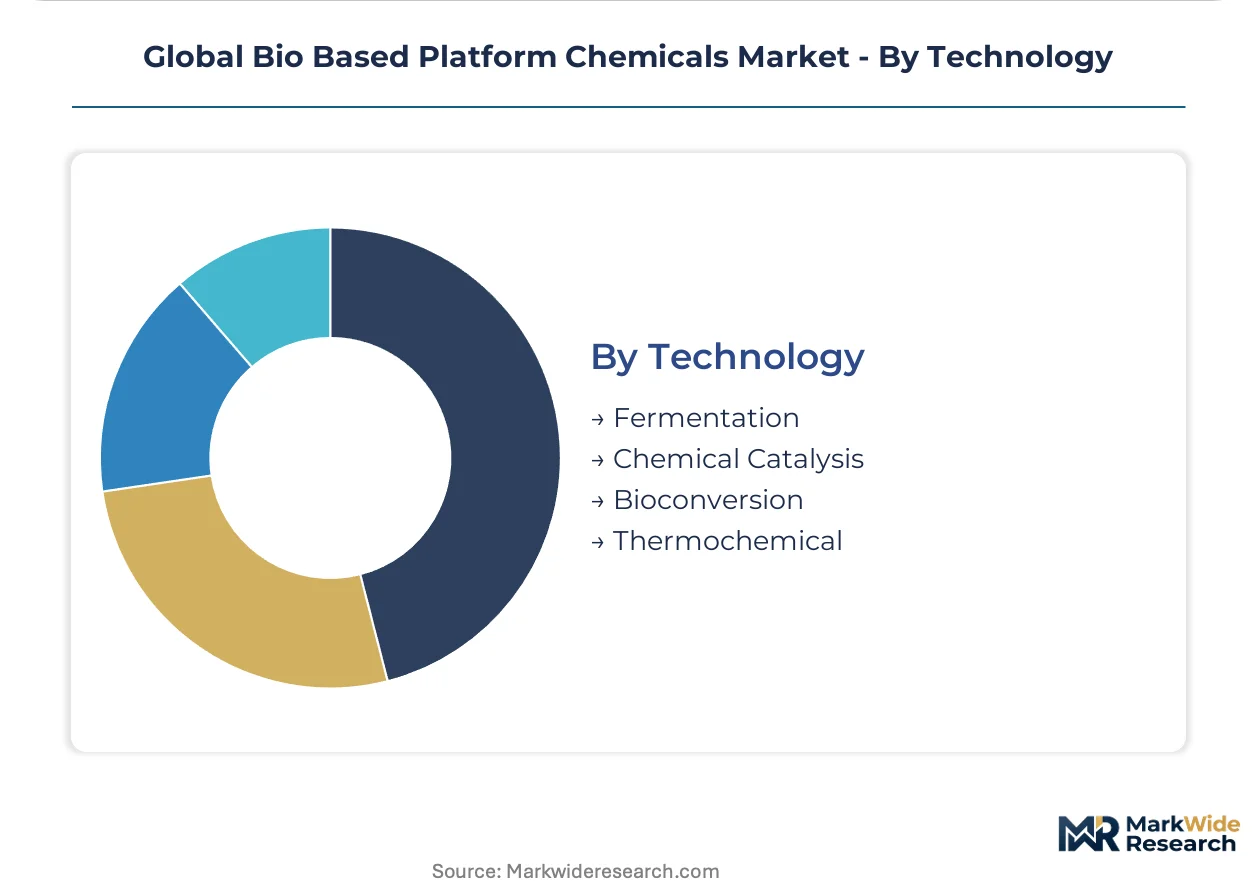
Production technologies define the efficiency, scalability, and economic viability of deriving platform chemicals from renewable biomass sources. Fermentation technology remains a dominant production pathway.
- Fermentation:This biological process uses microorganisms to convert sugars from biomass into desired platform chemicals such as lactic acid, ethanol, and butanol. Continuous improvements in fermentation efficiency are lowering production costs and expanding the range of economically viable molecules.
- Chemical Catalysis:This technology employs chemical catalysts to transform biomass-derived feedstocks into platform chemicals, often at higher temperatures and pressures. Advanced electrocatalysis is emerging as a key production technology, offering higher selectivity and energy efficiency.
- Bioconversion:Bioconversion processes leverage enzymes or whole cells to transform biomass into value-added chemicals, often operating under milder conditions than traditional chemical methods.
- Thermochemical:These methods involve high-temperature processes like gasification and pyrolysis to break down biomass into syngas or bio-oils, which can then be converted into platform chemicals.
Established Fermentation technologies secure the bulk of production, whereas Chemical Catalysis technologies are advancing rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for bio-based platform chemicals is evident across several key global regions. Regulatory initiatives and consumer preferences for sustainable materials are driving this adoption. Significant investments in production capacity are following these demand signals.
United States
Demand for bio-based packaging and personal care products drives market expansion in the United States. The US EPA's BioPreferred Program mandates federal procurement of bio-based products, creating a stable market pull. Research and development clusters in California are advancing new biomanufacturing processes for diverse platform chemicals.
Germany
European manufacturers in Germany seek bio-based inputs for coatings and plastics to meet stringent environmental targets. The EU Green Deal promotes circular economy principles, creating new commercialization pathways for bio-based alternatives. Chemical parks like Ludwigshafen are centers for bio-based chemical innovation, leveraging extensive engineering expertise.
China
China's dual carbon goals are compelling synthetic fibers and plastics industries to incorporate bio-based feedstocks. Government subsidies incentivize domestic production of non-fossil fuel chemicals, supporting local biorefineries. Manufacturing investments in Jiangsu province are concentrating to serve the domestic chemical industry's sustainability transformation.
Brazil
Abundant sugarcane resources position Brazil as a key producer of bio-ethanol and lactic acid derivatives. National renewable fuel mandates support the large-scale production of bio-based chemicals for both domestic use and export. Industrial hubs in São Paulo leverage advanced fermentation technology for efficient biomass conversion.
India
India's growing chemical industry and sustainability goals are increasing the uptake of bio-based materials, particularly in packaging. The PLI scheme for specialty chemicals could support indigenous production of bio-based alternatives. Industrial zones around Gujarat are developing new capacities for bio-based chemical synthesis from agricultural biomass.
Global Bio Based Platform Chemicals Market Key Industry Players
European producers anchor one tier, leveraging established chemical engineering expertise and stringent environmental mandates; Asian specialists hold another, driven by scale and rapidly expanding domestic demand. The market structure presents a mix of large integrated chemical companies and specialized bio-tech firms. Strategic archetypes include diversified chemical giants, bio-polymer specialists, and fermentation technology providers. Dominant competitive moves involve capacity expansion, strategic partnerships for feedstock security, and continuous technology licensing.
Within the diversified chemical giants' tier, BASF SE, a German-based AG, exemplifies broad portfolio integration across various bio-based intermediates, leveraging extensive chemical engineering expertise. DuPont de Nemours, Inc., an American-based Inc., occupies a position as a bio-polymer specialist, focusing on high-performance bio-based materials for demanding applications. Braskem S.A., a Brazil-based S.A., anchors the scale-driven end, particularly in bio-polyethylene production, leveraging abundant local biomass resources. These entities showcase diverse strategic approaches to capturing value in the evolving bio-based chemicals market, differentiating through either product breadth, specialized performance, or feedstock integration.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Braskem S.A. |
| Genomatica, Inc. |
| Novozymes A/S |
| Corbion N.V. |
| Roquette Frères |
| Avantium N.V. |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
The European Union's Green Deal, alongside China's dual carbon goals, gates access to qualified bio-based supply chains and enables premium pricing for certified materials. These regulatory frameworks influence market entry and product valuation.
Pricing Analysis
Premium pricing for short lead times characterizes specific bio-based platform chemicals, while commodity spot pricing applies to others. Contract-based long-term offtake agreements often govern larger volume placements. Price differentiation stems from certification levels, such as TÜV AUSTRIA or USDA BioPreferred, and volume scale. Pricing pressure originates from feedstock volatility, making commodity bio-ethanol buyers highly price-sensitive compared to packaging sector clients seeking certified compostable solutions.
Supply Chain Analysis
Reverse logistics for bio-based materials are still nascent, primarily focusing on post-consumer collection for mechanical recycling rather than chemical feedstock recovery. Geographic supply for bio-based platform chemicals concentrates in Brazil for sugarcane-derived products and the United States for corn-based inputs. China's manufacturing investments also contribute significantly. Commodity price volatility for biomass feedstocks represents a primary structural risk. Distribution runs through direct supply to large industrial consumers, with specialized distributors handling niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a technology-transition phase, as advanced electrocatalysis displaces traditional heat-intensive methods for chemical conversion. This shift fundamentally alters manufacturing economics and product portfolios.
For Market Incumbents:Anticipate continued regulatory pressure from the EU Green Deal and China's dual carbon goals, driving demand for certified bio-based inputs. Invest in capacity additions in Southeast Asian nations to secure diverse biomass resources and mitigate feedstock competition. Pursue strategic partnerships for advanced fermentation technology to lower production costs and expand product breadth against emerging bio-tech firms.
For New Entrants and Emerging Players:Specialized distributors offer a viable go-to-market angle for novel bio-based chemicals, particularly in high-value applications like bio-lubricants and adhesives. Target underpenetrated specialty markets in North America and Europe, where performance parity with petroleum alternatives is achievable. Focus on demonstrating superior sustainability credentials through robust certification programs to attract brand owners.
For Investors and Strategic Acquirers:Widespread adoption of bio-based packaging by major consumer brands is the leading indicator that this market’s long-term viability is strengthening. Focus on acquiring bio-polymer specialists or fermentation technology providers with proven scalability and diversified feedstock access. Monitor advancements in metabolic engineering and AI-driven process optimization for accelerated yield improvements.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This initiative secures abundant biomass resources and serves growing regional chemical demand. |
| Advanced Fermentation Technology Licensing | This move lowers production costs and expands the range of economically viable bio-based molecules. |
| Partnerships with Brand Owners | These collaborations accelerate market pull for certified bio-based materials in consumer-facing sectors. |
| Investment in Metabolic Engineering | This R&D focus accelerates the development of new bio-pathways and improves production yields. |
| Acquisition of Bio-Polymer Specialists | This strategy enhances product portfolios with high-performance bio-based materials for demanding applications. |
Research Approach
Independent corroboration across industry association reports, customs trade data, and corporate financial filings underwrites the qualitative findings and quantitative estimates. This approach combines primary interviews with R&D directors, procurement leads, and sustainability officers from leading chemical companies. Secondary validation draws from global regulatory body publications and academic research.
Rate-of-change decomposition across the analysis window informed the projection of market expansion. The analytical framework models segmentation dimensions including product type, application, end-user industry, and regional production capacity. CAGRs were derived by assessing historical growth trends and future demand drivers. Key forecast inputs include biomass feedstock availability and regulatory mandate stringency.
Caveats apply where unforeseen geopolitical events or rapid technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions documented at publication, acknowledging inherent market fluidity. Practitioners should monitor feedstock price volatility and new regulatory frameworks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Global Recovered Carbon Black Market