
 Seafood Packaging Market | 2026-2036
Seafood Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Packaging Market Analysis
European converter investment in recyclable barrier films is shifting capacity toward mono-material structures suited for seafood trays and pouches. Amcor leverages its global R&D network to develop high-barrier PE solutions that sustain shelf life without multi-layer complexity. Sealed Air competes through automated packaging systems that anchor throughput for processors in North America and Asia. Berry Global specializes in injection-molded PP containers that dominate fresh fillet segments in European retail.
Seafood packaging encompasses engineered materials and container systems designed to preserve aquatic product freshness, prevent oxidation, and maintain cold-chain integrity from harvest through consumption. Critical specifications include oxygen transmission rates below 1 cc/m²/day for vacuum formats and seal strengths exceeding 15 N/15mm to withstand ice slurry handling. Modified atmosphere packaging commands the largest volume share among technology segments, while active packaging with oxygen scavengers represents the fastest-expanding margin pool as premium retailers seek extended case-life. Plastic retains dominant share by material, though fiber-based trays and molded pulp formats are gaining ground in retail-ready applications where visual presentation and recyclability intersect.
The EU F-Gas Regulation and REACH framework restrict certain fluorinated barrier chemistries, redirecting R&D toward bio-based coatings and mineral-filled PE alternatives. FDA food contact regulations in the United States govern migration limits for adhesives and coatings used in lidding films and laminated structures. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling infrastructure gaps, as these will determine which material platforms achieve scale viability across major seafood processing and export corridors.
Market Dynamics
Retail chain consolidation across chilled and frozen seafood aisles is compressing supplier margins while demanding simultaneous shelf-life extension and material recyclability, forcing converters to re-engineer barrier architectures without multi-layer complexity.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for virgin plastic consumption are pulling investment into fiber-based tray formats and recyclable mono-material films across European retail channels.
- Vacuum skin packaging:Premium protein retailers are adopting this format for whole fish and fillet presentation, eliminating drip loss while extending retail case-life by 40-50% over conventional MAP.
- China:Aquaculture output expansion and processed seafood export growth are concentrating demand for high-barrier frozen formats capable of withstanding extended cold-chain transit to European and North American buyers.
Market Restraints
- Ethylene-vinyl alcohol (EVOH) supply concentration:Barrier resin production clusters in Northeast Asia create vulnerability for European and North American converters dependent on imported high-oxygen-barrier feedstocks.
- EU F-Gas Regulation:Restrictions on fluorinated barrier chemistries are eliminating proven high-performance substrates before bio-based alternatives achieve equivalent oxygen transmission specifications.
- Mechanical recycling infrastructure gaps:Multi-layer laminated structures common in lidding films lack viable sorting and reprocessing pathways, trapping brands in non-recyclable formats despite sustainability commitments.
Strategic Opportunities
- India:Underdeveloped cold-chain coverage in coastal states creates whitespace for active packaging with time-temperature indicators targeting domestic fresh fish distribution.
- Oxygen scavenger integration:Convergence of modified atmosphere technology with embedded iron-based absorbers is opening premium positioning for case-ready seafood in extended retail cycles.
- Direct-to-restaurant channels:Foodservice distributors are bypassing traditional retail packaging specifications, creating demand for bulk vacuum formats with processor-branded labeling.
Industry Challenges
- Migration testing protocols:FDA food contact notification timelines for novel bio-based coatings extend 12-18 months, delaying commercialization of recyclable barrier alternatives.
- Legacy thermoforming asset base:Capital-intensive tray production lines designed for PS and PET multilayers resist rapid retooling for fiber-based or mono-material substitutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Packaging Market |
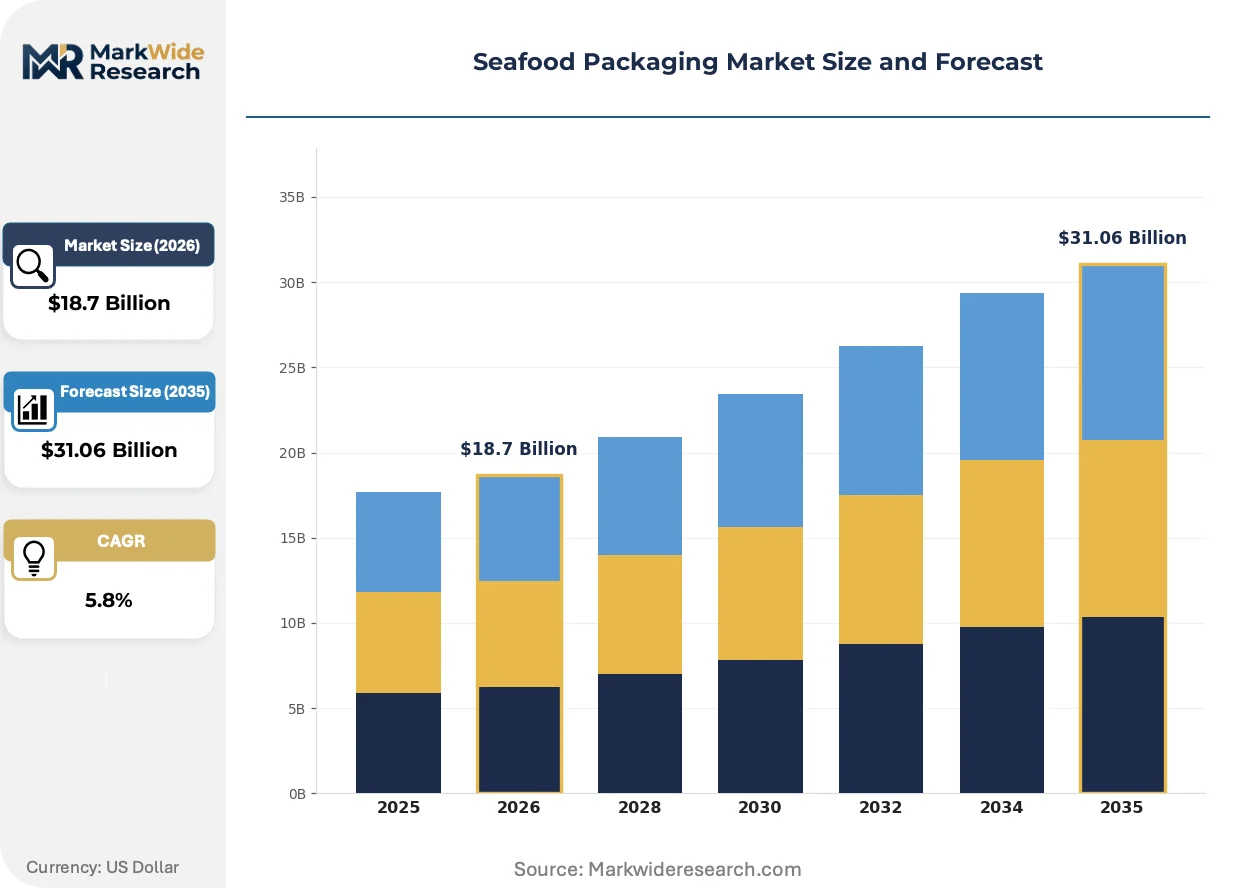
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Trays, Boxes, Cans Material: Plastic, Paper, Glass, Metal End User: Retail, Food Service, Wholesale, Direct-to-Consumer Technology: Vacuum Sealing, Modified Atmosphere Packaging, Skin Packaging, Active Packaging |
| Companies Covered | Amcor, Sealed Air, Berry Global, DS Smith, Mondi Group, Sonoco, Winpak, Coveris, Cascades, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Packaging Market Emerging Trajectories
Active and intelligent packaging systems are migrating from pharmaceutical applications into seafood preservation, while regulatory pressure on persistent chemistries accelerates mineral-filled and bio-based barrier development.
High-barrier polyethylene formulations incorporating mineral nanofillers are electrifying the technical feasibility of mono-material recyclable pouches. Nordic retail chains are piloting these structures for smoked salmon and marinated herring segments. The elimination of EVOH and polyamide layers is compressing sorting complexity for mechanical recycling streams while maintaining sub-1 cc/m²/day oxygen transmission rates.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from paper-based seafood trays. Converter R&D programs in Germany and the Netherlands are redirecting toward polysaccharide and lignin-derived barriers. Fresh fillet retail segments in France and Belgium are most affected, with private-label suppliers accelerating validation of fluorine-free alternatives ahead of 2025 restriction deadlines.
Central kitchen and ghost kitchen proliferation is fragmenting seafood procurement away from traditional wholesale markets. Foodservice operators in urban China and South Korea are demanding pre-portioned, individually quick-frozen formats with cook-in-bag functionality. This specification shift favors pouch converters capable of integrating easy-open features and sous-vide compatibility at volume scale.
Seafood Packaging Market Segmentation
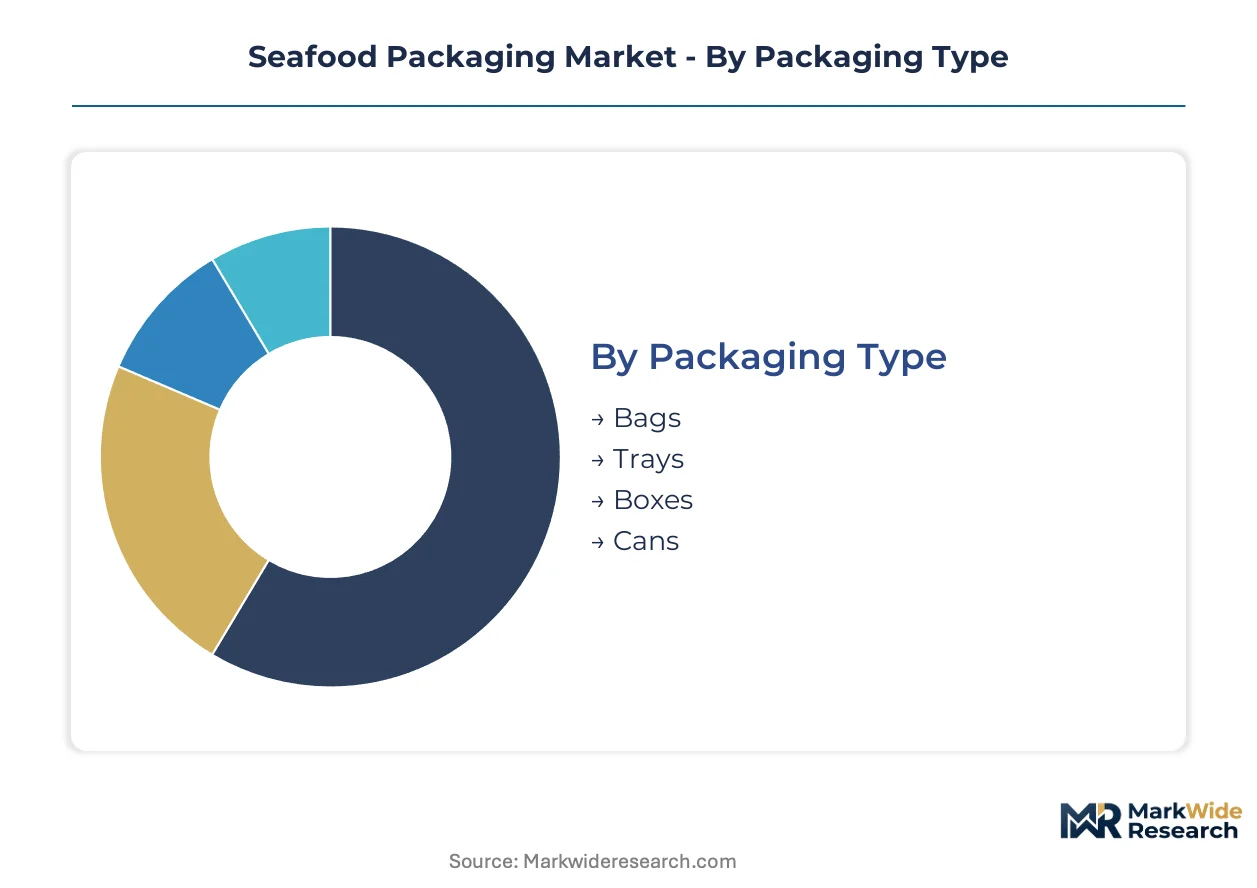
Packaging format selection in seafood markets hinges on cold-chain durability, oxygen barrier performance, and retail presentation requirements. Each segment category reflects distinct technical trade-offs between shelf-life extension, material recyclability, and automated handling compatibility.
Packaging Type:
Upgrade cycles in seafood packaging are accelerating as retail chains consolidate specifications and demand simultaneous barrier improvement and sustainability compliance.
- Trays:Injection-molded polypropylene and expanded polystyrene structures dominate fresh fillet presentation in European retail. German and French supermarket chains are mandating recyclable mono-material alternatives ahead of extended producer responsibility deadlines.
- Bags:High-barrier laminated pouches with EVOH or polyamide cores serve frozen shrimp and value-added seafood exports from China and Vietnam. Cold-chain transit to North American buyers demands puncture resistance exceeding 15 N for ice slurry handling.
- Boxes:Corrugated fiberboard with moisture-resistant coatings supports bulk frozen shipments and direct-to-restaurant distribution. Nordic processors favor wax-alternative barriers for smoked salmon export crates.
- Cans:Tinplate and aluminum containers preserve shelf-stable tuna, sardines, and mackerel for ambient retail. Thailand and Spain operate the largest canning capacities, with double-reduced tinplate specifications dominating premium positioning.
Trays sit at the top of the volume ranking, with skin packaging formats climbing the fastest as premium retailers eliminate drip loss.
Material:
Material selection cost tiers separate commodity frozen formats from premium fresh segments where barrier performance justifies price premiums.
- Plastic:Multilayer films combining polyethylene, polyamide, and EVOH retain dominance across frozen and modified atmosphere applications. REACH restrictions on fluorinated chemistries are redirecting converter R&D toward mineral-filled polyethylene alternatives in Germany and the Netherlands.
- Paper:Molded pulp trays and fiber-based boards are displacing polystyrene in retail-ready fresh segments. EU Single-Use Plastics Directive targets are pulling investment into barrier-coated paper for smoked fish presentation in Scandinavian markets.
- Metal:Tinplate and aluminum sustain ambient shelf-stable categories and retort pouches for ready-to-eat seafood. Canning lines in Thailand and Ecuador concentrate supply for global tuna brands.
- Glass:Premium jar formats preserve marinated herring, anchovies, and specialty seafood in European and Japanese retail. Higher unit costs restrict penetration to gift and gourmet channels.
Plastic commands the largest installed base, with paper gaining share fastest as fiber-based barriers achieve technical validation.
End User:
Customer type determines packaging complexity, with foodservice bypassing retail aesthetic requirements for bulk handling efficiency.
- Retail:Supermarket chains demand case-ready formats with extended case-life and recyclability credentials. Central kitchen proliferation in South Korea and urban China is fragmenting procurement toward pre-portioned, individually quick-frozen specifications.
- Food Service:Restaurants, hotels, and institutional kitchens prioritize bulk vacuum formats with processor-branded labeling over consumer-facing presentation. Ghost kitchen expansion favors cook-in-bag pouch compatibility.
- Wholesale:Distributors serving fish markets and smaller retailers require intermediate bulk packaging with basic barrier protection. Indian coastal states show whitespace for active packaging with time-temperature indicators.
- Direct-to-Consumer:Subscription seafood services and e-commerce platforms demand insulated shipper formats with gel packs and recyclable outer corrugate. Nordic pilot programs test mono-material polyethylene solutions for home delivery.
Retail absorbs the highest packaging value per kilogram, with direct-to-consumer expanding most quickly as cold-chain logistics mature.
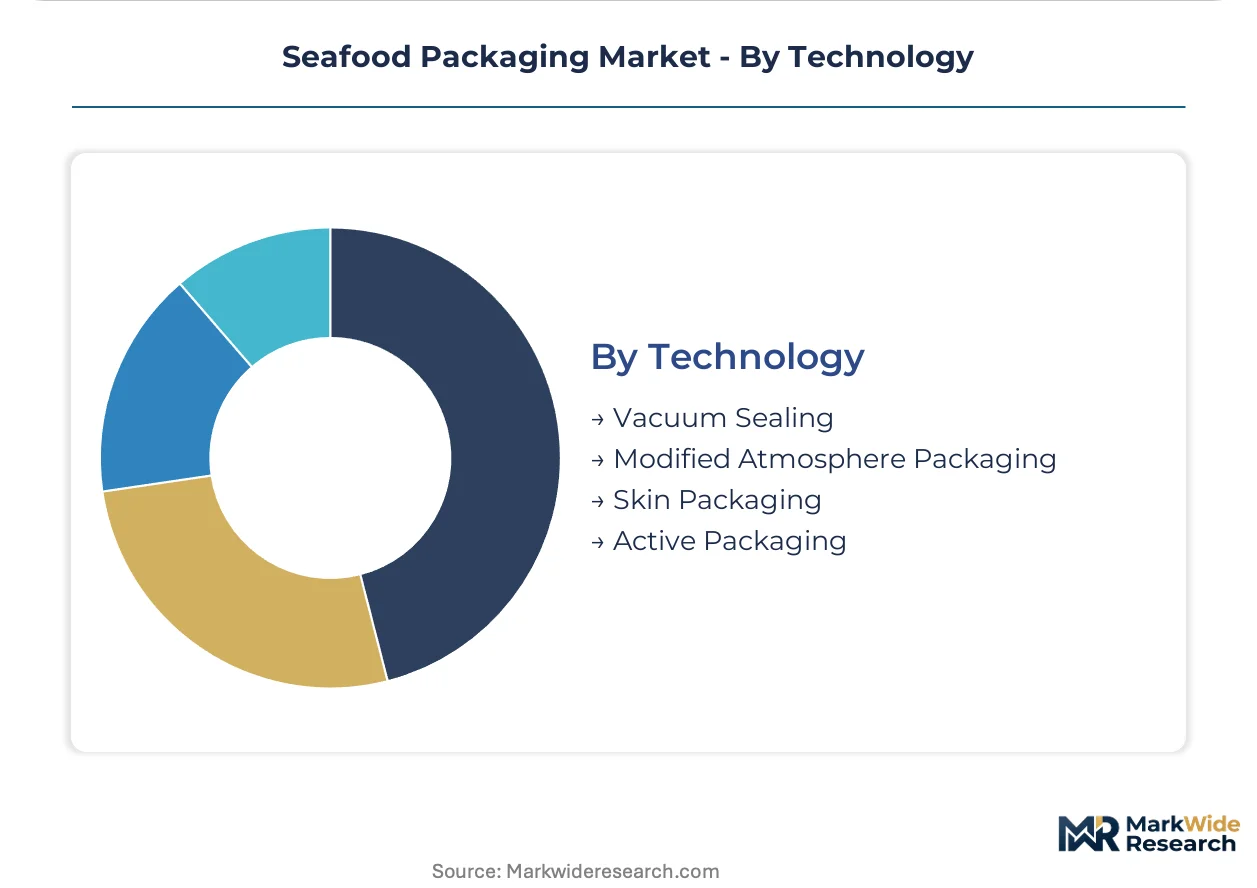
Technology:
Technology maturity curves separate proven modified atmosphere systems from emerging active and intelligent formats.
- Modified Atmosphere Packaging:Gas-flushed trays with tailored CO₂/N₂ ratios dominate fresh fillet and shellfish retail. European retail chains specify residual oxygen below 0.5% for premium salmon and cod portions.
- Vacuum Sealing:Chamber and thermoforming vacuum systems eliminate headspace oxygen for frozen and smoked categories. Chinese processors deploy high-barrier formats for extended transit to European buyers.
- Active Packaging:Oxygen scavengers, moisture regulators, and antimicrobial emitters extend shelf life without refrigeration dependence. Iron-based absorbers embedded in lidding films are gaining traction in French and Belgian fresh segments.
- Skin Packaging:Vacuum skin formats eliminate drip loss and extend retail case-life for whole fish and premium fillets. Nordic chains pilot these structures for marinated herring and smoked salmon.
Modified Atmosphere Packaging holds the largest volume position, with active packaging climbing the fastest as premium retailers seek extended case-life differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting seafood packaging investment toward jurisdictions with lower compliance costs for barrier material transitions. The EU F-Gas Regulation and REACH framework impose stricter migration limits than FDA equivalents, tilting R&D capital toward North American and Asian production bases.
United States
Foodservice distributors and retail chains drive demand for bulk vacuum formats and case-ready trays. FDA food contact notification timelines for novel bio-based coatings extend 12-18 months, delaying commercialization of recyclable alternatives. The Pacific Northwest and Gulf Coast concentrate seafood processing capacity, with Seattle-based converters supplying high-barrier films for Alaskan salmon exports.
Germany
Supermarket chains mandate recyclable mono-material alternatives ahead of extended producer responsibility deadlines. The EU Single-Use Plastics Directive pulls investment into fiber-based tray formats across German retail channels. The Ruhr industrial corridor hosts converter R&D programs redirecting toward mineral-filled polyethylene alternatives to EVOH barriers.
China
Aquaculture output expansion and processed seafood export growth concentrate demand for high-barrier frozen formats. GB standards govern food contact materials with less stringent migration limits than REACH equivalents. The Yangtze River Delta and Shandong Peninsula cluster thermoforming and pouch production for European and North American buyers.
France
Premium fresh fillet retail segments accelerate validation of fluorine-free barrier coatings ahead of 2025 restriction deadlines. ANSM oversees food contact safety alongside EU-wide EFSA frameworks. The Brittany and Normandy coastal regions anchor smoked salmon and marinated herring packaging innovation for Nordic export markets.
Thailand
Canning lines for shelf-stable tuna concentrate supply for global brands. The country's national food regulator applies ASEAN harmonized standards with shorter approval windows than EU equivalents. The Samut Sakhon industrial zone dominates tinplate and aluminum container production for ambient seafood categories.
Seafood Packaging Market Vendor Landscape
North American producers anchor one tier; European specialists hold another through regulatory-compliant material innovation. The vendor base fragments across film converters, rigid container molders, and integrated packaging systems suppliers. Three archetypes dominate: global diversified materials conglomerates, regional barrier film specialists, and foodservice-focused automation integrators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players position for mono-material transition cycles.
Among diversified packaging conglomerates, Amcor, Sealed Air, and Berry Global occupy positions spanning film, rigid, and equipment platforms. Amcor exemplifies the global R&D network archetype, while Sealed Air represents automation-integrated systems positioning. Berry Global anchors the injection-molded container specialization tier within North American and European retail channels.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Berry Global |
| DS Smith |
| Mondi Group |
| Sonoco |
| Winpak |
| Coveris |
| Cascades |
| Others |
Supply Flow & Price Mechanics
Barrier resin feedstock costs, particularly EVOH and polyamide grades, cascade through converter pricing tiers to differentiate premium mono-material films from commodity multi-layer laminates serving frozen shrimp exports.
Pricing Analysis
Distributor margins compress as retail chains consolidate chilled seafood specifications across European and North American channels. Pricing stratifies across premium, standard, and economy tiers based on oxygen barrier certification and volume scale commitments. Cost compression in standard-tier pouches intensifies because Chinese processors leverage GB-standard material costs below REACH-equivalent specifications. Foodservice buyers exhibit highest price sensitivity; premium retailers seeking extended case-life differentiation show lowest.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon goals are reshaping sourcing patterns for barrier film converters. EVOH production clusters in Japan and South Korea; polyamide resin supply draws from Germany and China. Raw material dependencies rest on ethylene feedstocks, mineral nanofillers, and fluorine-free coating chemistries. Single-source vulnerability concentrates in Northeast Asian barrier resin supply. Distribution runs through processor-direct contracts for frozen formats and retail chain specifications for fresh segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in seafood packaging hinges on converter ability to capture premium positioning through mono-material transitions while standard-tier volumes face feedstock cost compression.
For Market Incumbents: Anchor barrier film R&D in mineral-filled polyethylene platforms ahead of EU F-Gas restriction deadlines. Defend position by accelerating FDA food contact notification timelines for bio-based coatings before novel entrants achieve first-mover certification. Capacity addition in Germany's Ruhr corridor secures proximity to supermarket chain specification-setting.
For New Entrants and Emerging Players: Launch via direct-to-restaurant distribution bypassing retail certification barriers. Target Indian coastal states for active packaging with time-temperature indicators where cold-chain underinvestment creates whitespace. Foodservice procurement fragmentation favors processor-branded bulk vacuum formats over consumer-facing presentation requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where converter R&D programs lack mineral-filled barrier validation against REACH-compliant deadlines. Long-term viability favors specialists with captive coating formulation capability and retail chain specification lock-in. Watch Nordic retail chain pilot adoption rates for mono-material polyethylene solutions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film Scale-Up | Converters achieving sub-1 cc/m²/day oxygen transmission without EVOH layers capture recycling-compliant premium positioning. |
| Fluorine-Free Coating Validation | German and Dutch R&D programs accelerating polysaccharide barrier approval ahead of 2025 REACH restriction deadlines secure first-mover advantage. |
| Active Packaging Integration | Iron-based oxygen scavenger embedding in lidding films extends French and Belgian fresh fillet case-life for premium retail differentiation. |
| Foodservice Channel Bypass | Bulk vacuum formats with processor-branded labeling circumvent retail aesthetic specifications and accelerate volume capture. |
| Regional Production Footprint Expansion | Proximity to Yangtze River Delta thermoforming clusters reduces logistics exposure for Chinese export-oriented pouch converters. |
Methodological Framework
Direct dialogue with converter plant managers, seafood processor procurement leads, retail category buyers, and barrier film R&D directors combined with secondary validation from customs trade data, ECHA REACH registration databases, FDA food contact notifications, and SEC filings from diversified packaging conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across material, format, and technology segments.
Segmentation outputs across packaging type, material platform, end-user channel, and preservation technology dimensions informed CAGR derivation through analysis of installed capacity expansion, regulatory compliance cost trajectories, and retail specification migration patterns. Cold-chain infrastructure investment rates and export corridor volume flows served as seafood-specific demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas restriction timelines or EVOH supply disruption scenarios. Forecasts reflect assumptions regarding barrier material substitution rates and mechanical recycling infrastructure buildout. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Poultry Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Oven Bags and Pouches Market