
 Disposable Food Containers Market | 2026-2036
Disposable Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Food Containers Market Outlook
Market Dynamics and Strategic Positioning
Chinese molded fiber producers is recalibrating capacity allocations toward biodegradable foodservice formats. Huhtamaki leverages its integrated fiber-pulp operations across multiple continents to secure raw material continuity. Dart Container Corporation dominates North American foam and plastic container manufacturing through captive resin sourcing. Pactiv Evergreen Inc. specializes in paperboard-based solutions for quick-service and institutional channels.
Product Architecture and Segment Structure
Disposable food containers are single-use receptacles manufactured from plastic resins, paperboard, expanded polystyrene foam, or aluminum sheet, designed for temporary food storage, transport, and consumption without cleaning or return logistics. Clamshells and trays command the largest volume share due to structural integrity requirements for hot and greasy foods. Paper-based materials represent the fastest-expanding segment as foodservice operators preempt regulatory restrictions on conventional plastics. Meal kit end-use channels sustain premium pricing for compartmentalized, oven-safe formats with extended shelf-life barriers.
Regulatory Environment and Strategic Imperatives
The EU F-Gas Regulation and REACH chemical frameworks constrain fluorinated grease-barrier coatings in fiber containers, while the US FDA maintains active compliance programs for food-contact substances under 21 CFR. India's BIS certification mandates and extended producer responsibility proposals under the Plastic Waste Management Rules reshape import and domestic manufacturing requirements. Stakeholders must monitor evolving state-level bans on polystyrene in the US and corresponding compliance deadlines to align product portfolios with enforceable material restrictions.
Market Dynamics
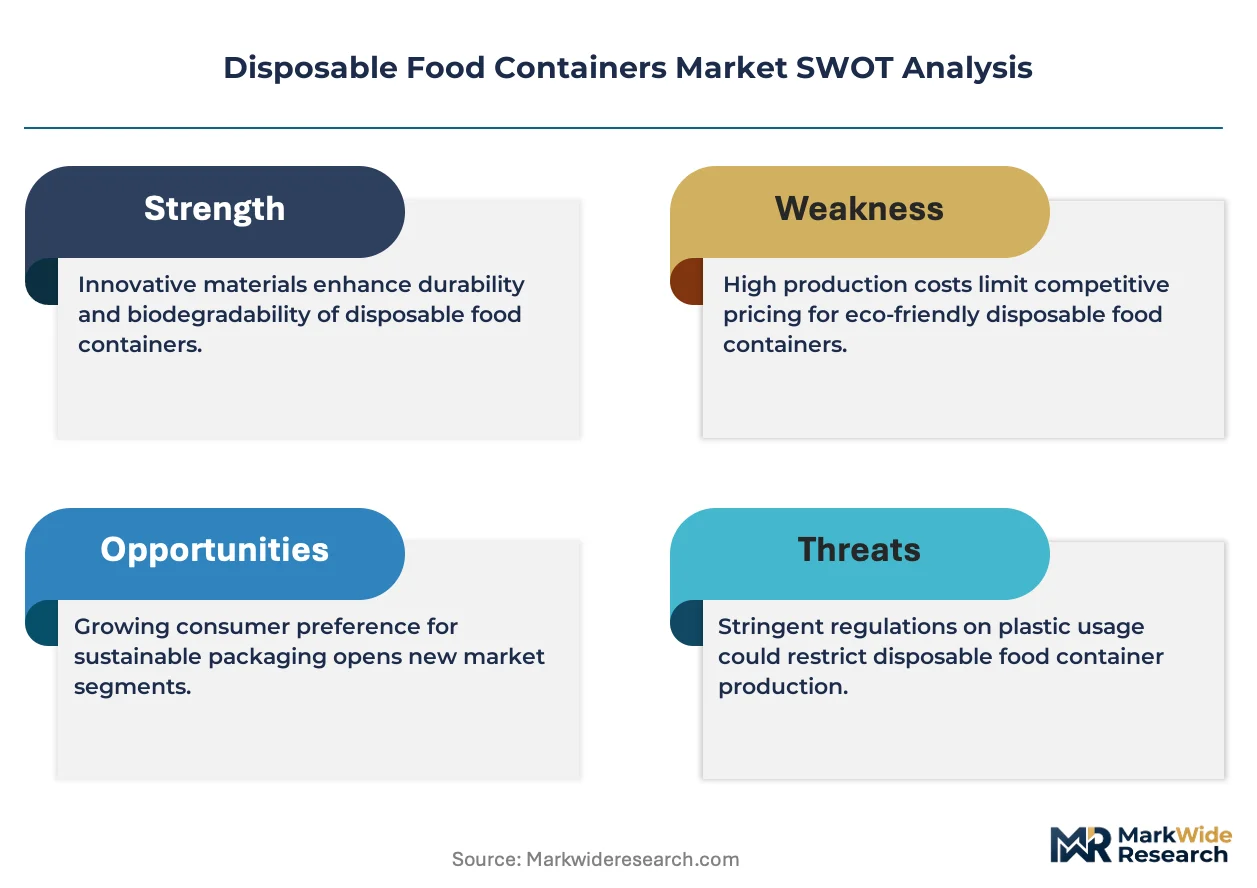
The EU Single-Use Plastics Directive is compressing demand for conventional polystyrene and polypropylene formats while simultaneously pulling capital toward molded fiber and bio-based polymer alternatives. This regulatory compression is redrawing competitive boundaries between incumbent resin processors and emerging pulp-molding specialists.
Growth Catalysts
- Cloud Kitchen Proliferation:Delivery-optimized container demand from India and Southeast Asia's ghost kitchen networks is pulling clamshell and compartmentalized tray volumes upward.
- F-Gas Regulation:The EU framework restricting fluorinated grease barriers is accelerating migration toward PFAS-free fiber formulations and plant-based barrier coatings.
- Street Food Formalization:India's vendor licensing programs and food safety mandates are replacing loose plastic bags with certified disposable containers across urban food corridors.
Market Restraints
- Pulp Price Volatility:Recycled fiber and agricultural residue supply fluctuations in China and Southeast Asia are compressing margins for molded fiber producers.
- Oil-Linked Resin Costs:Polypropylene and polystyrene input costs track crude benchmarks, exposing foam container manufacturers to energy market swings.
- Barrier Performance Gap:Current bio-based grease barriers fail hot-oil containment tests above 85°C, limiting fiber tray adoption for fried food segments.
Strategic Opportunities
- Meal Kit Channel Expansion:Oven-safe, multi-compartment formats with extended shelf-life barriers command premium positioning in subscription foodservice.
- Extended Producer Responsibility:India's proposed EPR mandates under Plastic Waste Management Rules will consolidate market share toward certified domestic manufacturers.
- Aluminum Sheet Convergence:Heat-sealable aluminum formats are capturing premium ready-meal segments where microwave-ability and barrier performance outweigh cost.
Industry Challenges
- Composting Infrastructure Mismatch:Industrial composting facility scarcity in the US and India leaves biodegradable containers without viable end-of-life pathways.
- REACH Compliance Timelines:Chemical substance notification requirements for novel barrier coatings are extending product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Food Containers Market |
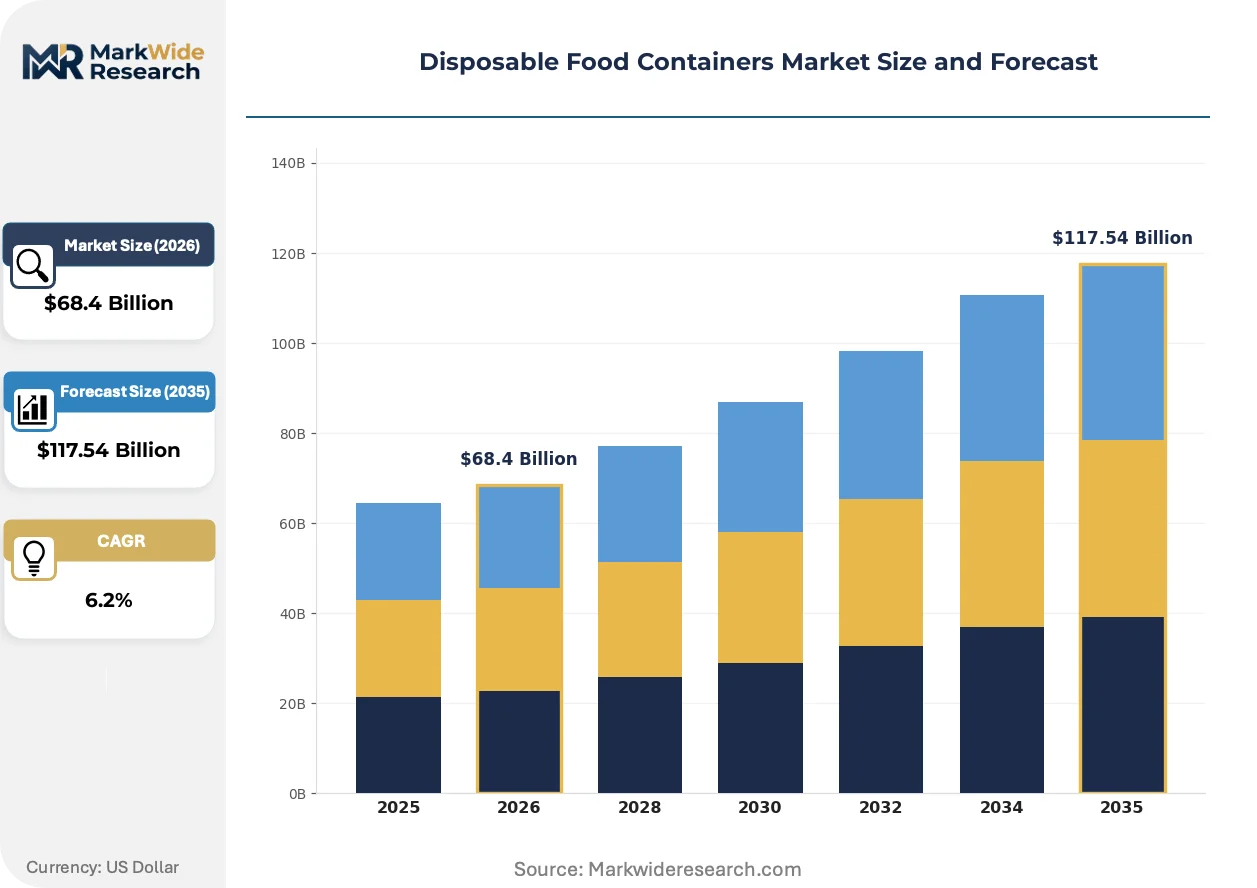
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Trays, Clamshells Material: Plastic, Paper, Foam, Aluminum End Use: Foodservice, Retail, Catering, Meal Kits Size: Small, Medium, Large, Extra Large |
| Companies Covered | Huhtamaki, Dart Container Corporation, WestRock, Pactiv Evergreen Inc., Genpak LLC, Berry Global Inc., Novolex Holdings, LLC, Sealed Air Corporation, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Food Containers Market Strategic Shifts
Active packaging technologies and regulatory chemistry restrictions are converging to reshape material selection and manufacturing processes across disposable foodservice formats. These forces are compressing legacy supply chains while opening white space for bio-based alternatives.
Barrier-coated molded fiber is decentralizing container manufacturing away from centralized resin pellet processing toward distributed pulp-molding facilities. Quick-service chains in Germany and France are specifying PFAS-free formats for 2025 menu rollouts. This geographic and technical shift is compressing lead times for regional foodservice operators while fragmenting supply relationships previously dominated by petrochemical container producers.
REACH chemical frameworks are constraining fluorinated grease-barrier coatings in fiber containers across EU member states. The regulation is forcing reformulation toward silicone, clay, and plant-based alternatives. Hot-food tray segments in France and Italy are absorbing compliance costs through supplier qualification programs that exclude non-compliant Asian imports.
Direct sourcing from molded fiber producers is displacing distributor-mediated procurement among large quick-service chains. Institutional buyers in India and Germany are establishing supplier development programs with captive volume commitments. This channel compression is most visible in cloud kitchen networks where packaging represents 8-12% of cost structure and standardization drives consolidation toward single-source relationships.
Disposable Food Containers Market Segmentation
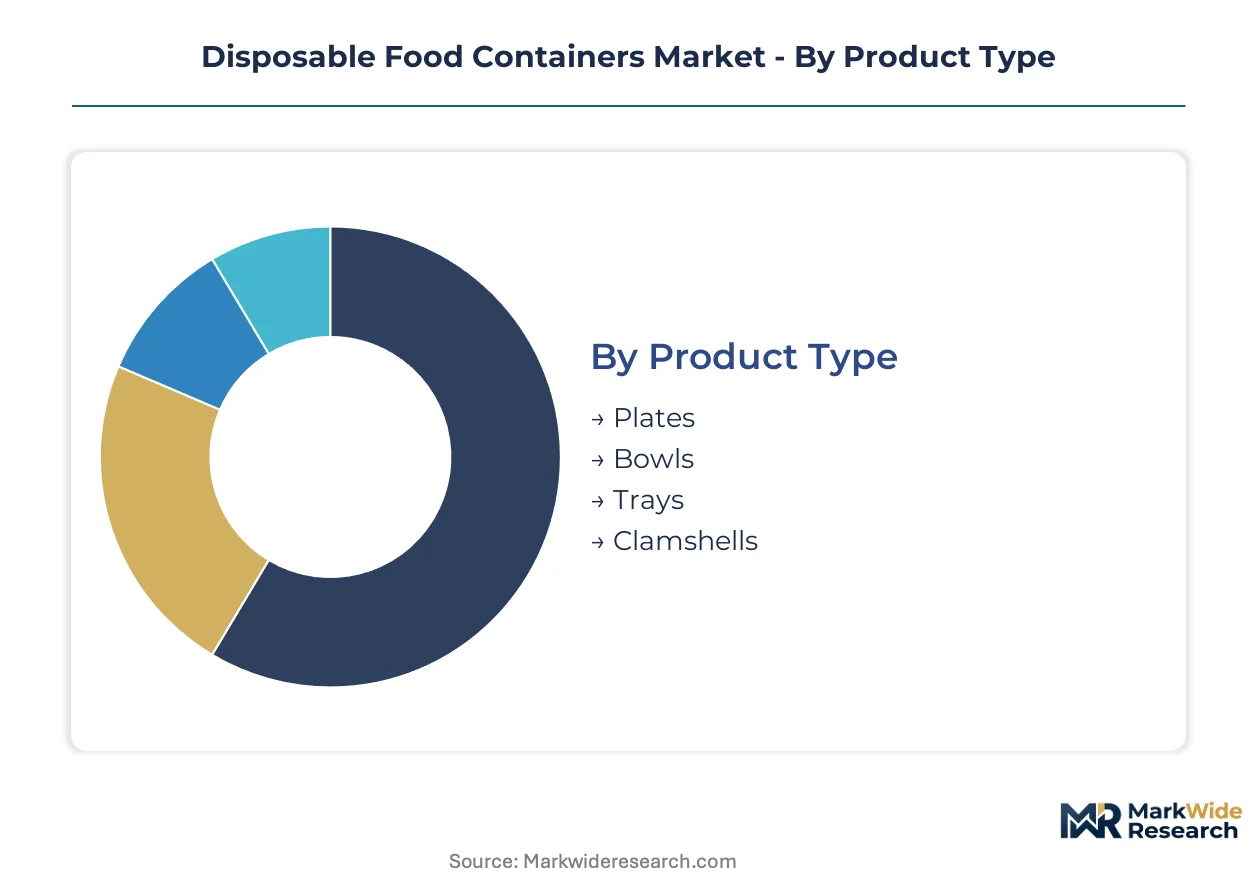
Disposable food container procurement diverges sharply across operator types, from standardized quick-service specifications to bespoke meal kit configurations. Material selection and format geometry cascade through cost structures, regulatory compliance, and end-of-life pathways in ways that reshape supplier relationships.
Product Type:
Standardization dominates high-volume formats while customization concentrates in premium segments requiring structural reinforcement or thermal management.
- Clamshells:Hinged-lid designs with integrated locking mechanisms provide structural integrity for hot, greasy foods during transport. Quick-service chains across India and Southeast Asia specify clamshells for fried protein and rice combinations, with hinge durability emerging as a key qualification criterion for vendor selection.
- Trays:Flat-bottomed, rimmed configurations accommodate compartmentalization for protein-starch-vegetable combinations. Meal kit operators in Germany and France source oven-safe tray formats with extended shelf-life barriers, where multi-compartment designs command supplier development programs with captive volume commitments.
- Plates:Single-use flatware for immediate consumption settings with minimal barrier requirements.
- Bowls:Curved-wall formats for liquid and semi-liquid foods, common in soup and noodle applications across East Asian foodservice.
Most installed capacity flows through clamshells. Expansion is steepest in trays.
Material:
Cost tiers separate petrochemical-derived formats from fiber-based alternatives, with aluminum occupying a narrow premium position where performance outweighs unit economics.
- Paper:Molded fiber and paperboard formats with barrier coatings are preempting regulatory restrictions on conventional plastics across EU member states. REACH constraints on fluorinated grease barriers are accelerating reformulation toward silicone, clay, and plant-based alternatives, with hot-food segments in France and Italy absorbing compliance costs through supplier qualification programs.
- Plastic:Polypropylene and polystyrene resins dominate North American foam and rigid container manufacturing, with input costs tracking crude oil benchmarks. The EU Single-Use Plastics Directive is compressing demand for these formats while pulling capital toward bio-based polymer alternatives.
- Foam:Expanded polystyrene formats face accelerating bans across US states and corresponding compliance deadlines that fragment regional supply availability.
- Aluminum:Heat-sealable sheet formats capture premium ready-meal segments where microwave-ability and barrier performance outweigh cost considerations in subscription foodservice channels.
Volume concentrates in plastic. The steepest expansion trajectory belongs to paper.
End Use:
Customer type determines procurement scale and standardization pressure, from fragmented street vendor purchases to consolidated cloud kitchen contracts.
- Foodservice:Quick-service chains, institutional cafeterias, and independent restaurants generate the largest absolute demand, with direct sourcing from molded fiber producers displacing distributor-mediated procurement among large chains in Germany and India.
- Meal Kits:Subscription foodservice operators specify oven-safe, multi-compartment formats with extended shelf-life barriers, where packaging represents 8-12% of cost structure and standardization drives consolidation toward single-source relationships.
- Retail:Supermarket deli and prepared food sections require display-optimized formats with print compatibility for branding and regulatory labeling.
- Catering:Event and institutional catering demands volume scalability with varying thermal retention requirements across service formats.
Foodservice commands the largest installed base. Meal kits are climbing the fastest.
Size:
Volume scale and geographic application patterns separate commodity small formats from specialized large configurations requiring custom tooling.
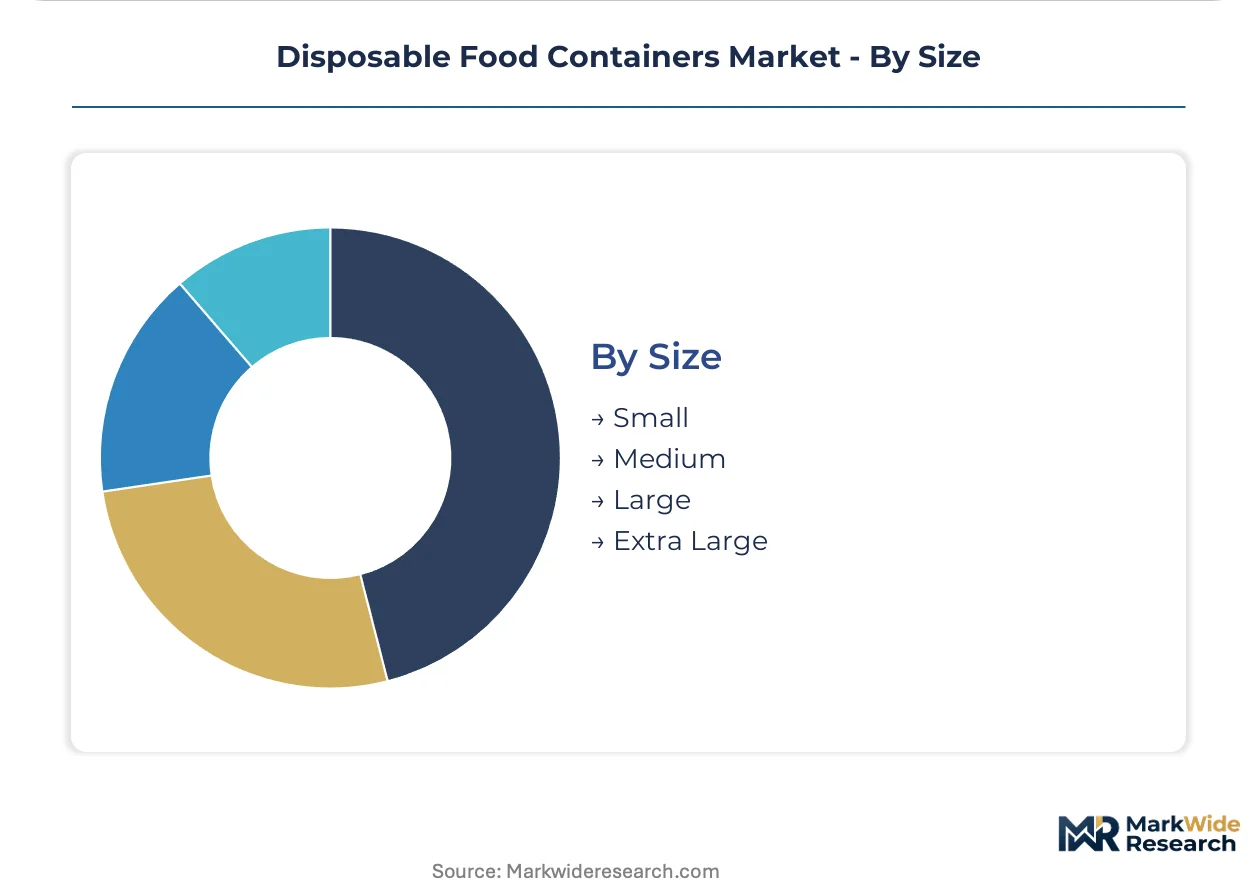
- Medium:Standard portion formats for single-serve meals dominate procurement volumes across quick-service and institutional channels, with dimensional standardization enabling equipment interoperability across global supply chains.
- Large:Family-size and shared-portion configurations concentrate in catering and retail deli applications, where structural load-bearing requirements drive material thickness specifications and corresponding cost premiums.
- Small:Condiment, sauce, and side-dish formats with minimal structural requirements.
- Extra Large:Bulk catering and institutional tray formats with reinforced sidewalls for transport stability.
Medium sizes absorb most capacity. Large formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks diverging compliance costs between jurisdictions. Molded fiber capacity is clustering in Southeast Asia and India where EPR obligations remain lighter than EU mandates. Resin-based manufacturing retains footholds in North American and Gulf state markets with less restrictive single-use plastic timelines.
United States
State-level polystyrene bans in California, New York, and Maine are fragmenting regional supply availability. The FDA maintains 21 CFR compliance programs for food-contact substances while EPA enforcement targets PFAS contamination in paper-based formats. Manufacturing concentrates in the Southeast industrial corridor where resin processors serve quick-service chains with standardized clamshell specifications.
Germany
Quick-service chains are specifying PFAS-free fiber formats for 2025 menu rollouts under REACH constraints. The F-Gas Regulation restricts fluorinated grease-barrier coatings, accelerating reformulation toward silicone and clay alternatives. Production clusters in Baden-Württemberg and Bavaria where pulp-molding facilities supply institutional buyers through direct sourcing relationships.
India
Cloud kitchen networks in Mumbai and Bangalore are pulling clamshell volumes upward as packaging represents 8-12% of operator cost structures. BIS certification mandates and proposed EPR frameworks under Plastic Waste Management Rules reshape import requirements. Street food vendor licensing programs in Delhi-NCR are replacing loose plastic bags with certified disposable containers.
China
Molded fiber producers in Zhejiang and Guangdong are recalibrating capacity toward biodegradable foodservice formats for export markets. GB standards and dual carbon goals pressure domestic manufacturers toward fiber-based alternatives. The Yangtze River Delta hosts concentrated pulp-molding capacity serving European buyers navigating REACH compliance timelines.
Vietnam
Quick-service expansion in Ho Chi Minh City and Hanoi drives tray and clamshell demand from regional ghost kitchen networks. Import substitution policies favor domestic molded fiber production over resin-based formats. The Mekong Delta agricultural residue supply supports emerging pulp-molding facilities targeting EU export channels.
Disposable Food Containers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue fiber-based and bio-polymer specializations. The market structures around three maturity tiers: integrated resin processors with captive raw material access, regional pulp-molding specialists scaling distributed manufacturing, and niche aluminum format providers serving premium ready-meal segments. Consolidation pressures concentrate among mid-scale foam container manufacturers facing state-level bans. Dominant competitive moves include backward integration into agricultural residue sourcing and geographic expansion through supplier development programs with captive volume commitments.
Among integrated packaging conglomerates, Huhtamaki and Dart Container Corporation exemplify divergent strategic positions. Huhtamaki occupies a fiber-pulp integration archetype across multiple continents. Dart Container Corporation anchors resin-based manufacturing dominance in North American markets. Pactiv Evergreen Inc. sits within the paperboard specialization tier serving institutional and quick-service channels.
| Leading Market Players |
|---|
| Huhtamaki |
| Dart Container Corporation |
| WestRock |
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Berry Global Inc. |
| Novolex Holdings, LLC |
| Sealed Air Corporation |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
The EU Single-Use Plastics Directive gates qualified supply and premium-tier pricing access for fiber-based formats, compressing margins for non-compliant resin processors while rewarding certified molded fiber producers with preferred supplier status among quick-service chains. Buyers absorb compliance premiums through direct sourcing relationships that bypass distributor markups.
Pricing Analysis
Distributor margins of 15-25 percent for conventional resin-based containers are compressing as institutional buyers in Germany and India establish direct procurement channels with molded fiber producers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant PFAS-free formats from transitional silicone-barrier products and conventional plastic alternatives. Cost compression in standard-tier foam containers is intensifying because state-level polystyrene bans fragment regional supply availability. Cloud kitchen operators exhibit highest price sensitivity due to packaging representing 8-12 percent of cost structure, while meal kit subscription services accept premium positioning for oven-safe multi-compartment formats.
Supply Chain Analysis
Returns and end-of-life collection flows remain underdeveloped for biodegradable containers, leaving industrial composting infrastructure gaps that strand fiber-based formats without viable disposal pathways. Manufacturing concentrates in China, India, and Vietnam where pulp-molding capacity clusters near agricultural residue supplies and export-oriented logistics hubs. Raw material dependencies draw from recycled fiber streams, bagasse and bamboo agricultural residues, and bio-based barrier coatings. Single-source vulnerability concentrates in fluorinated grease-barrier chemistries facing REACH restriction. Distribution runs through quick-service chain direct procurement programs and institutional supplier development agreements with captive volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable food containers market functions as a stable compounder where regulatory-driven material substitution sustains steady growth through compliance-mandated procurement cycles.
For Market Incumbents: Extend fiber-pulp integration into agricultural residue sourcing across Southeast Asia to secure raw material continuity against pulp price volatility. Add captive molding capacity in India ahead of BIS certification mandates and proposed extended producer responsibility frameworks that will consolidate market share toward certified domestic manufacturers. Defend against emerging pulp-molding specialists by qualifying PFAS-free barrier formulations before 2025 menu rollouts lock in supplier relationships. For New Entrants and Emerging Players: Capture cloud kitchen network procurement in Mumbai and Bangalore where standardization pressure drives single-source consolidation and packaging represents outsized cost structure exposure. Target Vietnam's quick-service expansion corridor where import substitution policies favor domestic molded fiber production over resin-based formats. Enter through supplier development programs offering captive volume commitments and technical assistance on BIS certification pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale foam container manufacturers facing accelerating state-level bans and corresponding compliance deadline pressures. Long-term viability over the next decade favors integrated fiber-pulp operators with multi-continent raw material access and qualified supply relationships with REACH-compliant barrier coating formulators. Monitor EU F-Gas Regulation enforcement timelines and corresponding PFAS-free formulation qualification rates as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Sourcing | Secures bagasse and bamboo supply continuity for molded fiber producers facing pulp price volatility in Southeast Asia. |
| PFAS-Free Barrier Formulation Qualification | Unlocks preferred supplier status with German and French quick-service chains specifying compliant formats for menu rollouts. |
| Supplier Development Programs with Captive Volume | Consolidates procurement relationships with Indian cloud kitchen networks where packaging drives 8-12 percent of cost structure. |
| Multi-Compartment Oven-Safe Format Development | Captures premium positioning in meal kit subscription channels requiring extended shelf-life barriers and thermal performance. |
| BIS Certification and EPR Compliance Investment | Positions domestic Indian manufacturers to benefit from Plastic Waste Management Rules consolidating import substitution. |
Study Parameters
Multiple input streams — executive interviews with quick-service chain procurement directors, molded fiber plant managers, and regulatory compliance officers; secondary validation through customs trade data, SEC filings of integrated packaging conglomerates, and EU REACH substance notification databases; plus field documentation of pulp-molding facility capacity expansions — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation across product type, material composition, end-use channel, and geographic production hub dimensions anchored volume and value outputs throughout the forecast period. CAGRs were derived from regression analysis of historical procurement patterns and regulatory compliance timeline impacts. Forecast inputs incorporated cloud kitchen network expansion trajectories, state-level polystyrene ban implementation schedules, and REACH chemical framework enforcement intensity.
Underlying measurement precision varies by segment; clamshell and tray product types carry tighter precision than emerging aluminum sheet formats due to established procurement reporting. Forecasts reflect assumptions about regulatory enforcement consistency and composting infrastructure development timelines. Practitioners should monitor EU F-Gas Regulation amendment proposals and Indian EPR framework finalization for early signals of competitive boundary shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Burger Boxes Market
Food Packaging
Produce Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Food Punnets Market