
 Cardiac Patch Monitor Market | 2026-2036
Cardiac Patch Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Patch Monitor Market Analytics
Remote data service revenue is reshaping profitability models in cardiac monitoring, pulling margin pools away from hardware sales toward subscription-based arrhythmia interpretation. iRhythm Technologies dominates this transition through its cloud-based diagnostic platform and proprietary AI-assisted analysis workflow. Koninklijke Philips N.V. leverages its hospital installed base and imaging integration to sustain enterprise-level contracts. VitalConnect specializes in multi-parameter biosensing patches that extend monitoring beyond single-lead electrocardiography into respiratory and temperature metrics.
A cardiac patch monitor is an adhesive, body-worn biosensor that captures electrophysiological signals through skin-contact electrodes, typically operating for seven to fourteen days on a single disposable unit, with wireless transmission to centralized diagnostic platforms for clinician review. The device eliminates lead wires and recorder boxes, enabling ambulatory patients to maintain normal activity during extended monitoring periods while reducing artifact from patient motion. Wearable patches and wireless monitors together command the dominant revenue share, though bioelectronic devices incorporating closed-loop therapeutic response represent the fastest-expanding margin pool as neuromodulation and drug delivery converge with sensing platforms. Home care and hospitals split end-user volume, with ambulatory surgical centers emerging as a high-velocity channel for pre- and post-procedure monitoring.
FDA premarket notification requirements under 21 CFR 870.2300 govern patch monitor safety and efficacy, while CMS national coverage determinations for extended external electrocardiographic monitoring directly shape reimbursement-driven demand curves. The EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa cardiac monitoring devices, lengthening approval timelines but raising barriers to low-quality entrants. Stakeholders must monitor evolving cybersecurity guidance from FDA and Health Canada as patch monitors integrate with cloud infrastructure and hospital networks, since data integrity breaches could trigger coverage restrictions or liability exposure that outweighs device performance advantages.
Market Dynamics
Subscription-based diagnostic platforms are displacing capital-intensive hardware sales, compressing upfront equipment margins while extending customer lifetime value through recurring interpretation fees and algorithmic risk stratification services.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated premarket notification pathways for extended-wear electrocardiography devices reduce time-to-market for novel patch designs, enabling faster clinical adoption cycles.
- Home care settings:Remote patient monitoring mandates from United States health systems under value-based care contracts favor ambulatory patch deployment over traditional inpatient telemetry.
- Cloud infrastructure:Scalable diagnostic platforms enable real-time arrhythmia detection algorithms that reduce specialist interpretation burden and expand monitoring capacity.
Market Restraints
- Silver and conductive polymer cost volatility:Electrode material inputs face supply concentration from East Asian chemical processors, compressing gross margins on disposable patch units.
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for Class IIa cardiac devices lengthen approval timelines and raise compliance expenditures for market entrants.
- Smartwatch single-lead ECG substitution:Consumer-grade atrial fibrillation detection from wearable technology vendors erodes demand for short-term diagnostic patches in low-risk patient stratification.
Strategic Opportunities
- Multi-parameter biosensing convergence:Integration of respiratory rate, temperature, and accelerometry into cardiac patches creates differentiated monitoring platforms for post-surgical recovery protocols.
- Ambulatory surgical centers:Pre- and post-procedure monitoring channels remain underpenetrated relative to hospital cardiology departments, offering volume expansion outside saturated electrophysiology markets.
- CMS national coverage determinations:Reimbursement expansion for extended external electrocardiographic monitoring under Medicare fee schedules accelerates physician prescribing behavior in United States outpatient settings.
Industry Challenges
- Cybersecurity engineering talent scarcity:Patch-to-cloud data transmission architectures require specialized firmware expertise that competes with broader medical device and consumer electronics sectors.
- Health system EHR integration complexity:Proprietary data formats from diagnostic platform vendors create interoperability friction with Epic and Cerner installations, delaying enterprise contract finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Patch Monitor Market |
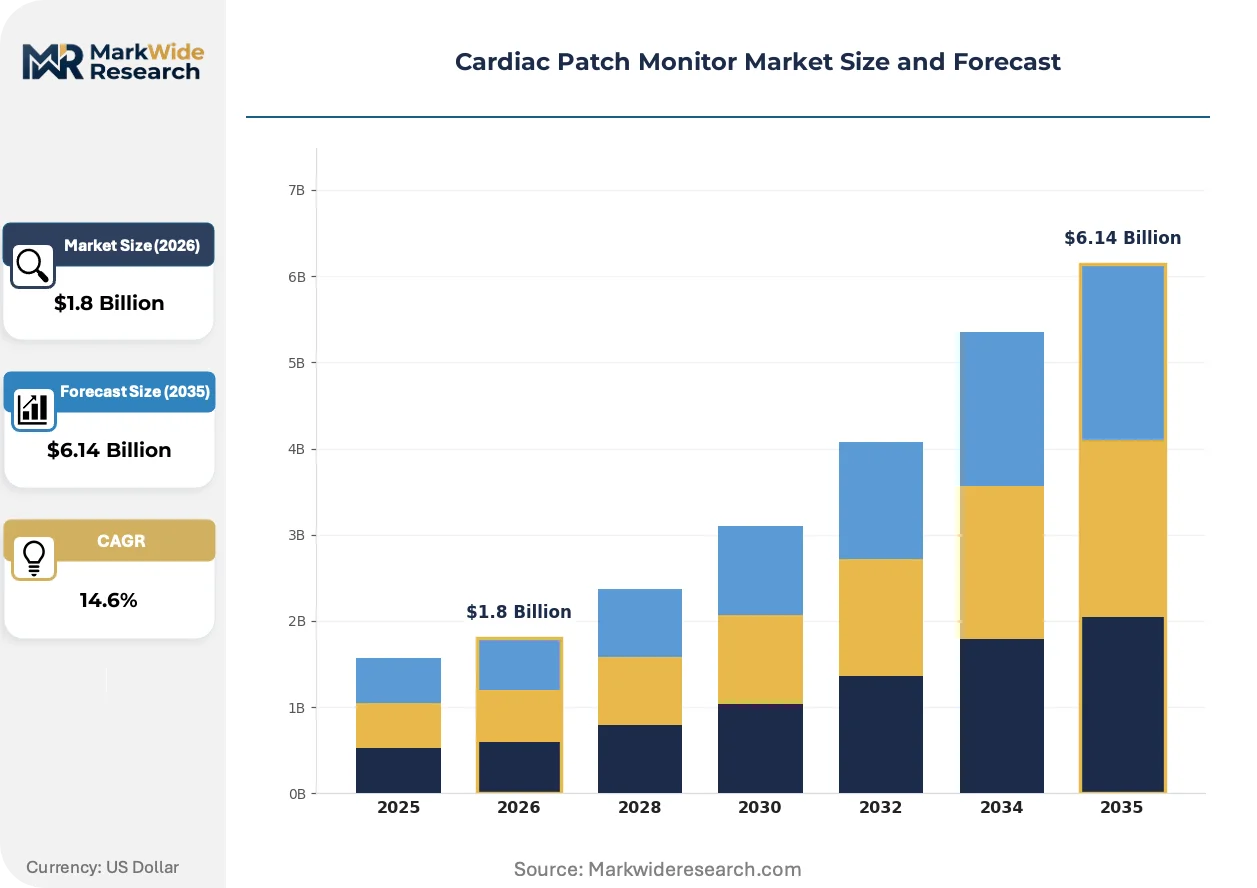
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Monitors, Wearable Patches, Smart Bandages, Bioelectronic Devices Technology: Electrocardiography, Biotelemetry, Signal Processing, Data Analytics End User: Hospitals, Home Care, Ambulatory Surgical Centers, Research Institutions Application: Arrhythmia Monitoring, Patient Rehabilitation, Heart Failure Management, Telemedicine |
| Companies Covered | iRhythm Technologies, Koninklijke Philips N.V., VitalConnect, LifeSignals, Baxter International, Mawi Inc., SmartCardia, Cardiac Insight, Zywie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Patch Monitor Market Evolving Landscape
Artificial intelligence-assisted interpretation workflows are compressing diagnostic turnaround times while expanding the addressable patient population beyond traditional cardiology referrals into primary care screening protocols.
Closed-loop neuromodulation patches is hybridizing sensing and therapeutic functions into single disposable units, enabling automatic vagal nerve stimulation in response to detected atrial arrhythmias. Electrophysiology departments in tertiary United States hospitals are piloting these bioelectronic devices for post-ablation monitoring. This convergence is compressing the distinction between diagnostic and interventional cardiac devices, creating new regulatory classification challenges for FDA reviewers.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic clinical follow-up data collection from patch monitor recipients. Manufacturers must now maintain active implant registries and periodic safety update reports that extend far beyond legacy vigilance obligations. Cardiac monitoring specialists with limited European notified body relationships face disproportionate compliance burdens relative to diversified device conglomerates.
Hospital procurement committees are unbundling hardware acquisition from interpretation service contracts, forcing diagnostic platform vendors to compete on software subscription terms rather than device placement economics. United States integrated delivery networks now separately negotiate patch supply agreements and cloud-based analysis fees, compressing vendor pricing power. This bifurcation is most visible in California and Texas health systems where value-based care penetration exceeds national averages.
Cardiac Patch Monitor Market Segmentation
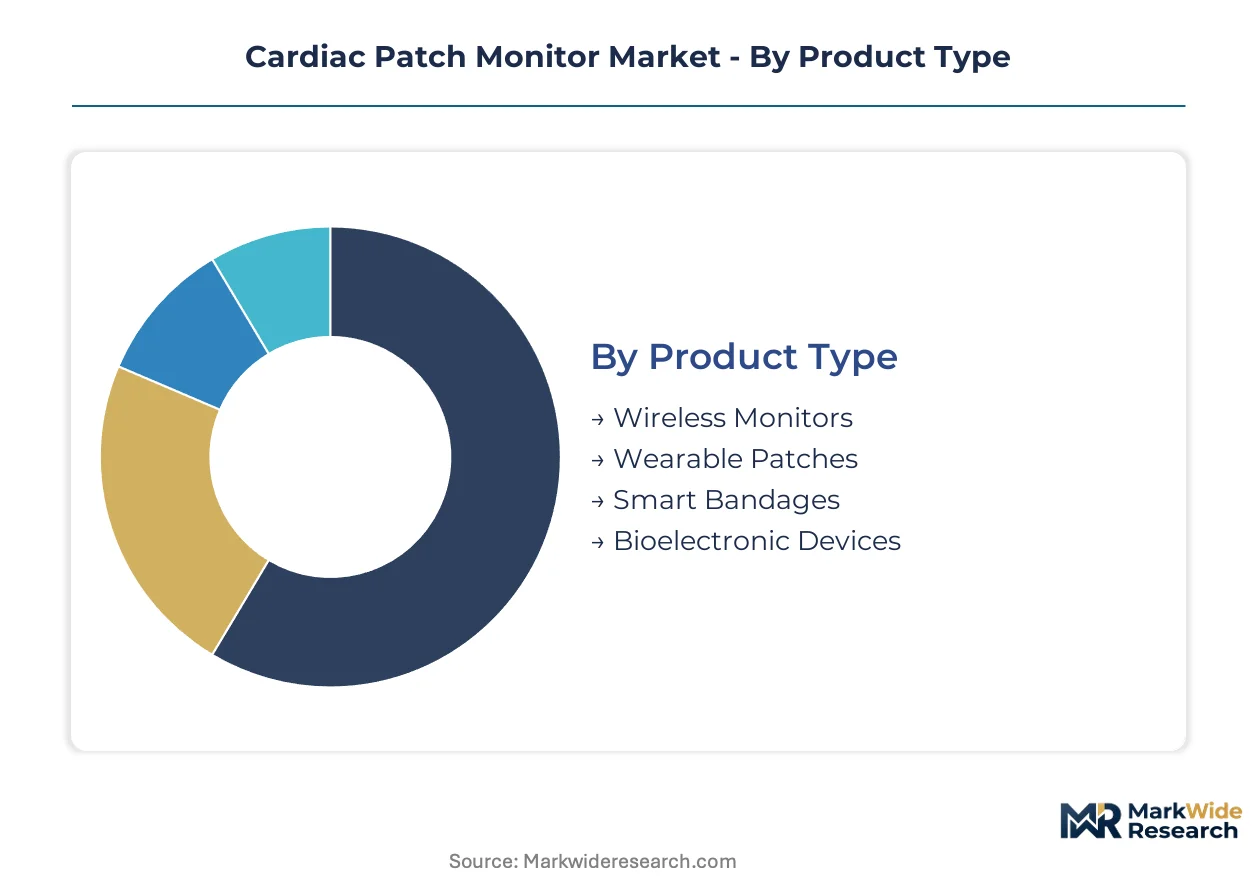
Cardiac patch monitor vendors pursue divergent margin strategies across product architectures and service delivery models. Segment boundaries blur as hardware platforms integrate cloud-based interpretation workflows and multi-parameter sensing capabilities.
Product Type:
After-sales service intensity varies sharply across disposable versus durable form factors, with recurring data interpretation fees dominating profitability in adhesive-based systems.
- Wireless Monitors:These rechargeable, multi-day recording devices transmit electrocardiographic data through Bluetooth or cellular protocols to centralized diagnostic platforms. Demand concentrates in United States hospital cardiology departments where extended monitoring protocols require 14-30 day continuous recording beyond Holter limitations. CMS reimbursement pathways for external electrocardiographic monitoring directly shape prescribing volume.
- Wearable Patches:Single-use adhesive biosensors integrate skin-contact electrodes with compact onboard storage and wireless transmission modules. Home care settings in the United States drive volume expansion as value-based care contracts mandate remote arrhythmia detection to reduce emergency department utilization. FDA 510(k) clearance timelines determine competitive positioning.
- Smart Bandages:Flexible substrate-based monitors incorporate printed electronics for conformal skin contact during activity-intensive monitoring periods.
- Bioelectronic Devices:Hybrid sensing-therapeutic platforms merge diagnostic capture with closed-loop neuromodulation response.
Wearable patches hold the largest share; momentum sits with bioelectronic devices.
Technology:
Cost tier differentiation separates premium AI-assisted interpretation platforms from commodity signal acquisition components.
- Electrocardiography:Single-lead and multi-lead electrode configurations capture cardiac electrical activity through skin-contact interfaces, with signal fidelity determining diagnostic utility for atrial fibrillation detection. United States electrophysiology laboratories specify 12-lead equivalent vector reconstruction for pre-ablation mapping.
- Biotelemetry:Real-time wireless transmission architectures enable immediate clinician notification of critical arrhythmias without patient action. Ambulatory surgical centers in Texas and California deploy these systems for post-procedure monitoring where rapid response protocols reduce readmission penalties.
- Signal Processing:Analog-to-digital conversion and noise filtering algorithms extract usable cardiac signals from motion artifact and electromagnetic interference.
- Data Analytics:Cloud-based algorithmic interpretation reduces specialist review burden through automated rhythm classification and risk stratification scoring.
Electrocardiography holds the largest share; data analytics is climbing the fastest.
End User:
Volume concentration varies by care setting reimbursement structure and patient acuity requirements.
- Hospitals:Inpatient telemetry units and outpatient cardiology departments deploy patch monitors for diagnostic workup of syncope, palpitations, and cryptogenic stroke evaluation. United States integrated delivery networks negotiate enterprise contracts spanning multiple facilities.
- Home Care:Remote patient monitoring programs dispatch disposable patches directly to ambulatory patients for extended wear periods without clinical site visits. Medicare Advantage plans in Florida and Arizona expand coverage for home-based arrhythmia detection to reduce acute care utilization.
- Ambulatory Surgical Centers:Pre-operative risk stratification and post-discharge surveillance protocols drive patch deployment for cardiac clearance.
- Research Institutions:Clinical trial sponsors utilize patch monitors for continuous safety monitoring in cardiovascular drug development.
Hospitals hold the largest share; home care is gaining share fastest.
Application:
Customer type segmentation separates diagnostic screening from chronic disease management workflows.
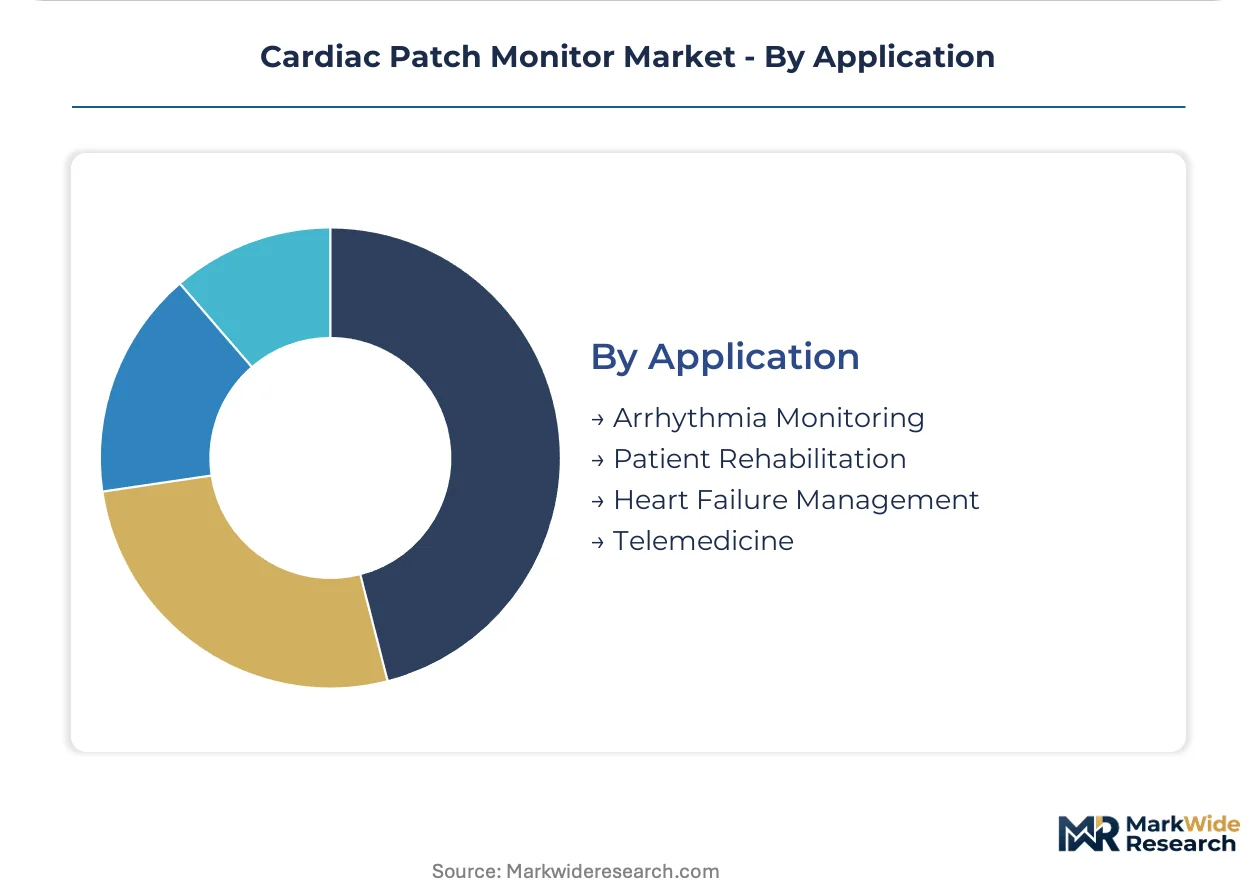
- Arrhythmia Monitoring:Extended electrocardiographic recording detects intermittent atrial fibrillation, ventricular tachycardia, and conduction abnormalities that elude short-duration testing. United States primary care networks adopt patch-based screening for stroke prevention in undiagnosed populations.
- Patient Rehabilitation:Post-cardiac surgery and post-myocardial infarction recovery protocols utilize patches to assess autonomic function and exercise tolerance. Cardiac rehabilitation centers in Pennsylvania and Ohio integrate patch data into personalized activity prescriptions.
- Heart Failure Management:Multi-parameter sensing tracks fluid status through impedance measurements and respiratory rate trends.
- Telemedicine:Asynchronous diagnostic platforms enable specialist interpretation without synchronous patient-clinician interaction.
Arrhythmia monitoring holds the largest share; telemedicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems demonstrate the lowest price elasticity for cardiac patch monitors, absorbing premium subscription fees through value-based care contracts, while emerging markets in Asia-Pacific and Latin America remain acutely sensitive to per-unit hardware costs and disposable electrode pricing.
United States
Integrated delivery networks in California and Texas drive enterprise-level adoption of cloud-based diagnostic platforms. FDA 510(k) clearance pathways for extended-wear electrocardiography devices accelerate commercialization timelines relative to European counterparts. The Minneapolis-St. Paul corridor hosts concentrated medical device manufacturing clusters where patch electrode production scales for domestic distribution.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia prioritize CE-marked devices with integrated EHR interoperability. EU MDR post-market surveillance obligations for Class IIa cardiac devices impose systematic clinical follow-up requirements that lengthen approval timelines. The MedTech cluster around Tübingen-Reutlingen advances printed electronics research for conformal biosensor substrates.
China
Domestic manufacturers in the Yangtze River Delta exploit cost advantages in silver electrode processing and flexible circuit fabrication. NMPA regulatory harmonization with international standards accelerates approval of imported diagnostic platforms while protecting local assembly operations. Shenzhen's electronics ecosystem supplies wireless transmission modules to regional patch monitor assemblers.
Japan
Aging demographics in the Kanto region expand demand for home-based arrhythmia detection reimbursed under public health insurance. PMDA clinical evidence requirements emphasize long-term safety data for adhesive skin-contact devices worn beyond fourteen days. Osaka-based medical device distributors negotiate exclusive territorial rights for imported patch platforms.
India
Private hospital chains in Maharashtra and Karnataka deploy patch monitors for pre-operative cardiac clearance in tier-1 cities. CDSCO import licensing requirements for Class B medical devices create regulatory friction for multinational vendors without local manufacturing partnerships. The medical electronics corridor around Bengaluru develops indigenous signal processing algorithms for cost-optimized diagnostic workflows.
Cardiac Patch Monitor Market Competitive Landscape
Diagnostic-platform specialists and diversified medical device conglomerates split the market along subscription-versus-hardware revenue models. The vendor base concentrates among three strategic archetypes: cloud-native interpretation platforms, hospital-installed-base incumbents, and multi-parameter biosensing specialists. Consolidation pressure intensifies as procurement committees unbundle device supply from analysis service contracts. Geographic expansion through notified body relationships in Europe and distributor networks in Asia-Pacific represents the dominant competitive maneuver alongside algorithmic differentiation in AI-assisted arrhythmia detection.
Within the cloud-native tier, iRhythm Technologies occupies a position exemplifying subscription-based diagnostic platform economics. Koninklijke Philips N.V. anchors the hospital-installed-base archetype through enterprise imaging integration capabilities. VitalConnect represents multi-parameter biosensing convergence, extending monitoring modalities beyond single-lead electrocardiography. These three entities collectively illustrate the strategic segmentation reshaping competitive positioning as hardware margins compress and recurring service revenue dominates profitability.
| Leading Market Players |
|---|
| iRhythm Technologies |
| Koninklijke Philips N.V. |
| VitalConnect |
| LifeSignals |
| Baxter International |
| Mawi Inc. |
| SmartCardia |
| Cardiac Insight |
| Zywie |
| Others |
Value Network & Pricing Analysis
Undercapacity in printed electrode substrate manufacturing across East Asian chemical processors is elevating raw material premiums while compressing gross margins on disposable patch units, forcing vendors to renegotiate long-term supply agreements or absorb cost volatility through subscription pricing buffers.
Pricing Analysis
Recurring data interpretation fees drive lifetime value in cardiac patch economics, with subscription-based diagnostic platforms capturing margin pools that hardware sales alone cannot sustain. Three-tier pricing structure across premium AI-assisted interpretation, standard algorithmic screening, and economy signal-acquisition-only tiers separates vendor positioning. Pricing pressure stems from smartwatch single-lead ECG substitution eroding demand for short-term diagnostic patches. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while United States integrated delivery networks absorb premium fees through value-based care contracts.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for electrode material inputs. Silver processing and conductive polymer fabrication concentrate in China, South Korea, and Japan, with flexible circuit substrates drawing from Taiwan and Shenzhen electronics ecosystems. Single-source vulnerability persists in specialized biosensor adhesives and wireless transmission modules. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-patient dispatch for home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac patch monitor market is cycling through a reimbursement-driven expansion phase, with CMS national coverage determinations for extended external electrocardiographic monitoring acting as the cyclical catalyst resetting prescribing velocity.
For Market Incumbents: Pre-empt smartwatch substitution by embedding multi-parameter biosensing capabilities that consumer wearables cannot replicate, particularly respiratory rate and temperature metrics for post-surgical protocols. Secure backward integration into electrode material processing to buffer silver cost volatility. Defend enterprise contracts through EHR interoperability investments that reduce health system integration friction. For New Entrants and Emerging Players: Ambulatory surgical centers in Texas and California represent underpenetrated channels relative to saturated electrophysiology markets, offering volume expansion without incumbent lock-in. Target pre- and post-procedure monitoring workflows where rapid response protocols reduce readmission penalties. Pursue FDA 510(k) clearance streamlining as the primary go-to-market angle, leveraging accelerated pathways to compress time-to-revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native diagnostic platforms as software margins displace hardware economics, favoring asset-light subscription models over manufacturing-heavy operations. Viable acquisition targets include multi-parameter biosensing specialists with proprietary AI-assisted interpretation workflows. Monitor FDA cybersecurity guidance evolution as the inflection signal, since data integrity breaches could trigger coverage restrictions that revalue platform vendors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Accelerated premarket notification reduces time-to-market for novel patch designs under 21 CFR 870.2300. |
| Multi-Parameter Biosensing Convergence | Integration of respiratory and temperature metrics creates differentiated platforms for post-surgical recovery protocols. |
| Hospital System Partnership | Enterprise contracts with United States integrated delivery networks lock in recurring interpretation revenue streams. |
| Reimbursement Strategy | CMS national coverage determinations directly shape physician prescribing behavior in Medicare outpatient settings. |
| Software Companion Development | Cloud-based algorithmic interpretation reduces specialist review burden and expands monitoring capacity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers, cross-validated against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and SEC 10-K disclosures from publicly traded device manufacturers. Bottom-up patch shipment estimates and top-down diagnostic service revenue projections were triangulated to converge on market sizing.
Calibration against historical adoption curves for extended-wear electrocardiography devices anchored growth assumptions across the projection horizon. Segmentation modeling spanned product architecture, technology tier, end-user setting, and application workflow. CAGRs were derived from fitted growth curves applied to each segment, with United States value-based care penetration and EU MDR approval timelines serving as key forecast inputs.
Practitioners should monitor FDA cybersecurity guidance evolution and silver electrode cost volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
South America Fetal and Neonatal Monitoring Market