
 Monolaurin for Feed Market | 2026-2036
Monolaurin for Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Monolaurin for Feed Market Insights
Commercial poultry integrators are unwinding their reliance on traditional antibiotic growth promoters, redirecting procurement toward monolaurin-based feed solutions. BASF leverages its broad oleochemical supply chain to secure lauric acid feedstock at scale across European rendering networks. Oleon NV anchors its position through backward integration into palm kernel oil fractionation, controlling raw material quality from plantation to esterification. Kerry differentiates via encapsulated monolaurin formulations that protect bioactivity through pelleting temperatures.
Monolaurin, the glycerol monoester of lauric acid (C12:0), functions as a medium-chain fatty acid derivative with broad-spectrum antimicrobial activity against Gram-positive bacteria and lipid-enveloped viruses; manufacturers produce it via glycerolysis of coconut or palm kernel oil followed by molecular distillation to achieve purity grades between 90% and 95%. The compound serves primarily as a non-antibiotic growth promoter and gut health modulator in livestock and aquaculture feeds. Powder formulations dominate current volume owing to blending compatibility with standard premix operations, while liquid emulsions capture expanding share in aquaculture feed mills seeking homogenous dispersion in extruded diets. Poultry applications lead value generation due to high stocking densities and regulatory pressure on antibiotic withdrawal periods, whereas aquaculture represents the fastest-growing animal type as shrimp producers in Southeast Asia adopt monolaurin to control Vibrio loads.
The European Food Safety Authority evaluates monolaurin under the feed additives re-authorization framework, with EMA coordination on cross-contamination thresholds influencing formulation standards for export-oriented suppliers. The US FDA maintains monolaurin within Generally Recognized as Safe listings for feed applications, though state-level veterinary feed directive enforcement varies antibiotic-alternative claim permissibility. China's Ministry of Agriculture and Rural Affairs classifies monolaurin as a feed additive requiring import registration and local efficacy trials, creating compliance complexity for foreign entrants. Stakeholders must monitor evolving maximum residue limits in meat and aquaculture products, as tightening standards in destination markets will determine which purity grades and documentation packages sustain market access.
Market Dynamics
The European Union's antibiotic withdrawal mandates are restructuring feed additive procurement, forcing integrators to validate alternative growth promoters through field efficacy trials before contract renewal cycles.
Growth Catalysts
- Regulatory Phase-Out Directives:The EU's ban on zinc oxide in piglet feeds under Regulation 2016/1095 redirects formulation spend toward monolaurin-based gut health modulation.
- Aquaculture Disease Pressure:Indonesian shrimp producers confronting persistent Vibrio parahaemolyticus outbreaks are expanding monolaurin inclusion in extruded grower diets.
- Poultry Density Economics:High stocking densities in Brazilian broiler houses amplify the cost-benefit calculus for antimicrobial alternatives that reduce necrotic enteritis incidence.
Market Restraints
- Lauric Acid Supply Concentration:Southeast Asian palm kernel oil fractionation capacity controls 70% of global C12:0 feedstock, exposing formulators to El Niño-driven harvest volatility.
- Purity Grade Cost Escalation:Molecular distillation to achieve 95% monolaurin purity consumes 40% more energy than standard glycerolysis, compressing margin structures for mid-tier suppliers.
- Cross-Contamination Thresholds:EMA coordination on residue limits in compound feeds forces dual-line manufacturing investments that smaller blenders cannot absorb.
Strategic Opportunities
- Vietnam Aquaculture Expansion:Mekong Delta pangasius producers remain undersupplied with encapsulated monolaurin formulations suited to high-moisture extrusion processes.
- Precision Dosing Hardware:Integration of liquid monolaurin emulsions with automated micro-dosing systems in Thai feed mills enables real-time inclusion rate adjustment based on pathogen load monitoring.
- US Veterinary Feed Directive Alignment:FDA enforcement discretion on antibiotic-alternative claims creates a compliance pathway for monolaurin suppliers documenting mode-of-action specificity.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of lipid chemistry and animal nutrition expertise remains concentrated among retiring specialists at European rendering cooperatives.
- Heat Stability Validation:Pelleting temperatures exceeding 85°C degrade unprotected monolaurin bioactivity, requiring capital-intensive coating equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monolaurin for Feed Market |
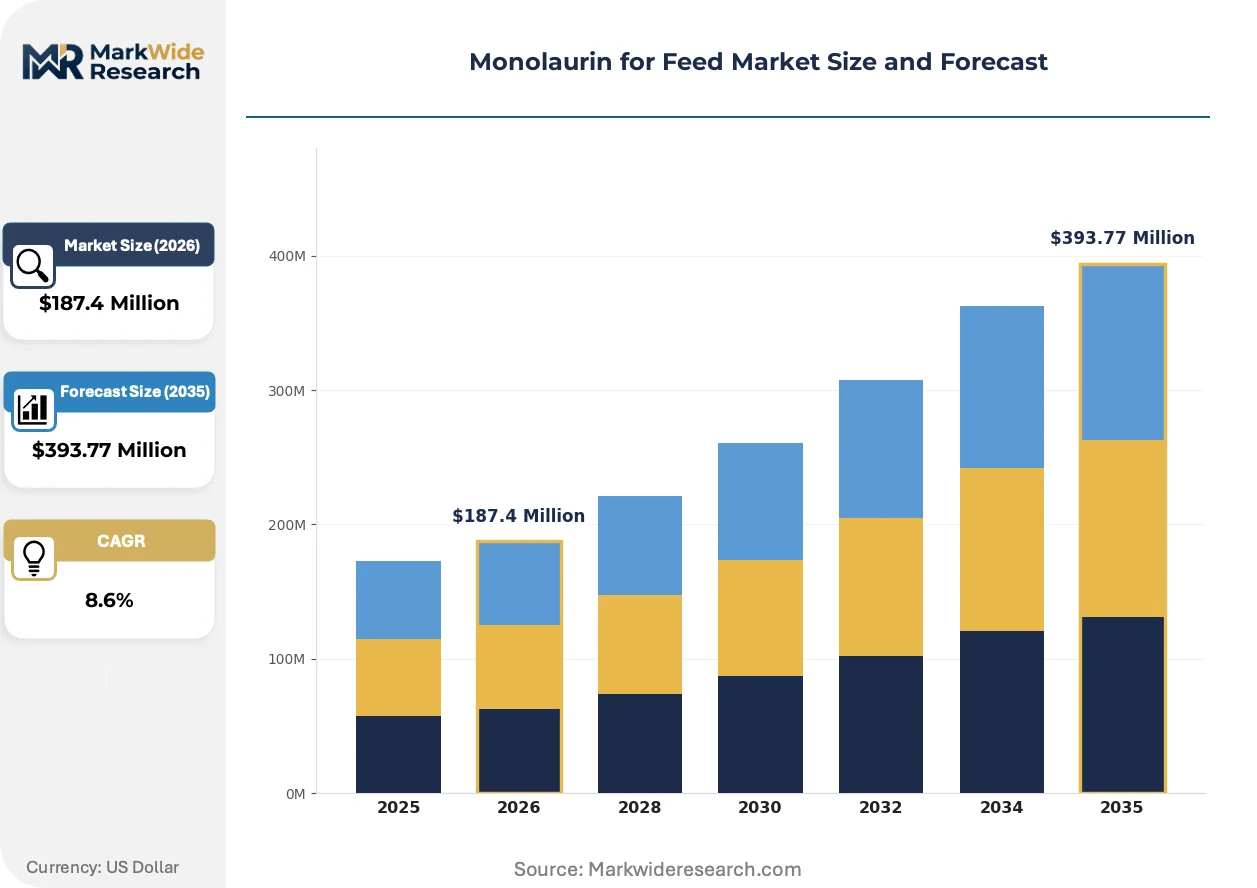
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granular, Emulsified Animal Type: Poultry, Swine, Ruminants, Aquaculture Application: Growth Promotion, Disease Prevention, Immune Support, Nutritional Supplement Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Oleon NV, Riken Vitamin, Danisco, Hangzhou Fuchun, PT Musim Mas, Kerry, BASF, Guangzhou Cardlo Biochemical, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monolaurin for Feed Market Trends and Innovations
Encapsulation technologies and regulatory documentation protocols are bifurcating the supplier base into specification-grade specialists and commodity glycerolysis operators.
Micro-encapsulated monolaurin using hydrogenated vegetable oil matrices protects antimicrobial activity through feed manufacturing thermal stress. Poultry integrators in Poland and Spain are adopting these formulations at 15-20% price premiums over standard powder grades. This thermal protection is decomposing the traditional trade-off between pelleting efficiency and additive bioavailability that constrained monolaurin inclusion rates.
EFSA's 2023 re-authorization framework for feed additives now requires extended sub-chronic toxicity datasets for glycerol monoester compounds. The industrial consequence is a 24-36 month documentation burden that favors incumbent suppliers with established safety pharmacology archives. Export-oriented Chinese manufacturers are responding by commissioning GLP-compliant studies at European contract research organizations to maintain market access.
Integrated poultry operators are consolidating premix procurement under single-source contracts that bundle monolaurin with organic acid blends and phytogenic additives. This specification bundling displaces standalone monolaurin spot purchasing at independent feed mills. The shift is most visible in Brazil's southern broiler belt, where three integrators now control 60% of antimicrobial-alternative formulation decisions.
Monolaurin for Feed Market Segmentation
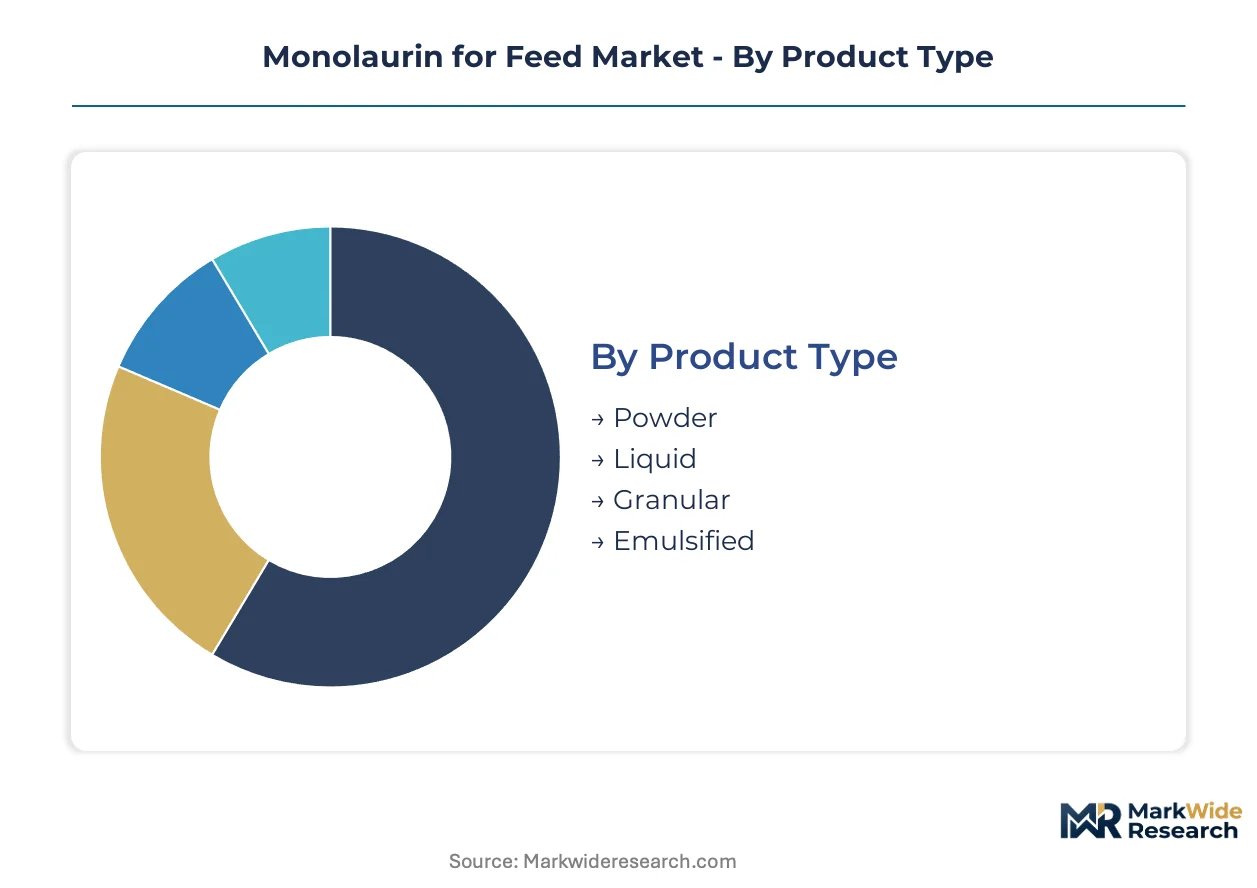
Monolaurin suppliers must align formulation specifications with distinct feed manufacturing processes and animal physiology requirements. Channel economics vary sharply between bulk direct sales to integrated poultry operators and fragmented distributor networks serving independent aquaculture farms.
Product Type:
Powder formulations flow through standard premix channels, while liquid and emulsified variants require specialized handling infrastructure at feed mill sites.
- Powder:Standard glycerolysis-derived monolaurin at 90-92% purity blends directly into vitamin-mineral premixes without equipment modification. Demand concentrates in Brazilian broiler operations where pelleting temperatures stay below 80°C, preserving unprotected bioactivity.
- Liquid:Molten monolaurin or oil-based suspensions enable homogenous dispersion in high-fat aquafeed extrusion. Indonesian shrimp feed mills in East Java and Sulawesi are expanding liquid inclusion for Vibrio control in grower diets.
- Granular:Spray-cooled beads improve flowability in automated dosing systems. European compound feed manufacturers favor granular formats for ruminant mineral supplements.
- Emulsified:Water-dispersible microemulsions suit high-moisture extrusion processes. Vietnamese pangasius producers represent emerging uptake for this format.
Powder dominates installed base. Liquid is where expansion concentrates.
Animal Type:
Species-specific digestive physiology and regulatory pressure on antimicrobial use create divergent value capture opportunities across livestock categories.
- Poultry:High stocking densities and necrotic enteritis pressure make broiler operations the primary revenue source. EU antibiotic withdrawal mandates under EFSA frameworks force integrators to validate monolaurin efficacy through field trials.
- Aquaculture:Shrimp and finfish producers confront Gram-negative Vibrio pathogens where monolaurin's membrane-disrupting mechanism shows strongest clinical evidence. Southeast Asian clusters in Indonesia and Vietnam are climbing the fastest.
- Swine:Post-weaning diarrhea control drives inclusion in piglet starter feeds, particularly following the EU's zinc oxide ban under Regulation 2016/1095.
- Ruminants:Ruminal degradation limits bioavailability, restricting monolaurin to protected formulations in dairy calf milk replacers.
Poultry commands current volume leadership. Aquaculture shows steepest expansion trajectory.
Application:
Functional positioning determines pricing architecture and regulatory documentation burden for suppliers seeking market access.
- Growth Promotion:Antibiotic-alternative claims require mode-of-action specificity under FDA veterinary feed directive enforcement. US integrators demand GLP-compliant efficacy datasets.
- Disease Prevention:Pathogen load reduction in gut microbiome modulation carries lower evidentiary thresholds than growth promotion claims. This positioning dominates EU commercial uptake.
- Immune Support:Adjuvant effects on mucosal immunity are being validated in academic trials at Wageningen University and Kasetsart University.
- Nutritional Supplement:Energy contribution from medium-chain fatty acids represents secondary positioning for metabolic support in transition dairy cows.
Disease prevention anchors commercial contracts. Growth promotion is where regulatory investment concentrates.
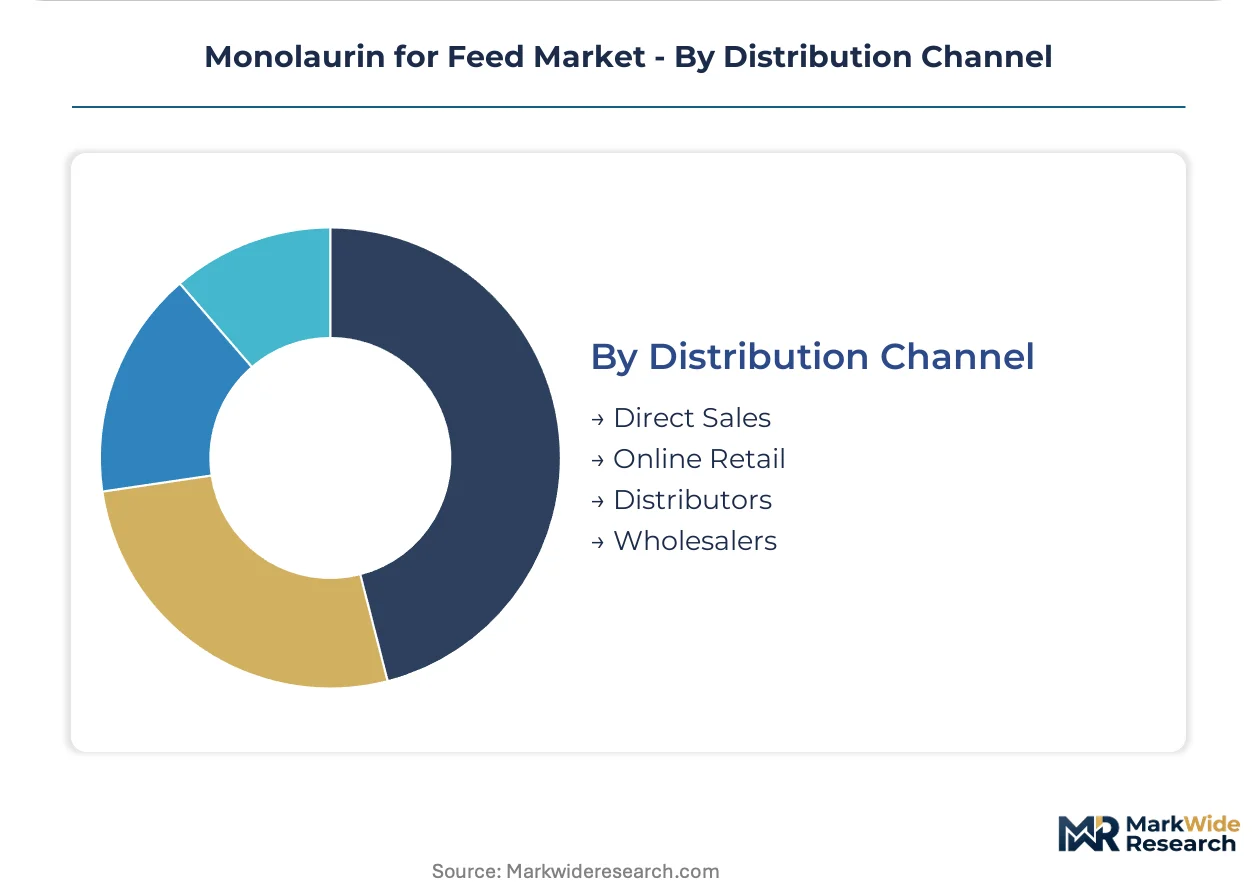
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and working capital constraints across geographic markets.
- Direct Sales:Long-term supply agreements with integrated poultry operators bundle monolaurin with organic acid and phytogenic portfolios. Brazil's southern broiler belt shows highest direct procurement concentration.
- Distributors:Regional feed additive distributors serve independent mills with technical formulation support. This channel dominates fragmented Southeast Asian aquaculture supply chains.
- Wholesalers:Bulk commodity traders handle standard powder grades for price-sensitive compounders. Margins compress through multiple handling layers.
- Online Retail:E-procurement platforms capture small-volume specialty orders from research institutions and niche organic livestock operations.
Direct sales capture value in contracted volumes. Distributors retain relevance in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's oleochemical processing infrastructure anchors European monolaurin distribution, while Singapore's Jurong Island petrochemical cluster channels Southeast Asian feedstock flows. These maritime-logistics assets determine regional supply security for lauric acid derivatives.
United States
Poultry integrators in Georgia and Arkansas are expanding antibiotic-free feed programs under FDA veterinary feed directive enforcement. The USDA's National Organic Program standards shape certification requirements for monolaurin inclusion in organic livestock operations. Chicago-area feed compounders represent the primary Midwest demand concentration for disease-prevention formulations.
Germany
EFSA's feed additive re-authorization framework under Regulation (EC) 1831/2003 forces suppliers to maintain GLP-compliant toxicity archives. The country's rendering cooperative network controls premium-grade lauric acid fractionation capacity. North Rhine-Westphalia's compound feed manufacturers lead adoption of encapsulated monolaurin for thermal-stable pelleting applications.
Indonesia
Shrimp producers in East Java and Sulawesi confront persistent Vibrio parahaemolyticus pressure in intensive grow-out ponds. The Ministry of Marine Affairs and Fisheries regulates aquafeed additive imports through registration requirements at the National Agency for Drug and Food Control. Surabaya's feed mill cluster drives liquid emulsion uptake for homogenous extrusion dispersion.
Brazil
High stocking densities in Paraná and Santa Catarina broiler houses amplify necrotic enteritis control economics. ANVISA coordinates with the Ministry of Agriculture on maximum residue limits for export-oriented meat production. The southern broiler belt's integrator consolidation concentrates procurement decisions under three dominant poultry operators.
Vietnam
Mekong Delta pangasius producers remain undersupplied with encapsulated formulations suited to high-moisture extrusion processes. The Ministry of Agriculture and Rural Affairs classifies imported monolaurin under feed additive registration protocols requiring local efficacy trials. Can Tho's aquafeed manufacturing zone represents the fastest-growing uptake node for emulsified product formats.
Monolaurin for Feed Market Competitive Landscape
Listed leaders compete with private specialists across documentation capacity and thermal-protection technology tiers. The supplier base bifurcates between specification-grade operators with EFSA safety archives and commodity glycerolysis producers serving price-sensitive compounders. Three archetypes dominate: palm-kernel-integrated fractionators, encapsulation technology licensors, and regional premix bundlers. Competitive moves concentrate on backward integration into plantation assets and coating equipment partnerships with feed mill engineering firms.
Within the integrated fractionator tier, Oleon NV and PT Musim Mas exemplify upstream control over C12:0 feedstock quality from plantation through esterification. BASF represents the diversified chemical conglomerate archetype, leveraging broad oleochemical supply chains across European rendering networks. Kerry occupies a position among formulation specialists, differentiating through encapsulated delivery systems that protect bioactivity through thermal stress. These three anchors illustrate how competitive positioning stratifies across raw material security, manufacturing scale, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Oleon NV |
| Riken Vitamin |
| Danisco |
| Hangzhou Fuchun |
| PT Musim Mas |
| Kerry |
| BASF |
| Guangzhou Cardlo Biochemical |
| Corbion |
| Others |
Pricing and Supply Chain Analysis
Fractionation capacity utilization at Southeast Asian palm kernel oil facilities directly determines monolaurin price floors, with 70% of global C12:0 feedstock controlled by Indonesian and Malaysian plantation-to-esterification networks. Scale economies in molecular distillation operations compress margin structures for mid-tier suppliers unable to secure long-term lauric acid offtake agreements with integrated renderers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade 95% purity monolaurin from standard 90-92% feed additive grades, with the former commanding substantial premia from EU integrators documenting EFSA re-authorization compliance. Price differentiation rests on thermal-stability certification and GLP-compliant toxicity archives rather than commodity glycerolysis output. Cost compression in standard powder grades is intensifying as Chinese manufacturers expand glycerolysis capacity without downstream distillation investment. Independent aquaculture feed mills in Southeast Asia exhibit highest price sensitivity, while EU poultry integrators prioritize specification security over unit cost.
Supply Chain Analysis
Inventory lead times for lauric acid feedstock stretch across 8-12 week plantation-to-fractionation cycles, exposing formulators to El Niño-driven harvest volatility in Indonesia and Malaysia. Raw material dependencies center on palm kernel oil fractionation output, coconut oil glycerolysis streams, and hydrogenated vegetable oil matrices for encapsulation. Single-source vulnerability concentrates in Surabaya and Rotterdam oleochemical hubs, where port congestion or regulatory inspection backlogs disrupt just-in-time premix operations. Distribution runs through compound feed manufacturers with in-house pelleting capacity, bypassing commodity wholesalers for integrated poultry operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monolaurin procurement cycles track livestock disease pressure and antibiotic withdrawal enforcement, positioning the market for cyclical recovery as EU zinc oxide bans and Southeast Asian Vibrio outbreaks sustain alternative growth promoter validation.
For Market Incumbents: Fortify specification-grade positioning by commissioning extended sub-chronic toxicity datasets at GLP-compliant European contract research organizations, insulating against EFSA re-authorization documentation burdens that favor established safety pharmacology archives. Deepen backward integration into palm kernel plantation assets in East Java and Sulawesi to secure captive C12:0 feedstock supply against El Niño-driven price spikes. For New Entrants and Emerging Players: EFSA fast-track registration pathways for glycerol monoester compounds represent the most penetrable regulatory entry point, particularly for Chinese manufacturers commissioning European toxicity studies to maintain export market access. Target Vietnamese pangasius producers in the Mekong Delta with emulsified monolaurin formulations suited to high-moisture extrusion processes, where incumbent supply remains undersaturated. Pursue joint development agreements with Thai feed mill engineering firms to integrate liquid micro-dosing hardware with pathogen load monitoring systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors encapsulation technology licensors with hydrogenated vegetable oil matrix patents, as thermal protection capabilities command 15-20% price premia from Polish and Spanish poultry integrators. Long-term viability across the 5-10 year window rests on documentation capacity rather than glycerolysis scale, directing acquisition interest toward specification-grade operators with EFSA safety archives. Watch for EMA coordination on cross-contamination thresholds as the inflection signal forcing dual-line manufacturing investments that eliminate smaller blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive palm kernel oil supply in Indonesia insulates against El Niño harvest volatility and lauric acid price spikes. |
| Encapsulation Technology Licensing | Hydrogenated vegetable oil matrix patents protect monolaurin bioactivity through pelleting temperatures exceeding 85°C. |
| GLP-Compliant Toxicity Study Commissioning | Extended sub-chronic datasets satisfy EFSA re-authorization requirements and sustain EU market access for glycerol monoesters. |
| Precision Dosing Hardware Partnership | Integration with Thai feed mill automation enables real-time monolaurin inclusion adjustment based on pathogen load monitoring. |
| Emulsified Formulation Development | Water-dispersible microemulsions address Vietnamese pangasius producer demand for high-moisture extrusion compatibility. |
Research Methodology
Desk research of EFSA feed additive re-authorization filings, EU customs trade data for lauric acid derivatives, and SEC disclosures from listed oleochemical producers preceded structured interviews with compound feed procurement directors, poultry integrator nutritionists, aquafeed mill operations managers, and GLP contract research organization study directors. Primary fieldwork across Indonesian shrimp farming clusters and Brazilian broiler belts combined with secondary validation against ANVISA registration databases and China's Ministry of Agriculture import protocols. Bottom-up volume estimates from individual feed mill consumption patterns triangulated against top-down fractionation capacity assessments at Rotterdam and Jurong Island oleochemical hubs.
Variance decomposition across product type, animal species, application positioning, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth differentials weighted by purity grade pricing premia and regional regulatory enforcement intensity. Modeled inputs incorporated pathogen pressure indices for Vibrio parahaemolyticus in Southeast Asian aquaculture and necrotic enteritis incidence rates in high-density Brazilian broiler operations.
Decision-makers should treat outputs as directional under assumptions of sustained EU antibiotic withdrawal enforcement and stable palm kernel oil harvest yields; material deviation in El Niño frequency or EFSA documentation timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Chitosan for Agriculture Market