
 Baobab Market | 2026-2036
Baobab Market Size, Share, and Industry Trends Forecast 2026-2036
Baobab Market Analysis
Premium organic certification is rotating the Baobab Market toward higher-margin supply tiers. Nexira leverages its extraction expertise to serve European nutraceutical formulators with standardized polyphenol grades. Mighty Baobab Ltd anchors East African supply through direct farmer partnerships in Kenya and Tanzania. Aduna Ltd differentiates via retail brand strength in UK health food channels.
Baobab denotes the dried fruit pulp, seeds, and leaves of Adansonia digitata, a sub-Saharan tree species whose pulp contains approximately 50% dietary fiber and high vitamin C content, processed through sun-drying, mechanical milling, and cold-pressing for oil extraction, serving functional food, cosmetic, and supplement industries. Powder dominates volume due to its incorporation into smoothie bases and fortified foods, while oil commands premium positioning in cosmetic formulations for its omega fatty acid profile. The nutraceuticals application segment leads value generation as capsule and tablet demand from health stores and direct-to-consumer channels expands.
The EU EFSA Novel Food framework, FDA GRAS self-affirmation pathways, and South African BIS-equivalent organic standards collectively govern market access and ingredient legitimacy for baobab-derived products. These regulatory layers elevate compliance costs for new entrants while rewarding pre-approved suppliers with durable shelf placements. Stakeholders must monitor evolving novel food rulings in target jurisdictions to anticipate reformulation requirements and sourcing qualification shifts.
Market Dynamics
EU EFSA Novel Food approval pathways are compressing market entry timelines for African-sourced baobab, concentrating supply legitimacy among pre-certified processors while elevating compliance costs for new entrants seeking shelf placement in regulated jurisdictions.
Growth Catalysts
- Functional beverage formulation:Food and beverage manufacturers in Germany and France are embedding baobab powder into smoothie bases and fortified drink lines, pulling volume through health-oriented retail channels.
- EFSA Novel Food framework:The EU regulatory pathway, once cleared, delivers durable ingredient legitimacy that protects supplier margins and locks in long-term procurement contracts from European nutraceutical formulators.
- Senegal processing clusters:Concentrated organic certification infrastructure and established export logistics in Dakar and Kaolack regions are anchoring supply-grade output for premium market tiers.
Market Restraints
- Raw material concentration risk:Wild-harvest dependence across the Sahel zone exposes supply continuity to rainfall variability and seasonal collection labor shortages.
- Input cost volatility:Organic certification audit fees and cold-chain logistics for oil extraction are inflating unit economics for small-batch processors.
- Technical limitation:Standardized polyphenol content consistency remains uneven across sun-drying operations, constraining pharmaceutical-grade supply expansion.
Strategic Opportunities
- Cosmetic omega positioning:Baobab oil's fatty acid profile is penetrating prestige skincare formulations in South Korea and Japan, opening premium pricing tiers outside traditional food channels.
- Direct-to-consumer capsule demand:Health store and subscription channels in the United Kingdom are expanding tablet and capsule uptake, bypassing conventional ingredient broker networks.
- Kenya-Tanzania supply expansion:East African farmer partnership models are diversifying geographic sourcing beyond West African concentration, reducing single-origin risk.
Industry Challenges
- Organic certification timeline compression:Multi-year conversion periods for wild-harvest plots are delaying new supplier qualification under EU organic equivalence agreements.
- Extraction equipment capex intensity:Cold-press oil machinery and mechanical milling infrastructure require substantial capital deployment that fragments processing scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baobab Market |
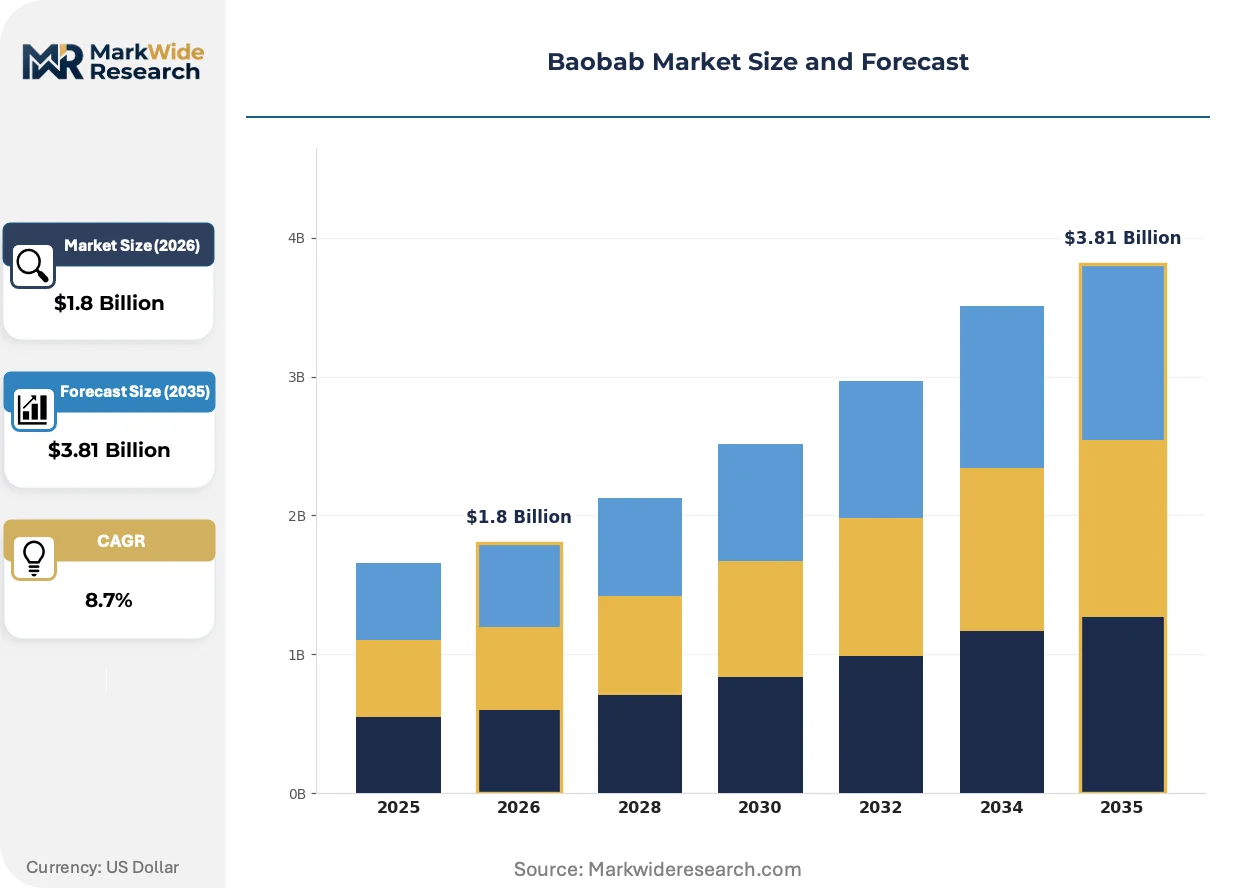
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Pulp, Capsules Application: Nutraceuticals, Cosmetics, Food & Beverages, Pharmaceuticals End User: Restaurants, Health Stores, Beauty Salons, Manufacturers Distribution Channel: Online Retail, Wholesalers, Supermarkets, Specialty Stores |
| Companies Covered | Nexira, Mighty Baobab Ltd, Aduna Ltd, Organic Africa, B'Ayoba, Baobab Foods LLC, Afriplex Pty Ltd, Woodland Foods, Baobab Fruit Company Senegal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baobab Market Emerging Trajectories
Processing technology and regulatory classification systems are actively restructuring how baobab pulp and oil enter commercial channels, with differentiation emerging between commodity-grade supply and certified premium tiers.
Spray-drying and low-temperature dehydration systems are replacing traditional sun-drying for vitamin C retention. Nutraceutical formulators in Switzerland and Germany are adopting these methods to meet pharmaceutical-grade specifications. The technology is bifurcating the supply base between artisan sun-dried output and standardized industrial production.
EFSA's evolving Novel Food guidance on traditional food from third countries is streamlining equivalence pathways for documented African use. This regulatory recalibration is accelerating approval timelines for established suppliers while tightening evidentiary requirements for new market entrants. West African exporters with pre-existing dossiers are capturing expanded shelf placements.
Health food retailers are consolidating procurement through direct-origin partnerships, displacing traditional commodity brokers. United Kingdom and Netherlands buyers are negotiating long-term offtake agreements with Senegalese and Kenyan cooperatives. This channel restructuring is most visible in organic-certified powder segments where provenance transparency commands price premiums.
Baobab Market Segmentation
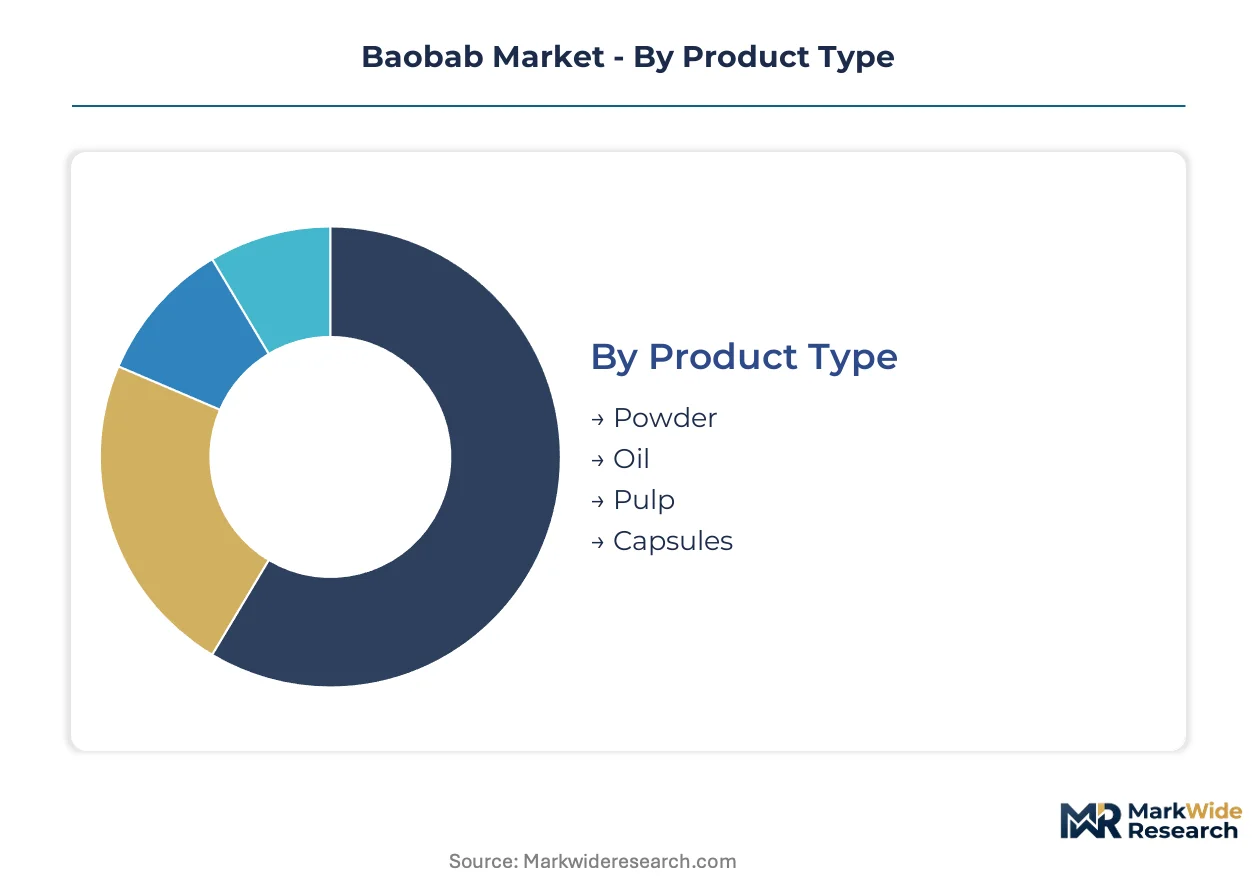
Baobab market segmentation reveals how regulatory frameworks and processing sophistication stratify commercial opportunity across product grades and channel tiers. Each dimension carries distinct compliance burdens and margin profiles that reshape supplier positioning.
Product Type:
EFSA Novel Food approval creates tiered market access where standardized extracts command shelf placement premiums over artisan-processed alternatives.
- Powder:Mechanical milling of sun-dried pulp yields approximately 50% dietary fiber content with high vitamin C retention. German and French functional beverage manufacturers anchor procurement volumes through health-oriented retail channels, though polyphenol standardization remains uneven across sun-drying operations.
- Oil:Cold-pressed extraction from seeds delivers omega fatty acid profiles suited to prestige skincare formulations. South Korean and Japanese cosmetic laboratories are expanding offtake agreements, bypassing conventional ingredient broker networks for direct-origin partnerships.
- Pulp:Raw dried fruit segments serve traditional food applications and regional consumption patterns across sub-Saharan markets.
- Capsules:Encapsulated powder formats target health store and subscription channel distribution in the United Kingdom.
Established volume favors Powder; emerging adoption favors Oil.
Application:
End-use sophistication determines extraction technology requirements and certification depth across commercial segments.
- Nutraceuticals:Capsule and tablet demand from Swiss and German pharmaceutical-grade formulators requires spray-drying and low-temperature dehydration systems for vitamin C retention. EFSA dossier holders capture durable procurement contracts through pre-approved supplier status.
- Cosmetics:Prestige skincare formulations leverage baobab oil's fatty acid composition in South Korean and Japanese markets where omega positioning commands premium pricing tiers.
- Food & Beverages:Smoothie bases and fortified drink lines in Germany and France embed certified organic powder for health-oriented retail placement.
- Pharmaceuticals:Standardized polyphenol grades face technical limitation from sun-drying inconsistency, constraining pharmaceutical-grade supply expansion.
Margin concentration sits with Nutraceuticals; steepest expansion trajectory appears in Cosmetics.
End User:
Procurement sophistication varies dramatically across buyer types, from commodity spot purchasing to long-term offtake agreements.
- Health Stores:Direct-to-consumer capsule and tablet demand in the United Kingdom consolidates procurement through provenance-transparent sourcing from Senegalese and Kenyan cooperatives.
- Manufacturers:Food and beverage producers in Germany and France negotiate multi-year supply contracts with pre-certified processors, locking in organic-certified powder volumes.
- Restaurants:Limited adoption concentrates in specialty health-focused establishments seeking ingredient differentiation.
- Beauty Salons:Niche oil consumption for professional skincare treatments remains fragmented across regional markets.
Contract security favors Manufacturers; price premium capture favors Health Stores.
Distribution Channel:
Channel restructuring is displacing traditional commodity brokers with direct-origin partnerships that reward transparency premiums.
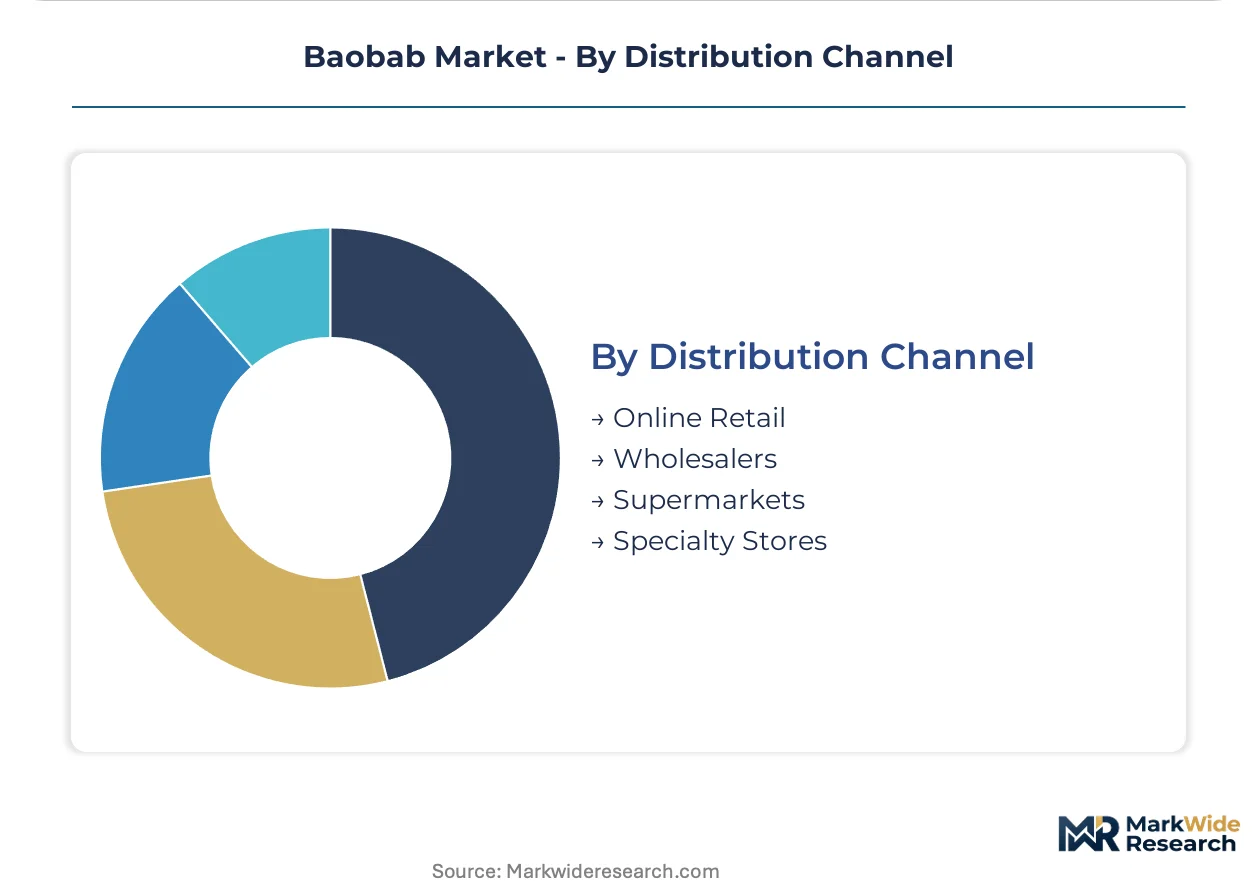
- Online Retail:Subscription channels and direct-to-consumer platforms in the United Kingdom expand tablet and capsule uptake, bypassing conventional ingredient broker networks entirely.
- Specialty Stores:Netherlands and United Kingdom health food retailers negotiate long-term offtake agreements with Senegalese and Kenyan cooperatives for organic-certified powder segments.
- Wholesalers:Traditional commodity aggregation faces margin compression as provenance transparency becomes a purchasing criterion.
- Supermarkets:Mainstream retail placement remains limited by novel food approval timelines and premium pricing relative to conventional ingredients.
Margin preservation favors Specialty Stores; volume scaling favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild-harvest corridors across the Sahel zone concentrate raw material flows toward coastal processing hubs. Senegal, Kenya, and Tanzania anchor export-grade supply through organic certification clusters. European and Asian importers source through these nodes under EFSA Novel Food and equivalent regulatory frameworks.
Senegal
Dakar and Kaolack host the densest organic certification infrastructure for baobab pulp processing. EFSA Novel Food dossiers filed by Senegalese cooperatives accelerate EU market access timelines. The Baobab Fruit Company Senegal anchors export logistics through direct long-term offtake agreements with German and French nutraceutical formulators.
Kenya
Farmer partnership models in coastal and eastern regions diversify supply beyond West African concentration. Kenya Bureau of Standards (KEBS) organic equivalence protocols align with EU import requirements. Mombasa port infrastructure supports cold-chain logistics for oil extraction bound for South Korean cosmetic laboratories.
Tanzania
Tanga and Dar es Salaam regions concentrate mechanical milling capacity for powder export grades. Tanzania Food and Drugs Authority (TFDA) registration pathways streamline regional trade into East African Community markets. Wild-harvest collection networks in central provinces feed processing facilities with vitamin C-rich pulp for Swiss spray-drying operations.
Germany
Swiss and German nutraceutical formulators in Baden-Württemberg and Bavaria drive pharmaceutical-grade powder demand. BfR (Federal Institute for Risk Assessment) coordinates with EFSA on Novel Food equivalence assessments for African-sourced ingredients. Stuttgart-area extraction specialists specify low-temperature dehydration systems to retain polyphenol consistency in capsule formulations.
South Korea
Seoul-based cosmetic laboratories expand baobab oil procurement for prestige skincare omega positioning. Ministry of Food and Drug Safety (MFDS) cosmetic ingredient notifications govern import clearance for cold-pressed seed extracts. Incheon free trade zone warehousing reduces lead times for Japanese and domestic formulators seeking direct-origin partnerships.
Baobab Market Vendor Landscape
Concentration sits with pre-certified processors holding EFSA Novel Food approvals and established organic audit trails. The supplier base stratifies between West African wild-harvest aggregators, East African farmer partnership networks, and European extraction specialists serving pharmaceutical-grade specifications. Three archetypes dominate: coastal export processors with integrated certification, European formulators with proprietary extraction technology, and direct-trade retail brands with provenance marketing. Competitive moves center on backward integration into farmer cooperatives and geographic diversification beyond single-origin supply.
Within the pre-certified processor tier, Nexira, Mighty Baobab Ltd, and Aduna Ltd occupy distinct positioning vectors. Nexira represents European extraction expertise serving standardized polyphenol grades to Swiss and German nutraceutical formulators. Mighty Baobab Ltd anchors East African supply architecture through Kenya and Tanzania farmer partnerships. Aduna Ltd exemplifies retail brand strength in UK health food channels, bypassing conventional ingredient broker networks through direct-to-consumer and subscription distribution.
| Leading Market Players |
|---|
| Nexira |
| Mighty Baobab Ltd |
| Aduna Ltd |
| Organic Africa |
| B'Ayoba |
| Baobab Foods LLC |
| Afriplex Pty Ltd |
| Woodland Foods |
| Baobab Fruit Company Senegal |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Senegalese cooperatives and German nutraceutical formulators lock in multi-year supply access while anchoring price visibility against organic certification audit volatility and wild-harvest labor cost fluctuations. These contract structures insulate pre-certified processors from spot-market turbulence while compressing margins for unqualified entrants seeking shelf placement under EFSA Novel Food frameworks.
Pricing Analysis
EFSA Novel Food approval dictates the pricing tier structure across the Baobab Market, separating pre-certified organic powder from artisan sun-dried alternatives. Three-tier pricing structure across premium pharmaceutical-grade, certified organic, and commodity-grade levels reflects polyphenol standardization consistency and extraction technology sophistication. Cost compression in commodity-grade powder is intensifying because mechanical milling capacity expansion in Tanzania fragments processing scale. Health store subscription channels exhibit lowest price sensitivity, while conventional food manufacturers purchasing through wholesale brokers face highest margin pressure.
Supply Chain Analysis
Dakar port logistics and cold-chain infrastructure for oil extraction constitute critical chokepoints that tether export-grade output to Senegal's coastal processing clusters. Raw material flows draw from wild-harvest networks across Senegal, Kenya, and Tanzania, with vitamin C-rich pulp feeding Swiss spray-drying operations and omega-profile seeds bound for South Korean cosmetic laboratories. Single-source vulnerability concentrates in seasonal collection labor pools across the Sahel zone, exposing continuity to rainfall variability. Distribution runs through direct-origin partnerships displacing traditional commodity brokers, with Netherlands and United Kingdom health food retailers negotiating provenance-transparent procurement from Kenyan farmer cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service models and recurring organic audit subscriptions expand faster than commodity powder volumes, creating attach-revenue opportunities for processors with established EFSA dossiers and farmer partnership infrastructure.
For Market Incumbents: Secure backward integration into Kenyan and Tanzanian farmer cooperatives to diversify geographic sourcing beyond West African concentration and reduce single-origin risk. Lock in capacity reservation agreements for cold-press oil machinery before extraction equipment capex inflation fragments processing scale. Incumbent processors with pre-certified status must defend margin position against emerging East African entrants by deepening provenance transparency through blockchain-traceable supply chains. For New Entrants and Emerging Players: EFSA Novel Food equivalence fast-tracks for documented traditional African use offer the most penetrable regulatory pathway for Senegalese and Kenyan cooperatives with pre-existing dossiers. Target cosmetic omega positioning in South Korean and Japanese prestige skincare markets where direct-origin partnerships bypass conventional ingredient broker networks entirely. Go-to-market angle should emphasize pharmaceutical-grade spray-drying technology adoption to meet Swiss and German nutraceutical specifications. For Investors and Strategic Acquirers: Capital is best deployed toward coastal export processors with integrated organic certification and established EFSA approvals, as these assets capture durable procurement contracts through pre-certified supplier status. Long-term viability over the next decade hinges on geographic diversification beyond single-origin supply and technology adoption for vitamin C retention. Watch for inflection in South Korean cosmetic laboratory offtake agreements as signal of premium pricing tier expansion outside traditional food channels.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Pre-certified status locks in multi-year procurement contracts from German formulators. |
| Farmer Partnership Network Expansion | Kenya-Tanzania sourcing reduces single-origin risk and secures organic audit trails. |
| Spray-Drying Technology Adoption | Low-temperature dehydration meets Swiss pharmaceutical-grade vitamin C specifications. |
| Direct-Origin Partnership Structuring | Provenance transparency commands price premiums in Netherlands health food channels. |
| Cosmetic Oil Cold-Chain Infrastructure | Mombasa port logistics enable South Korean prestige skincare market access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA Novel Food dossier filings, EU organic certification registries, and Senegal-Kenya-Tanzania customs export data. Primary interviews engaged cooperative managers, organic certification auditors, nutraceutical formulators, and health food retail buyers. Secondary validation drew from BfR risk assessment publications, EFSA guidance documents, and East African Community trade statistics. Bottom-up volume modeling triangulated against top-down value projections across product type and application segments.
Segmentation dimensions modeled include product grade tier, end-use application, extraction technology sophistication, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of historical procurement volumes and forward projection of EFSA approval pipeline timelines. Industry-specific forecast inputs incorporated organic certification conversion timelines and cold-press oil capacity buildout schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA Novel Food framework stability and continued EU organic equivalence recognition for African-sourced botanicals; material deviation in regulatory timelines or certification audit protocols would warrant model refresh. Practitioners should keep alternative scenarios live as South Korean cosmetic ingredient notification requirements and Japanese prestige skincare procurement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Global Agricultural Enzymes Market