
 Aircraft Buffing Wheel Market | 2026-2036
Aircraft Buffing Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Buffing Wheel Market Insights
Modular kit configurations for buffing wheel sets is shifting how MRO facilities and aerospace manufacturers procure surface finishing consumables, moving from single-item orders to bundled assortments matched to specific airframe sections. Parker Hannifin Corporation leverages its distribution network to supply integrated maintenance consumable packages across North American aviation hubs. Safran Group anchors its aftermarket position through dedicated MRO supply contracts with European flag carriers and component shops. Collins Aerospace differentiates via OEM-aligned specifications that tie buffing wheel grades to original surface finish requirements on new production lines.
Aircraft buffing wheels are abrasive finishing tools constructed from layered cotton, felt, sisal, or linen substrates bonded to metal centers, engineered to rotational speeds exceeding 3,000 RPM for precision surface treatment of aluminum alloys, titanium, and composite substrates used in airframe and engine components. Cotton buffing wheels dominate commercial procurement due to their versatility across polishing and cleaning stages on aluminum skin panels, while felt buffing wheels command premium positioning for final mirror finishes on turbine blades and landing gear struts where surface integrity affects fatigue performance. Application segmentation shows surface finishing generating the highest value per unit among cleaning, polishing, and deburring categories, driven by OEM first-build specifications and depot-level overhaul standards.
FAA airworthiness standards under 14 CFR Part 43 govern acceptable materials and traceability for aircraft maintenance consumables in the United States, while EASA Part 145 regulations impose equivalent conformity requirements across European maintenance organizations, and ISO 9001/AS9100 quality frameworks shape supplier qualification thresholds for OEM and tier-one procurement. These overlapping compliance layers elevate entry barriers for uncertified producers and concentrate sourcing decisions on established aerospace-grade suppliers. Stakeholders must monitor evolving sustainability mandates from regulators and OEM customers regarding consumable lifecycle and material sourcing transparency.
Market Dynamics
FAA airworthiness directives and EASA continuing airworthiness regulations are tightening material traceability requirements for aftermarket components, forcing MRO facilities and OEM production lines to consolidate supplier relationships around certified aerospace-grade consumable providers.
Growth Catalysts
- Legacy fleet maintenance cycles:Aging commercial aircraft in North American and European fleets require intensive surface restoration during heavy maintenance checks, driving recurring consumable demand at depot-level facilities.
- 14 CFR Part 43 compliance layers:FAA regulations governing acceptable materials for aircraft maintenance elevate entry barriers for uncertified producers, concentrating procurement decisions on established suppliers with documented traceability systems.
- Titanium and composite substrate expansion:Next-generation airframe designs incorporating advanced materials require specialized buffing wheel grades matched to hardness and thermal sensitivity specifications.
Market Restraints
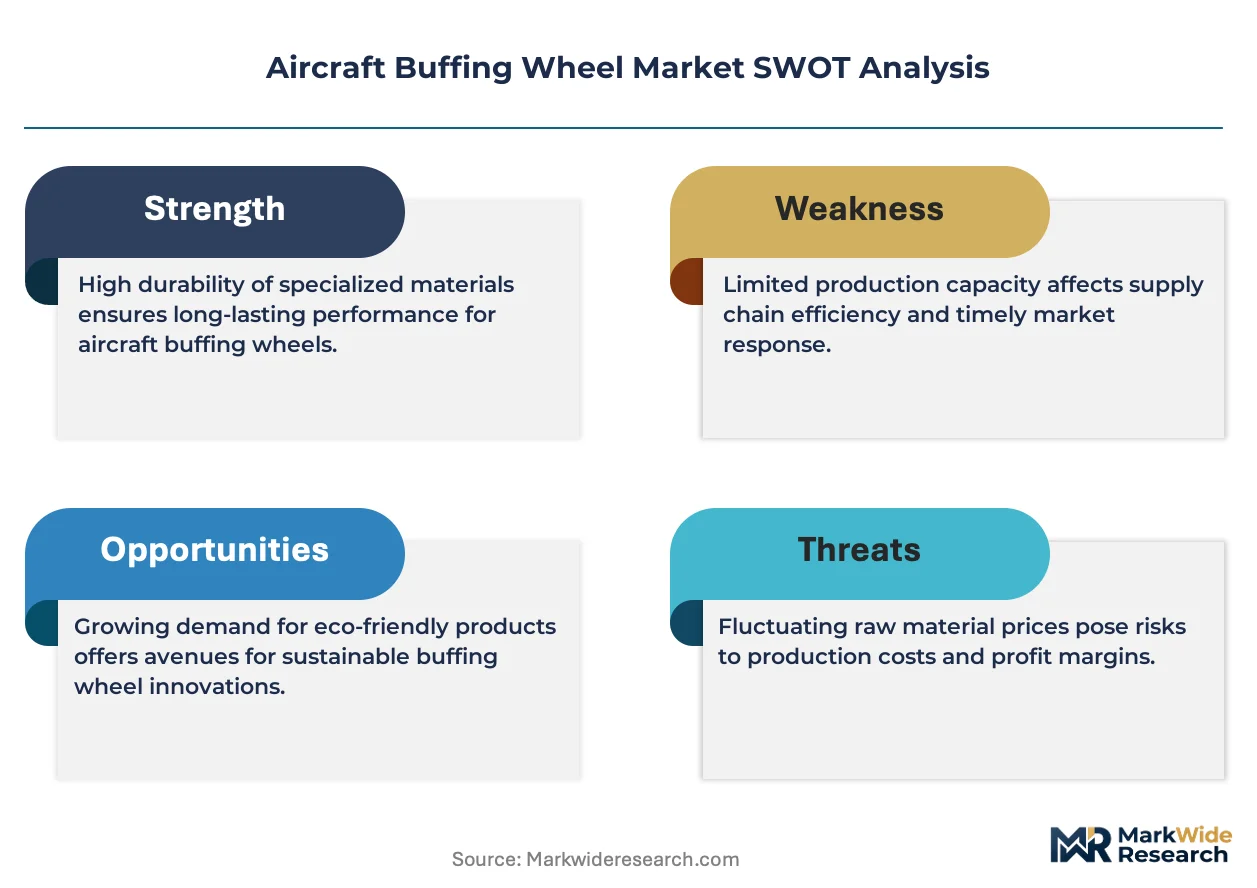
- Cotton and sisal fiber cost volatility:Raw material prices for natural substrate layers fluctuate with agricultural commodity markets, compressing margins for consumable manufacturers without backward integration into textile sourcing.
- AS9100 certification concentration:Supplier qualification thresholds limit viable sourcing options to a narrow base of quality-certified producers, creating single-source vulnerability for tier-one procurement teams.
- Non-woven abrasive substitution:Surface conditioning discs and flap wheels are displacing traditional buffing wheels in certain deburring applications within engine component shops.
Strategic Opportunities
- Indian MRO infrastructure buildout:The country's emerging maintenance hub status under DGFT import substitution policies creates first-mover positioning for consumable suppliers establishing local distribution partnerships.
- Sustainability-linked procurement mandates:OEM customers are introducing lifecycle transparency requirements for consumable materials, rewarding suppliers with verified recycled-content substrates and carbon footprint documentation.
- Robotic surface finishing integration:Automated polishing cells on new production lines are converging with machine vision systems, creating demand for precision-engineered buffing wheel sets with consistent density profiles.
Industry Challenges
- Skilled finishing technician scarcity:Experienced operators capable of matching buffing wheel grades to specific aluminum alloy temper conditions are retiring faster than training programs can replenish the workforce.
- Multi-standard certification timelines:Suppliers seeking simultaneous FAA, EASA, and CAAC approvals face extended validation periods that delay market entry and strain working capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Buffing Wheel Market |
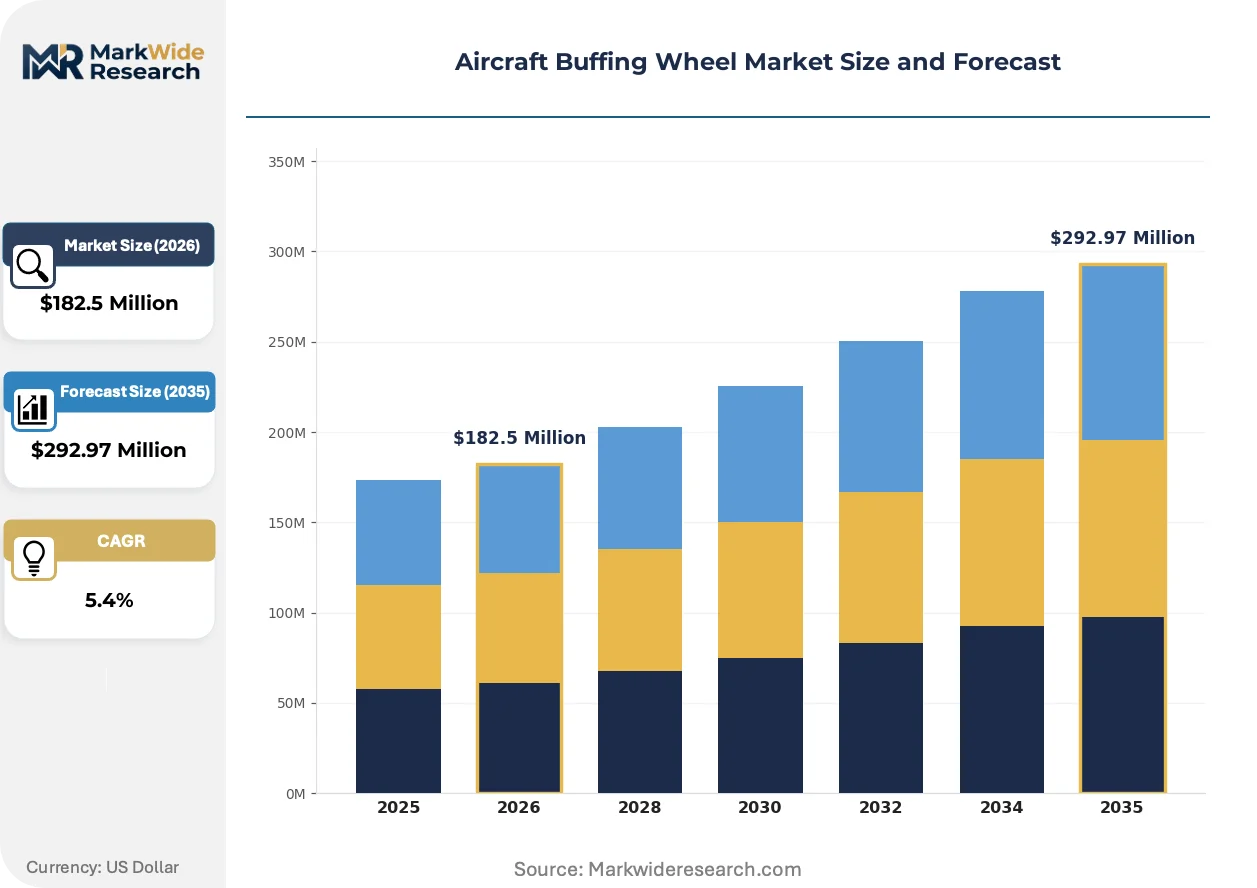
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $292.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton Buffing Wheels, Felt Buffing Wheels, Sisal Buffing Wheels, Linen Buffing Wheels Material Grade: Fine, Medium, Coarse, Extra Coarse Application: Cleaning, Polishing, Surface Finishing, Deburring End User: Aerospace Manufacturers, MRO Facilities, Component Suppliers, Aviation Maintenance Services |
| Companies Covered | Honeywell International Inc., Parker Hannifin Corporation, Safran Group, Collins Aerospace, Crane Aerospace & Electronics, The Goodyear Tire & Rubber Company, Meggitt PLC, Lufthansa Technik, Triumph Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Buffing Wheel Market Trends and Innovations
Surface finishing consumables are undergoing specification-level transformation as automation, regulatory transparency requirements, and consolidated procurement models reshape how MRO facilities and OEMs source buffing wheel products.
Robotic polishing systems are automating buffing wheel deployment on new airframe production lines, with Boeing and Airbus tier-one suppliers adopting automated cells for wing skin and fuselage panel finishing. These installations require buffing wheels with precisely calibrated density profiles and metal-center balance specifications that manual operations tolerate less strictly. The technology is automating quality consistency while compressing cycle times in high-volume manufacturing environments.
EASA Part 145 regulations are extending material traceability requirements to consumable-level documentation, compelling European maintenance organizations to reject suppliers lacking batch-level substrate origin records. Industrial consequence includes elevated administrative burden for MRO procurement teams and accelerated supplier consolidation toward integrated distributors. Component shops in Germany and France are responding by mandating digital chain-of-custody records for all surface finishing consumables.
Integrated maintenance consumable packages are displacing single-item buffing wheel orders as dominant procurement format, with North American aviation hubs adopting bundled assortments matched to specific airframe sections and maintenance check intervals. Distributors with kitting capabilities are capturing preference share from catalog-only suppliers. This pattern concentrates in the United States where legacy fleet complexity drives demand for configuration-managed consumable programs.
Aircraft Buffing Wheel Market Segmentation
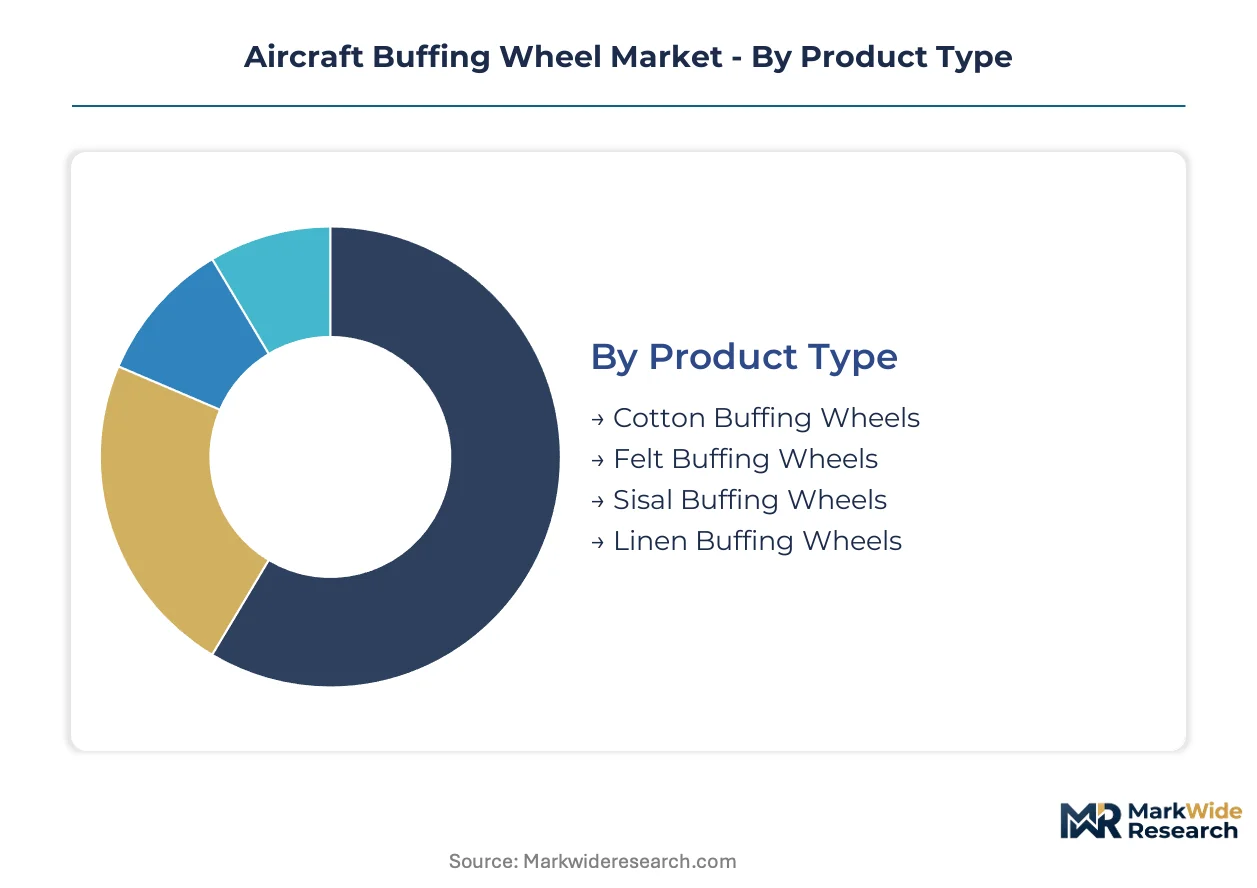
Buffing wheel procurement patterns diverge sharply across product construction, surface specification, and operational context. Understanding these segment boundaries reveals where supplier margins concentrate and where specification standards are tightening fastest.
Product Type:
Supply concentration favors natural fiber substrates with established aerospace certification trails, while synthetic alternatives struggle to penetrate OEM-approved material lists.
- Cotton Buffing Wheels:Layered cotton substrates bonded to metal centers deliver rotational stability above 3,000 RPM for aluminum skin panel treatment. Demand clusters at Boeing and Airbus tier-one suppliers in Wichita and Toulouse, where versatile polishing-to-cleaning performance reduces inventory SKU counts.
- Felt Buffing Wheels:Compressed wool-felt construction achieves mirror-grade finishes on turbine blade leading edges and landing gear struts where surface integrity governs fatigue life. Premium positioning at Safran and Collins Aerospace component shops in France and Iowa reflects exacting density specifications for final-stage finishing.
- Sisal Buffing Wheels:Aggressive cutting action from woven agave fibers suits initial grinding on titanium structural brackets before finer stages.
- Linen Buffing Wheels:Tighter weave patterns than cotton provide intermediate cutting with reduced fiber shedding on composite substrates.
Today's leader: Cotton Buffing Wheels. Tomorrow's challenger: Felt Buffing Wheels.
Material Grade:
Cost tier separation runs deepest between certified aerospace grades and commercial-industrial equivalents, with AS9100 traceability commanding 40-60% price premiums.
- Fine:Ultra-smooth abrasive grain distribution below 400 grit enables final cosmetic finishing on executive jet interior trim and exterior brightwork. Gulfstream and Dassault completion centers in Savannah and Bordeaux specify fine-grade wheels for customer-facing surfaces where defect visibility is zero-tolerance.
- Medium:180-320 grit range balances material removal with surface quality for production-line skin panel preparation. Airbus Mobile and Boeing Charleston facilities standardize on medium grades for fuselage section pre-paint conditioning, driving volume procurement through integrated distributor contracts.
- Coarse:80-150 grit aggression targets weld seam blending and repair area leveling on heavy maintenance checks.
- Extra Coarse:Sub-80 grit construction strips corrosion and old coatings from legacy fleet aluminum structures during depot overhaul.
Fine grades extract highest margin per wheel. Coarse grades move fastest in unit volume.
Application:
Volume concentration in cleaning and polishing masks a value migration toward surface finishing where OEM first-build specifications command price authority.
- Surface Finishing:Precision treatment of airframe skin panels, engine nacelles, and control surfaces to Ra 0.4-1.6 micrometer specifications. OEM production lines in Everett, Hamburg, and Tianjin specify grade-matched wheel sets with documented batch consistency, creating sole-source relationships with certified suppliers.
- Polishing:Intermediate luster enhancement between cutting and final finishing stages on aluminum and titanium components. MRO facilities at Delta TechOps in Atlanta and Lufthansa Technik in Hamburg consume polishing-grade wheels in predictable cycles tied to C-check intervals.
- Cleaning:Surface preparation for NDT inspection and adhesive bonding on repair patches.
- Deburring:Edge breaking on machined components, increasingly contested by non-woven abrasive discs in engine shops.
Surface Finishing commands specification authority. Deburring faces substitution pressure.
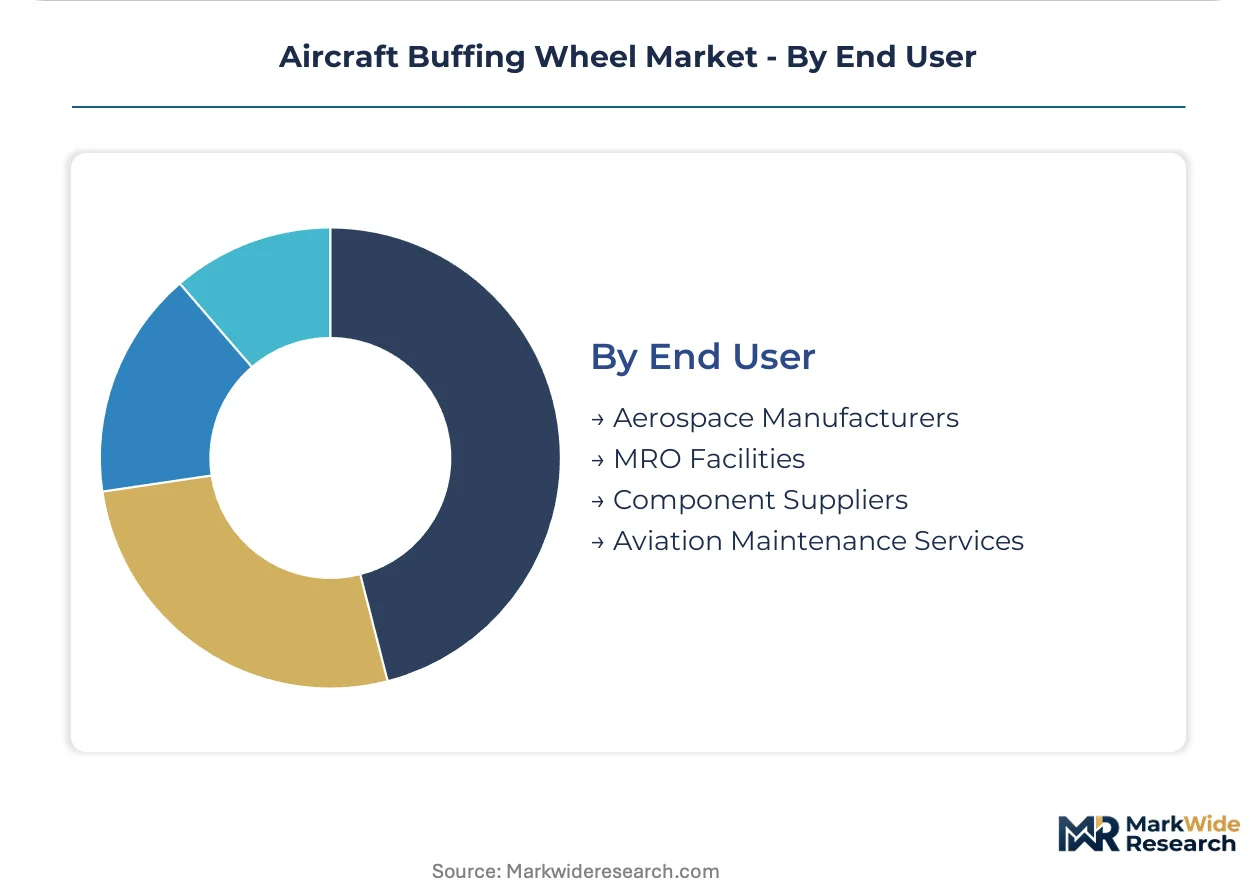
End User:
Customer type determines procurement format, with aerospace manufacturers favoring long-term supply agreements while MRO facilities prioritize kit-based spot purchasing.
- MRO Facilities:Depot-level maintenance organizations execute recurring surface restoration on aging fleets during heavy checks. ST Engineering in Singapore and AAR in Indianapolis drive consumable demand through configuration-managed wheel assortments matched to aircraft type and check interval.
- Aerospace Manufacturers:OEM production lines integrate buffing wheels into automated finishing cells with robotic deployment. Spirit AeroSystems in Wichita and GKN Aerospace in Bristol specify density-calibrated wheel sets with metal-center balance certification for machine-mounted applications.
- Component Suppliers:Tier-two and tier-three shops producing landing gear, actuators, and engine casings for upstream assembly.
- Aviation Maintenance Services:Line maintenance and regional repair stations handling A-check and minor repair scope.
MRO Facilities anchor current demand scale. Aerospace Manufacturers shape tomorrow's specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aircraft buffing wheel manufacturing traces its industrial lineage to early twentieth-century American aerospace clusters, where Wichita and Los Angeles established the first precision finishing supply chains for military and commercial aviation. These origins shaped a market that now distributes certified consumables through maintenance hubs and production centers across multiple continents.
United States
FAA 14 CFR Part 43 compliance mandates and legacy fleet maintenance cycles drive procurement concentration. The FAA airworthiness directives tighten material traceability requirements for aftermarket components. Wichita's Spirit AeroSystems facility and Boeing's Charleston production line anchor demand for density-calibrated cotton buffing wheels in automated finishing cells.
Germany
EASA Part 145 regulations extend material traceability to consumable-level documentation, compelling maintenance organizations to consolidate supplier relationships. The country's national aviation regulator enforces batch-level substrate origin records for surface finishing consumables. Lufthansa Technik in Hamburg and component shops across Bavaria specify grade-matched wheel sets with digital chain-of-custody documentation.
France
Safran Group's dedicated MRO supply contracts with European flag carriers sustain aftermarket procurement volumes. EASA continuing airworthiness regulations shape conformity requirements across French maintenance organizations. Toulouse's Airbus final assembly line and Safran component facilities in the Paris region drive premium-grade felt buffing wheel demand for turbine blade finishing.
United Kingdom
GKN Aerospace in Bristol integrates buffing wheels into robotic polishing systems for wing skin and fuselage panel finishing. The country's civil aviation authority maintains equivalent material traceability standards to EASA frameworks. Southwest England's aerospace corridor concentrates OEM-aligned specification development for next-generation composite substrate treatments.
India
DGFT import substitution policies and emerging MRO hub status create first-mover positioning for consumable suppliers. The Directorate General of Civil Aviation regulates maintenance organization certification with tightening material documentation requirements. ST Engineering's expanding Bangalore facility and Delhi-NCR maintenance clusters drive configuration-managed wheel assortment demand for narrow-body fleet checks.
Aircraft Buffing Wheel Market Competitive Landscape
The competitive structure tilts toward diversified aerospace conglomerates with integrated distribution networks. Supplier qualification thresholds under AS9100 and FAA/EASA regulations concentrate viable sourcing options among established quality-certified producers. Three archetypes dominate: aerospace-grade consumable specialists with backward integration into textile sourcing, diversified industrial distributors leveraging kitting capabilities, and OEM-aligned specification developers. Competitive moves center on strategic partnerships with tier-one airframe manufacturers and geographic expansion into emerging MRO hubs.
Among North American diversified industrials, Parker Hannifin Corporation and Honeywell International Inc. occupy positions as integrated maintenance consumable suppliers with distribution reach across aviation hubs. Collins Aerospace exemplifies the OEM-aligned specification tier, anchoring aftermarket relationships through original surface finish requirements. Safran Group represents the European MRO-contract anchor, securing dedicated supply agreements with flag carrier maintenance networks. These three companies illustrate how certification depth and customer integration separate viable competitors from catalog-only suppliers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| Safran Group |
| Collins Aerospace |
| Crane Aerospace & Electronics |
| The Goodyear Tire & Rubber Company |
| Meggitt PLC |
| Lufthansa Technik |
| Triumph Group |
| Others |
Pricing and Supply Chain Analysis
Robotic polishing system integration on Boeing and Airbus production lines simultaneously compresses cycle-time economics and concentrates procurement power among tier-one suppliers capable of delivering density-calibrated wheel sets with machine-mount certification. This automation transition elevates specification barriers for manual-grade producers while rewarding AS9100-certified manufacturers with sole-source positioning on new airframe programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace grades from commercial-industrial equivalents and uncertified imports. Price differentiation centers on material traceability documentation and batch-level substrate origin records demanded by EASA Part 145 and FAA 14 CFR Part 43 compliance layers. Cost compression in economy tiers is intensifying because Indian and Southeast Asian suppliers are expanding cotton fiber wheel production without quality certification investment. MRO facilities exhibit highest price sensitivity due to competitive tendering for heavy check contracts, while OEM production lines prioritize specification adherence over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for metal centers and substrate layers remain underdeveloped in this consumables category, creating linear material throughput without circular recovery economics. Supply concentrates in the United States, Germany, and China, with American producers dominating certified aerospace grades and Chinese manufacturers supplying commercial-industrial tiers. Raw material dependencies draw from Egyptian long-staple cotton for premium wheels, New Zealand wool felt for turbine-grade finishing, and Brazilian sisal for aggressive cutting applications. Single-source vulnerability runs through Egyptian cotton supply channels subject to Nile basin agricultural volatility. Distribution runs through integrated aerospace distributors with kitting capabilities rather than direct manufacturer-to-buyer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EASA and FAA traceability mandates continuously elevate compliance costs and consolidate viable supplier pools. The FAA's 14 CFR Part 43 material documentation requirements serve as the primary demand amplifier, forcing MRO procurement teams toward certified providers with digitized chain-of-custody systems.
For Market Incumbents: Hedge against non-woven abrasive substitution in engine component deburring applications by deepening backward integration into textile sourcing and expanding felt wheel capacity for turbine blade finishing. Collins Aerospace and Safran Group procurement consolidation threatens distributor margins; incumbents should secure long-term supply agreements with flag carrier MRO networks before contract windows close. For New Entrants and Emerging Players: Enter via DGFT import substitution corridors in India, where ST Engineering and emerging Delhi-NCR maintenance clusters lack configuration-managed wheel assortment suppliers. The narrow-body fleet check market offers lowest certification barriers among aerospace end uses. A kit-based go-to-market model matching wheel grades to specific airframe sections and check intervals bypasses incumbent catalog dominance. For Investors and Strategic Acquirers: Valuations sit cheapest among commercial-industrial grade producers possessing textile manufacturing assets but lacking AS9100 certification investment. Long-term viability over the next decade hinges on regulatory compliance depth rather than production scale alone. The signal to watch is EASA extension of material traceability requirements to consumable-level batch documentation, which would accelerate supplier consolidation and reward certified acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks tier-one procurement at Spirit AeroSystems and GKN Aerospace robotic finishing cells. |
| Backward Integration into Textile Sourcing | Captures margin compression from Egyptian cotton price volatility and secures substrate consistency. |
| Configuration-Managed Kit Development | Matches bundled wheel assortments to Boeing 737 and Airbus A320 check intervals at Delta TechOps. |
| Digital Chain-of-Custody Implementation | Satisfies Lufthansa Technik and Air France Industries batch-level origin documentation mandates. |
| Indian Distribution Partnership | Positions for DGFT import substitution incentives at ST Engineering Bangalore and Delhi-NCR clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with MRO procurement managers, OEM finishing cell engineers, AS9100 certification auditors, and aerospace distributor category buyers with secondary validation against FAA airworthiness directive filings, EASA Part 145 organization approvals, customs trade data for cotton and felt substrate imports, and SEC 10-K disclosures from diversified industrial suppliers. Bottom-up demand modeling from individual MRO facility consumption patterns triangulated against top-down OEM production line integration forecasts.
Historical reference periods anchored the projection framework to established maintenance cycle patterns and new aircraft delivery schedules across the analysis window. Segmentation dimensions modeled include product construction type, material grade tier, application specification, and end-user procurement format. CAGRs derived from weighted average growth across these segments, incorporating titanium and composite substrate expansion rates, legacy fleet age demographics, and robotic finishing cell adoption curves at tier-one suppliers.
The model holds under stable regulatory enforcement of FAA and EASA traceability mandates; deviation in certification timeline delays or raw material supply disruptions would shift supplier consolidation velocity and pricing tier boundaries. Practitioners should monitor EASA consumable-level documentation rulemaking and Egyptian cotton harvest forecasts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market