
 Pureed Food Market | 2026-2036
Pureed Food Market Size, Share, and Industry Trends Forecast 2026-2036
Pureed Food Market Analysis
Home care providers are rotating toward retail-format pureed meals as institutional budgets tighten. Nestlé S.A. leverages its geriatric nutrition portfolio to anchor shelf-stable distribution across North American pharmacy chains. Kerry Group competes on flavor masking technology that improves palatability in medically prescribed textures. Danone sustains its position through dairy-based puree formulations targeting post-surgical recovery diets.
Pureed food consists of mechanically or thermally processed sustenance milled to a smooth, semi-liquid consistency, typically between 0.5 and 4 millimeters particle size for dysphagia safety, serving clinical nutrition and convenience food applications. Vegetable purees dominate volume due to their integration into infant feeding and senior care protocols, while fruit purees capture premium positioning through clean-label and organic claims in retail channels. Pouch packaging is displacing rigid formats in home care settings where single-serve portability reduces waste and caregiver burden.
The FDA enforces texture standards under the Food Safety Modernization Act, while the USDA governs nutritional content in federally subsidized meal programs, collectively elevating compliance costs for new entrants. The EU Green Deal and F-Gas Regulation indirectly reshape puree processing by pressuring cold-chain energy intensity, though direct food texture regulation remains member-state fragmented. Stakeholders must monitor evolving dysphagia diet frameworks from the International Dysphagia Diet Standardisation Initiative as these protocols increasingly dictate procurement specifications across healthcare systems.
Market Dynamics
Home care providers are consolidating purchasing power around shelf-stable pureed meals as institutional reimbursement rates compress, forcing manufacturers to reconfigure distribution toward retail-format packaging and direct-to-consumer logistics.
Growth Catalysts
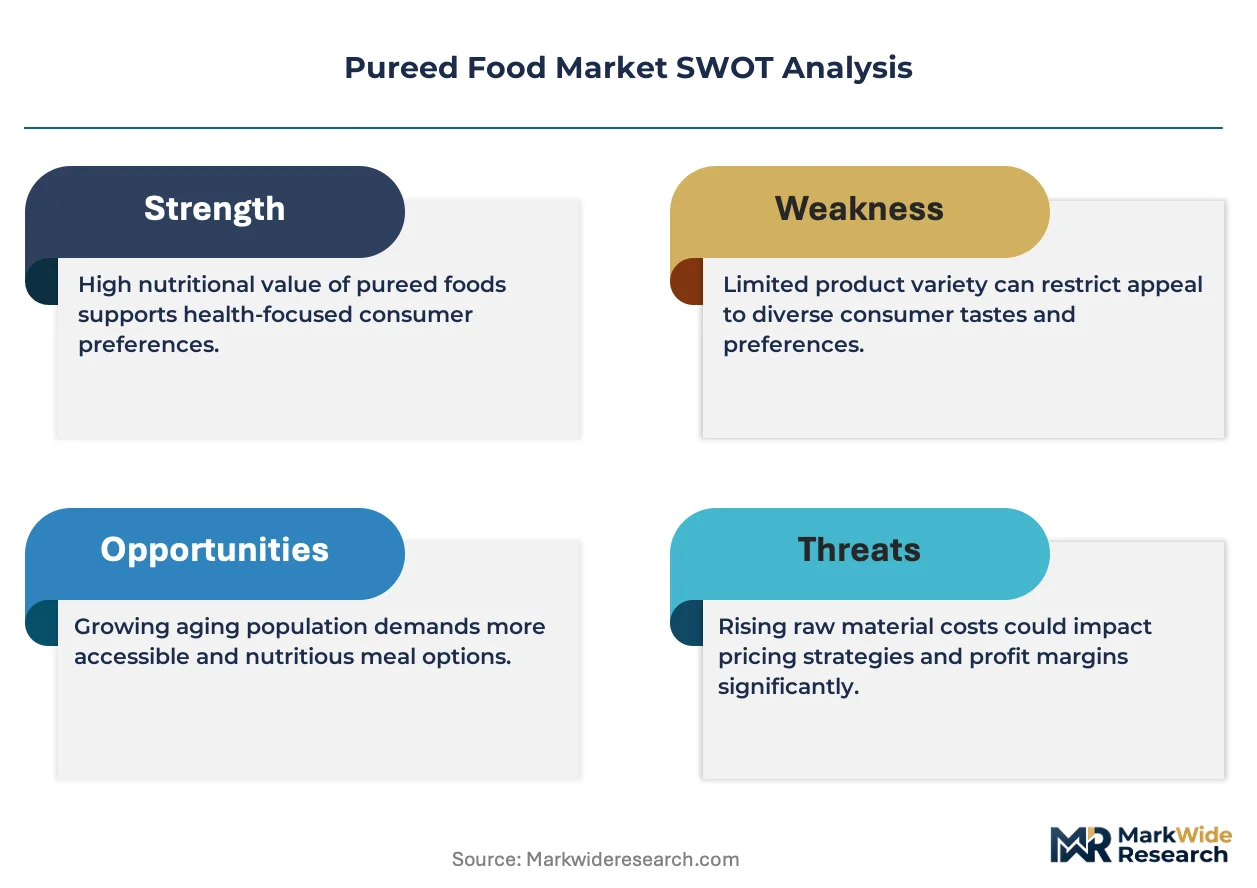
- Aging Demographics:The United States, Japan, and Germany face accelerating dysphagia prevalence among populations over 75, expanding the addressable patient base for texture-modified nutrition.
- IDDSI Framework Adoption:Healthcare systems across Australia, Canada, and the United Kingdom are mandating International Dysphagia Diet Standardisation Initiative compliance in procurement specifications, standardizing demand for certified pureed textures.
- Pouch Packaging Innovation:Flexible retort pouches reduce per-unit shipping weight by 60% versus glass jars, enabling cost-effective direct distribution to home care settings.
Market Restraints
- Ingredient Cost Volatility:Fruit and vegetable puree concentrates face price swings tied to climate-driven harvest variability in California, Spain, and Chile.
- Regulatory Fragmentation:EU member states maintain divergent texture classification systems outside IDDSI adoption, forcing manufacturers to maintain multiple production specifications.
- Substitution Pressure:Ready-to-drink medical nutrition shakes from Nestlé and Abbott capture dysphagia patients seeking convenience over spoon-thick textures.
Strategic Opportunities
- Underpenetrated Home Care:Brazil and Mexico lack established pureed meal distribution networks, presenting first-mover advantages for shelf-stable entrants.
- Clean-Label Positioning:Organic certification and single-ingredient claims command 40% retail premiums in German and French pharmacy channels.
- Telehealth Integration:Remote dysphagia screening protocols are expanding prescription-linked meal delivery in Australia's aged care system.
Industry Challenges
- Texture Validation Expertise:IDDSI Level 4-7 compliance requires specialized rheology testing capabilities scarce outside established medical nutrition firms.
- Cold-Chain Reconfiguration:Frozen puree producers face capital intensity in converting to ambient-stable retort processing without sacrificing vitamin retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pureed Food Market |
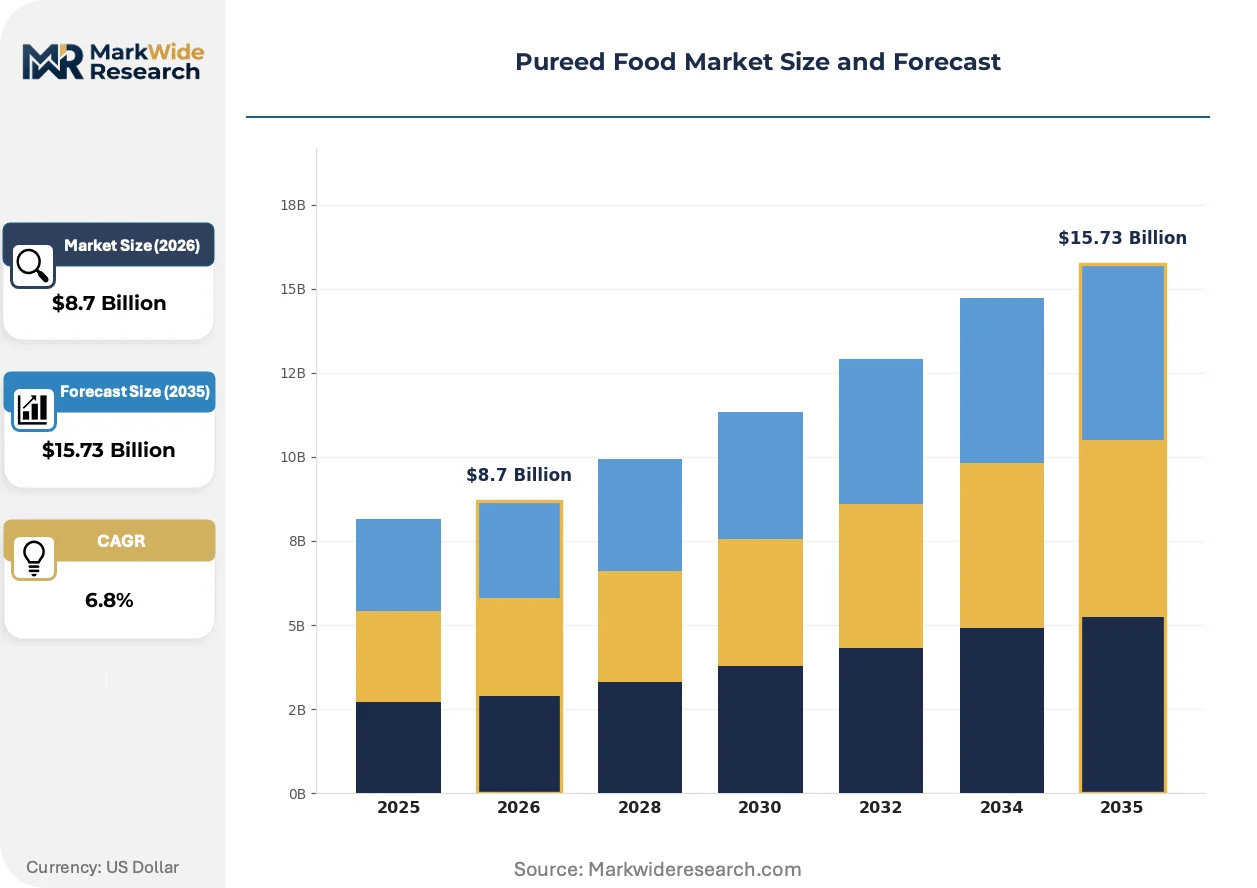
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Purees, Fruit Purees, Meat Purees, Dairy Purees End User: Hospitals, Nursing Homes, Home Care, Restaurants Packaging Type: Pouches, Tubs, Jars, Cans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Nestlé S.A., Döhler Group, Ingredion Incorporated, Danone, Kerry Group, Blossom Foods, SVZ Industrial Fruit & Vegetable Ingredients, AGRANA Beteiligungs-AG, Kiril Mischeff Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pureed Food Market Emerging Trajectories
Retort pouch technology and high-pressure processing are collapsing the traditional trade-off between shelf stability and sensory quality, enabling manufacturers to serve institutional and retail channels from unified production lines.
High-pressure processing (HPP) preserves heat-sensitive micronutrients in vegetable purees while achieving commercial sterility without thermal degradation. Pediatric and geriatric nutrition buyers in Japan and South Korea are adopting HPP purees at triple-digit annual rates for immune-compromised patient populations. This technology is displacing conventional retort canning in premium positioning, compressing margin structures for legacy thermal processors.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in frozen puree cold chains, elevating capital costs for temperature-controlled distribution. Manufacturers serving Nordic and Benelux healthcare systems are accelerating shift to ambient-stable formats to circumvent refrigeration infrastructure dependencies. German institutional buyers now specify climate-impact thresholds in procurement tenders, favoring shelf-stable suppliers.
Hospital discharge protocols are shortening length-of-stay for dysphagia patients, compressing the window for institutional pureed meal consumption and redirecting demand toward home-delivered solutions. Home care agencies in the United States and United Kingdom are replacing bulk institutional contracts with patient-specific subscription models. This behavioral pivot concentrates purchasing power with specialized medical nutrition distributors possessing last-mile cold chain or ambient logistics capabilities.
Pureed Food Market Segmentation
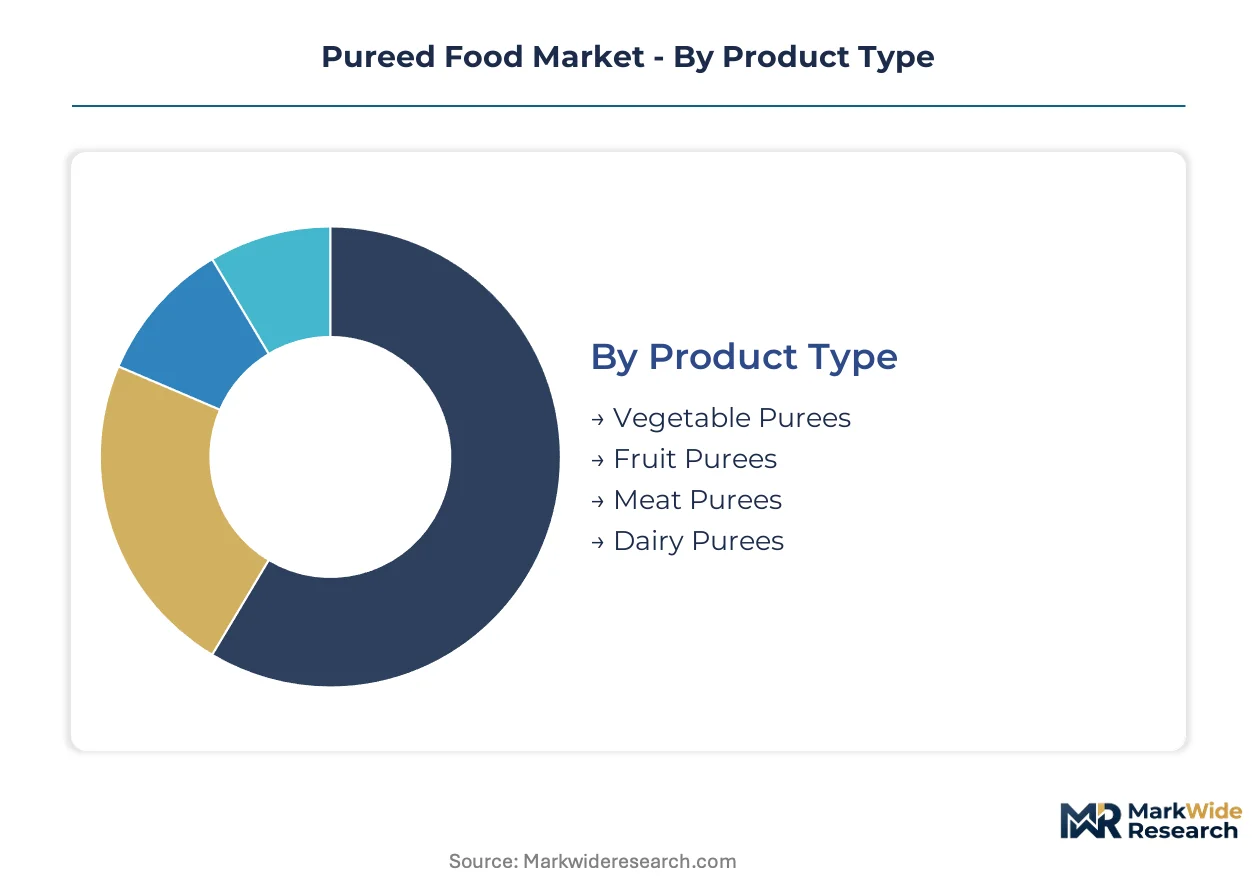
Pureed food segmentation reflects divergent margin economics across clinical versus retail channels. Texture certification requirements and packaging format choices create distinct profitability profiles that manufacturers must navigate.
Product Type:
Margin pools concentrate in dairy-based formulations where post-surgical recovery protocols command reimbursement premiums, while vegetable purees compete on volume through institutional contracts.
- Vegetable Purees:Thermally processed carrots, peas, and squash milled to IDDSI Level 4-7 specifications. Demand concentrates in United States nursing homes where CMS reimbursement codes cover texture-modified meals for dysphagia patients, though per-unit margins compress under bulk procurement.
- Fruit Purees:Single-ingredient apple, pear, and berry preparations targeting pediatric and geriatric clean-label preferences. German and French pharmacy channels absorb organic-certified formats at substantial retail premiums, making this the most profitable volume tier.
- Meat Purees:Protein-fortified beef, chicken, and turkey formulations meeting USDA child nutrition standards.
- Dairy Purees:Yogurt and custard-based textures for post-operative protein delivery.
Vegetable purees hold installed capacity. Fruit purees are rotating up the share rankings.
End User:
Customer-type economics split between institutional volume contracts and direct-to-consumer subscription models with divergent logistics costs.
- Hospitals:Acute-care settings purchasing IDDSI-compliant trays through group purchasing organizations. Japan's PMDA-enforced texture standards and shortened length-of-stay protocols are compressing consumption windows and redirecting procurement toward discharge-ready retail formats.
- Home Care:Individual patients and family caregivers sourcing shelf-stable meals through pharmacy chains and telehealth-linked subscriptions. Australia's aged care system is expanding prescription-linked meal delivery, creating the steepest expansion trajectory among end-user categories.
- Nursing Homes:Long-term care facilities under state-level dietary regulations.
- Restaurants:Commercial kitchens producing texture-modified options for senior dining programs.
Hospitals maintain procurement volume leadership. Home care is gaining share fastest.
Packaging Type:
Format selection determines cold-chain dependency and last-mile economics, with ambient-stable options capturing investment preference.
- Pouches:Flexible retort structures reducing shipping weight by 60% versus glass alternatives. United States home care agencies are consolidating purchasing around single-serve portability that minimizes caregiver burden and food waste.
- Tubs:Rigid plastic containers dominating institutional bulk service.
- Jars:Glass formats retaining premium positioning in European retail.
- Cans:Legacy metal containers for emergency stockpile and military applications.
Tubs retain institutional installed base. Pouches are climbing the fastest.
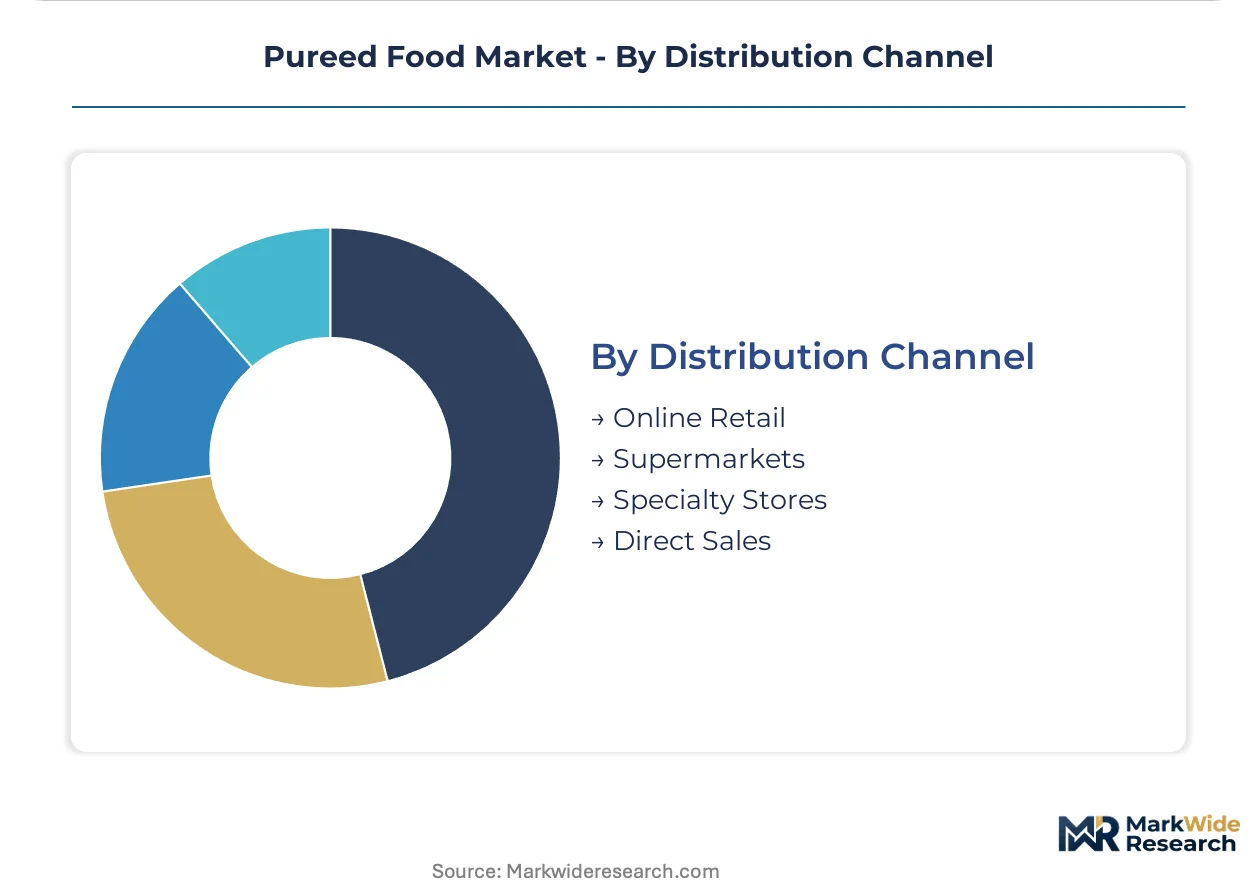
Distribution Channel:
Channel strategy separates reimbursement-linked institutional flows from out-of-pocket retail purchases with distinct margin structures.
- Online Retail:Direct-to-consumer platforms enabling subscription-based replenishment for homebound dysphagia patients. United Kingdom caregivers are migrating toward automated delivery schedules that reduce pharmacy trip frequency.
- Supermarkets:Mass retail placement for shelf-stable infant and senior nutrition. German chains are expanding dedicated medical nutrition aisle space, capturing walk-in demand from discharged hospital patients.
- Specialty Stores:Pharmacy and medical supply channels with trained staff consultation.
- Direct Sales:Manufacturer contracts with healthcare systems and home care agencies.
Direct sales hold contracted volume base. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean fruit puree exporters supply German pharmaceutical chains with organic-certified concentrates, while California vegetable processors ship IDDSI-compliant formulations to Japanese nursing home distributors.
United States
CMS reimbursement codes for texture-modified meals drive nursing home procurement volumes, while home care agencies pivot toward subscription-based retail formats. The FDA enforces Food Safety Modernization Act texture standards that elevate compliance barriers for new entrants. Chicago-area food processing clusters host retort pouch manufacturing lines serving pharmacy chain distribution networks.
Germany
Pharmacy channel absorption of organic-certified purees commands substantial retail premiums in elderly nutrition segments. The EU F-Gas Regulation pressures frozen puree cold-chain operators toward ambient-stable format conversions. Bavarian institutional buyers now specify climate-impact procurement thresholds favoring shelf-stable suppliers.
Japan
PMDA-enforced texture standards and accelerated hospital discharge protocols compress institutional consumption windows. METI guidelines on elderly nutrition procurement increasingly reference IDDSI compliance specifications. Osaka-based medical nutrition distributors are consolidating last-mile logistics for home-delivered pureed meal subscriptions.
Australia
Telehealth-linked prescription meal delivery is expanding fastest among aged care system innovations. The Therapeutic Goods Administration maintains strict labeling requirements for texture-modified foods in healthcare procurement. Melbourne and Sydney home care agencies are replacing bulk institutional contracts with patient-specific replenishment models.
Brazil
Underpenetrated pureed meal distribution networks present first-mover positioning for shelf-stable entrants targeting aging demographics. ANVISA governs nutritional content claims in medical food categories with evolving texture classification frameworks. São Paulo hospital discharge coordinators are piloting retail-format pureed meal prescriptions for dysphagia patients.
Pureed Food Market Vendor Landscape
Player mix skews toward diversified nutrition conglomerates with established medical food divisions and specialized ingredient suppliers with texture modification expertise. Market structure concentrates around three to five integrated operators controlling shelf-stable distribution through pharmacy chain relationships. Strategic archetypes include geriatric nutrition specialists, clean-label organic pureé processors, and institutional contract manufacturers with IDDSI certification capabilities. Competitive moves center on retort pouch capacity expansion and telehealth platform partnerships for direct-to-home prescription fulfillment.
Among Switzerland-based nutrition conglomerates, Nestlé S.A. occupies a position exemplifying diversified medical food portfolio depth, while Irish taste and nutrition specialists Kerry Group represent flavor masking technology integration for palatability improvement in prescribed textures. French dairy nutrition operators Danone sit within the post-surgical recovery diet positioning archetype. These three anchors illustrate the competitive spectrum from broad geriatric nutrition platforms to specialized texture and sensory optimization capabilities.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Döhler Group |
| Ingredion Incorporated |
| Danone |
| Kerry Group |
| Blossom Foods |
| SVZ Industrial Fruit & Vegetable Ingredients |
| AGRANA Beteiligungs-AG |
| Kiril Mischeff Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between California vegetable processors and Japanese nursing home distributors lock in both raw material access and price visibility across multi-year procurement cycles, insulating buyers from climate-driven harvest volatility while securing supply for IDDSI-certified production lines.
Pricing Analysis
Thermal-processing versus high-pressure-processing technology-generation pricing gaps stratify the market into three distinct tiers. Conventional retort canning commands economy positioning through established scale, while HPP-equipped facilities capture premium pricing through nutrient-retention claims in pediatric and geriatric segments. Pricing pressure stems from substitution by ready-to-drink medical nutrition shakes from Nestlé and Abbott, which compress margins for spoon-thick textures in home care channels. Institutional buyers in United States nursing homes exhibit highest price sensitivity under CMS reimbursement constraints, whereas German pharmacy channels absorb substantial organic certification premiums with minimal volume elasticity.
Supply Chain Analysis
Inbound logistics costs through Port of Long Beach congestion and trans-Pacific container availability constraints elevate landed costs for Chilean fruit concentrate shipments to European pharmaceutical chains. Raw material supply concentrates in California vegetable growing regions, Spanish tomato processing corridors, and Chilean berry cultivation zones. Processing dependencies rest on retort pouch film suppliers concentrated in Chinese and South Korean petrochemical corridors. Single-source vulnerability in HPP equipment manufacturing creates chokepoint risk for premium tier expansion. Distribution feeds from centralized retort facilities through pharmacy chain warehousing and direct-to-consumer subscription fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated home care agencies in the United States and United Kingdom, which are replacing fragmented bulk institutional contracts with centralized subscription procurement that concentrates volume leverage among fewer purchasing decision-makers.
For Market Incumbents: Secure IDDSI Level 4-7 certification capabilities as a defensive moat against emerging clean-label entrants, while expanding retort pouch capacity in Chicago-area processing clusters to capture pharmacy chain distribution slots before substitution by medical nutrition shakes accelerates. For New Entrants and Emerging Players: Lead with organic-certified fruit puree positioning in German and French pharmacy channels where 40% retail premiums sustain new brand economics, targeting telehealth-linked prescription delivery models in Australia's aged care system as the most penetrable go-to-market pathway. For Investors and Strategic Acquirers: Capital is best deployed toward specialized texture-modification technology firms with HPP processing capabilities and existing IDDSI compliance infrastructure, as these assets command scarcity premiums in a market where cold-chain reconfiguration costs deter legacy frozen puree operators; watch for ANVISA regulatory harmonization in Brazil as the signal indicating first-mover window closure for shelf-stable entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Capacity Expansion | Reduces shipping weight by 60% versus glass, enabling cost-effective home care distribution through United States pharmacy chains. |
| IDDSI Certification Investment | Unlocks procurement eligibility across Australian, Canadian, and United Kingdom healthcare systems mandating standardized texture compliance. |
| Telehealth Platform Partnership | Links dysphagia screening protocols to automated meal replenishment in Australia's prescription-linked aged care delivery models. |
| Organic Certification Acquisition | Captures 40% retail premiums in German and French pharmacy channels where clean-label positioning commands patient loyalty. |
| HPP Technology Integration | Preserves heat-sensitive micronutrients for immune-compromised populations in Japan and South Korea at triple-digit adoption rates. |
Methodological Framework
A standing panel of food processing plant managers, institutional procurement directors at United States nursing home chains, pharmacy category buyers in Germany, and telehealth platform operators in Australia provided ongoing calibration across primary interview cycles, supplemented by secondary validation through FDA Food Safety Modernization Act filings, USDA child nutrition program data, IDDSI protocol documentation, and EU F-Gas Regulation impact assessments, with bottom-up volume builds triangulated against top-down market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with analytical frameworks modeling segmentation across product type, end-user category, packaging format, and distribution channel dimensions. CAGRs were derived from trend extrapolation anchored in aging demographic trajectories and dysphagia prevalence rates, incorporating climate-driven harvest variability and reimbursement policy shifts as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained IDDSI framework adoption, stable CMS reimbursement codes, or contained input cost volatility would require recalibration. Practitioners should keep alternative scenarios live as EU member-state regulatory fragmentation and substitution pressure from medical nutrition shakes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Goat Milk Formula Market