
 North America Baby Food Market | 2026-2036
North America Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baby Food Market Outlook
Market Context
USDA Organic certification is collapsing the competitive field, forcing smaller brands to either absorb compliance costs or exit shelf space entirely. Danone sustains its North American position through backward integration into dairy sourcing and specialized pediatric nutrition R&D. Abbott Laboratories anchors hospital and clinical channels with its metabolic and allergy-focused infant formulas. Kraft Heinz competes aggressively on price in mainstream grocery, leveraging its manufacturing scale to occupy volume-tier placements across Walmart and Kroger banners.
Technical Definition and Structural Segments
North America baby food encompasses commercially prepared, nutritionally formulated products for infants and toddlers from birth to thirty-six months, typically manufactured through thermal processing, aseptic filling, or high-pressure pasteurization to ensure microbiological safety while preserving vitamin stability. The category serves dual commercial purposes: substituting or complementing breast milk during early infancy, then transitioning palates toward family foods through texture-graded purees and finger foods. Pouches now lead packaging format growth due to parental demand for portable, mess-free feeding occasions, though glass jars retain margin concentration in premium organic tiers. Organic ingredient type claims command shelf-space premiums, while online retail channels are displacing supermarkets as the fastest-growing distribution vector for subscription-based replenishment models.
Regulatory Framework and Outlook
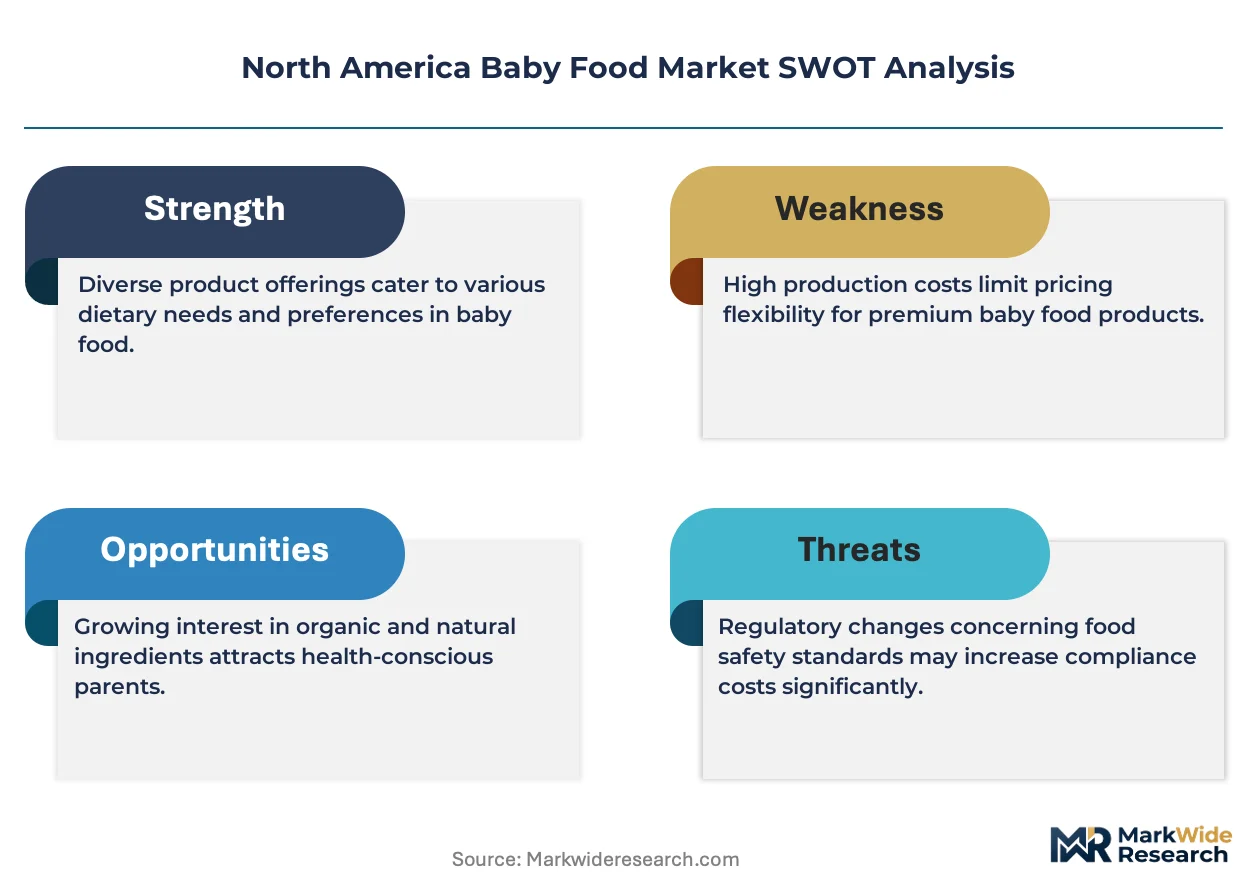
The FDA governs infant formula through the Federal Food, Drug, and Cosmetic Act and its implementing quality-control regulations, while the USDA National Organic Program certifies organic claims through accredited third-party inspectors. Health Canada and PMRA coordinate cross-border standards through joint scientific reviews, though labeling divergence still fragments binational product portfolios. Stakeholders must monitor pending FDA guidance on heavy-metal limits in finished baby foods, as this rulemaking will force reformulation investments or supply-chain switches for multiple ingredient categories.
Market Dynamics
USDA Organic certification requirements are compressing the competitive field, forcing smaller brands to absorb compliance costs or surrender shelf space to vertically integrated dairy processors with captive organic supply chains.
Growth Catalysts
- California organic demand concentration:Premium organic baby food penetration in California exceeds all other U.S. states, creating a test-bed market for clean-label innovations that diffuse eastward.
- FDA infant formula safety updates:The agency's strengthened quality-control regulations are accelerating hospital channel consolidation around clinically validated pediatric nutrition portfolios.
- Pouch packaging technology:Aseptic spouted pouches are capturing portable feeding occasions, displacing rigid containers in on-the-go consumption contexts.
Market Restraints
- Organic dairy input cost volatility:Certified organic milk powder and whey protein concentrate prices fluctuate with pasture availability and feed grain markets, compressing margin predictability for formula manufacturers.
- Heavy metal supply-chain exposure:Rice-based ingredients and root vegetables concentrate naturally occurring arsenic and lead, forcing reformulation investments or ingredient sourcing switches ahead of pending FDA guidance.
- Retail channel concentration:Walmart and Kroger banner consolidation in mainstream grocery creates buyer power asymmetry, extracting slotting fee concessions and promotional depth from mid-tier brands.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer platforms with predictive algorithms are displacing supermarket trips for routine purchases, capturing lifetime value through automated reordering.
- Metabolic and allergy-focused formulas:Specialized clinical nutrition segments remain underpenetrated relative to standard cow's milk-based offerings, rewarding R&D investment in hydrolyzed protein and amino acid formulations.
- High-pressure pasteurization convergence:Cold-pressure processing paired with clean-label positioning enables vitamin stability without thermal degradation, opening premium shelf space for refrigerated organic purees.
Industry Challenges
- Pediatric nutrition R&D talent scarcity:Formulation scientists with dual expertise in early-life immunology and food safety microbiology command premium compensation, constraining mid-cap brand innovation velocity.
- Multi-jurisdictional label compliance:Divergent FDA and Health Canada disclosure requirements fragment binational product portfolios, forcing SKUs with jurisdiction-specific packaging.
- Legacy ERP integration with traceability systems:Lot-level ingredient tracking mandated by FSMA preventive controls requires retrofitting manufacturing execution software, extending compliance timelines for smaller processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baby Food Market |
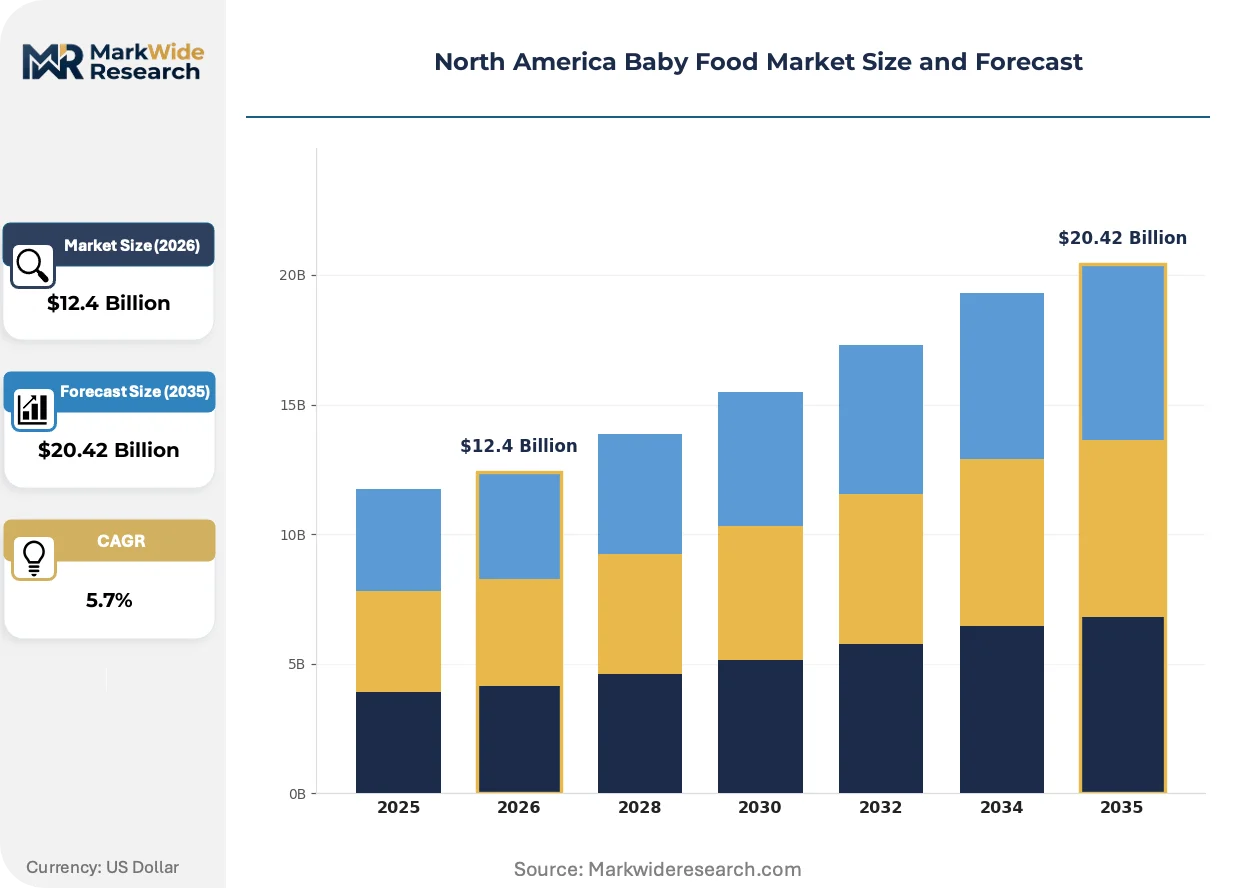
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Snacks, Cereals, Meals Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores Packaging Type: Jars, Pouches, Tubs, Cans Ingredient Type: Organic, Conventional, Gluten-Free, Non-GMO |
| Companies Covered | Hain Celestial Group, Reckitt Benckiser Group, Kraft Heinz Company, Beech-Nut Nutrition Corporation, Danone, Abbott Laboratories, Nestle, Perrigo Company, Hero Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baby Food Market Strategic Shifts
Clean-label ingredient sourcing and cold-processing technologies are redrawing competitive boundaries between mass-market and premium organic tiers, while regulatory pressure on heavy metals accelerates supply-chain restructuring.
High-pressure pasteurization is bifurcating the prepared baby food category into shelf-stable thermal-processed segments and refrigerated clean-label alternatives. Millennial parents in coastal metropolitan markets are adopting cold-pressed purees at three times the rate of conventional jarred formats. This technology is compressing distribution economics for regional brands while enabling margin capture through premium positioning in natural channel doors.
The FDA's pending guidance on heavy metal limits in finished baby foods is forcing rice cereal reformulation across the category. Manufacturers are accelerating supply-chain switches toward multi-grain blends and alternative carbohydrate sources. California-based organic brands with established quinoa and oat sourcing relationships are responding fastest, while legacy rice-dependent portfolios face 18-24 month reformulation cycles.
Subscription replenishment platforms are displacing stock-up trips to mass retail for routine nutrition purchases. Direct-to-consumer channels with predictive algorithms are capturing household pantry inventory management, particularly among dual-income professional parents. This shift is most visible in the Northeast corridor and Pacific Northwest metropolitan corridors where delivery density supports unit-economic viability.
North America Baby Food Market Segmentation
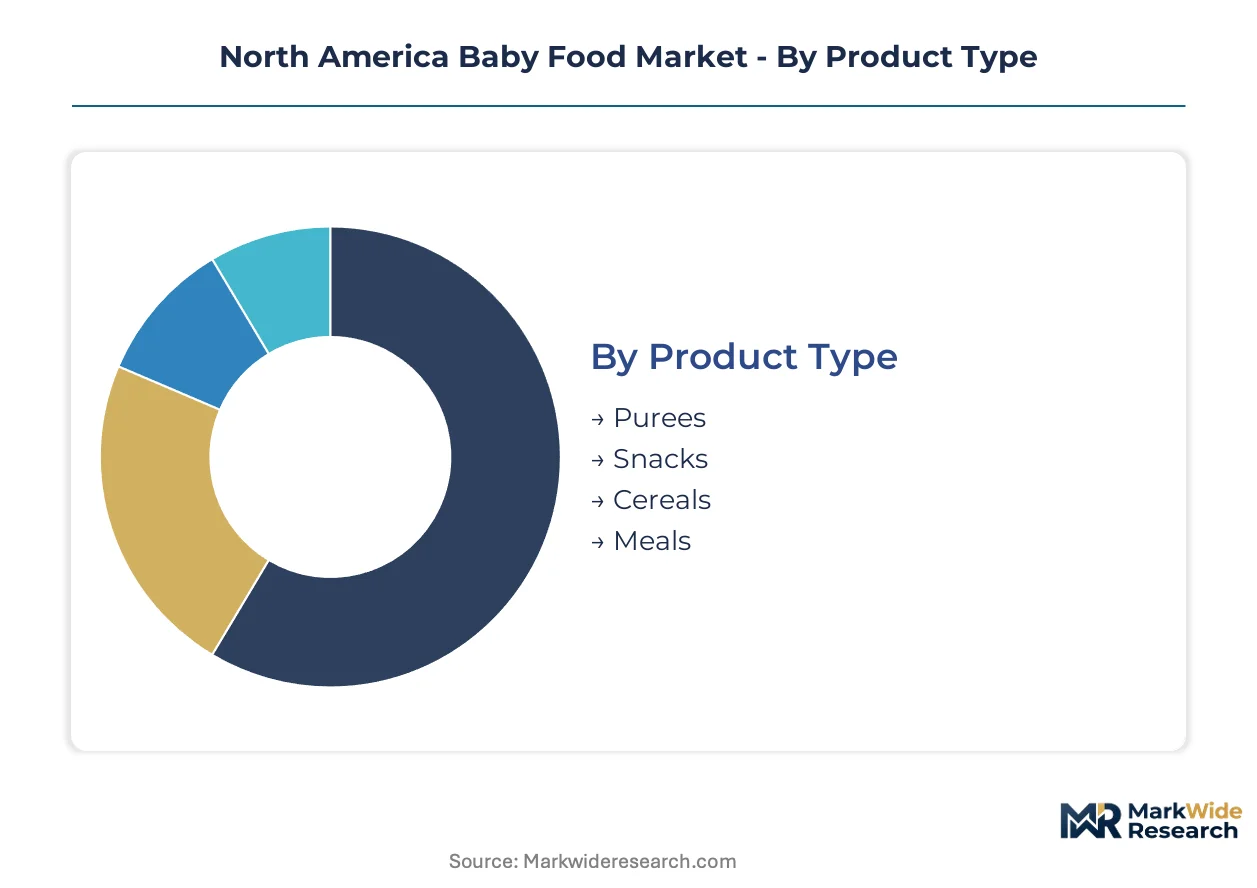
Segmentation reveals where margin pools concentrate versus where volume flows in North American infant nutrition. Product format and certification tier create the primary profit stratification, while channel and packaging choices determine accessibility and brand positioning.
Product Type:
Purees command the highest margin per ounce due to ingredient flexibility and premium positioning, while snacks drive repeat purchase frequency through convenience appeal.
- Purees:Thermally processed or cold-pressed fruit and vegetable blends, often single-ingredient for early weaning then multi-component for toddler palates. California parents purchase organic puree subscriptions at rates triple the national average, lured by clean-label transparency and refrigerated delivery logistics.
- Snacks:Puffed grain bites, teething wafers, and fruit-based finger foods engineered for self-feeding milestones. Northeast metropolitan demand clusters around portable formats for daycare and travel occasions, with pouched yogurt melts gaining shelf space in urban natural channels.
- Cereals:Iron-fortified rice and multi-grain powders reconstituted with breast milk or formula.
- Meals:Texture-graded protein-vegetable combinations mimicking family dinner compositions.
The dominant share belongs to purees, while snacks are closing the gap fastest.
Distribution Channel:
Channel selection determines margin capture versus household penetration, with digital platforms extracting lifetime value through subscription lock-in.
- Supermarkets:Kroger and Walmart banners anchor mainstream volume through promotional cycling and private-label placement. Slotting fee structures favor multinationals with trade spend depth, compressing mid-tier brand presence to end-cap and seasonal displays.
- Online Retail:Direct-to-consumer portals with predictive replenishment algorithms bypass retail markup while capturing pantry inventory data. Pacific Northwest urban corridors show highest subscription density, where dual-income households prioritize automated delivery over stock-up trips.
- Pharmacies:CVS and Walgreens stock specialized metabolic formulas and physician-recommended brands.
- Convenience Stores:Emergency purchase occasions for travel-size pouches and single-serve snacks.
Supermarkets still move the most units, though online retail is expanding most quickly.
Packaging Type:
Format economics separate premium positioning from mass-market accessibility, with material choice signaling quality tier to millennial purchasers.
- Pouches:Aseptic spouted flexible packaging enables portion control and mess-free feeding without refrigeration until opened. Coastal metropolitan parents adopt pouches at twice the rate of interior states, drawn by portability and reduced utensil dependency.
- Jars:Glass containers retain margin concentration in organic tiers through perceived purity and recycling appeal. Premium natural channel placement in California and New York sustains jar relevance despite pouch growth.
- Tubs:Plastic containers for cereal powders and thicker puree textures.
- Cans:Metal packaging for liquid concentrates and ready-to-feed formulas.
Pouches hold the volume lead, while jars maintain the steepest margin trajectory.
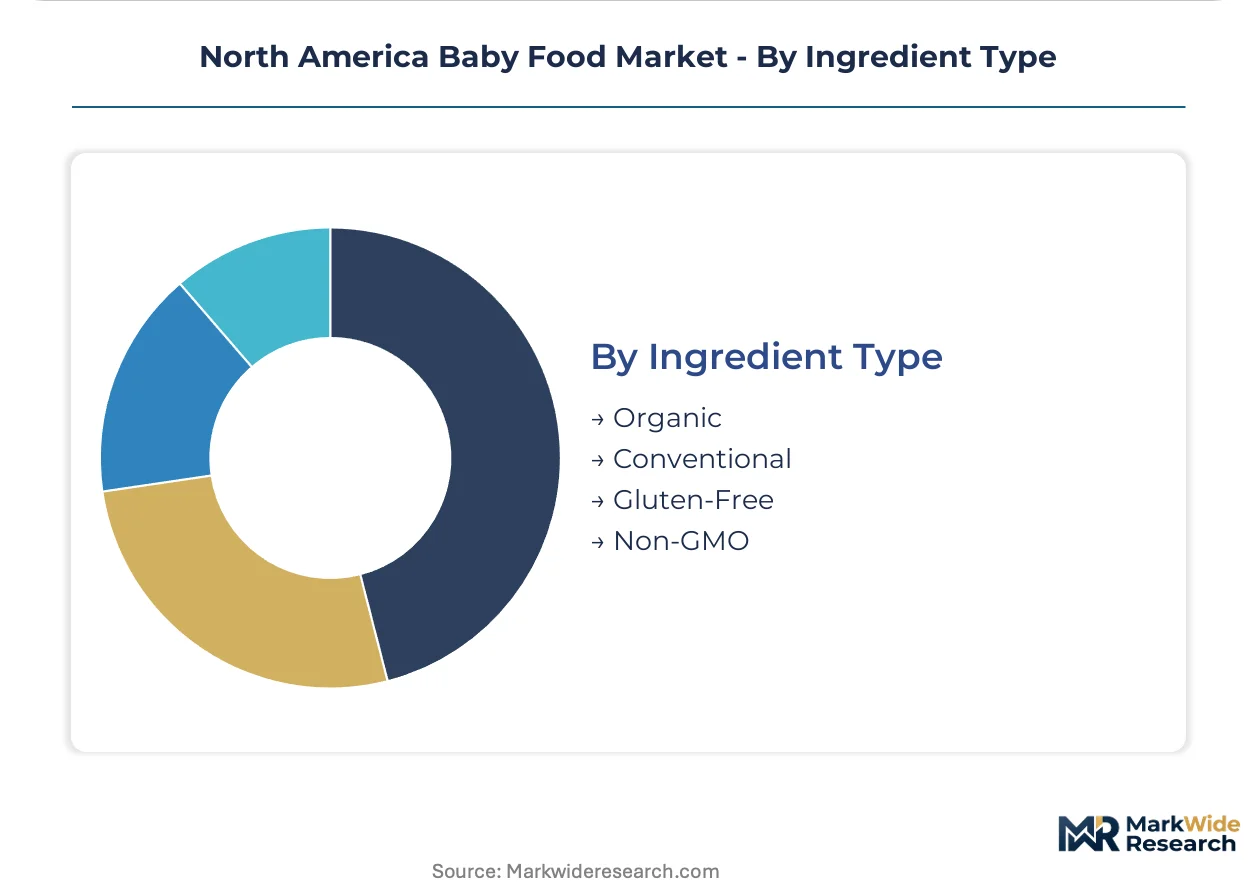
Ingredient Type:
Certification tier creates the deepest pricing stratification in the category, with organic claims requiring full supply-chain verification.
- Organic:USDA-certified ingredients from accredited operations with pasture-based dairy and prohibited synthetic inputs. FDA pending guidance on heavy metals is accelerating multi-grain reformulation among organic brands with established quinoa and oat supplier relationships.
- Conventional:Standard agricultural inputs without third-party certification, competing primarily on price per ounce.
- Gluten-Free:Formulations excluding wheat, barley, and rye for celiac-sensitive infants.
- Non-GMO:Verified absence of genetically modified organisms through supply-chain documentation.
Organic claims capture the dominant margin pool, while gluten-free is gaining share fastest among specialty diet households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA infant formula safety updates and USDA organic certification incentives are reshaping procurement patterns across North American markets. Canada and the United States coordinate cross-border standards through joint scientific reviews, while Mexico's expanding middle class drives demand for imported premium formulations.
United States
California's premium organic baby food penetration exceeds all other states, creating a test-bed market for clean-label innovations that diffuse eastward. FDA strengthened quality-control regulations under the Federal Food, Drug, and Cosmetic Act accelerate hospital channel consolidation around clinically validated pediatric nutrition portfolios. Northeast metropolitan corridors from Boston to Washington DC show highest subscription replenishment density, where dual-income households prioritize automated delivery over stock-up trips.
Canada
Health Canada and PMRA coordinate pesticide residue standards with US EPA benchmarks, reducing cross-border formulation friction for binational brands. The country's national organic regulator enforces equivalency agreements with USDA National Organic Program standards, enabling seamless certified ingredient sourcing. Ontario and Quebec concentrate manufacturing capacity near dairy processing clusters, with Toronto-Waterloo emerging as a cold-chain logistics hub for refrigerated organic puree distribution.
Mexico
Rising dual-income professional households in Mexico City and Monterrey drive demand for imported premium organic formulations. COFEPRIS, the country's national health regulator, aligns infant formula registration requirements with Codex Alimentarius standards, streamlining multinational market entry. The Bajío Region's expanding retail infrastructure attracts distribution investment from US-based subscription platforms seeking southward expansion.
Pacific Northwest
Portland and Seattle metropolitan parents adopt cold-pressed organic purees at rates triple the national average, lured by clean-label transparency and refrigerated delivery logistics. Washington State's organic dairy cooperative networks supply certified milk powder to regional formula manufacturers. Vancouver, British Columbia anchors cross-border organic ingredient trading, leveraging port access for Asian quinoa and oat sourcing relationships.
North America Baby Food Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access, creating a bifurcated structure where scale-driven multinationals anchor mainstream grocery while mid-cap organic brands capture premium natural channel placements. The vendor base separates into three strategic archetypes: vertically integrated dairy processors with captive organic supply chains, clinical nutrition specialists with hospital formulary relationships, and direct-to-consumer platforms with predictive replenishment algorithms. Dominant competitive moves include backward integration into dairy sourcing and subscription-based customer acquisition to bypass retail markup extraction.
Within the clinical nutrition tier, Abbott Laboratories and Danone exemplify hospital channel anchoring through specialized metabolic and allergy-focused portfolios. Among mainstream grocery competitors, Kraft Heinz Company occupies volume-tier placements across Walmart and Kroger banners through manufacturing scale advantages. Hain Celestial Group represents the premium organic archetype, with California-based sourcing relationships enabling rapid multi-grain reformulation ahead of pending FDA heavy metal guidance.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Reckitt Benckiser Group |
| Kraft Heinz Company |
| Beech-Nut Nutrition Corporation |
| Danone |
| Abbott Laboratories |
| Nestle |
| Perrigo Company |
| Hero Group |
| Others |
Value Chain & Pricing Dynamics
Long-term organic ingredient offtake contracts lock in both USDA-certified dairy access and price visibility for North American formula manufacturers facing volatile pasture-based milk powder markets. These arrangements tether margin predictability to captive supply relationships with Upper Midwest and Pacific Northwest organic cooperatives while insulating against spot-market spikes in whey protein concentrate.
Pricing Analysis
Certification level creates the primary spread across the North American baby food category. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies shelf placement. USDA Organic and FDA infant formula-grade certifications command 40-60% premiums over conventional tiers due to third-party audit costs and restricted input sourcing. Price erosion runs through mid-tier conventional segments as Walmart and Kroger extract promotional depth through buyer power asymmetry. Economy private-label purchasers show highest price sensitivity, while premium organic subscribers demonstrate inelastic demand for clean-label transparency.
Supply Chain Analysis
Strategic stockpiling of certified organic dairy inputs dominates inventory strategy as pasture availability fluctuations drive six-month price cycles. Raw material sourcing draws from Upper Midwest dairy cooperatives, Pacific Northwest organic grain handlers, and Canadian Prairie oat and quinoa suppliers. Rice-based ingredient dependencies create single-source vulnerability ahead of pending FDA heavy metal guidance. Distribution runs through temperature-controlled regional hubs serving natural channel doors and direct-to-consumer cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pending FDA heavy metal limits represent a regulatory inflection accelerating supply-chain restructuring and multi-grain reformulation investments across the category. This disruption compresses competitive timelines for brands dependent on legacy rice-cereal portfolios.
For Market Incumbents: Shield margin concentration in premium organic tiers by accelerating backward integration into certified dairy sourcing. Secure captive supply relationships with Pacific Northwest and Upper Midwest organic cooperatives before contract renewal cycles. Invest in high-pressure pasteurization capacity to capture refrigerated clean-label positioning as thermal-processed volumes plateau.
For New Entrants and Emerging Players: Lead with metabolic and allergy-focused formula segments where hospital formulary penetration remains underdeveloped relative to standard offerings. Target Pacific Northwest and Northeast metropolitan corridors where subscription replenishment density supports unit-economic viability. Deploy direct-to-consumer platforms with predictive algorithms to bypass retail markup extraction and capture lifetime value through automated pantry management.
For Investors and Strategic Acquirers: California-based organic brands with established quinoa and oat supplier relationships present acquisition targets positioned for rapid reformulation ahead of FDA guidance. Long-term viability hinges on supply-chain agility and multi-jurisdictional label compliance infrastructure. Watch for COFEPRIS registration acceleration signaling Mexico market entry momentum among US-based subscription platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Dairy | Captive supply from Upper Midwest cooperatives locks in USDA certification continuity and margin predictability. |
| High-Pressure Pasteurization Capacity Addition | Cold-processing infrastructure enables refrigerated clean-label positioning in coastal metropolitan natural channels. |
| Direct-to-Consumer Platform Launch | Predictive replenishment algorithms capture pantry inventory data and lifetime value in dual-income households. |
| Multi-Grain Reformulation Investment | Quinoa and oat sourcing relationships ahead of FDA heavy metal guidance protect shelf space access. |
| COFEPRIS Registration Pathway | Mexico regulatory alignment with Codex Alimentarius standards streamlines premium organic market entry. |
Study Parameters
Operator-level perspectives from brand managers at organic and conventional manufacturers, category buyers at Kroger and Walmart banners, supply planners at dairy cooperatives, and regulatory affairs leads at formula producers anchored the qualitative base. Secondary validation drew from FDA Federal Register filings, USDA National Organic Program accreditation records, Nielsen retail audit data, and Health Canada joint scientific review documentation. Bottom-up volume modeling triangulated against top-down category value assessments.
Sensitivity analysis tested forecast robustness across organic input cost volatility scenarios and regulatory timeline variations. Segmentation dimensions included product format, certification tier, packaging type, distribution channel, and regional demand concentration. CAGRs derived from trend extrapolation calibrated to historical volume trajectories and elasticity-adjusted price assumptions. Modeled inputs incorporated FDA guidance implementation timing and subscription platform penetration curves.
Forecasts assume regulatory continuity in FDA infant formula safety requirements and USDA National Organic Program standards; material policy shifts would require re-modeling. Revision becomes warranted when FDA heavy metal guidance thresholds or COFEPRIS registration timelines cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Pet Milk Replacers Market