
 Russia Pet Food Market | 2026-2036
Russia Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Pet Food Market Outlook
The Eurasian Economic Union's technical regulation TR TS 022/2011 on food product labeling is recalibrating how Russian manufacturers formulate and package pet food. Mars Petcare leverages its global R&D infrastructure to sustain premium positioning across Moscow retail channels. Nestlé Purina PetCare anchors mid-tier volume through broad supermarket distribution. PetKorm competes on cost-efficient dry food production tailored to regional Russian preferences.
Pet food encompasses nutritionally complete and complementary feeds formulated for domesticated animals, typically containing proteins from poultry, fish, or plant meals combined with vitamins, minerals, and preservatives to meet species-specific dietary requirements. The primary commercial purpose is to deliver standardized nutrition that supports animal health while enabling convenient feeding routines for owners. Dry food dominates volume throughput due to longer shelf stability and lower logistics costs across Russia's vast territory. Premium wet food captures disproportionate margin pools in urban centers where owners prioritize palatability and hydration benefits. Treats and snacks represent the fastest-expanding segment as humanization trends reshape spending patterns.
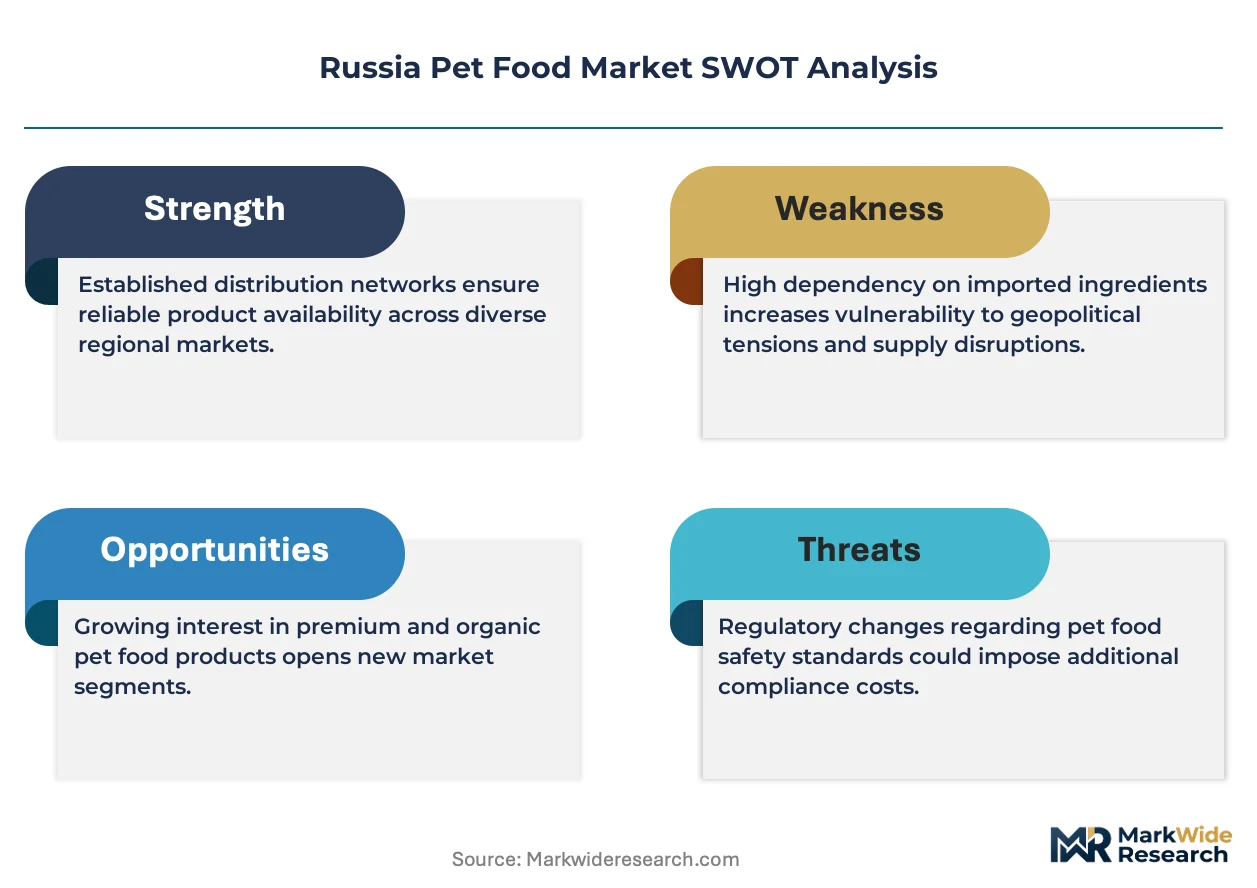
Russia's Federal Service for Veterinary and Phytosanitary Surveillance (Rosselkhoznadzor) enforces feed safety inspections that determine which imported ingredients enter domestic production. The Eurasian Economic Commission harmonizes standards across member states, creating cross-border compliance obligations for manufacturers operating in Belarus and Kazakhstan. GOST R certification requirements for pet food packaging and nutritional claims shape product development cycles. Stakeholders must monitor how Rosselkhoznadzor adjusts import quotas for meat meals and whether domestic producers expand captive rendering capacity to reduce exposure to volatile raw material flows.
Market Dynamics
Rosselkhoznadzor's tightening import quotas for meat meals are forcing domestic manufacturers to rebuild supply chains around captive rendering capacity and alternative protein sourcing. This regulatory pressure sits at the center of competitive positioning across Russia's pet food sector.
Growth Catalysts
- TR TS 022/2011 labeling harmonization:The Eurasian Economic Union's technical regulation is creating cross-border production efficiencies for manufacturers operating in Belarus and Kazakhstan, reducing formulation complexity across the customs union.
- Humanization-driven treat segmentation:Owners in Moscow and St. Petersburg are redirecting spending toward functional snacks positioned as health supplements, expanding addressable margin pools beyond core nutrition.
- Central Federal District urban density:Concentrated cat ownership in high-rise residential clusters is accelerating premium dry food throughput and enabling specialized retail formats.
Market Restraints
- Meat meal import dependency:Rosselkhoznadzor's quota adjustments for poultry and fish meals expose formulations to raw material flow interruptions from Argentina and Brazil.
- GOST R certification timelines:Nutritional claim verification and packaging compliance testing extend product development cycles by four to six months versus European benchmarks.
- Domestic rendering capacity gaps:Limited investment in captive protein processing forces reliance on spot-market purchases, compressing margin stability during rouble volatility.
Strategic Opportunities
- Volga Federal District underpenetration:Secondary cities including Nizhny Novgorod and Kazan present whitespace for mid-tier dry food distribution through veterinary clinic networks.
- Wet food hydration positioning:Veterinary endorsement of moisture-rich diets for renal health is creating clinical channel pull for premium canned formulations.
- E-commerce subscription mechanics:Direct-to-consumer replenishment models are capturing repeat purchase loyalty among time-constrained urban professionals in St. Petersburg.
Industry Challenges
- Veterinary nutritionist scarcity:Formulation teams lack species-specific expertise in feline metabolic disease management, slowing therapeutic diet development.
- Cold chain capex requirements:Wet food shelf stability demands refrigerated logistics infrastructure that regional distributors cannot finance without manufacturer co-investment.
- Ingredient provenance verification:Blockchain traceability implementation faces legacy ERP integration friction at mid-scale production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Pet Food Market |
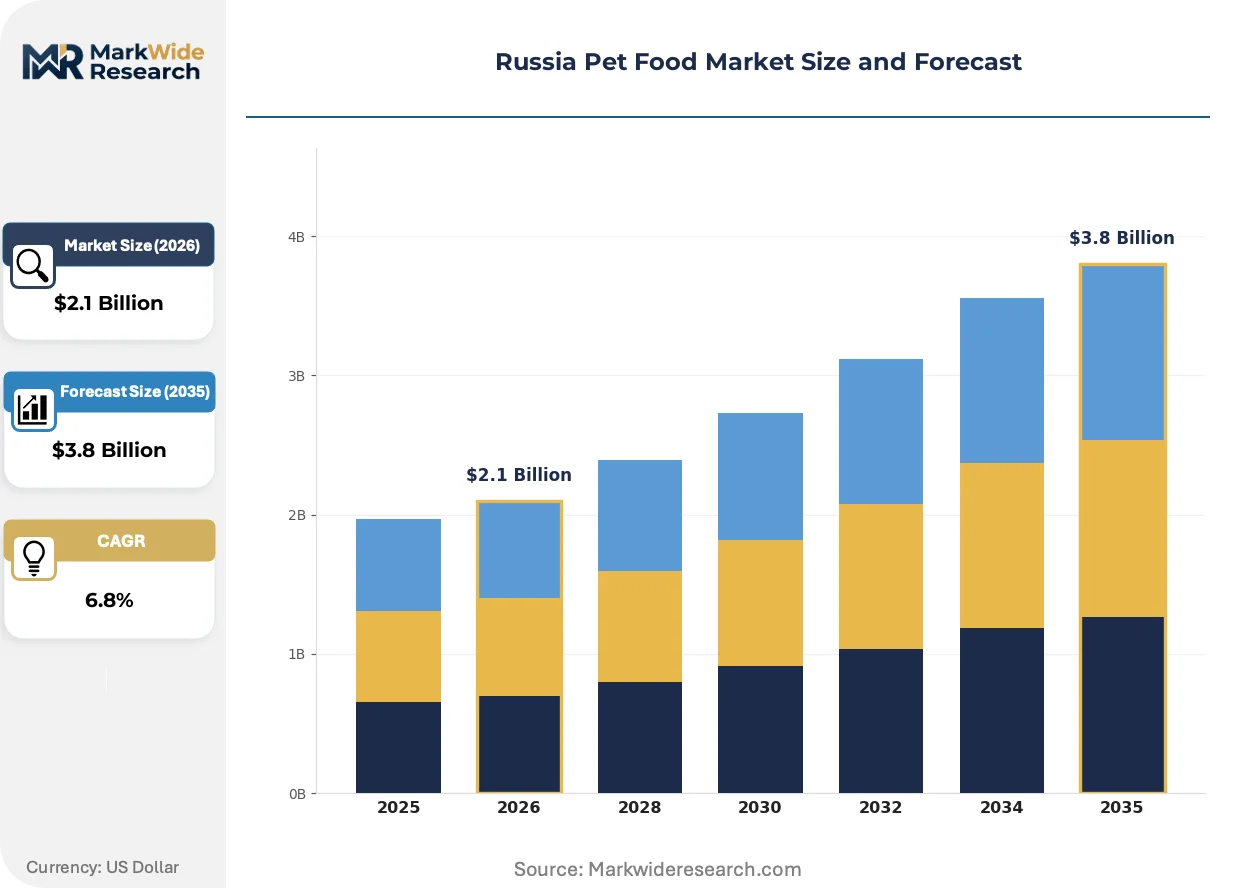
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Supermarkets, Pet Shops, Online Stores, Veterinary Clinics Price Tier: Premium, Mid-range, Budget, Organic |
| Companies Covered | PetKorm, R-Trade, Raduga LLC, Aller Petfood, AlphaPet, Gatchina Feed Mill, Limkorm, Mars Petcare, Nestlé Purina PetCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Pet Food Market Strategic Shifts
Protein sourcing and preservation technologies are converging with distribution infrastructure constraints to reshape product architecture across Russia's vast territory. Manufacturers are adapting formulation and packaging to accommodate temperature extremes and extended shelf requirements.
Extrusion technology paired with high-pressure processing is converging with modified atmosphere packaging to extend wet food stability without refrigeration. Premium manufacturers in Moscow are adopting these combined systems to reduce cold chain dependency. The hybrid approach is converging with regional distributor capabilities, enabling premium positioning beyond the Central Federal District.
Rosselkhoznadzor's 2024 amendments to feed safety inspection protocols are mandating enhanced mycotoxin screening for grain-based ingredients. Domestic mills must now maintain third-party certified testing laboratories or face import permit suspensions. Mid-tier dry food producers in the Northwestern Federal District are consolidating supplier bases to reduce compliance audit burden.
Subscription-based replenishment is displacing supermarket bulk purchasing among dual-income households in St. Petersburg. Automated delivery scheduling paired with veterinary teleconsultation bundling is capturing loyalty from cat owners managing chronic conditions. This behavioral shift is most visible in the premium therapeutic nutrition segment, where convenience and clinical credibility intersect.
Russia Pet Food Market Segmentation
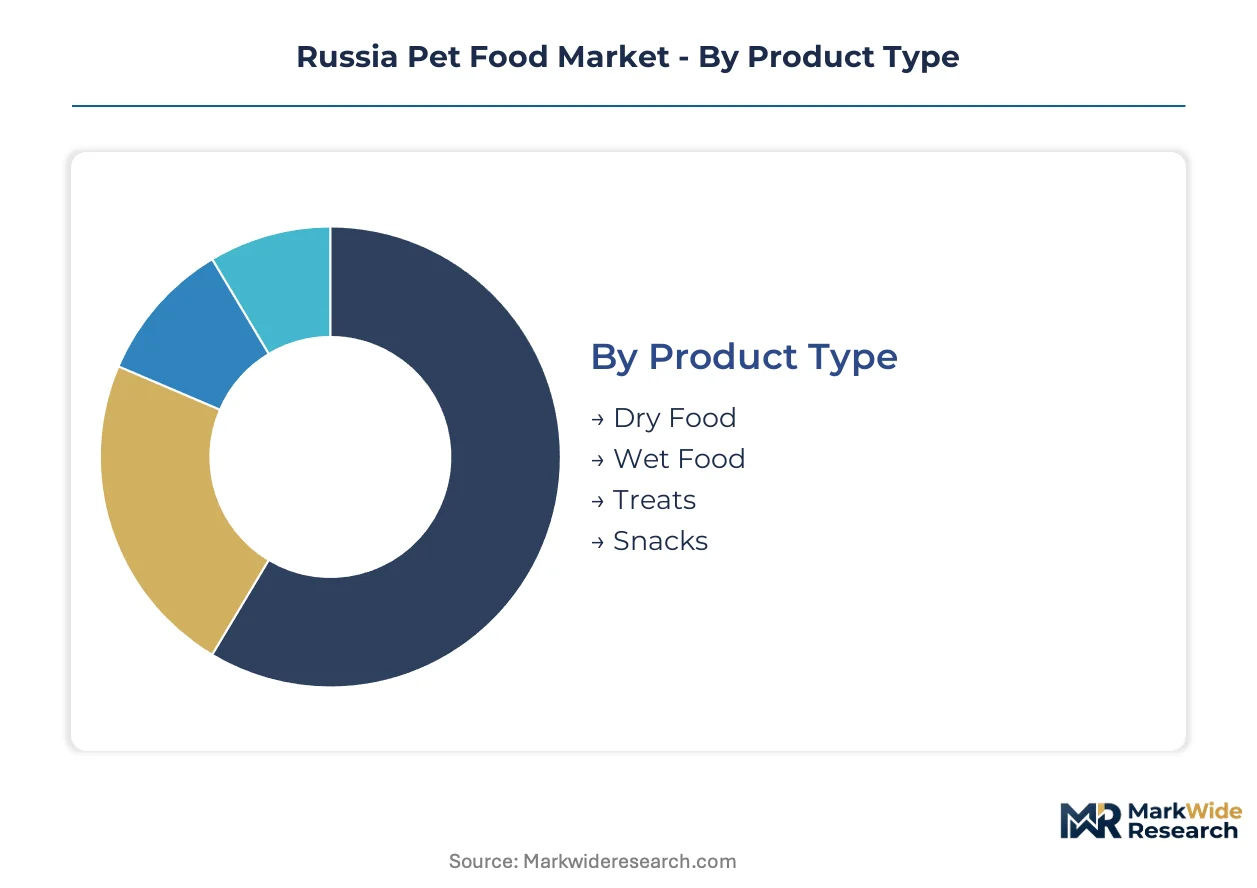
Segmentation reveals how Russian pet food demand fragments across feeding formats, species ownership patterns, and channel access. Manufacturers must align formulation investments with the upgrade cycles driving replacement purchases in each category.
Product Type:
Upgrade cycles vary sharply by format, with shelf stability and convenience dictating repurchase frequency across Russia's climatic extremes.
- Dry Food:Extruded kibble formulations achieve 18-24 month shelf stability through moisture reduction below 10%. Central Federal District cat owners in high-rise clusters drive premium dry food throughput, prioritizing storage convenience in compact urban dwellings.
- Wet Food:Canned or pouch formats with 75-85% moisture content deliver palatability and hydration benefits. Moscow veterinary clinics are pulling moisture-rich formulations for renal health management, expanding clinical channel placement.
- Treats:Functional snacks positioned as health supplements are redirecting spending from core nutrition in St. Petersburg dual-income households.
- Snacks:Chewing and dental formats occupy impulse purchase occasions at supermarket checkout zones.
Dry Food sits at the top of the volume ranking, with Treats climbing the fastest.
Animal Type:
Species-specific metabolic requirements dictate formulation complexity and margin capture across veterinary and retail channels.
- Cats:Obligate carnivores requiring taurine supplementation and precise protein-to-fat ratios. Moscow and St. Petersburg ownership clusters are accelerating premium therapeutic nutrition development for chronic renal and urinary conditions.
- Dogs:Omnivorous tolerance enables grain-inclusive formulations at lower price points. Regional distributors in the Volga Federal District are expanding mid-tier dry food placement through veterinary clinic networks.
- Birds:Seed and pellet blends for psittacines and passerines occupy niche specialty retail.
- Small Mammals:Hay-based and extruded diets for rabbits, guinea pigs, and rodents serve limited but stable demand.
Cats command the steepest expansion trajectory, with Small Mammals holding the most concentrated specialist channel.
Distribution Channel:
Channel selection determines margin structure and customer relationship depth, with digital formats disrupting traditional bulk purchasing patterns.
- Supermarkets:Mass-market volume through broad SKU availability and promotional pricing. Nestlé Purina anchors mid-tier positioning across federal retail chains.
- Pet Shops:Specialist advice and premium assortment drive higher basket values in urban centers.
- Online Stores:Subscription replenishment models capture repeat loyalty among time-constrained St. Petersburg professionals, bundling automated delivery with veterinary teleconsultation.
- Veterinary Clinics:Clinical credibility and therapeutic endorsement support premium wet food placement for renal health positioning.
Supermarkets retain volume leadership, with Online Stores gaining share fastest.
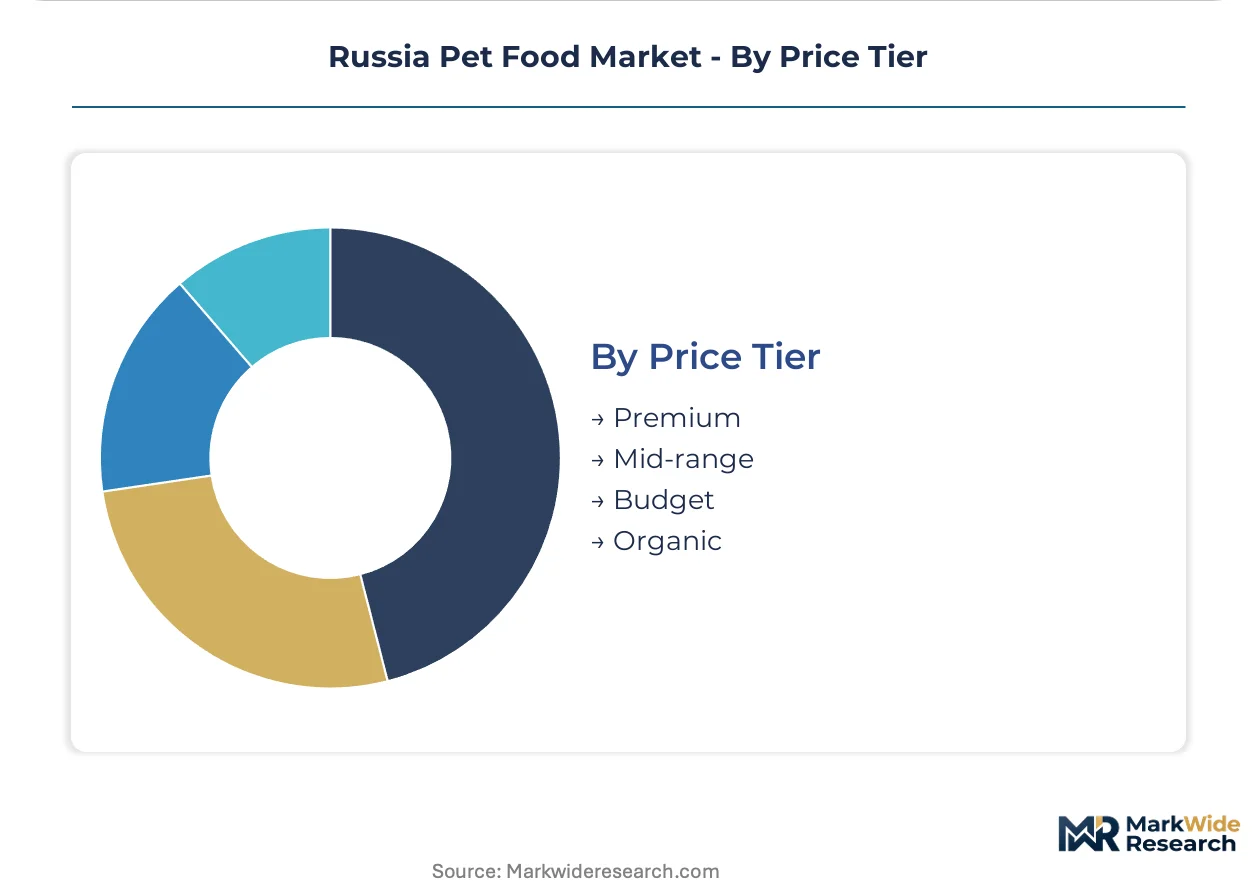
Price Tier:
Cost stratification aligns with ingredient provenance, certification burden, and packaging sophistication across regulatory compliance tiers.
- Premium:Human-grade protein sourcing and GOST R nutritional claim verification. Mars Petcare sustains positioning through global R&D infrastructure and Moscow retail channel dominance.
- Mid-range:Balanced cost-quality positioning for mass-market volume. PetKorm competes on cost-efficient dry production tailored to regional Russian preferences.
- Budget:Commodity protein meals and simplified formulations serve price-sensitive rural markets.
- Organic:Certified ingredient chains and limited synthetic additive profiles attract niche urban demand.
Premium holds margin leadership, with Organic expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Russian pet food industry traces its modern scaling to Soviet-era state feed complexes that transitioned into commercial production during the 1990s privatization wave. These historical foundations established protein rendering infrastructure concentrated in the Central Federal District. Contemporary demand patterns now radiate from this core toward secondary urban clusters.
Central Federal District
Moscow's high-rise residential density concentrates cat ownership and drives premium dry food throughput. Rosselkhoznadzor's feed safety inspections enforce GOST R certification requirements that shape local formulation standards. The Moscow-St. Petersburg corridor anchors specialized retail formats and veterinary clinic networks for therapeutic nutrition distribution.
Volga Federal District
Nizhny Novgorod and Kazan present underpenetrated whitespace for mid-tier dry food expansion through veterinary channels. The Eurasian Economic Union's TR TS 022/2011 labeling harmonization reduces cross-border compliance costs for producers sourcing from Kazakhstan. Regional distributors here lack refrigerated logistics capacity, favoring shelf-stable extruded formulations.
Northwestern Federal District
St. Petersburg's dual-income households accelerate subscription-based replenishment models bundling automated delivery with veterinary teleconsultation. The Eurasian Economic Commission's mycotoxin screening mandates force domestic mills to maintain third-party certified testing laboratories. Mid-tier producers here consolidate supplier bases to reduce compliance audit burdens.
Siberian Federal District
Novosibirsk and Krasnoyarsk face extended cold chain requirements that disadvantage wet food distribution. Regional preferences favor high-calorie dry formulations suited to harsh winter conditions. Local rendering capacity remains underdeveloped, forcing reliance on rail-transported protein meals from Central Federal District suppliers.
Southern Federal District
Rostov-on-Don and Krasnodar benefit from proximity to Black Sea grain corridors and poultry production clusters. Rosselkhoznadzor's import quota adjustments for Argentine and Brazilian meat meals directly impact regional formulation costs. Captive rendering investments here aim to reduce exposure to volatile raw material flows from overseas suppliers.
Russia Pet Food Market Competitive Environment
Capital-heavy producers compete with asset-light brand marketers across Russia's pet food sector. The market structure consolidates around three tiers: multinational corporations with global R&D infrastructure, mid-scale domestic manufacturers with regional distribution networks, and commodity-focused mills serving price-sensitive rural markets. Two strategic archetypes dominate competitive dynamics: premium-positioned players leveraging veterinary endorsement and cost-optimized producers capturing volume through supermarket channels. Capacity expansion and portfolio diversification represent the primary competitive moves, with cold chain co-investment emerging as a partnership mechanism for wet food distribution.
Among multinational operators, Mars Petcare and Nestlé Purina PetCare exemplify divergent positioning strategies—Mars sustaining premium-tier credentials through Moscow retail dominance while Purina anchors mid-market volume via federal supermarket chains. Domestic specialists including PetKorm occupy the cost-efficient production archetype, tailoring dry food formulations to regional Russian palatability preferences. These three entities collectively illustrate how global R&D scale, brand equity depth, and manufacturing flexibility compete for distinct customer segments across the territory.
| Leading Market Players |
|---|
| PetKorm |
| R-Trade |
| Raduga LLC |
| Aller Petfood |
| AlphaPet |
| Gatchina Feed Mill |
| Limkorm |
| Mars Petcare |
| Nestlé Purina PetCare |
| Others |
Value Chain & Pricing Dynamics
Rosselkhoznadzor's mycotoxin screening mandates for grain-based ingredients gate both qualified supply and premium-tier pricing access. Domestic mills without third-party certified testing laboratories face import permit suspensions, forcing consolidation of supplier bases and compressing margin stability for mid-tier producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Russia's pet food market. Price differentiation rests on GOST R certification grade and human-grade protein sourcing credentials. Cost compression in the economy tier is intensifying because Rosselkhoznadzor's import quota adjustments for Argentine and Brazilian meat meals expose formulations to volatile raw material flows. Rural distributors exhibit highest price sensitivity, while Moscow cat owners in high-rise residential clusters demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Reverse-logistics flows remain underdeveloped across Russia's pet food sector, with limited refurbishment or remanufacturing of expired inventory. Geographic supply concentration draws from Argentina, Brazil, and domestic Central Federal District rendering facilities. Raw material dependencies center on poultry meal, fish meal, and grain-based carbohydrates. Single-source vulnerability to Rosselkhoznadzor's quota adjustments creates structural risk exposure. Distribution runs through federal supermarket chains, veterinary clinic networks, and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's pet food market functions as a stable compounder, with humanization trends driving steady upgrade cycles from economy to premium tiers across the analysis window.
For Market Incumbents: To counter Rosselkhoznadzor's tightening import quotas for meat meals, Mars Petcare and Nestlé Purina PetCare should deepen backward integration into captive rendering capacity within the Central Federal District. Certification investment in GOST R nutritional claim verification preserves Moscow retail channel dominance against emerging domestic challengers. For New Entrants and Emerging Players: The mid-tier price-point gap between Mars Petcare's premium positioning and PetKorm's economy focus presents whitespace for regional specialists. Nizhny Novgorod and Kazan in the Volga Federal District offer underpenetrated veterinary clinic networks for dry food distribution. A go-to-market angle bundling cost-efficient production with localized palatability formulations captures share from federal supermarket chains. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale domestic manufacturers with regional distribution networks but limited captive protein processing. Long-term viability over a five-to-ten year window hinges on backward integration completion and Eurasian Economic Union cross-border production scale. The signal to watch is Rosselkhoznadzor's adjustment frequency for meat meal import quotas as an inflection indicator for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Rendering Capacity Expansion | Reduces exposure to Rosselkhoznadzor quota volatility for poultry and fish meal sourcing. |
| GOST R Certification Investment | Enables premium nutritional claims in Moscow's high-rise cat owner segment. |
| Veterinary Clinic Network Penetration | Captures therapeutic wet food placement for renal health positioning in St. Petersburg. |
| Subscription Replenishment Platform Launch | Locks repeat purchase loyalty among time-constrained dual-income households. |
| Eurasian Economic Union Cross-Border Scale | Leverages TR TS 022/2011 harmonization for production efficiency across Belarus and Kazakhstan. |
Study Parameters
Bottom-up pet owner spending modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with veterinary nutritionists, Rosselkhoznadzor inspection officials, supermarket category buyers, and regional distribution partners combined with secondary validation from customs trade records, GOST R certification databases, and Eurasian Economic Commission regulatory filings. Triangulation across these sources ensures coverage of both demand-side upgrade cycles and supply-side compliance constraints.
Historical trendline analysis of dry food, wet food, and treat segment trajectories informed the projection framework. Modeled dimensions span product format, species type, distribution channel, price tier, and federal district geography. CAGRs were derived from regression analysis of replacement purchase frequencies and premiumization elasticities. Forecast inputs incorporated Rosselkhoznadzor regulatory amendment timelines and Eurasian Economic Union technical regulation harmonization schedules.
Caveats apply where Rosselkhoznadzor quota adjustments, rouble volatility spikes, or veterinary teleconsultation adoption rates could materially shift the outlook. Forecasts reflect assumptions about import permit continuity and domestic rendering capacity expansion pacing. Practitioners should monitor Rosselkhoznadzor inspection protocol amendments and captive protein processing investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Wet Cat Food Market