
 Baby Food Testing Market | 2026-2036
Baby Food Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food Testing Market Insights
Subscription-based laboratory information management systems is shifting how testing contracts are priced and renewed in the baby food testing sector. Eurofins Scientific leverages its pan-European laboratory network to secure multi-year retainer agreements with organic baby food processors. SGS Group anchors its competitive stance through dedicated infant nutrition testing centers in Switzerland and the Netherlands. Bureau Veritas differentiates by bundling shelf life validation with ongoing microbial monitoring programs for pouch-format products.
Baby food testing encompasses analytical protocols that verify microbiological safety, nutritional label accuracy, chemical contaminant levels, and packaging integrity in products intended for infants and toddlers up to 36 months. High-performance liquid chromatography with tandem mass spectrometry serves as the reference method for quantifying pesticide residues below 0.01 mg/kg in fruit and vegetable purees. Microbial analysis commands the largest share of testing volume due to mandatory salmonella and cronobacter sakazakii screening requirements across major markets. Chemical residue testing represents the fastest-expanding segment as regulators add emerging contaminants like per- and polyfluoroalkyl substances to monitoring scopes.
The FDA enforces infant formula quality standards through its Center for Food Safety and Applied Nutrition, while the EFSA sets European-wide reference points for heavy metals in processed cereal-based baby foods. ISO 17025 accreditation has become a non-negotiable threshold for laboratories seeking contracts with multinational baby food manufacturers. Stakeholders must monitor evolving regulatory contaminant lists and invest in method validation capabilities before compliance deadlines tighten testing windows.
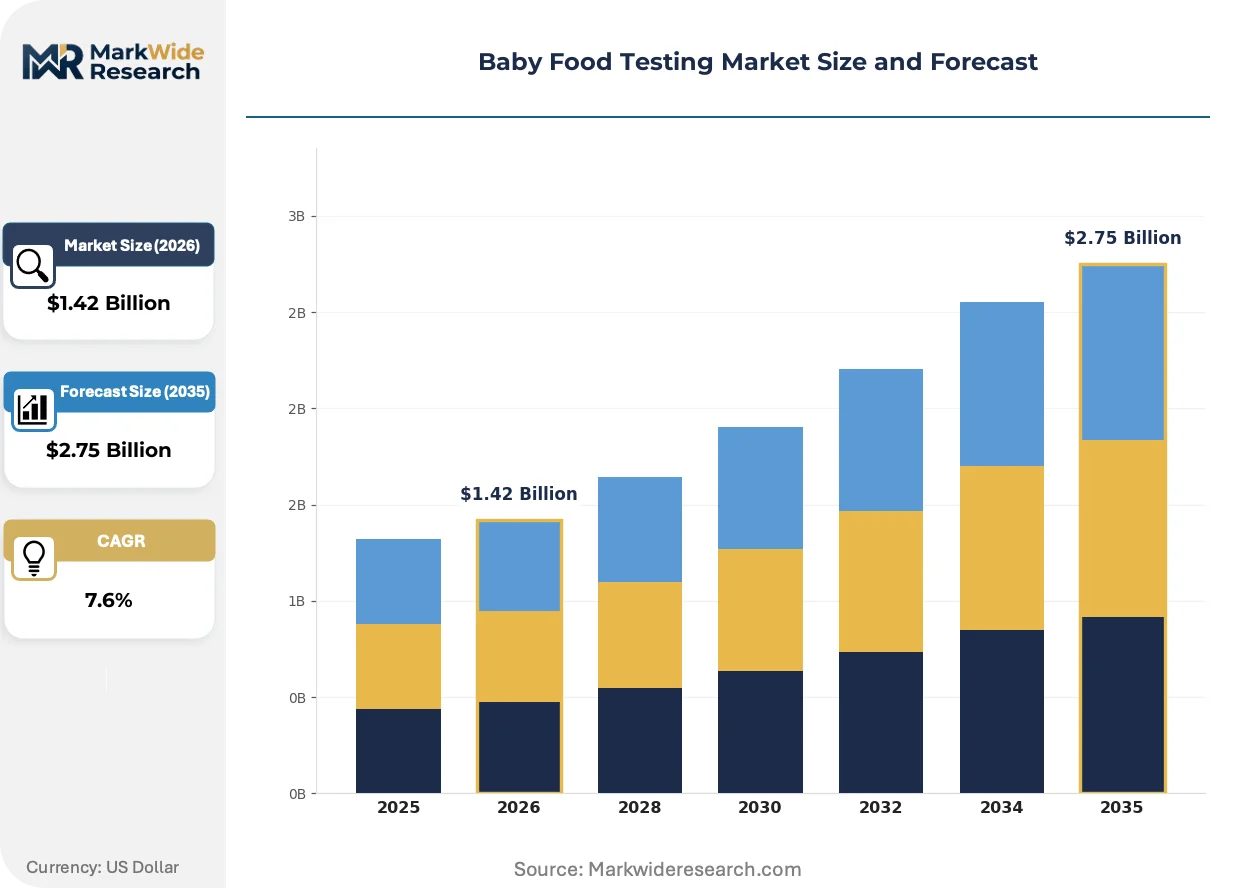
Market Dynamics
Retailer compliance mandates are compressing testing windows and forcing laboratories to validate methods before regulatory deadlines. Third-party certification has shifted from competitive differentiator to minimum viable threshold for contract eligibility.
Growth Catalysts
- EU Maximum Residue Limit Tightening:The European Commission's reduced pesticide thresholds in processed infant foods are compelling manufacturers to expand chromatography testing budgets and secure batch-level documentation.
- Private-Label Expansion:German supermarket chains now require certificates of analysis for every production batch, creating sustained demand for accredited laboratory capacity.
- Cronobacter sakazakii Screening Mandates:Mandatory pathogen detection protocols across major markets are driving volume in microbial analysis services.
Market Restraints
- Mass Spectrometry Equipment Costs:High-performance liquid chromatography-tandem mass spectrometry systems require substantial capital outlay, limiting laboratory expansion.
- Accreditation Bottlenecks:ISO 17025 certification timelines stretch 12-18 months, constraining new market entrants from securing multinational manufacturer contracts.
- Specialized Chemist Shortages:Analytical method development for emerging contaminants like per- and polyfluoroalkyl substances demands expertise that outpaces training pipeline output.
Strategic Opportunities
- Pouch-Format Shelf Life Validation:Flexible packaging integrity testing represents an underserved service line with recurring revenue potential.
- Subscription LIS Pricing Models:Laboratory information management systems are enabling multi-year retainer structures that improve revenue predictability.
- Emerging Contaminant Method Development:Regulators are expanding monitoring scopes beyond legacy pesticide panels, creating first-mover advantages for validated protocols.
Industry Challenges
- Method Validation Compression:Tightening compliance deadlines are reducing the window for analytical protocol verification before mandatory implementation.
- Legacy System Integration:Paper-based certificate workflows at smaller manufacturers create friction with automated laboratory data management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food Testing Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Cereals, Meats Testing Method: Microbial Analysis, Nutritional Analysis, Chemical Residue Testing, Shelf Life Testing End User: Manufacturers, Retailers, Laboratories, Consumers Packaging Type: Jars, Pouches, Tubs, Sachets |
| Companies Covered | Eurofins Scientific, SGS Group, Intertek Group, Bureau Veritas, TÜV SÜD, Mérieux NutriSciences, Romer Labs, ALS Limited, Silliker Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food Testing Market Trends and Innovations
Digital infrastructure and regulatory expansion are converging to reshape how testing services are procured, delivered, and consumed across the infant nutrition value chain.
High-performance liquid chromatography-tandem mass spectrometry is unifying pesticide residue quantification across fruit puree and vegetable concentrate matrices. Organic baby food processors in Germany and the Netherlands are adopting this platform as their reference method within 18-month validation cycles. The technology is unifying previously fragmented analytical workflows into single-instrument protocols, compressing turnaround times and reducing per-sample costs.
EFSA reference points for heavy metals in processed cereal-based foods are tightening laboratory performance requirements. The policy is forcing manufacturers to source testing partners with demonstrated proficiency in low-level quantification. Infant cereal producers are responding by consolidating vendor relationships toward pan-European laboratory networks with harmonized quality systems.
Retailer-driven batch certification is displacing periodic auditing as the dominant quality assurance model. German private-label brands now require certificates of analysis before shelf placement, shifting testing from annual compliance verification to production-integrated workflows. This pattern is most visible in Central European markets where supermarket concentration grants retailers leverage over supplier quality systems.
Baby Food Testing Market Segmentation
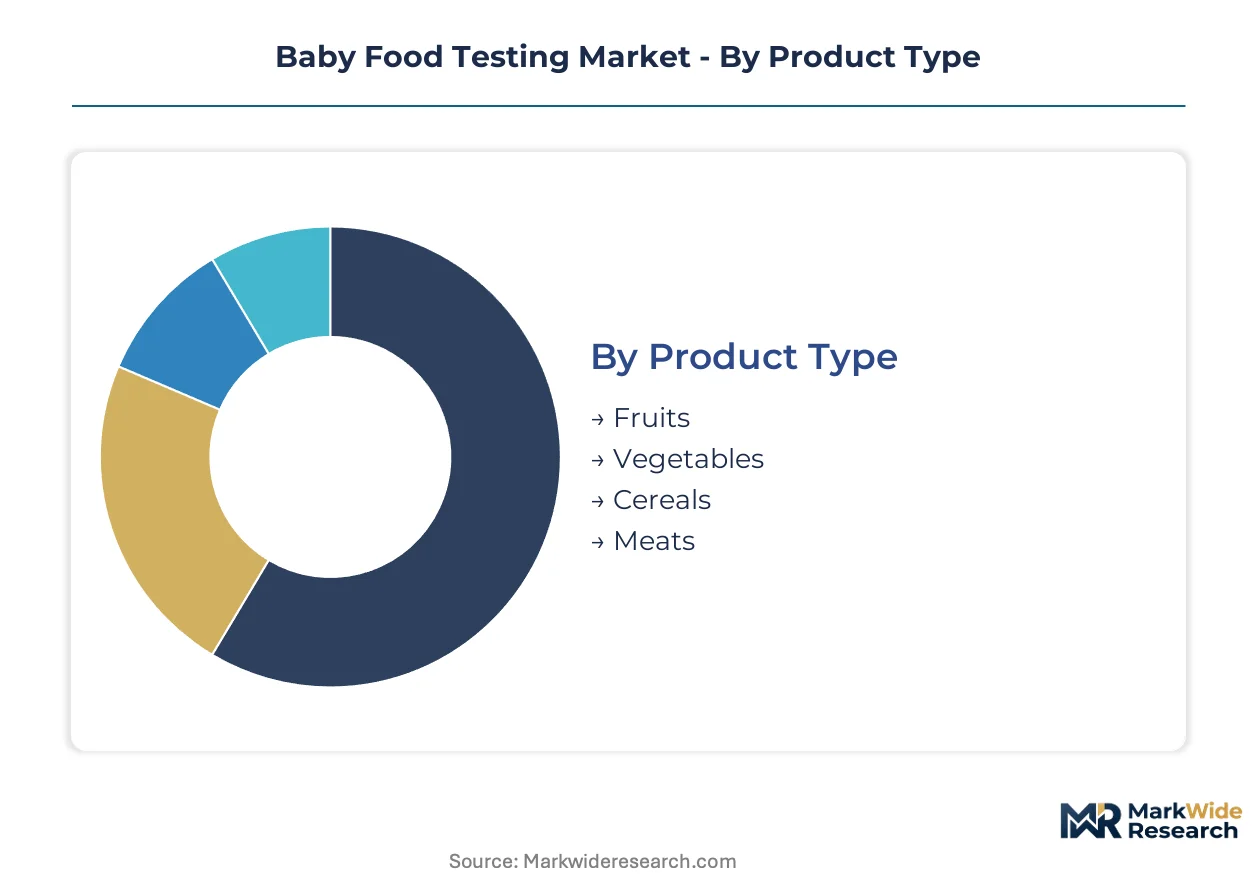
Segmentation in baby food testing reveals how certification burdens distribute unevenly across product matrices and stakeholder types. Laboratories configure service portfolios around which segments trigger mandatory pathogen screening versus voluntary label verification.
Product Type:
Fruit purees carry the heaviest pesticide residue certification load under EFSA protocols, while cereal-based foods face distinct heavy metal thresholds that demand specialized analytical partnerships.
- Fruits:High-sugar purees and concentrates require HPLC-MS/MS screening for organophosphate residues below 0.01 mg/kg. German private-label brands now mandate batch-level certificates before shelf placement, compressing laboratory turnaround windows.
- Vegetables:Root vegetable purees accumulate heavy metals from soil uptake, forcing manufacturers to source testing partners with demonstrated low-level quantification proficiency. EFSA reference points for cadmium and lead are tightening laboratory performance requirements across Central European processing facilities.
- Cereals:Iron-fortified infant cereals face dual scrutiny for nutritional label accuracy and mycotoxin contamination. The segment demands validated protocols for aflatoxin B1 quantification.
- Meats:Hydrolyzed protein formulas require veterinary drug residue screening alongside standard microbial panels. Testing volumes concentrate in markets with domestic poultry processing capacity.
Vegetables sits at the top of the volume ranking, with Fruits climbing the fastest.
Testing Method:
Cost tiers separate reference-grade chromatography from rapid screening methods, with capital equipment requirements determining laboratory entry barriers.
- Microbial Analysis:Salmonella and Cronobacter sakazakii screening commands the largest share of testing volume due to mandatory detection protocols across FDA and EFSA jurisdictions. Per-sample pricing remains compressed by high-throughput automation.
- Chemical Residue Testing:Per- and polyfluoroalkyl substances are expanding monitoring scopes beyond legacy pesticide panels. Method development for emerging contaminants is gaining share fastest as regulators add compounds to compliance lists.
- Nutritional Analysis:Label claim verification for macronutrients and micronutrients serves manufacturers defending against retailer audit requirements. Protein and fat quantification dominate routine testing schedules.
- Shelf Life Testing:Accelerated aging protocols for pouch-format products bundle packaging integrity with microbial monitoring. Recurring revenue potential attracts laboratories seeking retainer structures.
Microbial Analysis generates the highest test volumes, while Chemical Residue Testing shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with multinational manufacturers demanding pan-European laboratory networks and retailers imposing batch-specific documentation.
- Manufacturers:Infant formula producers require ISO 17025-accredited partners with multi-site harmonized quality systems. Contract terms stretch across 18-24 month validation cycles.
- Retailers:German supermarket chains now require certificates of analysis for every production batch, displacing periodic auditing with production-integrated workflows.
- Laboratories:Third-party service providers subcontract specialized methods to fill capability gaps in emerging contaminant analysis.
- Consumers:Direct-to-consumer testing remains marginal, limited to niche organic certification verification and allergen concerns.
Manufacturers anchor contract value, with Retailers driving the fastest volume growth.
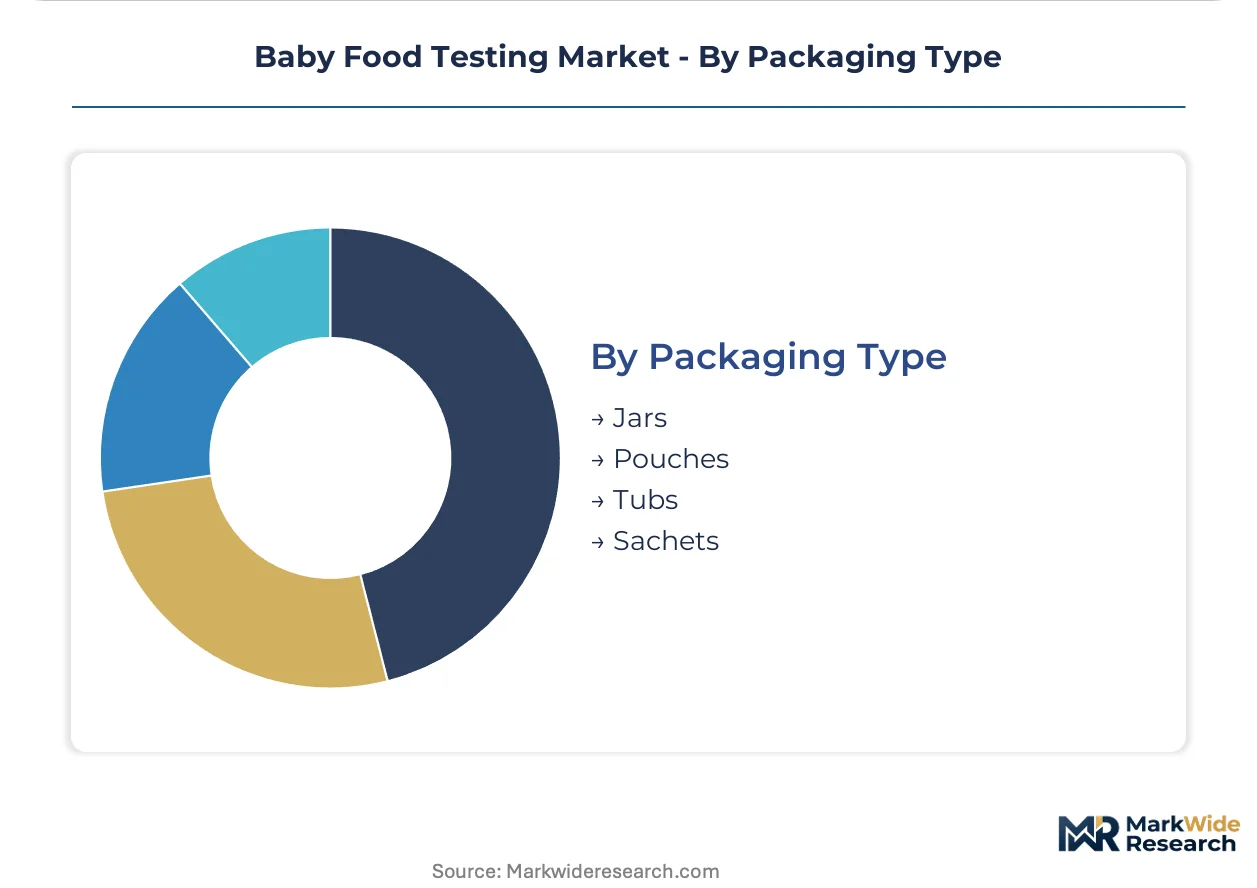
Packaging Type:
Material-matrix interaction dictates which integrity tests apply, with flexible formats creating method validation challenges absent in rigid containers.
- Pouches:Multi-layer flexible packaging requires specialized migration testing for adhesives and printing inks. Shelf life validation services are expanding most quickly in this segment.
- Jars:Glass containers face thermal shock testing and vacuum seal verification. Traditional formats maintain stable testing volumes in Mediterranean markets.
- Tubs:Plastic rigid containers demand compatibility testing with high-acid fruit purees. Recycling content mandates are adding material characterization requirements.
- Sachets:Single-serve powder formats concentrate microbial risk at reconstitution points. Testing protocols emphasize Cronobacter sakazakii detection in dry blend environments.
Jars retain the highest cumulative test volume, with Pouches expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where baby food testing contracts concentrate, as manufacturers migrate production toward jurisdictions with harmonized compliance frameworks and accredited laboratory density. Cost-of-compliance gaps between markets are diverting investment toward regions with established ISO 17025 infrastructure.
United States
FDA enforcement through its Center for Food Safety and Applied Nutrition drives infant formula quality mandates, with manufacturers clustering testing spend around Cronobacter sakazakii screening protocols. The agency's updated guidance on powdered infant formula microbial limits has compressed method validation timelines for domestic laboratories. Greater Boston anchors specialized analytical capacity, where contract research organizations serve multinational formula producers with integrated safety and nutritional verification workflows.
Germany
Private-label supermarket chains now mandate batch-level certificates of analysis before shelf placement, creating sustained demand for accredited testing capacity. EFSA reference points for heavy metals in processed cereal-based foods are tightening laboratory performance requirements across domestic processing facilities. The Rhine-Ruhr metropolitan region concentrates pan-European laboratory networks serving organic baby food processors with multi-site harmonized quality systems.
Netherlands
EFSA headquarters proximity accelerates regulatory intelligence integration into testing protocols, particularly for emerging contaminant method development. The country's export-oriented infant nutrition sector requires documentation aligned with destination market requirements across Asia and the Middle East. Rotterdam-Antwerp corridor laboratories specialize in high-throughput pesticide residue screening for fruit and vegetable purees entering European distribution networks.
Switzerland
Swissmedic oversight of infant formula imports maintains stringent documentation requirements that favor domestic testing partnerships with multinational manufacturers. The country's organic baby food processing sector demands validated protocols for per- and polyfluoroalkyl substances beyond legacy pesticide panels. Zurich and Basel host dedicated infant nutrition testing centers serving Central European markets with specialized chromatography capabilities.
China
SAMR implementation of GB standards for infant formula safety has expanded mandatory testing scopes for both domestic production and import verification. NMPA registration requirements for cross-border e-commerce channels are driving demand for third-party certificates from internationally accredited laboratories. Yangtze River Delta manufacturing clusters source testing services from Shanghai-based providers with dual domestic and international accreditation portfolios.
Baby Food Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pan-European laboratory networks capturing multinational manufacturer contracts through harmonized quality systems. The vendor base concentrates around three strategic tiers: integrated testing conglomerates with multi-continental footprints, regional specialists with deep regulatory expertise in single jurisdictions, and niche method developers focused on emerging contaminant protocols. Competitive positioning depends on accreditation breadth, turnaround time compression, and subscription-based laboratory information management system deployment. Consolidation pressure is intensifying as ISO 17025 certification timelines stretch capacity expansion horizons.
Among integrated testing conglomerates, Eurofins Scientific, SGS Group, and Bureau Veritas exemplify the scale-driven archetype, each anchoring competitive stance through geographic network density rather than single-site specialization. Eurofins leverages its pan-European laboratory footprint to secure multi-year retainer structures. SGS occupies a position emphasizing dedicated infant nutrition testing infrastructure. Bureau Veritas represents the service-bundling approach, combining shelf life validation with ongoing monitoring programs. These three entities collectively illustrate how accreditation breadth and geographic coverage determine contract eligibility at the multinational manufacturer tier.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS Group |
| Intertek Group |
| Bureau Veritas |
| TÜV SÜD |
| Mérieux NutriSciences |
| Romer Labs |
| ALS Limited |
| Silliker Inc |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up laboratory networks in Germany and the Netherlands anchor supply concentration while enforcing pricing discipline through multi-year retainer structures. Their consolidated bargaining power with mass spectrometry equipment vendors compresses per-test costs, yet batch-level certification mandates from retailers sustain premium pricing for accredited capacity.
Pricing Analysis
Capacity additions in Switzerland and the Netherlands are reshaping price floors for HPLC-MS/MS pesticide residue screening. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited laboratories from regional specialists and unaccredited providers. Price differentiation hinges on certification grade and geographic delivery cost, with pan-European networks commanding premiums. Pricing pressure stems from automation investments in high-throughput microbial screening, compressing margins for standalone laboratories. Retailers demonstrate highest price sensitivity for routine nutritional label verification, while infant formula manufacturers accept premium rates for Cronobacter sakazakii batch certification.
Supply Chain Analysis
Freight costs for temperature-sensitive reference standards and chromatography consumables concentrate supply planning around Rotterdam-Antwerp corridor distribution hubs. Manufacturing of analytical instruments centers on Germany, Switzerland, and the United States, with consumables production anchored in China and India. Raw material dependencies span helium carrier gas, high-purity solvents, and certified pesticide reference materials. Single-source vulnerability in specialty column manufacturing from Germany creates chokepoint exposure. Distribution runs through pan-European logistics networks serving batch-integrated testing workflows at private-label processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's tightened heavy metal reference points in processed cereal-based foods generate sustained demand acceleration for validated testing protocols.
For Market Incumbents: Extend accreditation breadth into emerging contaminant method development before compliance deadlines compress validation windows. Consolidate vendor relationships with infant formula manufacturers through integrated safety and nutritional verification workflows. Capacity additions in Central Europe by Eurofins and SGS intensify territorial competition, making ISO 17025 certification investment the critical defensive lever against margin erosion. For New Entrants and Emerging Players: The price-point gap between premium pan-European networks and economy-tier regional laboratories opens white-space in pouch-format shelf life validation services. Target German private-label supermarket chains with subscription-based laboratory information management systems that displace paper-based certificate workflows. Underserved demand for per- and polyfluoroalkyl substances method development offers fastest penetration path. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional specialists with ISO 17025 accreditation but limited emerging contaminant capabilities. Long-term viability over the next decade rests on regulatory expansion momentum rather than cyclical volume growth. Acquisition targets should demonstrate proficiency in low-level heavy metal quantification. The signal to monitor is EFSA's contaminant list expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Expansion | ISO 17025 certification unlocks contracts with multinational infant formula manufacturers requiring harmonized quality systems. |
| Emerging Contaminant Method Development | First-mover validation of per- and polyfluoroalkyl substances protocols captures regulatory expansion premium pricing. |
| Subscription LIS Deployment | Laboratory information management systems enable multi-year retainer structures with German private-label retailers. |
| Pouch-Format Shelf Life Validation | Flexible packaging integrity testing addresses underserved segment with recurring revenue potential. |
| Pan-European Network Integration | Harmonized quality systems across Rhine-Ruhr and Rotterdam-Antwerp corridors satisfy retailer batch certification mandates. |
Research Methodology
Coverage spans Germany, the Netherlands, Switzerland, the United States, and China, with primary inputs from each market's regulatory and commercial stakeholders. Primary interviews with laboratory operations directors, infant formula quality assurance managers, supermarket chain procurement officers, and regulatory affairs specialists combined with secondary validation from EFSA guidance documents, FDA enforcement records, ISO accreditation databases, and customs trade data. Bottom-up testing volume estimates triangulated against top-down manufacturer expenditure patterns.
Granularity-level modeling disaggregated projections across product type, testing method, end user, and packaging format dimensions. Segment-level CAGRs derived from regulatory mandate implementation timelines and equipment capacity expansion patterns. Forecast inputs incorporated EFSA reference point revision schedules, private-label retailer certification mandate adoption curves, and mass spectrometry automation penetration rates across the analysis window.
Caveats apply where accelerated EFSA contaminant list expansion or delayed ISO 17025 accreditation timelines could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market