
 Human Milk Oligosaccharides in Infant Formula Market | 2026-2036
Human Milk Oligosaccharides in Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Human Milk Oligosaccharides in Infant Formula Market Insights
Asset-light bioprocessing partnerships and contract fermentation models are reconfiguring capital requirements for HMO suppliers, allowing mid-scale entrants to compete without billion-dollar manufacturing footprints. Jennewein Biotechnologie GmbH leverages its proprietary microbial cell-line technology to dominate 2'-FL production in Europe. DSM-Firmenich sustains global supply security through multi-site fermentation networks across Switzerland and the United States. Abbott Laboratories anchors North American demand by integrating HMOs across its Similac formulation portfolio.
Human milk oligosaccharides comprise a structurally diverse class of unconjugated glycans, with 2'-fucosyllactose, lacto-N-neotetraose, and 6'-sialyllactose representing the most commercially advanced structures, typically synthesized via precision fermentation using engineered microbial hosts such as E. coli or yeast strains. These bioactive compounds function as prebiotic substrates that selectively nourish Bifidobacterium species in the infant gut, thereby modulating immune development and pathogen exclusion. Powder formulations currently occupy the largest volume share due to extended shelf stability and lower logistics costs, while ready-to-feed liquid formats are capturing faster growth among hospital neonatal units and premium home-care channels. The hypoallergenic formulation segment differentiates through clinical positioning for cow's milk protein sensitivity, whereas fortified standard variants compete on cost-accessibility in emerging markets.
FDA GRAS notifications and EFSA novel food authorizations shape ingredient approval pathways, with China's NMPA and SAMR increasingly influencing global formulation standards through domestic infant formula registration rules. The EU F-Gas Regulation and REACH frameworks constrain solvent and reagent choices in European HMO fermentation facilities, elevating compliance costs for suppliers serving that market. Stakeholders must monitor evolving GRAS self-affirmation thresholds and country-specific prebiotic claim substantiation requirements as regulatory divergence between the United States, European Union, and China intensifies.
Market Dynamics
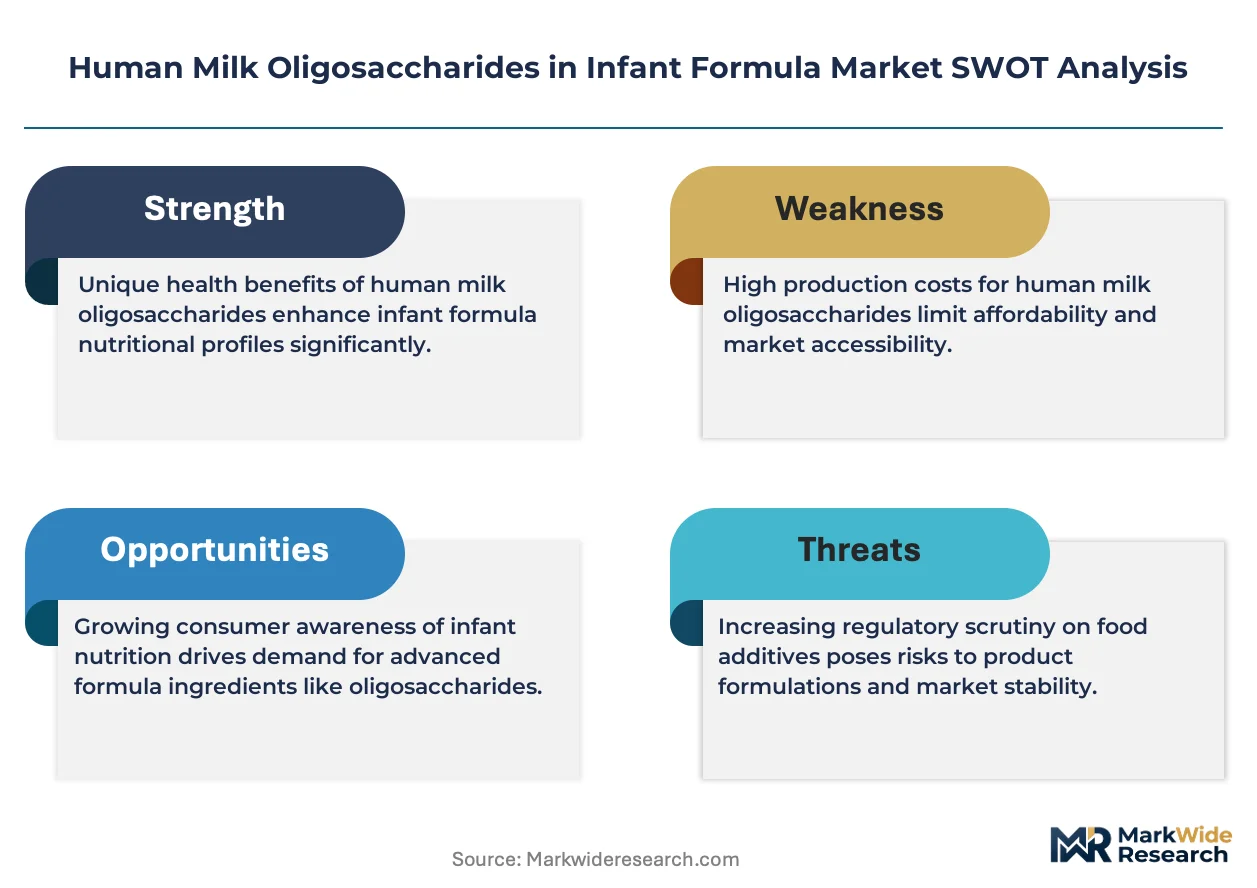
Precision bioprocessing platforms are collapsing the capital intensity barrier for HMO production, enabling microbial fermentation specialists to challenge incumbent chemical synthesis suppliers without billion-dollar manufacturing footprints.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for 2'-fucosyllactose and lacto-N-neotetraose accelerate European market entry for fermentation-derived ingredients.
- Neonatal Intensive Care Units:Ready-to-feed liquid formats with clinically validated HMO dosing protocols penetrate hospital procurement channels in Germany and the United States.
- Precision Fermentation Scale-Up:Engineered E. coli and yeast strain optimization cuts batch cycle times and purification costs for bioactive glycan structures.
Market Restraints
- Feedstock Cost Volatility:Lactose and glucose substrate prices fluctuate with dairy commodity markets, compressing margins for fermentation-based HMO suppliers.
- European Regulatory Compliance Burden:EU F-Gas Regulation and REACH frameworks constrain solvent choices in purification steps, elevating facility capex for suppliers serving that market.
- Structural Supply Concentration:Multi-site fermentation networks remain concentrated among established biotechnology firms, limiting spot-market liquidity for mid-scale formula manufacturers.
Strategic Opportunities
- China NMPA Registration Window:Domestic infant formula registration rules create first-mover advantages for HMO suppliers achieving novel food status with China's national medical products regulator.
- Hypoallergenic Positioning:Clinical differentiation for cow's milk protein sensitivity applications opens premium pricing corridors in pediatric specialty nutrition.
- Continuous Bioprocessing Convergence:Integration of perfusion fermentation with in-line analytical monitoring enables real-time quality control and reduced facility footprints.
Industry Challenges
- Glycobiology Talent Scarcity:Specialized expertise in microbial glycoengineering and downstream purification remains concentrated in academic and industrial research clusters, constraining workforce expansion.
- GRAS Self-Affirmation Complexity:Evolving FDA thresholds for prebiotic claim substantiation require extensive clinical documentation, extending product development timelines.
- Multi-Jurisdiction Labeling Harmonization:Divergent prebiotic and novel food claim standards between the United States, European Union, and China force formula manufacturers to maintain separate packaging and marketing materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Milk Oligosaccharides in Infant Formula Market |
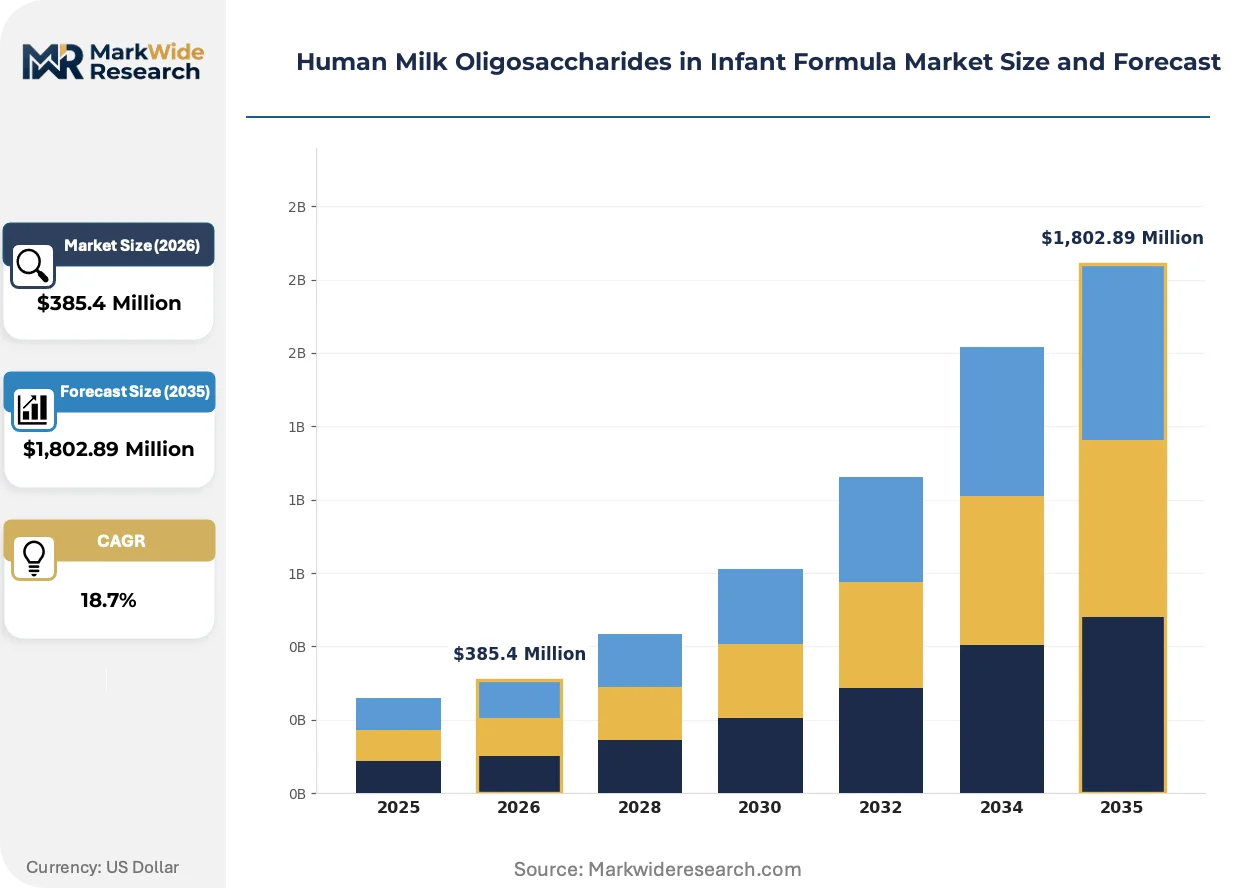
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Ready-to-Feed, Concentrate End User: Hospitals, Home Care, Clinics, Health Centers Distribution Channel: Online, Pharmacies, Supermarkets, Specialty Stores Formulation Type: Standard, Hypoallergenic, Organic, Fortified |
| Companies Covered | DuPont Nutrition & Biosciences, Jennewein Biotechnologie GmbH, Nestlé, Abbott Laboratories, DSM-Firmenich, Chr. Hansen Holding A/S, BASF SE, FrieslandCampina, KYOWA HAKKO BIO CO. LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Milk Oligosaccharides in Infant Formula Market Trends and Innovations
Bioprocessing technology convergence and regulatory pathway maturation are reconfiguring competitive entry barriers, while demand-side purchasing behavior shifts toward clinically validated premium positioning.
Cell-free enzymatic synthesis is hybridizing with traditional microbial fermentation, enabling modular production of complex HMO structures without live-cell cultivation constraints. Specialty ingredient suppliers in Switzerland and Germany pilot these hybrid platforms for lacto-N-fucopentaose variants. The technology is compressing capital requirements for rare glycan production while shortening regulatory qualification timelines.
China's SAMR and NMPA are tightening novel food registration requirements for imported HMO ingredients, mandating domestic clinical trials and manufacturing site inspections. This policy shift forces global suppliers to establish local technical representation and quality documentation systems. European fermentation specialists face extended approval cycles as they adapt to China's dual-track safety assessment protocols.
Pediatric nutrition procurement teams now specify certificate-of-analysis documentation for every HMO lot, replacing commodity purchasing with quality-contract frameworks. Hospital formulary committees in Germany and the United States drive this specification tightening. The shift compresses supplier qualification cycles and elevates analytical testing costs for mid-tier ingredient distributors.
Human Milk Oligosaccharides in Infant Formula Market Segmentation
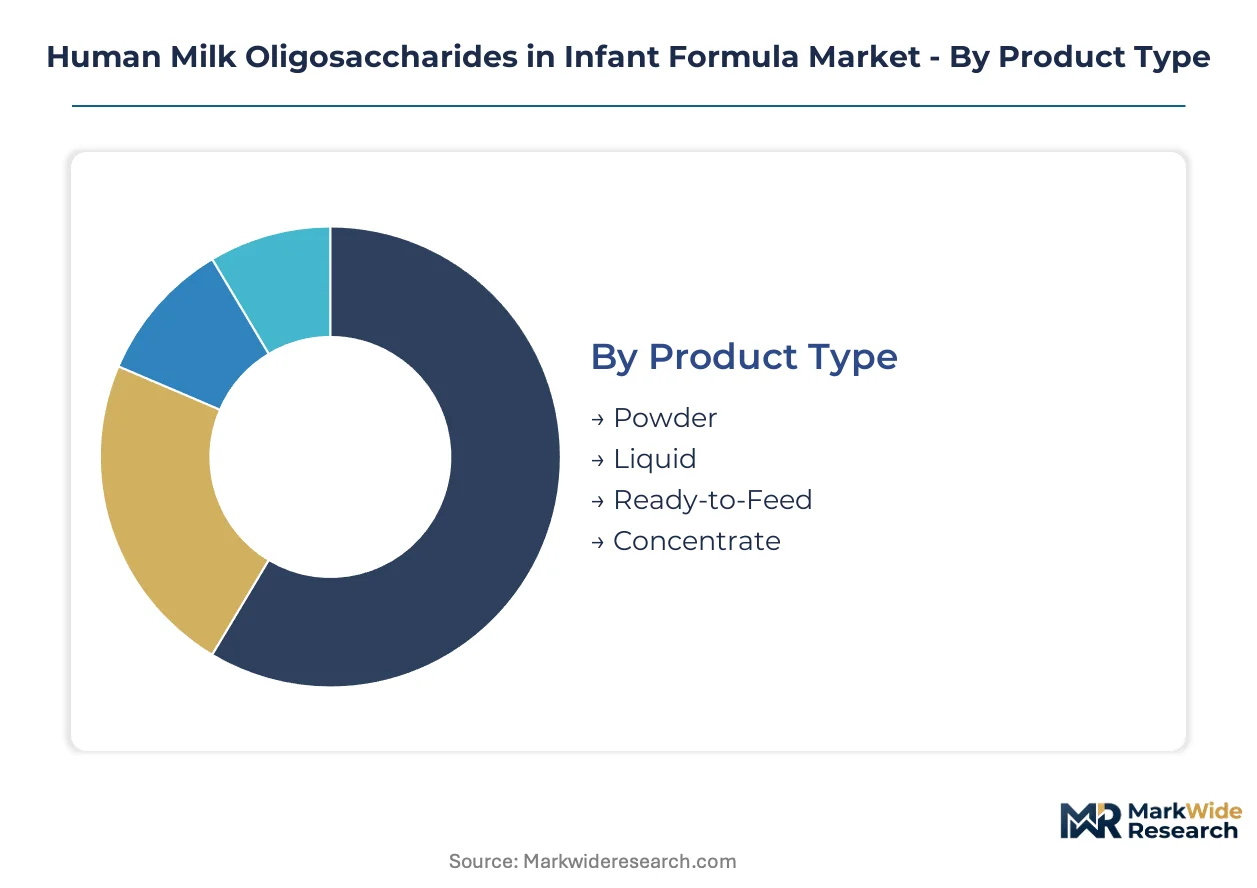
Segmentation in the HMO infant formula market reveals how formulation technology, procurement channel, and clinical positioning split demand across divergent price and quality tiers. Manufacturers configure production lines and regulatory submissions around these divides.
Product Type:
Cost tier separates these formats, with powder commanding manufacturing scale advantages and liquid formats extracting premium positioning through convenience and dosing precision.
- Powder:Dehydrated formulations with extended shelf stability and lower logistics costs dominate volume procurement. Demand concentrates in retail home-care channels across Germany and the United States, driven by cost-accessibility in emerging markets and bulk purchasing patterns.
- Liquid:Ready-to-dilute or pre-mixed aqueous suspensions reduce preparation error in clinical settings. Hospital neonatal units in Germany and the United States specify liquid formats with validated HMO dosing protocols, though cold-chain requirements constrain distribution reach.
- Ready-to-Feed:Sterile single-serve containers eliminate mixing steps entirely. Neonatal intensive care procurement in the United States favors this format for infection control compliance.
- Concentrate:Reduced-water formulations requiring dilution before consumption. Home-care segments in price-sensitive markets utilize concentrate as a middle-cost compromise.
Powder holds installed capacity. Ready-to-Feed is rotating up the share rankings.
End User:
Application context determines formulation specification, with clinical settings demanding certificate-of-analysis documentation and home-care channels prioritizing convenience and cost.
- Hospitals:Neonatal intensive care units and maternity wards specify HMO-enhanced formulas with lot-level analytical documentation. Procurement committees in Germany and the United States drive quality-contract frameworks that compress supplier qualification cycles.
- Home Care:Parent-directed purchasing through retail and e-commerce channels dominates volume. China and the United States represent the largest addressable populations, with premium organic positioning gaining traction among educated consumers.
- Clinics:Pediatric outpatient facilities recommend HMO formulas for allergy-prone infants. Cow's milk protein sensitivity applications open premium pricing corridors in specialty nutrition.
- Health Centers:Community-based maternal health programs distribute subsidized formulations. Emerging market access programs in China utilize health centers for rural penetration.
Hospitals hold installed capacity. Home Care is rotating up the share rankings.
Distribution Channel:
Customer type and purchasing behavior fragment across channels, with online platforms capturing educated premium consumers and pharmacies retaining clinical trust.
- Online:Direct-to-consumer platforms and e-commerce marketplaces enable subscription purchasing and educational content delivery. Specialty organic brands in the United States and China scale digital-first distribution to bypass traditional retail margins.
- Pharmacies:Licensed dispensaries provide clinical credibility and pharmacist consultation. German pharmacy chains maintain formulary relationships with fermentation-derived HMO suppliers.
- Supermarkets:Mass retail channels compete on price accessibility and brand recognition. Standard fortified variants dominate shelf placement in emerging markets.
- Specialty Stores:Premium baby product retailers curate organic and hypoallergenic assortments. Urban centers in China and the United States concentrate specialty store footprint.
Supermarkets hold installed capacity. Online is rotating up the share rankings.
Formulation Type:
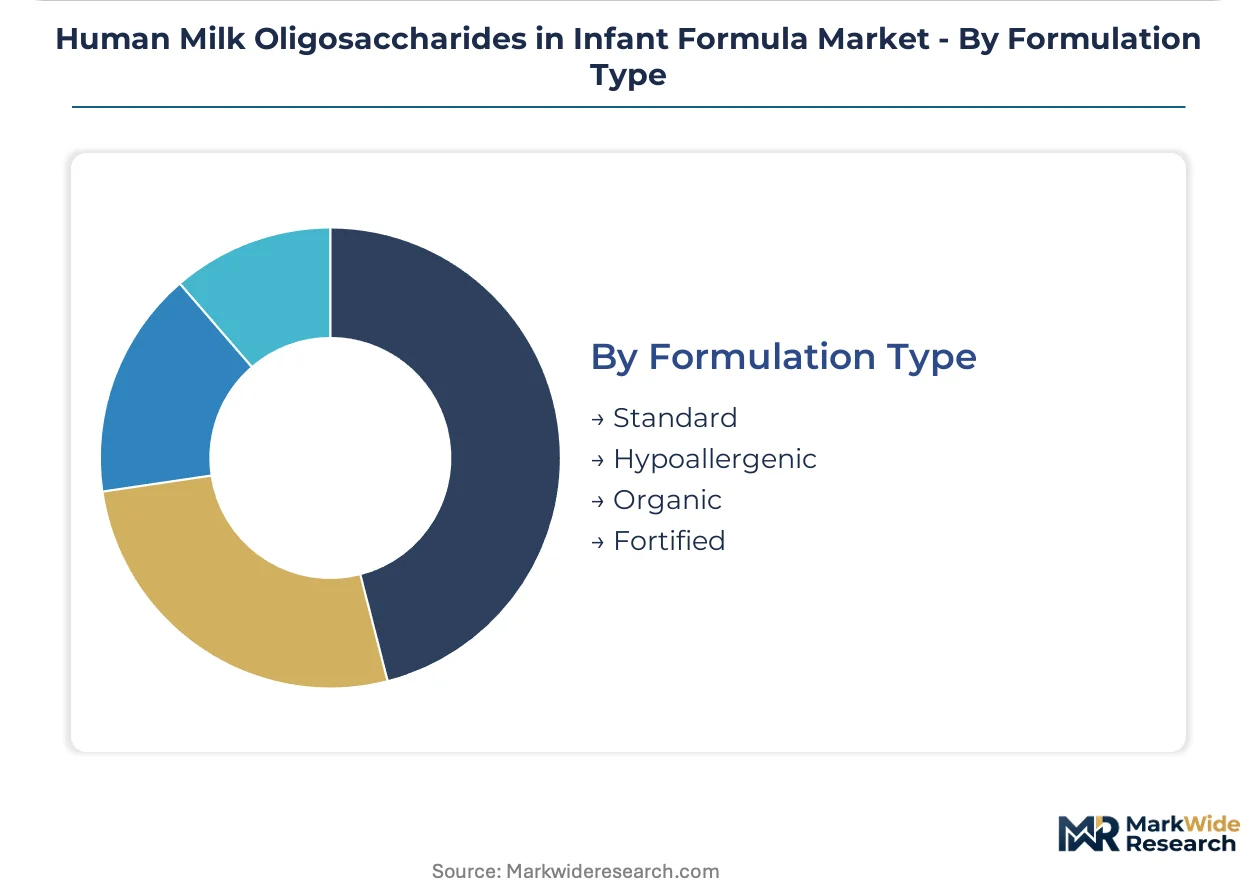
Margin structure and regulatory pathway differentiate these categories, with hypoallergenic and organic variants commanding certification premiums and standard formulations competing on cost.
- Hypoallergenic:Extensively hydrolyzed or amino acid-based proteins combined with HMO prebiotics for cow's milk protein sensitivity. Clinical differentiation supports premium pricing in pediatric specialty nutrition across Germany and the United States.
- Organic:Certified ingredient sourcing and processing standards attract parent willingness-to-pay for perceived purity. Jennewein Biotechnologie GmbH and DSM-Firmenich supply fermentation-derived HMOs meeting organic formulation requirements in European markets.
- Standard:Conventional protein bases with HMO fortification at cost-accessible price points. Volume manufacturing in China targets mass-market penetration.
- Fortified:Multi-nutrient enhancement beyond HMO inclusion, combining prebiotics with probiotics, DHA, or ARA. Emerging market positioning emphasizes developmental benefit claims.
Standard holds installed capacity. Hypoallergenic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in HMO ingredients reveal concentrated production hubs serving dispersed formulation markets. Fermentation-derived glycans move from European and North American bioprocessing facilities into Asian formula manufacturing, while regulatory divergence shapes trade corridor viability.
Germany
Jennewein Biotechnologie GmbH anchors European 2'-fucosyllactose supply from its North Rhine-Westphalia operations. EFSA novel food authorizations streamline intra-EU ingredient movement, though EU F-Gas Regulation elevates purification facility compliance costs. The Rhine-Ruhr industrial corridor concentrates precision fermentation capacity serving continental formula manufacturers.
United States
Abbott Laboratories integrates HMOs across its Similac portfolio, driving domestic absorption of fermentation-derived ingredients. FDA GRAS self-affirmation pathways enable faster ingredient qualification than European novel food procedures. Boston-Cambridge biotech clusters host microbial engineering firms optimizing E. coli strain productivity for glycan synthesis.
China
NMPA and SAMR novel food registrations constrain imported HMO ingredient access, forcing foreign suppliers into domestic clinical trial commitments. Shanghai and Beijing formula manufacturers accelerate HMO incorporation as parents seek gut health differentiation. Yangtze River Delta bioprocessing parks attract joint ventures seeking localized fermentation capacity.
Switzerland
DSM-Firmenich operates multi-site fermentation networks supplying global formula manufacturers with lacto-N-neotetraose and related structures. Swissmedic oversight of novel food ingredients runs parallel to EFSA procedures, creating dual-track compliance requirements. Basel's pharmaceutical-industrial complex hosts downstream purification and analytical validation facilities.
Netherlands
FrieslandCampina leverages dairy cooperative feedstock integration for HMO precursor supply chain control. REACH framework compliance shapes solvent selection in glycan purification operations. Randstad logistics infrastructure enables just-in-time ingredient delivery to European formula packaging facilities.
Human Milk Oligosaccharides in Infant Formula Market Competitive Landscape
On the supply side, the industry is consolidating around biotechnology specialists with proprietary microbial platforms and multi-product fermentation capabilities. Tiered competitive positioning separates strain-optimization leaders from contract manufacturing service providers. Three archetypes dominate: integrated nutrition conglomerates with captive HMO programs, standalone fermentation technology licensors, and dairy cooperatives leveraging lactose feedstock integration. Capacity expansion through perfusion fermentation scale-up and strategic partnerships for Chinese regulatory registration constitute the dominant competitive moves.
Among European biotechnology specialists, Jennewein Biotechnologie GmbH and DSM-Firmenich exemplify the platform-technology archetype, each occupying positions defined by microbial cell-line ownership and multi-structure glycan portfolios. Abbott Laboratories represents the integrated nutrition conglomerate model, anchoring North American demand through formula brand ownership. DuPont Nutrition & Biosciences sits within the ingredient supply tier, serving manufacturers without captive fermentation capabilities.
| Leading Market Players |
|---|
| DuPont Nutrition & Biosciences |
| Jennewein Biotechnologie GmbH |
| Nestlé |
| Abbott Laboratories |
| DSM-Firmenich |
| Chr. Hansen Holding A/S |
| BASF SE |
| FrieslandCampina |
| KYOWA HAKKO BIO CO. LTD. |
| Others |
Pricing and Supply Chain Analysis
Feedstock cost volatility in lactose and glucose substrates compresses margins across fermentation-derived HMO tiers while simultaneously forcing suppliers toward multi-source procurement architectures and regional manufacturing redundancy. This dual pressure widens price spreads between premium clinical-grade glycans and standard-fortified formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifies across premium clinical-grade, standard-fortified, and economy mass-market tiers driven by certification level and volume scale. Price differentiation stems from EFSA novel food authorization status and lot-level analytical documentation. Cost compression in the economy tier is intensifying because Chinese mass-manufacturers absorb feedstock spikes without pricing power. Hospital procurement committees exhibit lowest price sensitivity, while emerging market health centers face acute budget constraints.
Supply Chain Analysis
Lactose feedstock supply draws from Germany, the Netherlands, and New Zealand dairy cooperative networks, with glucose substrates sourcing from corn processing facilities in the United States and Brazil. Engineered microbial strains, chromatography resins, and sterile packaging materials constitute critical component dependencies. Single-source vulnerability concentrates in proprietary E. coli and yeast cell lines held by Jennewein Biotechnologie GmbH and DSM-Firmenich. Distribution runs through just-in-time ingredient delivery to European formula packaging facilities and ocean-freight consolidation for Asian manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate-of-analysis documentation and quality-contract frameworks represent a service-attach layer expanding faster than base ingredient supply, as hospital formulary committees mandate lot-level traceability and analytical validation.
For Market Incumbents: Entrench multi-site fermentation redundancy across Switzerland and the United States to defend against emerging microbial engineering specialists in China's Yangtze River Delta bioprocessing parks. Deepen backward integration into lactose precursor supply through dairy cooperative partnerships, while accelerating NMPA registration timelines to preempt domestic Chinese HMO producers.
For New Entrants and Emerging Players: Establish a beachhead in the hypoallergenic formulation segment, where clinical differentiation for cow's milk protein sensitivity commands premium pricing corridors with lower volume thresholds than mass-market standard variants. Target ready-to-feed liquid formats for neonatal intensive care units in Germany and the United States, leveraging quality-contract procurement frameworks that favor analytical documentation capabilities over scale.
For Investors and Strategic Acquirers: The market sits at a regulatory-pathway-maturation phase that favors platform-technology specialists with proprietary cell-line ownership and multi-structure glycan portfolios. Five-to-ten year viability hinges on fermentation scale-up economics and Chinese market access. Monitor NMPA novel food registration approvals as the inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Fermentation Scale-Up | Jennewein Biotechnologie GmbH and DSM-Firmenich deploy continuous bioprocessing to compress batch cycle times and facility footprints. |
| China NMPA Registration Investment | Foreign suppliers commit to domestic clinical trials and manufacturing site inspections to unlock formula manufacturer procurement channels. |
| Cell-Free Enzymatic Synthesis Pilot | Swiss and German specialists hybridize enzymatic platforms with traditional fermentation for modular rare glycan production. |
| Quality-Contract Framework Adoption | Hospital formulary committees in Germany and the United States replace commodity purchasing with certificate-of-analysis mandates. |
| Organic Certification Alignment | Fermentation-derived HMO suppliers adapt purification protocols to meet European organic formulation requirements. |
Research Methodology
A spread of perspectives from fermentation technology directors, infant formula procurement managers, regulatory affairs specialists at EFSA and NMPA, and neonatal nutrition clinicians converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA GRAS notifications, EFSA novel food authorizations, SAMR registration databases, and customs trade data for glycan ingredient flows. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user, distribution channel, and formulation type alongside regional regulatory cluster differentiation. CAGRs derived from installed fermentation capacity expansion curves and formula manufacturer adoption rate modeling. Forecast inputs incorporated EFSA approval timelines, NMPA registration windows, and hospital procurement specification tightening.
Sensitivities concentrate around feedstock commodity price swings, regulatory approval delays in China, and competitive entry from cell-free enzymatic synthesis platforms. Forecasts reflect documented assumptions regarding strain productivity improvements and purification yield advances. Cross-checking against EFSA novel food authorization databases and NMPA registration status records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Pet Milk Replacers Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market