
 Fortified Pet Food Market | 2026-2036
Fortified Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Pet Food Market Foresight
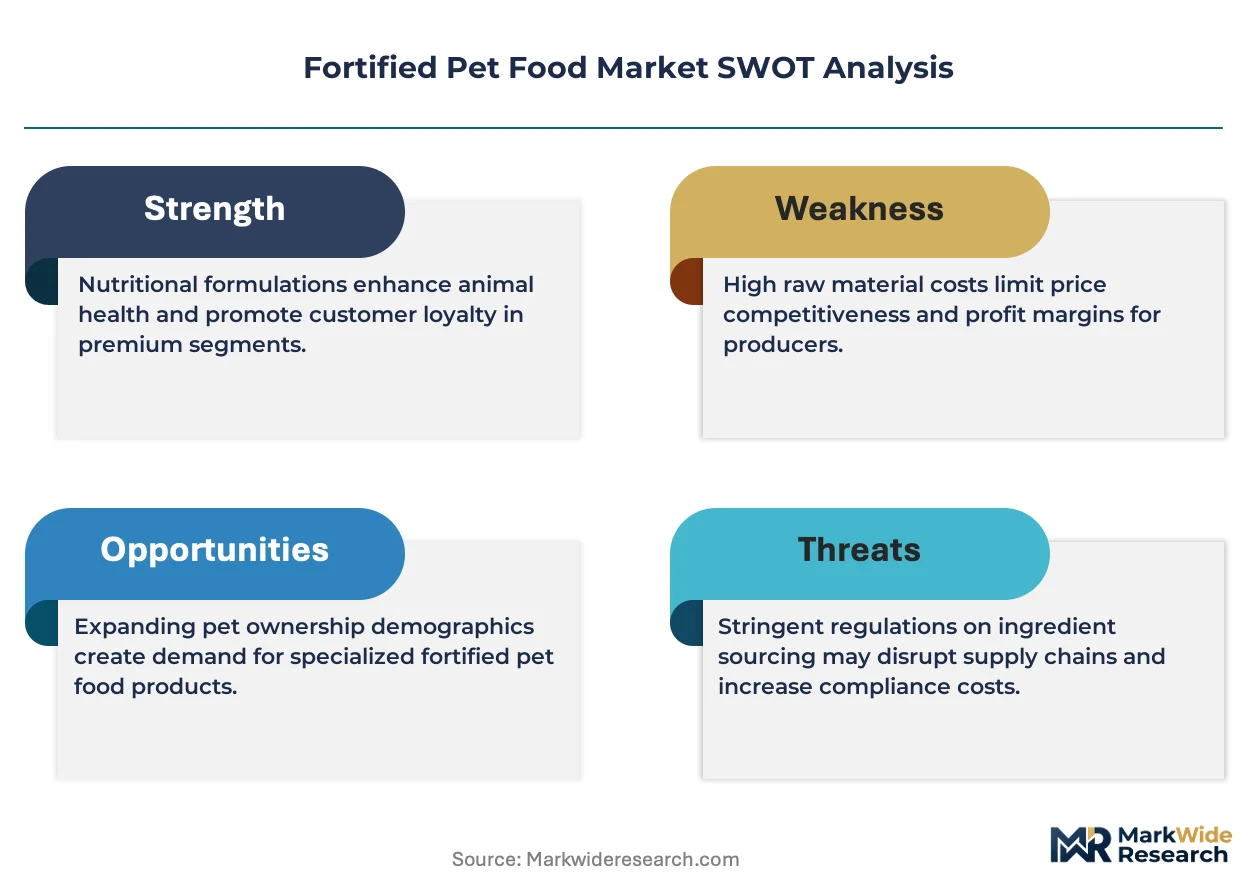
Premium human-grade ingredient specifications is rotating through the fortified pet food category as owners equate pet nutrition with personal wellness standards. Nestle Purina Petcare leverages its global manufacturing footprint to sustain cost advantages across multiple fortification tiers. Mars Petcare anchors its position through veterinary channel exclusivity for prescription-grade formulations. Hill's Pet Nutrition differentiates via science-backed clinical nutrition protocols developed in partnership with veterinary institutions.
Fortified pet food denotes commercially prepared animal nutrition products enhanced with bioavailable vitamins, minerals, probiotics, and functional fatty acids through extrusion, retorting, or cold-press manufacturing processes, designed to address specific physiological needs beyond baseline macronutrient provision. Dry food formulations occupy the largest volume position due to shelf stability and cost efficiency, while wet food segments command disproportionate margin pools through moisture-rich delivery systems that improve palatability and nutrient absorption rates. Probiotic fortification is expanding fastest within the nutrient category as gastrointestinal health claims gain veterinary endorsement and consumer willingness to pay premiums for microbiome-supporting formulations rises across canine and feline applications.
The FDA's Center for Veterinary Medicine enforces ingredient safety and labeling accuracy requirements that elevate compliance costs for new market entrants, while the Association of American Feed Control Officials establishes nutrient profiles that manufacturers must meet for complete-and-balanced claims. State-level agriculture departments conduct feed inspection programs that create additional jurisdictional variation in enforcement intensity across the United States. Stakeholders must monitor evolving substantiation standards for structure-function claims as regulatory scrutiny of probiotic and omega-3 efficacy assertions intensifies without requiring pre-market approval.
Market Dynamics
Urban millennial pet owners in the United States and Western Europe are compressing the humanization cycle of pet nutrition, forcing manufacturers to accelerate formulation transparency and clinical substantiation timelines.
Growth Catalysts
- Veterinary channel endorsement:Small-animal clinics in the United States now stock fortified formulations as revenue centers, converting preventive care visits into recurring nutrition subscriptions.
- EPA and state-level feed safety frameworks:Harmonized inspection protocols across California, Texas, and New York reduce interstate compliance friction for multi-facility manufacturers.
- Probiotic strain stabilization:Microencapsulation advances enable shelf-stable microbiome formulations previously limited to refrigerated veterinary products.
Market Restraints
- Animal protein input volatility:Rendering facility concentration in the Midwestern United States creates price transmission risk for omega-3 and amino acid fortification bases.
- Technical limitation in bioavailability:Heat-sensitive vitamin degradation during extrusion above 120°C forces costly post-extrusion coating or cold-press process shifts.
- FDA substantiation friction:Structure-function claims for joint health formulations face elevated evidentiary demands without pre-market approval pathways, extending launch timelines.
Strategic Opportunities
- Underpenetrated senior pet segment:Cognitive function and mobility-focused fortification for dogs aged 8+ remains underserved relative to the puppy growth category.
- Direct-to-veterinarian subscription platforms:Telehealth-integrated auto-ship models bypass traditional distributor markups while capturing compliance data.
- EU Green Deal packaging mandates:Mono-material recyclable pouches for wet fortified formats create first-mover positioning in advance of 2030 circular economy requirements.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning veterinary nutrition, food science, and regulatory affairs commands premium compensation and extends hiring cycles.
- Legacy ERP integration:Track-and-trace serialization requirements for FDA compliance collide with decades-old manufacturing execution systems at mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Pet Food Market |
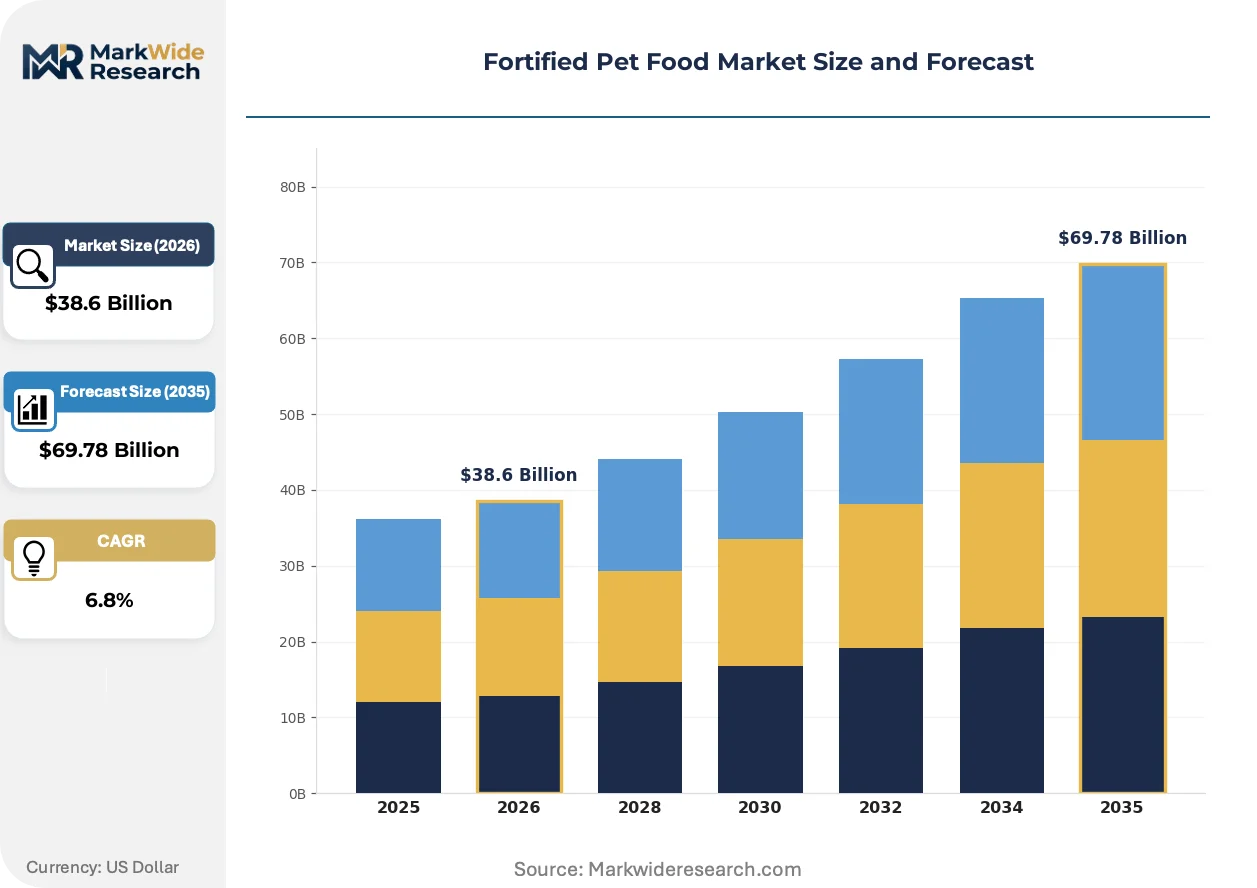
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Semi-Moist Food, Treats, Supplements Fortification Nutrients: Vitamins, Minerals, Probiotics, Omega-3 Fatty Acids, Antioxidants Target Animal: Canine, Feline, Avian, Small Mammals, Exotic Pets Sales Channel: Veterinary Clinics, Specialty Pet Stores, Online Retailers, Supermarkets, Convenience Stores |
| Companies Covered | General Mills, The J.M. Smucker Company, Nestle Purina Petcare, Wellness Pet Company, Diamond Pet Foods, Mars Petcare, Colgate-Palmolive, Royal Canin, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Pet Food Market Shifts & Advancements
Cold-press and freeze-dried manufacturing architectures are redrawing competitive boundaries in premium fortified categories, enabling nutrient retention rates that extrusion cannot match.
Precision fermentation-derived proteins are fragmenting the traditional rendering-based supply chain for amino acid fortification. Boutique manufacturers in Colorado and Oregon have adopted these inputs for hypoallergenic formulations. The technology is fragmenting procurement patterns as buyers bypass commodity meat meal markets entirely.
EFSA's 2023 updated guidance on animal feed additives demands novel safety data packages for probiotic strains not previously authorized in the European Union. Manufacturers must commission 90-day toxicology studies and environmental fate assessments. Wet food producers targeting German and French veterinary channels face the steepest compliance cost escalation.
Subscription-based replenishment models now capture one-third of repeat purchases in metropolitan United States corridors. Independent pet specialty retailers respond with private-label fortified lines and loyalty programs. The shift concentrates in coastal cities where same-day delivery infrastructure supports perishable wet format logistics.
Fortified Pet Food Market Segmentation
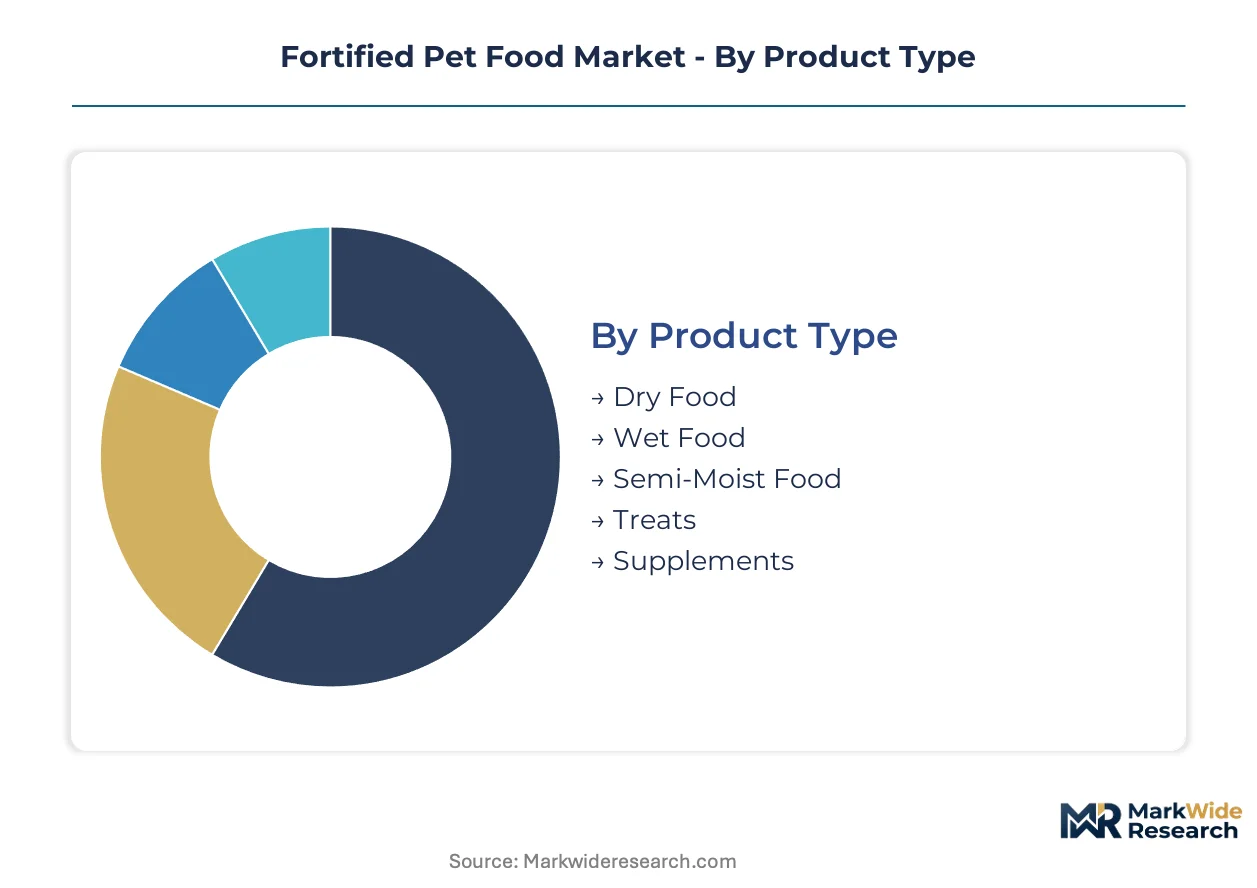
Segmentation in fortified pet food determines channel economics and margin capture. Veterinary-exclusive formulations command subscription pricing power. Mass-market SKUs compete on shelf velocity and manufacturing scale.
Product Type:
Veterinary clinics stock dry and wet formats as compliance tools. Specialty retailers push freeze-dried and semi-moist as differentiation levers. Online channels carry the full spectrum with subscription mechanics.
- Dry Food:Extruded kibble with post-process vitamin coating dominates volume. Midwestern manufacturing clusters in Kansas and Iowa supply veterinary chains across Texas and Florida with cost-efficient complete nutrition.
- Wet Food:Retorted cans and pouches deliver moisture-rich nutrient absorption. Coastal metropolitan corridors in California and New York show disproportionate subscription attachment for palatability-sensitive senior pets.
- Semi-Moist Food:Intermediate moisture formats target training and portability segments. Independent pet retailers in Colorado and Oregon stock these as bridge products between dry bulk and wet premium.
- Treats:Functional chews with glucosamine or dental additives. Veterinary clinics dispense these as preventive care extensions.
- Supplements:Powder and liquid add-ons for homemade diets. Online direct-to-consumer models capture this fragmentation.
Dry food dominates installed base. Wet food is where expansion concentrates.
Fortification Nutrients:
Cost tier separates commodity fortification from clinical-grade inputs. Vitamin and mineral premixes compete on procurement scale. Probiotics and omega-3s extract premiums through strain specificity.
- Vitamins:Heat-stable A, D, E, K and B-complex blends form baseline complete nutrition. Extrusion-compatible formulations from DSM and BASF supply mid-tier manufacturers in the Midwest.
- Minerals:Chelated zinc, selenium yeast, and calcium phosphates address bioavailability gaps. Large-format dry food producers in Iowa and Nebraska integrate these at lowest cost per ton.
- Probiotics:Microencapsulated Bacillus and Lactobacillus strains with CFU guarantees. German and French veterinary channels demand EFSA-compliant safety dossiers that elevate entry costs.
- Omega-3 Fatty Acids:Marine and algal DHA/EPA sources for cognitive and coat health. Sustainability-conscious buyers in the Pacific Northwest and New England drive algal substitution.
- Antioxidants:Natural tocopherols and synthetic BHT/BHA for shelf-life extension. Clean-label pressure in California and New York favors rosemary and mixed tocopherol alternatives.
Vitamins and minerals dominate installed base. Probiotics is where expansion concentrates.
Target Animal:
Application focus determines formulation complexity and regulatory pathway. Canine and feline segments absorb clinical nutrition R&D. Avian and exotic categories operate with lighter substantiation burdens.
- Canine:Breed-specific and life-stage formulations from puppy growth to senior mobility. Hill's Prescription Diet and Royal Canin Veterinary Diet anchor clinic shelves with joint, renal, and weight management SKUs.
- Feline:Obligate carnivore protein requirements with urinary pH modulation. Wet format preference among urban owners in San Francisco and Chicago drives premium pouch development.
- Avian:Seed and pellet fortification for psittacine species. Specialty retailers in Florida and Texas serve parrot owner concentrations.
- Small Mammals:Rabbit, guinea pig, and ferret formulations with species-specific fiber and protein ratios. Online communities drive demand for hay-fortified and probiotic-enhanced options.
- Exotic Pets:Reptile and amphibian nutritional gels and powders. Veterinary exotic specialists in metropolitan teaching hospitals prescribe these for metabolic bone disease prevention.
Canine dominates installed base. Feline is where expansion concentrates.
Sales Channel:
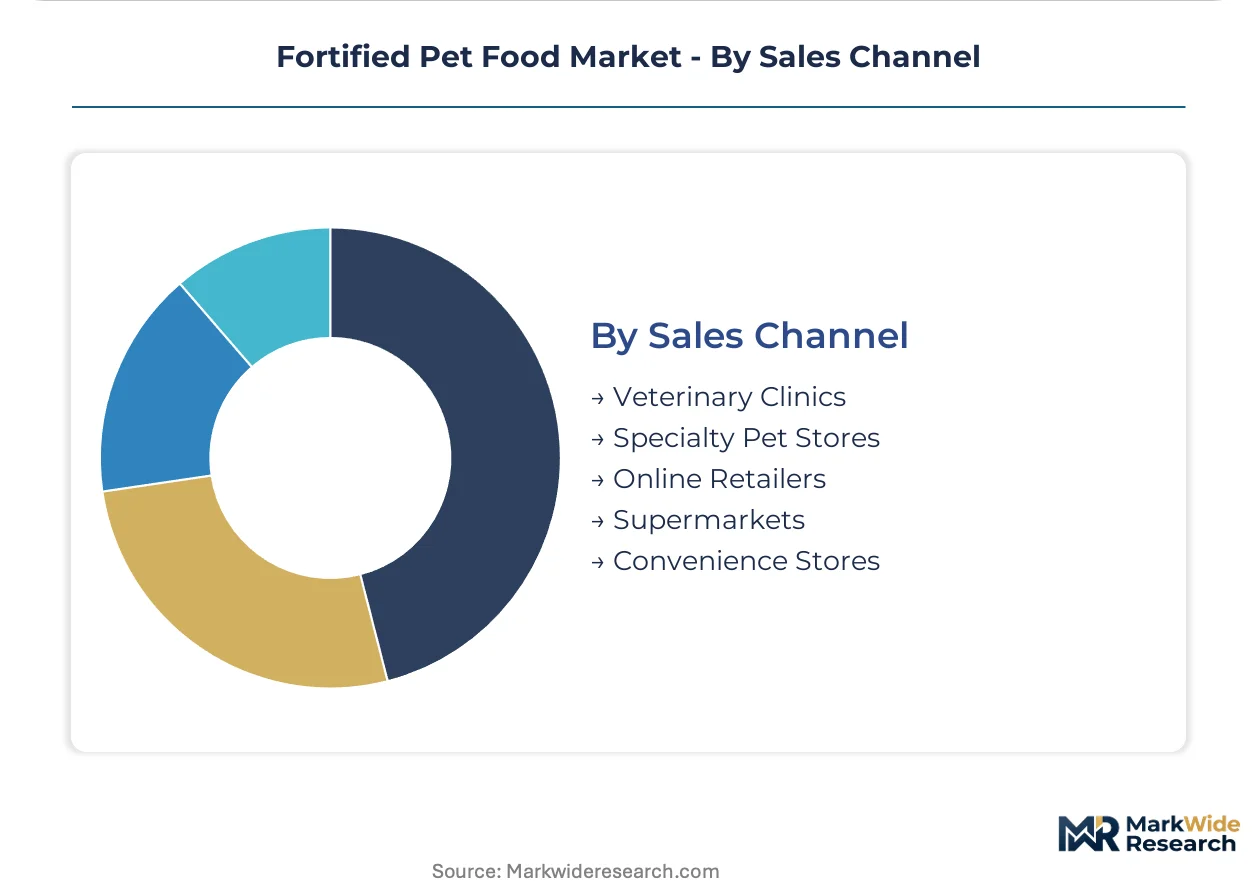
Geography shapes channel viability. Veterinary density correlates with subscription penetration. Same-day delivery infrastructure determines wet format online success.
- Veterinary Clinics:Prescription and wellness-grade formulations with compliance monitoring. Small-animal practices in Boston and Los Angeles convert preventive visits to auto-ship subscriptions.
- Specialty Pet Stores:Curated premium and natural positioning with staff consultation. Independent retailers in Portland and Austin deploy private-label fortified lines against chain competition.
- Online Retailers:Algorithm-driven replenishment and veterinary telehealth integration. Chewy and Amazon capture repeat purchase loyalty in suburban corridors with high pet ownership density.
- Supermarkets:Mass-market complete nutrition with price-promotion mechanics. Kroger and Walmart distribution centers in Ohio and Arkansas push volume through circular advertising.
- Convenience Stores:Emergency single-serve wet packs and treat impulse purchases. Urban bodega networks in New York City stock these for unplanned pet care needs.
Veterinary clinics dominate installed base. Online retailers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in fortified pet food tilt toward net-import dependence in Western Europe and East Asia, while the United States and Brazil sustain exportable surpluses in extruded dry formulations. Regulatory divergence between FDA substantiation requirements and EFSA's novel feed additive protocols fragments cross-border formulation standardization.
United States
Veterinary clinic density in metropolitan corridors drives subscription penetration for prescription-grade formulations. The FDA's Center for Veterinary Medicine enforces structure-function claim substantiation that extends launch timelines for probiotic SKUs. Manufacturing clusters in Kansas and Iowa supply cost-efficient extruded kibble to Texas and Florida veterinary chains.
Germany
EFSA's 2023 updated guidance on animal feed additives demands 90-day toxicology studies for unauthorized probiotic strains. Wet food producers targeting German veterinary channels face steep compliance cost escalation. The Rhine-Ruhr industrial zone concentrates cold-press equipment manufacturing for premium European exporters.
China
SAMR's national food safety standards for pet feed create harmonized domestic compliance frameworks that reduce provincial friction. Algal DHA sourcing from Qingdao bioreactors displaces marine fish oil dependence for omega-3 fortification. Yangtze River Delta contract manufacturers serve Southeast Asian private-label demand.
Brazil
Rendering facility concentration in São Paulo state generates cost-advantaged amino acid premix bases for Mercosur export. ANVISA's veterinary product registration pathways remain lighter than FDA equivalents, accelerating formulation iteration. Campinas industrial parks host multinational co-manufacturing agreements for Latin American distribution.
Japan
PMDA's quasi-drug classification for functional pet foods creates a distinct regulatory tier between feed and pharmaceuticals. Tokyo metropolitan pet owners demonstrate disproportionate willingness to pay for cognitive function fortification in senior dogs. Osaka-based ingredient traders mediate European probiotic strain imports.
Fortified Pet Food Market Competitive Landscape
Concentration sits with diversified consumer goods conglomerates that leverage cross-category procurement scale for vitamin and mineral premix sourcing. Mid-tier specialists compete through veterinary channel exclusivity and species-specific formulation depth. Two strategic archetypes dominate: multinational CPG platforms with global manufacturing footprints, and clinical-nutrition specialists anchored in veterinary institutional partnerships. Competitive moves center on backward integration into rendering and precision fermentation inputs, plus telehealth-integrated subscription platform development.
Within the multinational CPG tier, Nestle Purina Petcare and Mars Petcare exemplify scale-driven archetypes that sustain cost advantages across multiple fortification tiers through captive supply chain control. Hill's Pet Nutrition occupies a position representing the clinical-specialist archetype, anchoring its market presence through science-backed protocols developed alongside veterinary teaching institutions. Colgate-Palmolive sits within the consumer goods diversification model, applying oral care R&D infrastructure toward dental-functional pet treat development.
| Leading Market Players |
|---|
| General Mills |
| The J.M. Smucker Company |
| Nestle Purina Petcare |
| Wellness Pet Company |
| Diamond Pet Foods |
| Mars Petcare |
| Colgate-Palmolive |
| Royal Canin |
| Hill's Pet Nutrition |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for rendered protein and algal DHA lock in supply access for Nestle Purina and Mars Petcare while anchoring price visibility across volatile amino acid and omega-3 input markets. These agreements insulate veterinary-grade formulations from spot-market swings in Midwestern rendering facility output.
Pricing Analysis
Industrial OEM buyers anchor subscription pricing for veterinary-exclusive formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical substantiation depth. Price differentiation hinges on FDA compliance tier and veterinary channel endorsement. Pricing pressure stems from precision fermentation protein substitution in boutique Colorado and Oregon formulations. Mass-market supermarket buyers exhibit highest price sensitivity; prescription-grade subscribers demonstrate lowest.
Supply Chain Analysis
Midwestern rendering facility concentration in Iowa, Kansas, and Nebraska underwrites cost-efficient amino acid premix supply for dry food extrusion. Raw material dependencies center on marine fish oil, algal DHA, and microencapsulated probiotic strains. Single-source vulnerability concentrates in Bacillus strain suppliers serving EFSA-compliant European channels. Distribution runs through veterinary clinic networks, specialty retail, and telehealth-integrated auto-ship platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary telehealth platforms are creating platform-economics inflection by collapsing nutrition consultation, prescription authorization, and auto-replenishment into unified subscription ecosystems. Interoperability between clinic practice management software and direct-to-consumer fulfillment systems locks in recurring revenue capture.
For Market Incumbents: Fortify backward integration into precision fermentation protein production to neutralize boutique competitor sourcing advantages. Deepen captive supply of heat-stable vitamin premixes through DSM and BASF partnership exclusivity. Counter cold-press equipment proliferation in Colorado and Oregon by accelerating microencapsulation R&D for shelf-stable probiotic retention. For New Entrants and Emerging Players: EFSA fast-track certification for novel Bacillus strains creates entry pathway into German and French veterinary channels. Target senior canine cognitive function formulations as the most penetrable white-space segment relative to saturated puppy growth categories. Deploy direct-to-veterinarian subscription platforms with compliance data capture as primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors clinical-nutrition specialists with veterinary teaching hospital partnerships. Long-term viability rests on telehealth-integrated platform ownership rather than manufacturing scale alone. Watch probiotic strain IP portfolios as inflection signal for acquisition premium justification.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Chewy and Amazon auto-ship models capture compliance data while bypassing distributor markups. |
| Precision Fermentation Scale-Up | Algal DHA from Qingdao bioreactors displaces marine fish oil dependence for omega-3 fortification. |
| Veterinary Channel Exclusivity | Hill's Prescription Diet anchors clinic shelves through science-backed renal and joint health protocols. |
| EFSA Certification Investment | German and French wet food producers face steep compliance cost escalation for novel probiotic strains. |
| Mono-Material Packaging Transition | EU Green Deal mandates create first-mover positioning for recyclable wet food pouches by 2030. |
Research Methodology
The analysis maps dry, wet, semi-moist, treat, and supplement sub-sectors, each validated through formulation chemists, veterinary nutritionists, regulatory affairs leads at FDA and EFSA, and procurement directors at Midwestern manufacturing clusters. Secondary sources include FDA Center for Veterinary Medicine filings, AAFCO nutrient profile databases, EFSA feed additive guidance updates, and customs trade data for rendered protein flows. Bottom-up SKU-level volume estimates triangulate against top-down category expenditure benchmarks from veterinary practice management systems.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, fortification nutrient tier, target animal species, and sales channel density. CAGRs derive from installed base attrition rates and expansion segment penetration curves. Forecast inputs incorporate probiotic strain stabilization timelines and cold-press equipment deployment rates in premium manufacturing.
Underlying assumptions cover regulatory substantiation pathway stability and rendering facility capacity expansion, with deviation risk concentrated in FDA structure-function claim enforcement intensity and EFSA novel additive authorization delays. Practitioners should keep alternative scenarios live as precision fermentation protein cost curves and EU packaging mandate timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market