
 Europe Organic Baby Food Market | 2026-2036
Europe Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Baby Food Market Foresight
Specialty retail is narrowing its footprint across continental Europe as online subscription channels capture urban parent cohorts. HiPP GmbH & Co. Vertrieb KG anchors its position through backward integration into biodynamic ingredient sourcing. Danone S.A. leverages its specialized nutrition division to sustain R&D intensity in allergen-free formulations. Nestlé S.A. competes through controlled distribution partnerships with premium pharmacy chains in France and Switzerland.
Europe organic baby food comprises certified agricultural ingredients processed without synthetic pesticides, artificial preservatives, or genetically modified organisms, meeting EU Regulation 2018/848 standards for organic production and labeling. The category serves infants and toddlers from four months to three years, delivering stage-appropriate micronutrient density for neurological and physical development. Pouches now lead packaging innovation due to convenience and portion control, though glass jars retain margin pools in gift and pharmacy segments. Direct sales channels represent the fastest-growing distribution vector, while cereal formulations occupy mature shelf space in conventional supermarkets.
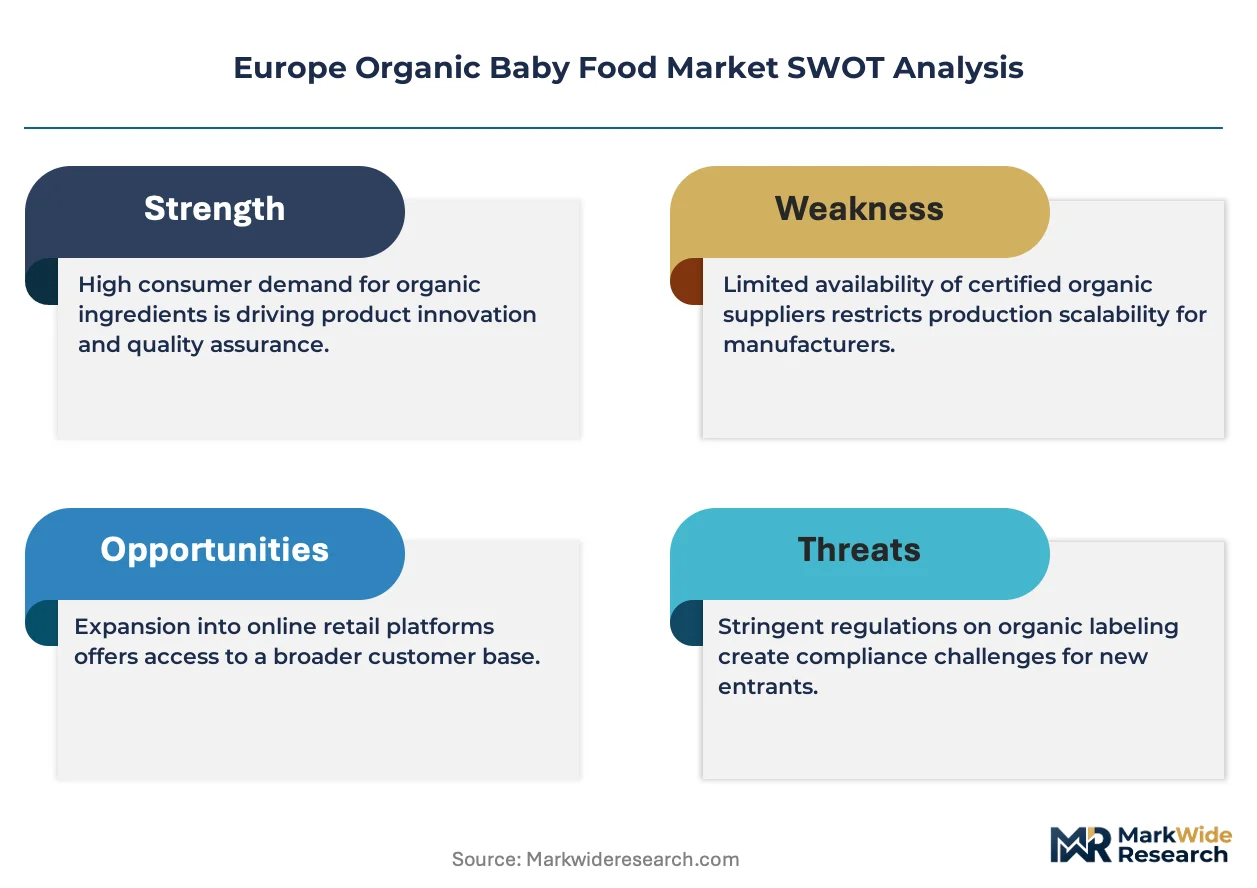
EMA and EFSA frameworks govern nutritional claim substantiation and infant formula composition across EU member states, while the EU Green Deal mandates recycled content thresholds in food packaging. These regulations elevate compliance costs for non-EU exporters and reward domestic producers with established certification infrastructure. Stakeholders must monitor forthcoming revisions to the EU Organic Regulation and packaging Extended Producer Responsibility schemes that will reshape cost structures and competitive barriers.
Market Dynamics
Millennial parent cohorts across Germany, France, and the United Kingdom are restructuring demand toward certified organic infant nutrition, compressing conventional formula shelf space while elevating compliance burdens under tightening EU packaging mandates.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds in food-grade materials are forcing incumbent manufacturers to redesign pouch and jar specifications, creating first-mover advantages for domestic producers with established circular supply partnerships.
- Biodynamic ingredient sourcing:Backward integration into controlled agricultural zones in Austria and southern Germany secures supply predictability for micronutrient-dense cereal formulations, insulating processors from conventional commodity volatility.
- Urban parent subscription adoption:Direct-to-consumer channels in London, Paris, and Berlin are capturing repeat purchase loyalty through personalized stage-based nutrition plans, reducing customer acquisition costs versus conventional retail.
Market Restraints
- Organic dairy input concentration:Biodynamic milk supply clusters in Alpine regions of Austria and Switzerland, exposing processors to weather-driven yield variability and limited supplier diversification.
- F-Gas Regulation refrigeration compliance:Cold-chain logistics retrofits for hydrofluorocarbon phase-out impose capital intensity on smaller regional distributors without scale economies.
- Glass jar cost premium:Energy-intensive container production and weight-driven freight economics disadvantage traditional packaging formats against flexible pouches in price-sensitive retail segments.
Strategic Opportunities
- Poland and Romania penetration gaps:Underdeveloped premium organic infant nutrition retail infrastructure in Warsaw and Bucharest urban corridors offers whitespace for pharmacy-direct and subscription entry before incumbent saturation.
- Extended Producer Responsibility schemes:Forthcoming EU packaging waste regulations will reward producers with take-back infrastructure, enabling margin recovery through recycled material arbitrage.
- Allergen-free formulation convergence:Integration of hydrolyzed protein technologies with organic certification protocols addresses growing parent demand for hypoallergenic stage-one nutrition in Nordic markets.
Industry Challenges
- EU Regulation 2018/848 certification timelines:Multi-year conversion periods for conventional agricultural suppliers to achieve organic status create ingredient procurement bottlenecks during demand surges.
- Biodynamic agronomist scarcity:Specialized expertise in Demeter-standard cultivation practices concentrates in German-speaking regions, constraining rapid supply expansion into southern and eastern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Baby Food Market |
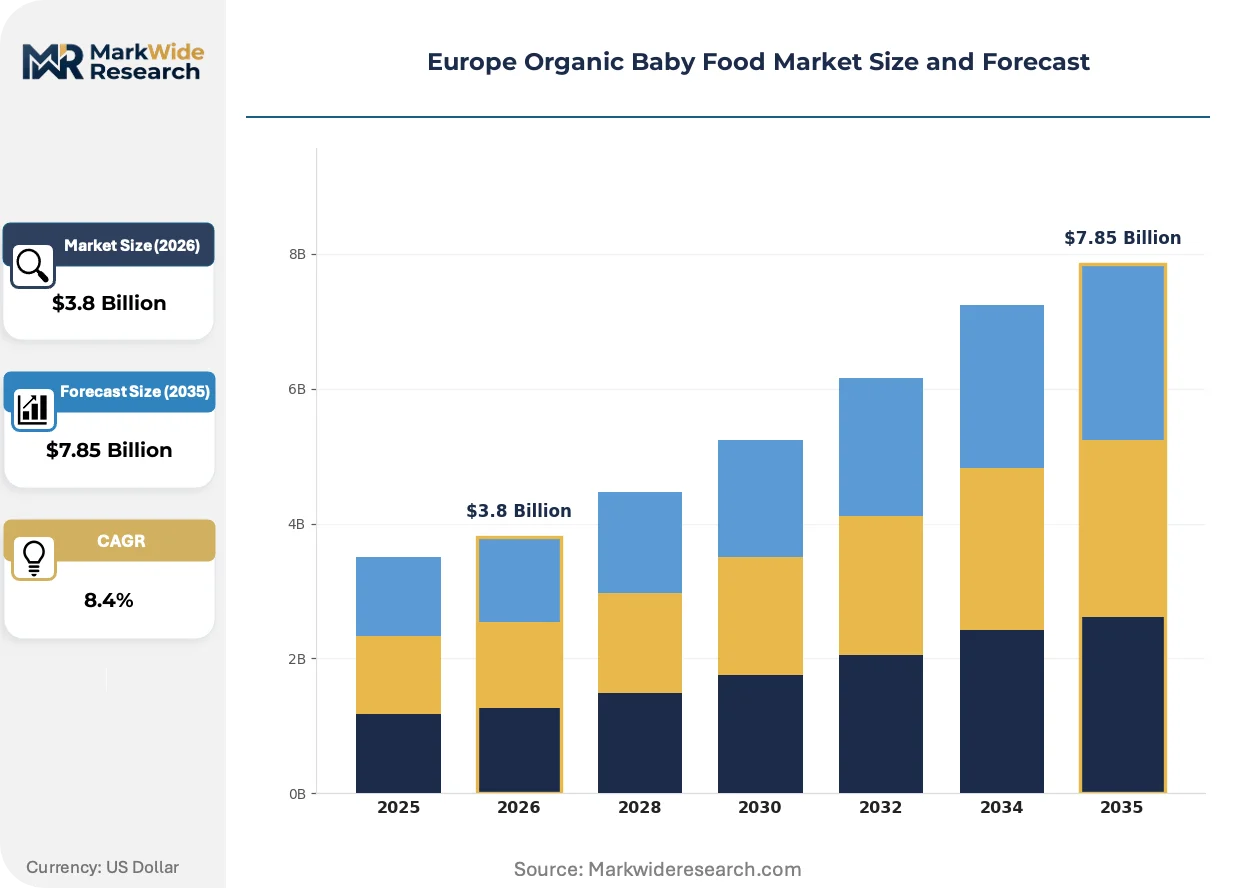
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereal, Snacks, Meals Packaging Type: Glass Jars, Pouches, Boxes, Tetra Packs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Age Group: Newborn, Infant, Toddler, Pre-School |
| Companies Covered | Nestlé S.A., Danone S.A., HiPP GmbH & Co. Vertrieb KG, Hero Group, Abbott Laboratories, Holle baby food AG, The Hain Celestial Group, Inc., FrieslandCampina, Arla Foods, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Baby Food Market Shifts & Advancements
Formulation science and packaging engineering are converging to reshape competitive positioning across European organic infant nutrition, with sustainability credentials and convenience functionality becoming inseparable purchase determinants for urban parent segments.
High-pressure processing technology is hybridizing thermal pasteurization protocols in ready-to-feed liquid formulations, preserving heat-sensitive micronutrients while extending ambient shelf stability. Premium pharmacy chains in Switzerland and France are adopting these formats for travel and nighttime feeding occasions. This convergence is compressing the traditional trade-off between nutritional integrity and logistical convenience that previously segmented glass jar and UHT liquid markets.
EU Green Deal packaging Extended Producer Responsibility frameworks are mandating minimum recycled content thresholds in flexible pouch laminates by 2030, forcing material science investment in food-grade rPET and aluminum barrier compatibility. Mid-tier processors without captive recycling partnerships face compliance cost escalation. German and French regulators are accelerating enforcement timelines, compressing supplier qualification windows for non-domestic exporters.
Subscription-based replenishment models are displacing conventional supermarket stock-up behavior among dual-income households in metropolitan France and the United Kingdom. Direct channels now capture recurring purchase commitments through algorithmic stage-transition prompts as infants advance from four-month cereals to twelve-month textured meals. This behavioral shift is most visible in Greater London and Île-de-France, where pharmacy and specialty retail foot traffic for routine restocking has declined measurably.
Europe Organic Baby Food Market Segmentation
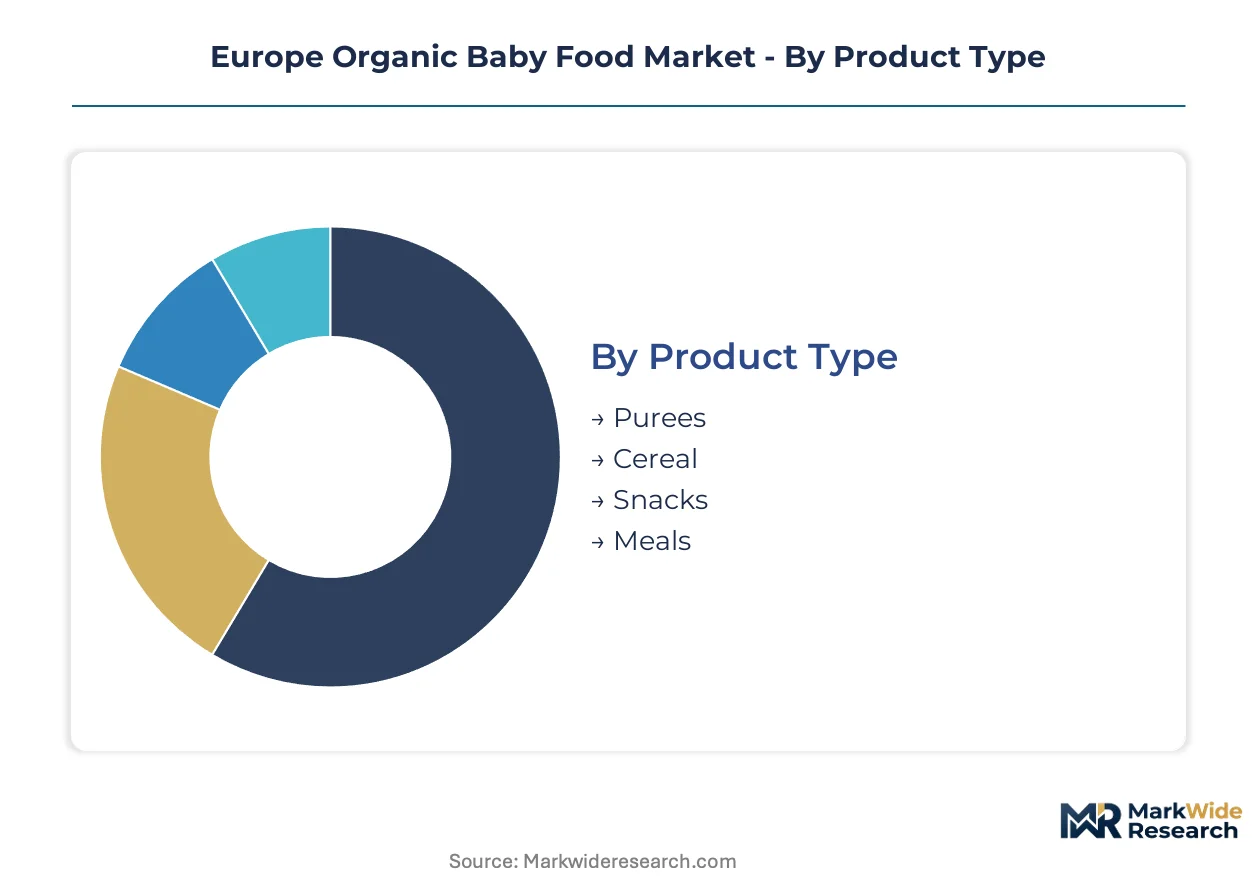
Segmentation in European organic infant nutrition reveals how purchasing decisions split across convenience priorities, sustainability credentials, and developmental timing. Manufacturers configure their portfolios around these fracture lines to capture recurring revenue from subscription cohorts while managing compliance costs under divergent packaging mandates.
Product Type:
Mature shelf-stable formats coexist with emerging fresh-refrigerated lines as parents balance nutritional density against preparation convenience across feeding stages.
- Purees:Single-ingredient and multi-fruit vegetable blends processed through high-pressure pasteurization retain heat-sensitive vitamins for four-to-eight-month infants. Demand clusters in French pharmacy chains and German biodynamic retail where Demeter-certified SKUs command shelf prominence.
- Cereal:Iron-fortified rice and oat formulations serve as traditional first foods, though growth has flattened in Nordic markets where parents bypass cereals for baby-led weaning approaches. Austrian and Swiss processors dominate organic dairy-cereal combinations through captive milk supply.
- Snacks:Puffed rice, teething biscuits, and fruit bars targeting mobility-stage toddlers.
- Meals:Complete protein-vegetable-carbohydrate combinations for twelve-month-plus transition to family eating patterns.
Purees handle the majority of throughput; meals are expanding most quickly on share as parents seek convenience in later feeding stages.
Packaging Type:
Cost tier differentiation separates premium positioning from mass-market accessibility, with material choice directly signaling organic authenticity to parent purchasers.
- Glass Jars:Inert borosilicate containers preserve flavor integrity for premium gifting occasions and pharmacy-channel positioning in Switzerland and France. Energy-intensive production and weight-driven logistics constrain expansion beyond affluent urban corridors.
- Pouches:Flexible multilayer laminates with spout closures dominate convenience-oriented purchasing through subscription channels in Greater London and Île-de-France. EU Green Deal recycled-content mandates are forcing material requalification across German and French supply bases.
- Boxes:Dry cereal and snack formats utilizing paperboard with moisture barriers.
- Tetra Packs:Aseptic cartons for ready-to-feed liquid formulations in travel and nighttime feeding occasions.
Pouches capture the volume lead; Tetra Packs are climbing the fastest as high-pressure processing extends ambient-stable liquid availability.
Distribution Channel:
Customer type fragmentation separates routine replenishment behavior from discovery-driven trial purchases across urban household segments.
- Supermarkets:Conventional grocery retains cereal and jar dominance in price-sensitive segments, though shelf space compression is accelerating as retailers prioritize faster-turning conventional SKUs.
- Online Retail:Algorithmic subscription platforms in Berlin, Paris, and London capture stage-transition loyalty through automated replenishment prompts as infants advance feeding milestones.
- Specialty Stores:Biodynamic-focused independents in German-speaking regions.
- Direct Sales:Pharmacy partnerships and manufacturer-owned channels in Swiss and French premium positioning.
Supermarkets retain the throughput base; online retail is gaining share fastest through recurring purchase lock-in.
Age Group:
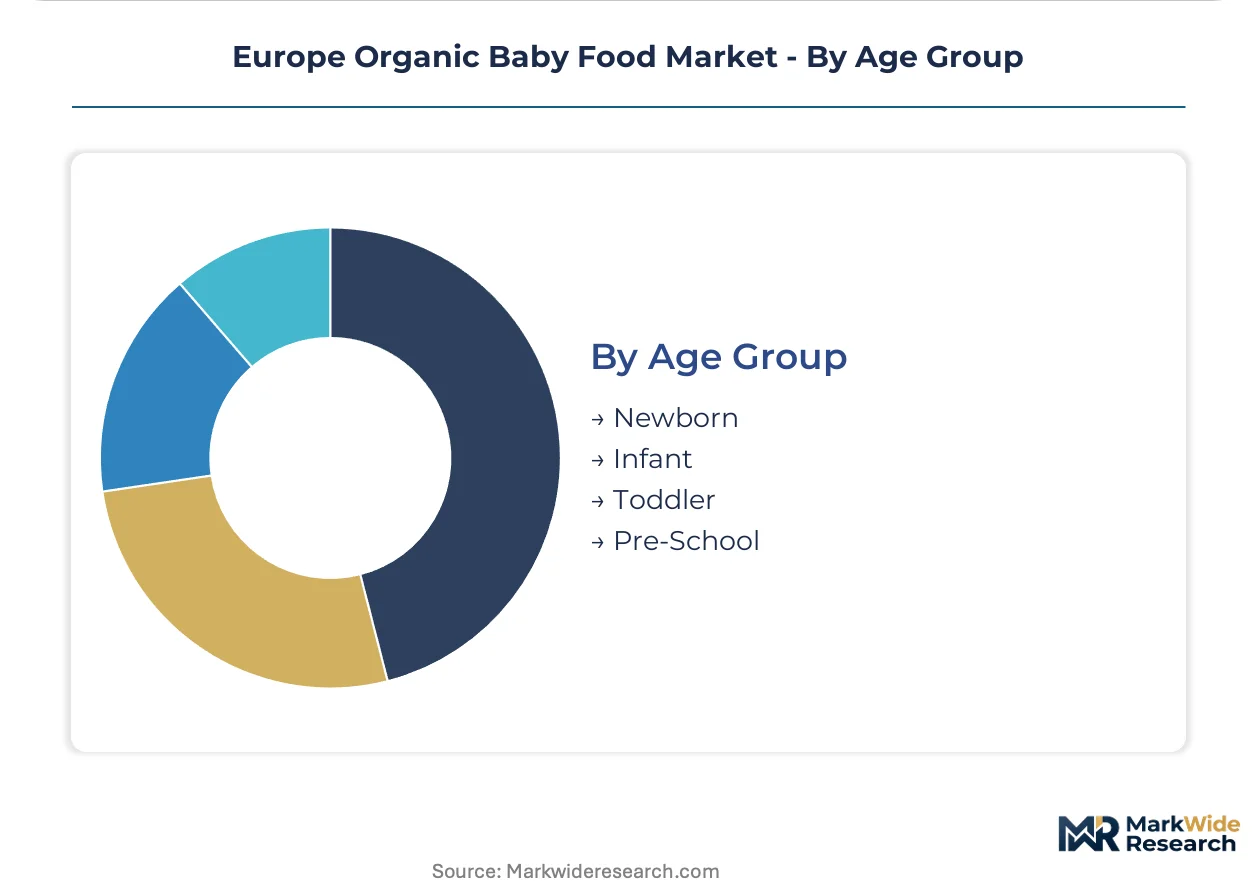
Application progression from single-ingredient introduction through textured family-food transition structures formulation R&D priorities and micronutrient fortification protocols.
- Newborn:Organic infant formula and early complementary foods for zero-to-four-month nutritional foundation, governed by EFSA compositional standards and EMA nutritional claim oversight.
- Infant:Four-to-twelve-month purees and cereals represent the commercial core, with allergen-free and hydrolyzed protein variants capturing parent anxiety in Nordic markets.
- Toddler:Twelve-to-thirty-six-month textured meals and finger foods.
- Pre-School:Three-plus years organic meal solutions for nursery and school-lunch occasions.
Infant-stage products anchor revenue concentration; pre-school formulations are expanding most quickly as manufacturers extend customer lifetime value beyond traditional category exit points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network connects Dutch distribution hubs to Swiss precision manufacturing zones, underwriting northern Europe's role as the primary logistics backbone for temperature-sensitive organic infant nutrition shipments.
Germany
Millennial parents in Berlin and Munich are restructuring purchasing toward Demeter-certified biodynamic formulations. EFSA nutritional claim substantiation requirements govern all stage-based micronutrient fortification declarations. The Baden-Württemberg agricultural cluster around Stuttgart supplies captive organic dairy inputs to processors with backward integration into controlled cultivation zones.
France
Urban households in Greater Paris and Lyon are adopting subscription-based replenishment models for stage-transition nutrition plans. ANSM pharmacy-channel regulations elevate compliance burdens for non-EU exporters seeking premium positioning. The Île-de-France logistics hub concentrates cold-chain distribution infrastructure for refrigerated ready-to-feed formulations.
United Kingdom
Dual-income families in London and the Southeast are compressing conventional supermarket shelf space through algorithmic direct-to-consumer platforms. UK REACH chemical safety standards intersect with EU Green Deal packaging mandates for imported organic infant foods. The M25 distribution ring hosts specialized fulfillment centers for temperature-controlled subscription deliveries.
Switzerland
Affluent parent cohorts in Zurich and Geneva sustain demand for glass-jar premium gifting formats despite logistics cost premiums. Swissmedic pharmaceutical-grade manufacturing standards attract allergen-free formulation specialists seeking regulatory credibility. The Swiss Plateau organic dairy belt supplies biodynamic milk concentrates to adjacent Alpine processing facilities.
Poland
Emerging middle-class households in Warsaw and Krakow represent whitespace for pharmacy-direct entry before incumbent saturation. EU Regulation 2018/848 certification timelines create procurement bottlenecks for conventional agricultural suppliers seeking organic conversion. The Silesian logistics corridor offers distribution reach into underdeveloped premium retail infrastructure across central-eastern Europe.
Europe Organic Baby Food Market Competitive Landscape
On the supply side, the industry is consolidating around processors with captive biodynamic ingredient sourcing and established circular packaging partnerships. Tiered competitive dynamics separate multinational nutrition conglomerates from regional biodynamic specialists and private-label aggregators. Dominant competitive moves include backward integration into controlled agricultural zones and strategic pharmacy-channel distribution partnerships in premium positioning markets.
Among Swiss and German biodynamic specialists, Holle baby food AG and HiPP GmbH & Co. Vertrieb KG exemplify the regional archetype of processors with Demeter-standard cultivation expertise and Alpine dairy supply concentration. Nestlé S.A. represents the diversified nutrition conglomerate tier with controlled distribution infrastructure spanning multiple premium retail channels. These three anchors illustrate how competitive positioning splits between provenance-authenticated regional players and scale-driven portfolio operators.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| HiPP GmbH & Co. Vertrieb KG |
| Hero Group |
| Abbott Laboratories |
| Holle baby food AG |
| The Hain Celestial Group, Inc. |
| FrieslandCampina |
| Arla Foods |
| Others |
Supply & Pricing Matrix
Biodynamic milk supply concentration in Alpine Austria and Switzerland determines both tier spreads and supply chain configuration, compressing margins for non-integrated processors while rewarding Demeter-certified operators with captive dairy sourcing and pharmacy-channel pricing power.
Pricing Analysis
Volume-discount tiering structures separate pharmacy-direct premium positioning from mass-market subscription penetration, with Demeter certification commanding shelf-space premiums in German biodynamic retail. Price differentiation hinges on organic certification grade and backward integration depth, with hydrolyzed protein and allergen-free variants sustaining margin pools in Nordic markets. Cost compression in conventional pouch formats intensifies as EU Green Deal recycled-content mandates escalate material requalification expenses. Urban subscription cohorts in London and Paris exhibit lowest price sensitivity, while Polish and Romanian mass-market entrants face acute margin pressure from freight-weighted glass jar logistics.
Supply Chain Analysis
Contract-manufacturing concentration rests with Austrian and Swiss dairy processors holding captive biodynamic milk supply, supplemented by German ingredient specialists with Demeter-standard cultivation expertise. Raw material dependencies center on Alpine organic milk concentrates, Demeter-certified cereal grains, and food-grade rPET for pouch laminate compliance. Single-source vulnerability pervades biodynamic agronomist scarcity in German-speaking regions, constraining rapid supply expansion. Distribution runs through Rhine-Alpine freight corridors connecting Dutch hubs to Swiss precision manufacturing zones, with cold-chain specialization for refrigerated ready-to-feed formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services are expanding faster than conventional retail hardware, creating service-attach opportunities through algorithmic stage-transition nutrition planning and recurring revenue capture.
For Market Incumbents: Entrench pharmacy-channel control in France and Switzerland through ANSM compliance investment, while deepening backward integration into Baden-Württemberg organic dairy zones to offset biodynamic milk supply volatility. Prioritize circular packaging partnerships ahead of Extended Producer Responsibility enforcement to recover margin through recycled material arbitrage. For New Entrants and Emerging Players: Build out pharmacy-direct infrastructure in Warsaw and Bucharest urban corridors before incumbent saturation, targeting underdeveloped premium organic infant nutrition retail with EU Regulation 2018/848-certified sourcing. Leverage allergen-free formulation convergence with hydrolyzed protein technologies to penetrate Nordic markets with hypoallergenic stage-one positioning. For Investors and Strategic Acquirers: EU Green Deal packaging mandates reshape the acquisition landscape toward processors with established circular supply partnerships and food-grade rPET qualification timelines. Five-to-ten-year viability favors Demeter-certified regional specialists with Alpine dairy captive supply over conventional organic label aggregators. Monitor enforcement acceleration in German and French recycled-content thresholds as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodynamic Dairy | Alpine milk supply concentration insulates processors from weather-driven yield volatility. |
| Direct-to-Consumer Subscription Launch | Algorithmic stage-transition prompts capture recurring loyalty in Greater London and Île-de-France. |
| Circular Packaging Partnership Formation | Extended Producer Responsibility schemes reward take-back infrastructure with margin recovery. |
| Allergen-Free Formulation Development | Hydrolyzed protein integration addresses parent anxiety in Nordic pharmacy channels. |
| Pharmacy-Channel Distribution Expansion | ANSM regulations elevate barriers for non-EU exporters seeking Swiss and French premium positioning. |
Research Methodology
A standing panel of brand managers, category buyers at pharmacy chains, biodynamic agronomists, and cold-chain logistics operators provided ongoing calibration against secondary validation from EFSA nutritional claim filings, EU Organic Regulation compliance databases, Nielsen retail audit data, and Rhine-Alpine freight corridor customs records. Bottom-up volume triangulation across product-type and packaging-format segments converged with top-down value estimates from subscription-platform revenue disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning puree-cereal-snack-meal categories, pouch-jar-box-Tetra Pack formats, and newborn-infant-toddler-pre-school age groups. CAGRs derived from stage-transition purchase velocity and urban household subscription adoption curves, incorporating EMA regulatory timeline risks and biodynamic supply expansion constraints as sensitivity inputs.
Sensitivities concentrate around EU Organic Regulation revision timelines, Alpine dairy yield volatility, and recycled-content mandate enforcement acceleration. Forecasts reflect documented assumptions on parent cohort purchasing shift persistence and pharmacy-channel regulatory stability. Quarterly review of Demeter certification conversion rates and Extended Producer Responsibility scheme implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market