
 Disposable Medical Supplies Market | 2026-2036
Disposable Medical Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Medical Supplies Market Intelligence
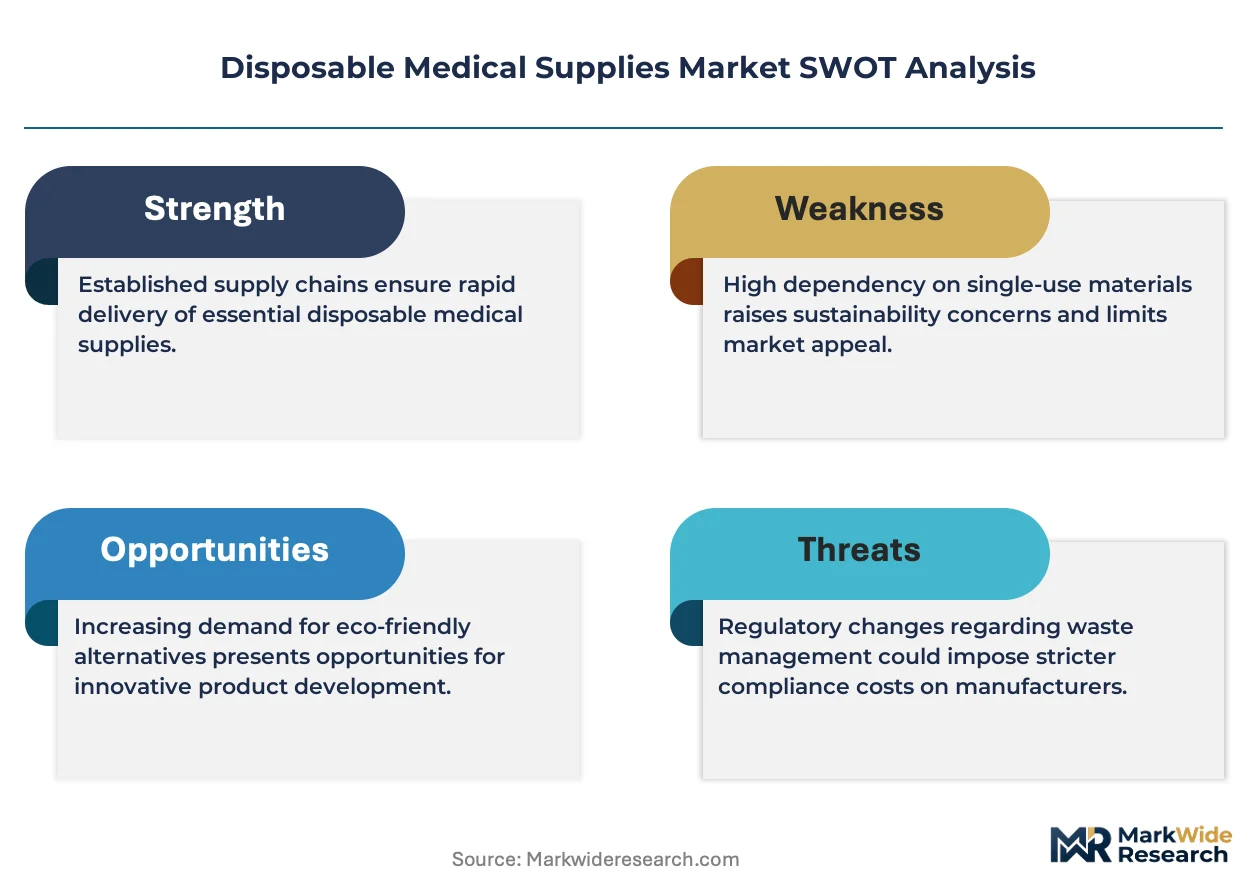
The substitution of traditional PVC with non-phthalate plasticizers and alternative polymers like polypropylene in items such as IV bags and tubing is expanding material options for manufacturers. B. Braun SE leverages its expertise in infusion therapy to develop PVC-free product lines. Baxter International sustains a strong market presence through its large-scale production of essential hospital products, while 3M differentiates through its focus on adhesive-based dressings.
Disposable medical supplies encompass single-use items designed to prevent cross-contamination and ensure patient safety in clinical settings. These products are often manufactured from medical-grade polymers or non-woven fabrics and sterilized using methods like ethylene oxide (EtO) or gamma irradiation. While syringes and catheters constitute high-volume product categories, advanced wound care dressings and items for surgical procedures offer higher margin potential. Demand is driven by end users like hospitals and ambulatory surgical centers for infection control.
Product market access is governed by stringent regulatory frameworks, such as the US FDA's premarket clearance pathways and the European Union's Medical Device Regulation (MDR). These standards, along with those from China's NMPA, dictate material safety, labeling, and quality system requirements. Successfully navigating these disparate and evolving compliance landscapes remains a critical competency for all market participants.
Market Dynamics
The market's structure is defined by the dual pressures of stringent infection control protocols demanding single-use products and growing environmental scrutiny over polymer waste. This dynamic forces manufacturers to innovate in materials science while navigating complex global regulations for product safety and market access.
Growth Catalysts
- EU Medical Device Regulation (MDR):The MDR's emphasis on material traceability and post-market surveillance elevates quality standards, favoring suppliers with robust quality management systems and creating a barrier for non-compliant products.
- Ambulatory Surgical Center (ASC) Expansion:The shift of surgical procedures to outpatient settings, particularly in the US, increases the consumption of procedural kits, drapes, and other single-use items tailored for high-turnover environments.
- Healthcare Infrastructure in China:Government investment in expanding hospital capacity and primary care clinics across China creates a significant and sustained new source of volume demand for fundamental supplies like syringes and catheters.
Market Restraints
- Polymer Resin Price Volatility:Fluctuations in the cost of medical-grade polymers like PVC and polypropylene, tied to petrochemical markets, directly impact manufacturer margins and can lead to pricing instability for end-users.
- Sterilization Method Scrutiny:Increased regulatory oversight by bodies like the US EPA on ethylene oxide (EtO) emissions creates compliance costs and operational risks, forcing investment in alternative sterilization methods.
- Reusable Device Advancement:The development of durable, easily sterilizable surgical instruments and diagnostic tools made from advanced metals presents a substitution threat in specific high-cost procedural categories.
Strategic Opportunities
- Southeast Asian Market Entry:Rapidly urbanizing countries with rising healthcare expenditures, such as Vietnam and Indonesia, represent underpenetrated markets for advanced wound care and specialized surgical disposables.
- Home Healthcare Kits:An aging global population creates an opportunity for customized disposable kits for chronic disease management, post-operative care, and remote patient monitoring consultations.
- Direct-to-Clinic E-commerce Platforms:Digital sales channels that bypass traditional group purchasing organizations allow manufacturers to reach smaller clinics and ASCs directly, offering greater pricing transparency.
Industry Challenges
- Disparate Global Labeling Standards:Harmonizing product labeling and Unique Device Identification (UDI) requirements across the US FDA, EU MDR, and China's NMPA systems adds significant administrative overhead and delays market access.
- Non-Woven Fabric Supply Concentration:Dependence on a limited number of suppliers for critical non-woven materials, primarily centered in Asia, exposes the supply chain to geopolitical risks and potential bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Medical Supplies Market |
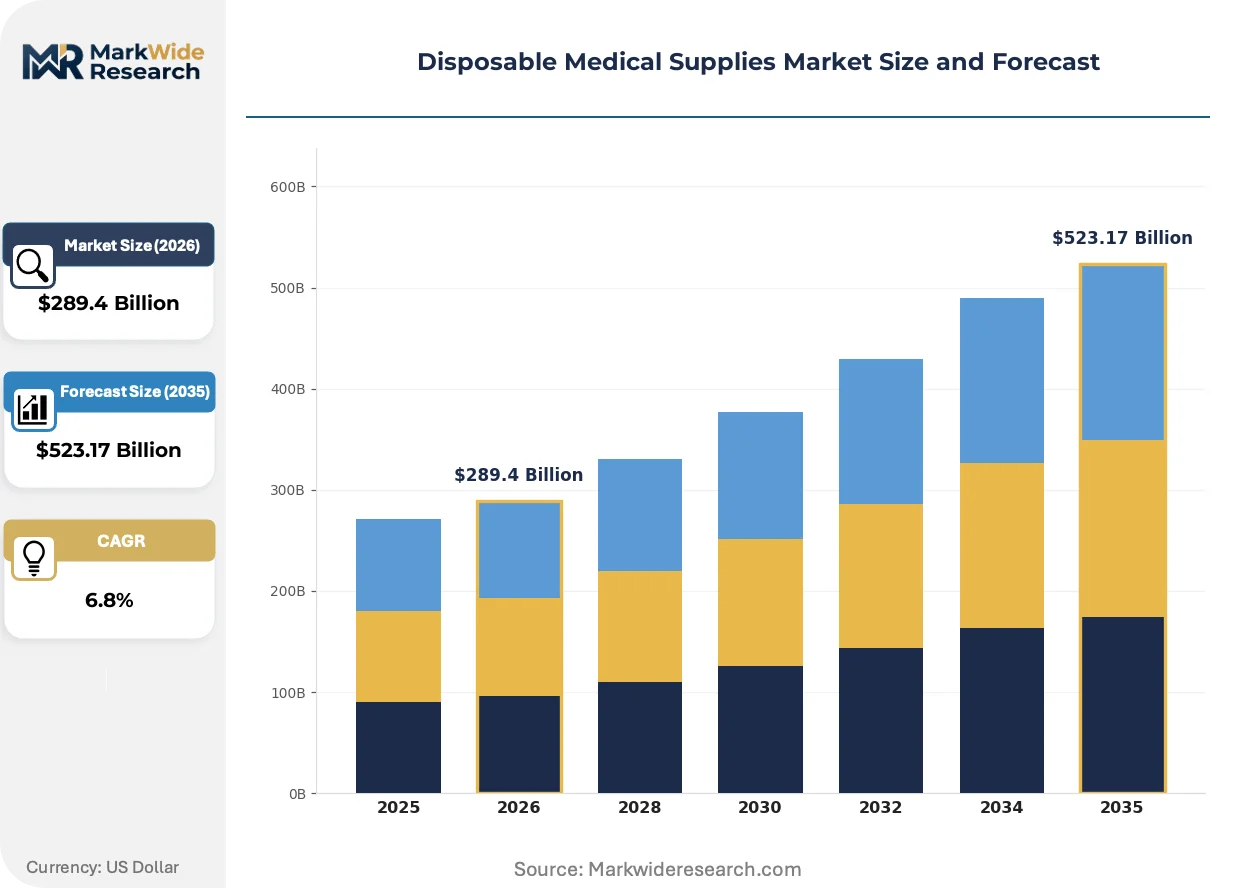
| Market Size in 2026 | $289.4 Billion |
| Market Size in 2035 | $523.17 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Syringes, Catheters, Dressings, Surgical Gowns, Face Masks Application: Wound Care, Injection & Infusion, Infection Control, Surgical Procedures, Diagnostic Testing, Critical Care End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers, Emergency Care Units, Specialty Clinics Packaging Type: Individual Packs, Bulk Packs, Sterile Packaging, Non-Sterile Packaging, Reclosable Bags, Blister Packs |
| Companies Covered | Medline Industries, Medtronic, Johnson & Johnson, B. Braun SE, Baxter International, Cardinal Health, 3M, Teleflex, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Medical Supplies Market Strategic Shifts & Innovations
Material innovation is the central theme, driven by a need to balance clinical performance with environmental responsibility. This shift influences everything from raw material sourcing for IV bags to end-of-life considerations for complex surgical kits, reshaping competitive positioning for manufacturers.
Smart polymer technology, which can change properties in response to stimuli, is being integrated into advanced wound dressings. Adoption is currently highest in specialized hospital units focused on chronic wound management. This advanced material science is converging with micro-sensor technology to create dressings that can actively monitor wound status and signal the need for a change.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates comprehensive reporting on environmental and social impacts across the value chain. This regulation forces medical device manufacturers to quantify the lifecycle footprint of disposable products, from raw material extraction to disposal. The directive most affects companies with significant European sales, pushing them to adopt circular economy principles and seek recyclable or bio-based polymers.
Hospital value analysis committees are shifting their focus from simple unit price to a total cost of ownership model. This model evaluates disposables based on factors like reduced infection risk, procedural efficiency, and waste disposal costs, challenging suppliers who compete only on price. This procurement behavior is most prominent within large hospital networks in North America and Western Europe.
Disposable Medical Supplies Market Segmentation
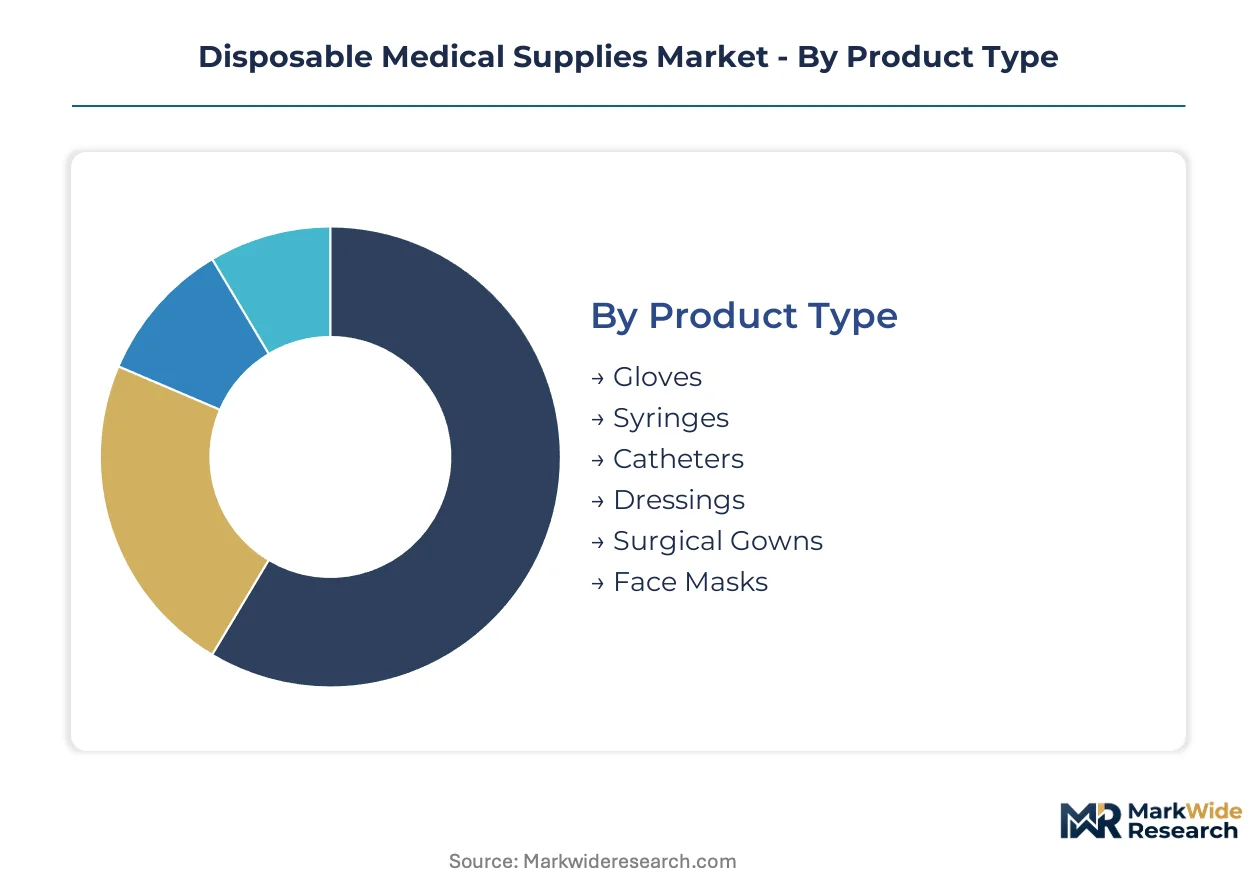
The Disposable Medical Supplies Market is intricately segmented, reflecting the diverse clinical needs and regulatory requirements across healthcare settings. Understanding these distinct segments illuminates varying demand patterns, procurement behaviors, and the specific material science innovations necessary for competitive differentiation within this vital industry.
Product Type:
Regulatory approvals from bodies like the US FDA, EU MDR, and China's NMPA impose significant certification burdens, particularly on complex product types within this segment.
- Syringes:Disposable devices for medication delivery or fluid aspiration. Demand is high in hospitals and vaccination programs, driven by sterile, single-use injection needs.
- Catheters:Flexible tubes inserted into body cavities for medical procedures. Complex design and patient contact require rigorous material safety validation across global regulators.
- Gloves:Barrier protection from latex, nitrile, or vinyl for infection control.
- Dressings:Materials like gauze and advanced wound care products for wound protection.
- Surgical Gowns:PPE creating a sterile barrier during surgery, often non-woven.
- Face Masks:Respiratory protective devices preventing airborne pathogen transmission.
Gloves sit at the top of the volume ranking, with Face Masks climbing the fastest.
Application:
The commercial attractiveness of each application segment varies significantly, directly correlating with the complexity of the procedures and the specialized nature of the disposable products required.
- Surgical Procedures:Encompasses disposables like drapes, gowns, and specialized kits for operating rooms. Demand is high in hospitals and ASCs, driven by increasing surgical volumes.
- Critical Care:Products supporting ICU patients, like breathing circuits and feeding tubes. These high-value items require advanced material science for severe patient conditions.
- Wound Care:Products for managing acute and chronic wounds, from basic to advanced dressings.
- Injection & Infusion:Includes syringes, needles, IV bags, and administration sets for fluid delivery.
- Infection Control:Covers items like gloves, masks, and disinfectants, crucial for pathogen prevention.
- Diagnostic Testing:Disposable components such as blood tubes and swabs for laboratory diagnostics.
Demand for Injection & Infusion remains foundational, while Surgical Procedures sees significant expansion.
End User:
The procurement models and volume requirements differ substantially across end-user segments, influencing distribution strategies and product customization for manufacturers.
- Hospitals:Largest consumers of disposables, requiring a vast range of products. Group purchasing organizations facilitate procurement for large networks, emphasizing bulk orders.
- Ambulatory Surgical Centers:ASCs specialize in outpatient procedures, driving demand for efficient procedural kits. Focus on cost-effectiveness influences product design.
- Diagnostic Laboratories:Utilize disposables for specimen collection, processing, and testing.
- Home Healthcare Providers:Supply patients with disposables for chronic disease management.
- Emergency Care Units:Rely on critical disposables for immediate patient stabilization.
- Specialty Clinics:Include dental, ophthalmology, and dermatology clinics, requiring specific disposables.
Hospitals continue to be the primary consumer, with Home Healthcare Providers representing an expanding segment.
Packaging Type:
The functional purpose of packaging directly impacts product integrity and patient safety, driving specific design and material choices for each disposable item.
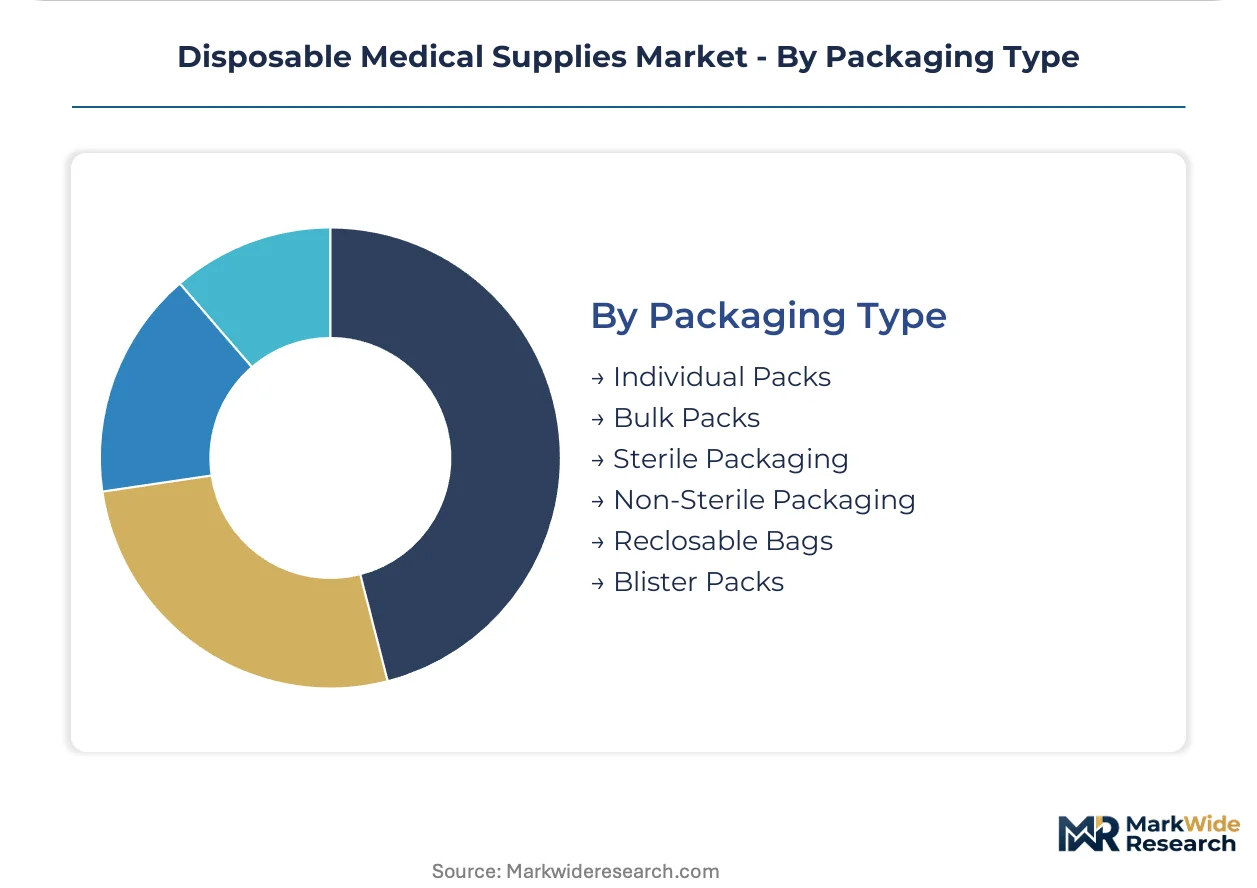
- Sterile Packaging:Designed to maintain product sterility until use, employing barrier films. Critical for invasive procedures, with validation mandated by regulators.
- Individual Packs:Single-unit packaging prevents cross-contamination, ensuring sterility for one-time use. Preferred in ambulatory surgical centers for efficiency and waste reduction.
- Bulk Packs:Multiple non-sterile units grouped for cost-efficiency and high-volume usage.
- Non-Sterile Packaging:For products not requiring sterility, focusing on protection and dispensing.
- Reclosable Bags:Flexible solutions allowing multiple access points to non-sterile items.
- Blister Packs:Rigid plastic with a lidding seal, protecting small, often sterile, components.
Sterile Packaging is foundational for clinical safety, as Individual Packs gain traction for outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States' advanced medical device manufacturing hub drives significant innovation and consumption in disposable medical supplies. This market thrives on stringent regulatory standards and a vast healthcare infrastructure. Key regions worldwide contribute distinct demand patterns and manufacturing capabilities.
United States
Demand for surgical disposables and advanced wound care products propels the US market. The US FDA's premarket clearance pathways govern product market access for manufacturers. Major medical technology clusters around Boston and California foster material science innovations for complex disposables.
Germany
Germany's robust hospital network and aging population sustain a strong demand for injection and infusion products. The European Union's Medical Device Regulation (MDR) sets high standards for material traceability and quality. The Rhine-Main region concentrates specialized medical device manufacturers focused on high-value disposables.
China
Healthcare infrastructure expansion across China generates substantial volume demand for essential supplies like syringes and catheters. China's NMPA regulations dictate material safety and labeling requirements for all imported and domestic products. Industrial zones in the Yangtze River Delta are focal points for large-scale production and distribution.
India
India's expanding healthcare access and rising surgical volumes increase the need for cost-effective disposable medical supplies. The CDSCO governs medical device approvals and quality standards for products entering the Indian market. Manufacturing hubs in Gujarat and Maharashtra are developing capabilities for basic and advanced disposables.
Japan
An aging population and advanced medical practices drive demand for high-quality, specialized disposables in Japan. The PMDA ensures rigorous safety and efficacy standards for all medical devices. The Kanto region, including Tokyo, hosts research and development centers for innovative disposable technologies.
Disposable Medical Supplies Market Key Industry Players
Global majors compete with regional champions across product breadth and specialized offerings. The market structure exhibits consolidation among top-tier players for high-volume products, alongside fragmentation for niche or advanced disposables. Strategic archetypes include diversified conglomerates, specialized innovators, and cost-efficient volume producers. Dominant competitive moves involve portfolio diversification and geographic expansion into emerging markets.
At the scale-driven end, Baxter International sustains a strong market presence through its large-scale production of essential hospital products. B. Braun SE exemplifies a specialized innovator, leveraging its expertise in infusion therapy to develop PVC-free product lines. 3M occupies a position as a differentiated player, focusing on adhesive-based dressings and other advanced medical solutions. These companies anchor different segments through their distinct operational models and product focuses, reflecting varied strategies for market penetration.
| Leading Market Players |
|---|
| Medline Industries |
| Medtronic |
| Johnson & Johnson |
| B. Braun SE |
| Baxter International |
| Cardinal Health |
| 3M |
| Teleflex |
| BD |
| Others |
Cost & Logistics Intelligence
Skilled labor concentration in specialized medical device manufacturing hubs, such as those in Germany and the US, influences pricing-tier spreads for complex disposables. This labor cost differential impacts product categories requiring precision assembly and advanced material science.
Pricing Analysis
Input-cost pass-through remains a significant factor for disposable medical supplies manufacturers. The dominant pricing structure involves contract-based long-term offtake agreements with large hospital networks and group purchasing organizations. Price differentiation stems from product complexity, such as advanced wound care dressings, and certification levels, like specific EU MDR compliance. Pricing softness runs through high-volume, commoditized products due to intense competition. Hospitals, driven by budget constraints, represent the most price-sensitive buyer segment, while specialty clinics prioritize performance over initial cost.
Supply Chain Analysis
Workforce availability in manufacturing geographies like China, India, and Mexico underpins the production capacity for many disposable medical supplies. The supply chain draws heavily from medical-grade polymers, non-woven fabrics, and sterilization chemicals. Single-source vulnerability for specialized components, particularly in advanced diagnostics, presents a structural risk. Distribution runs through a dual model, with large-scale group purchasing organizations handling bulk hospital procurement and direct-to-clinic e-commerce platforms serving smaller ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, as demand shifts toward premium specifications driven by stringent regulatory frameworks and patient safety mandates.
For Market Incumbents: Cement market leadership through strategic investment in material innovation, particularly bio-based and recyclable polymers, to mitigate growing environmental scrutiny. Expand manufacturing capacity in geographies with stable labor and energy costs to counter polymer resin price volatility. Defend against reusable device advancement by emphasizing superior infection control and procedural efficiency for single-use items. Focus on R&D for smart polymer technology in high-margin advanced wound care.
For New Entrants and Emerging Players: Enter via specialized product niches, such as home healthcare kits tailored for chronic disease management. Target underpenetrated Southeast Asian markets for advanced wound care and specialized surgical disposables, where healthcare expenditures are rising. A viable go-to-market angle involves leveraging direct-to-clinic e-commerce platforms to bypass established distribution channels and offer greater pricing transparency to smaller facilities.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirers in this space, seeking to expand their product portfolios. The long-term viability of the disposable medical supplies market remains strong over the next five to ten years, driven by aging populations and healthcare infrastructure expansion. Acquisition target archetypes include specialized innovators with robust intellectual property in sustainable materials or advanced monitoring technologies. A key signal to watch is the adoption rate of alternative sterilization methods beyond ethylene oxide, indicating future compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Polymers | Reduces environmental footprint and aligns with EU CSRD mandates for sustainable product development. |
| Expand Manufacturing in Southeast Asia | Captures new volume demand from rapidly urbanizing countries with rising healthcare expenditures. |
| Develop Smart Wound Dressings | Addresses complex patient needs and offers higher margin potential through advanced material science. |
| Strengthen Regulatory Compliance Teams | Ensures seamless market access across disparate global standards like US FDA and EU MDR. |
| Acquire Niche Technology Innovators | Enhances portfolio with specialized solutions and intellectual property for future growth segments. |
Research Approach
Direct dialogue with hospital procurement managers, clinicians, regulatory affairs leads, and GPO contract managers formed the qualitative grounding for this analysis. This primary research was complemented by secondary validation from sources including US FDA filings, EU MDR documentation, China NMPA reports, and medical industry journals. The study employed both bottom-up and top-down triangulation to ensure robust data integrity.
A bottom-up analytical lens was applied to estimate market size and growth, aggregating data from key product types, applications, and end-user segments across the analysis window. Segmentation dimensions modeled included product type, application, end user, packaging type, and key geographies. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected based on factors like healthcare expenditure growth and surgical procedure volumes.
Inputs from regulatory body publications and industry association reports were available through the study window; gaps in real-time polymer supply chain data introduce uncertainty bands. Forecasts reflect assumptions regarding healthcare policy stability and technological advancement. Material deviation in new sterilization regulations or significant polymer supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Swab Cups Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Medical Liners Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Trach Care Trays Market