
 Multi-Core Processors Market | 2026-2036
Multi-Core Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Core Processors Market Outlook
Software-defined feature licensing is expanding how semiconductor vendors monetize multi-core silicon beyond the initial hardware sale. Intel Corporation leverages its foundry partnerships to sustain manufacturing scale across x86 and emerging process nodes. NVIDIA Corporation anchors data center revenue through CUDA-locked GPU core architectures that command premium positioning. Qualcomm Technologies Inc. competes in mobile SoC integration by controlling 5G modem-to-application processor connectivity at the die level.
Multi-core processors integrate multiple independent processing units onto a single semiconductor die, typically fabricated at process nodes below 7nm where transistor density enables parallel thread execution across shared cache hierarchies. These devices serve commercial and industrial purposes by accelerating concurrent workloads in servers, smartphones, automotive ECUs, and embedded controllers. ARM architecture dominates mobile and embedded deployments where power efficiency constrains thermal budgets, while x86 retains structural margin pools in enterprise data centers and cloud infrastructure. System-on-Chip integration represents the fastest-growing configuration as automotive and telecom OEMs consolidate discrete functions onto unified die designs.
FDA oversight affects medical device processors through electromagnetic compatibility and software validation requirements, while FCC Part 15 rules constrain radio-integrated multi-core systems in consumer electronics. EPA energy efficiency standards and EU RoHS substance restrictions shape material selection and power-state management in processor design. Stakeholders must monitor how sovereign chip subsidies and export control classifications on advanced lithography equipment redirect supply chain investments and alter competitive access to leading-edge fabrication.
Market Dynamics
Leading-edge wafer fabrication capacity concentrates in Taiwan, South Korea, and the United States, creating chokepoints where EU Chips Act subsidies and export controls on lithography equipment redirect investment flows and reshape competitive access to advanced nodes.
Growth Catalysts
- EU Chips Act subsidies:Sovereign semiconductor programs redirect fabrication investments toward domestic foundry capacity in Europe, expanding regional multi-core supply security.
- Cloud infrastructure scaling:Service providers deploy high core-count silicon for concurrent workload acceleration, pulling demand for parallel thread execution architectures.
- Automotive ECU consolidation:OEMs integrate discrete functions onto unified die designs, driving System-on-Chip configurations as the fastest-growing processor category.
Market Restraints
- Advanced lithography equipment access:Export control classifications on EUV systems constrain foundry expansion beyond existing clusters in Taiwan and South Korea.
- Sub-7nm process node cost structure:Transistor density scaling requires exponential capital intensity at each successive node, elevating break-even volume thresholds.
- ARM architecture substitution in data centers:Power-efficient designs encroach on x86 structural margin pools as cloud operators optimize thermal budgets.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives attract assembly and testing investments for mobile and embedded multi-core processors.
- 5G modem-to-AP die-level integration:Telecom OEMs demand unified connectivity and compute silicon, creating white space for advanced packaging expertise.
- Medical device processor certification:FDA electromagnetic compatibility requirements create premium positioning for validated multi-core designs in diagnostic equipment.
Industry Challenges
- Packaging and thermal engineering talent scarcity:Advanced 3D stacking and heterogeneous integration outpace specialized workforce development.
- Legacy x86 software stack compatibility:Enterprise data center migration to alternative architectures encounters friction from decades of accumulated code dependencies.
- Multi-jurisdiction certification timelines:FDA, EMA, and PMDA validation requirements for safety-critical applications extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Core Processors Market |
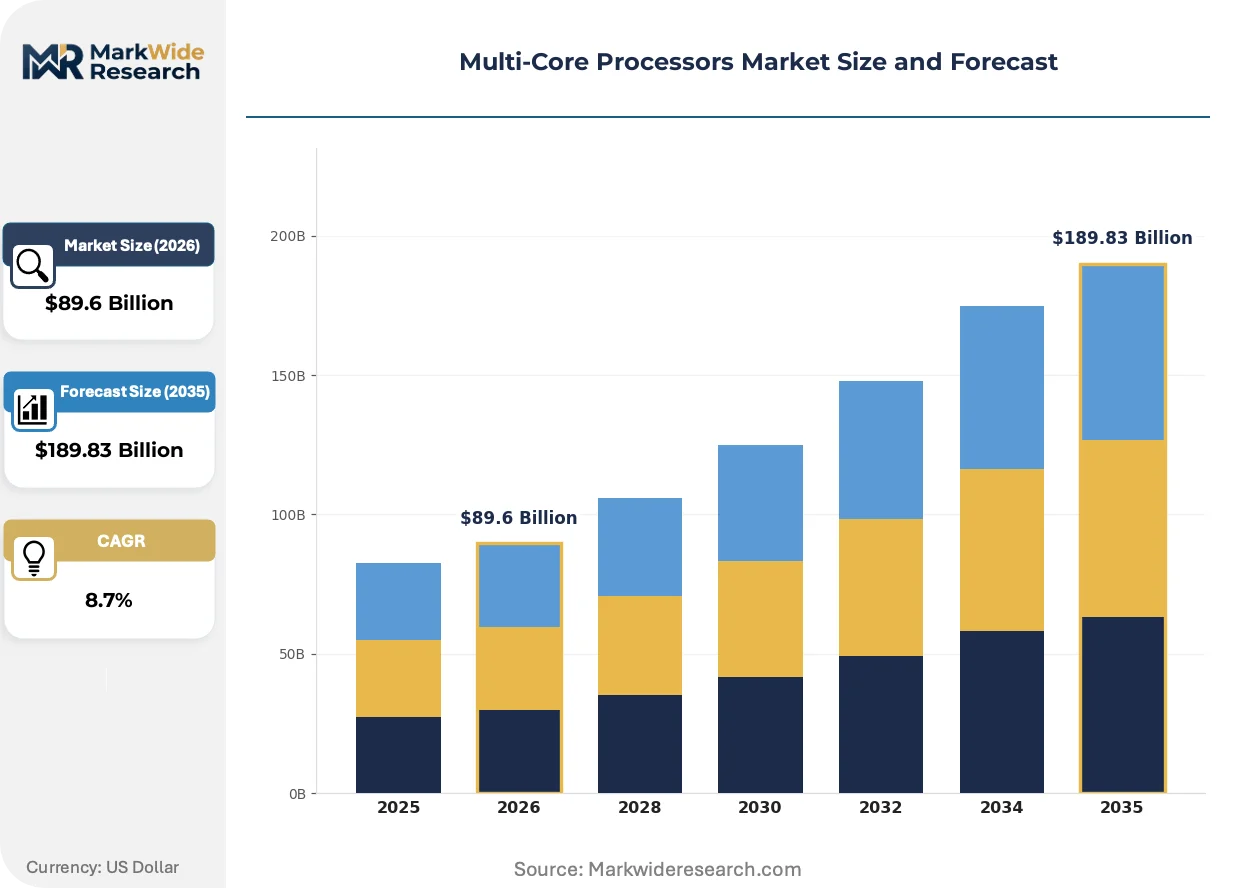
| Market Size in 2026 | $89.6 Billion |
| Market Size in 2035 | $189.83 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Architecture Type: ARM, x86, SPARC, MIPS Application: Gaming, Data Centers, Mobile Devices, Embedded Systems End User: Consumer Electronics, Telecom, Automotive, Industrial Automation Integration Level: System-on-Chip, Dual-Core, Quad-Core, Octa-Core |
| Companies Covered | Apple Inc., MediaTek Inc., Intel Corporation, Broadcom Inc., NVIDIA Corporation, Advanced Micro Devices Inc., ARM Holdings plc, NXP Semiconductors N.V., Qualcomm Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Core Processors Market Strategic Shifts
Software-defined feature licensing is electrifying how semiconductor vendors capture recurring revenue streams beyond initial hardware transactions, while sovereign industrial policy and shifting procurement patterns restructure competitive positioning across fabrication and design.
Chiplet-based modular architectures are electrifying processor design by decoupling compute, memory, and I/O functions into discrete tiles interconnected through advanced packaging. Data center operators and automotive Tier-1 suppliers adopt these configurations to customize performance-thermal tradeoffs. This disaggregation is electrifying foundry business models toward multi-vendor assembly ecosystems and compressing traditional monolithic design cycles.
REACH substance restrictions and EU RoHS directives constrain material selection in high-density interconnects and substrate compositions. Manufacturers reformulate solder alloys and underfill materials to maintain reliability while eliminating restricted substances. Medical device and automotive segments face the steepest compliance burdens as they operate under dual jurisdiction of EU chemicals regulation and sector-specific safety mandates.
Hyperscaler direct silicon customization represents a structural break from merchant processor procurement. Amazon Web Services, Microsoft Azure, and Google Cloud commission ARM-based designs through foundry partnerships, bypassing traditional x86 vendors. This vertical integration into proprietary silicon is most visible in the United States where cloud capital expenditure concentrates and custom accelerator deployment accelerates.
Multi-Core Processors Market Segmentation
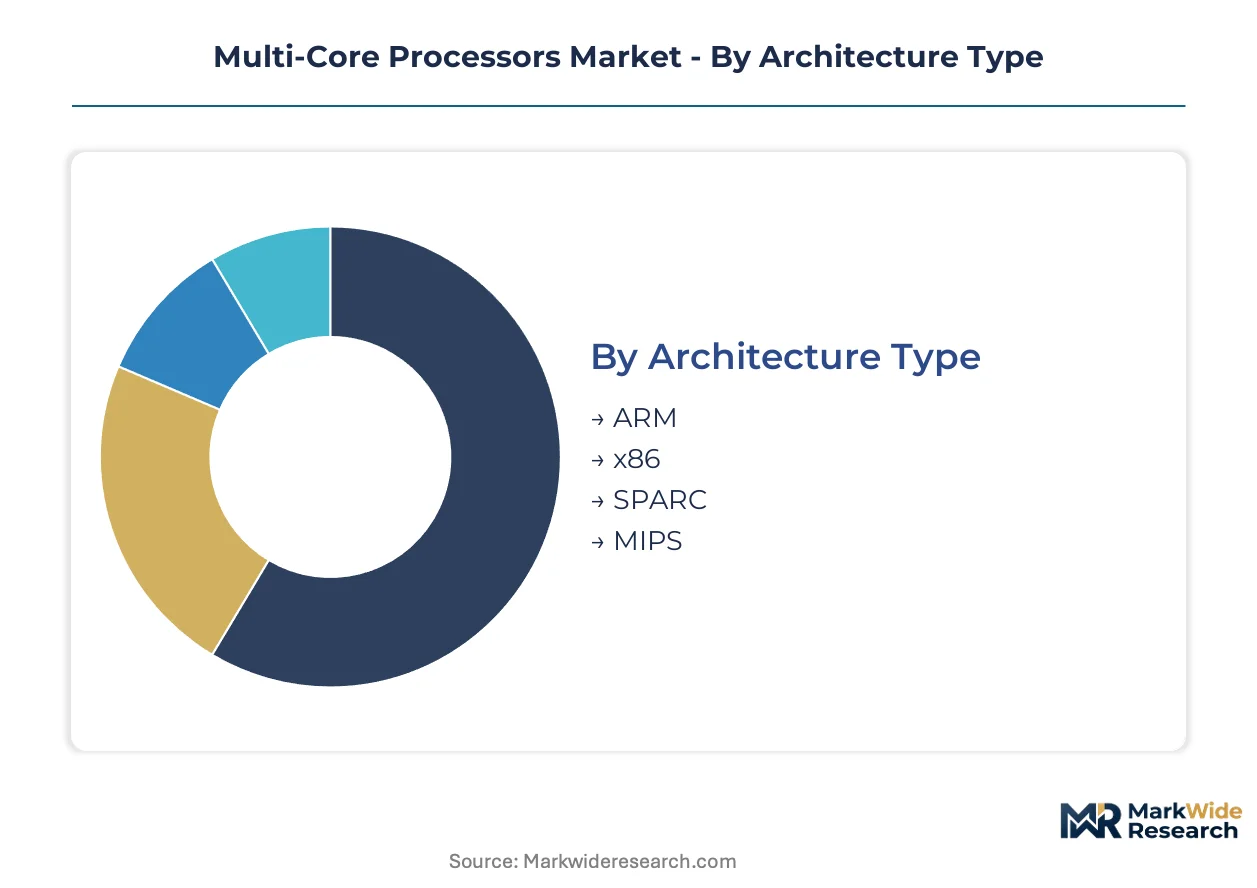
Multi-core processor segmentation reveals how architectural choices, integration density, and end-use requirements fragment procurement patterns. Vendors must align fabrication investments with the specific thermal, power, and software compatibility constraints governing each category.
Architecture Type:
The customization-vs-standardization spectrum runs from instruction-set flexibility to legacy software lock-in across processor architectures.
- ARM:Reduced instruction set computing enables power-efficient parallel execution at sub-5W thermal envelopes. Smartphone OEMs in Taiwan and South Korea concentrate orders for 5G-integrated application processors where battery life constrains design.
- x86:Complex instruction set computing maintains backward compatibility with decades of enterprise software. Data center operators in the United States and Germany sustain demand despite higher per-core power draw.
- SPARC:Oracle-controlled architecture persists in legacy financial services infrastructure requiring binary compatibility.
- MIPS:RISC-based designs serve embedded networking equipment and automotive infotainment where real-time determinism matters.
Leading the category by volume: ARM. Growing fastest: ARM.
Application:
Cost tier stratification separates capital-intensive infrastructure deployments from consumer electronics with compressed replacement cycles.
- Data Centers:Hyperscalers deploy 64-core and 96-core sockets for virtualization density. Cloud service providers in Virginia, Frankfurt, and Singapore drive socket-level customization through direct foundry partnerships.
- Mobile Devices:Handset OEMs prioritize die-size efficiency and modem integration over raw thread count. Flagship smartphone launches in South Korea and China set annual core-count benchmarks.
- Gaming:Discrete GPU-CPU combinations target frame-rate consistency rather than server-grade reliability metrics.
- Embedded Systems:Industrial controllers and medical devices favor long-life availability over leading-edge node migration.
Data Centers lead procurement value. Mobile Devices expand most quickly by unit shipment.
End User:
Customer type determines certification burden, volume predictability, and margin structure across processor procurement.
- Automotive:Functional safety requirements under ISO 26262 mandate lock-step cores and error-correcting memory. ECU consolidation in Germany and Japan pulls demand for 16-core automotive SoCs with real-time deterministic execution.
- Telecom:Baseband processing and radio unit controllers require hardware-accelerated signal processing. 5G infrastructure buildouts in India and the United States concentrate orders for high-throughput multi-core silicon.
- Consumer Electronics:Tablet and wearable OEMs prioritize bill-of-materials cost over thermal headroom.
- Industrial Automation:Programmable logic controllers and robotics systems demand extended temperature range specifications.
Automotive commands premium pricing. Telecom shows steepest expansion trajectory.
Integration Level:
Supply concentration in advanced packaging capacity shapes which integration tiers remain accessible to non-hyperscale buyers.
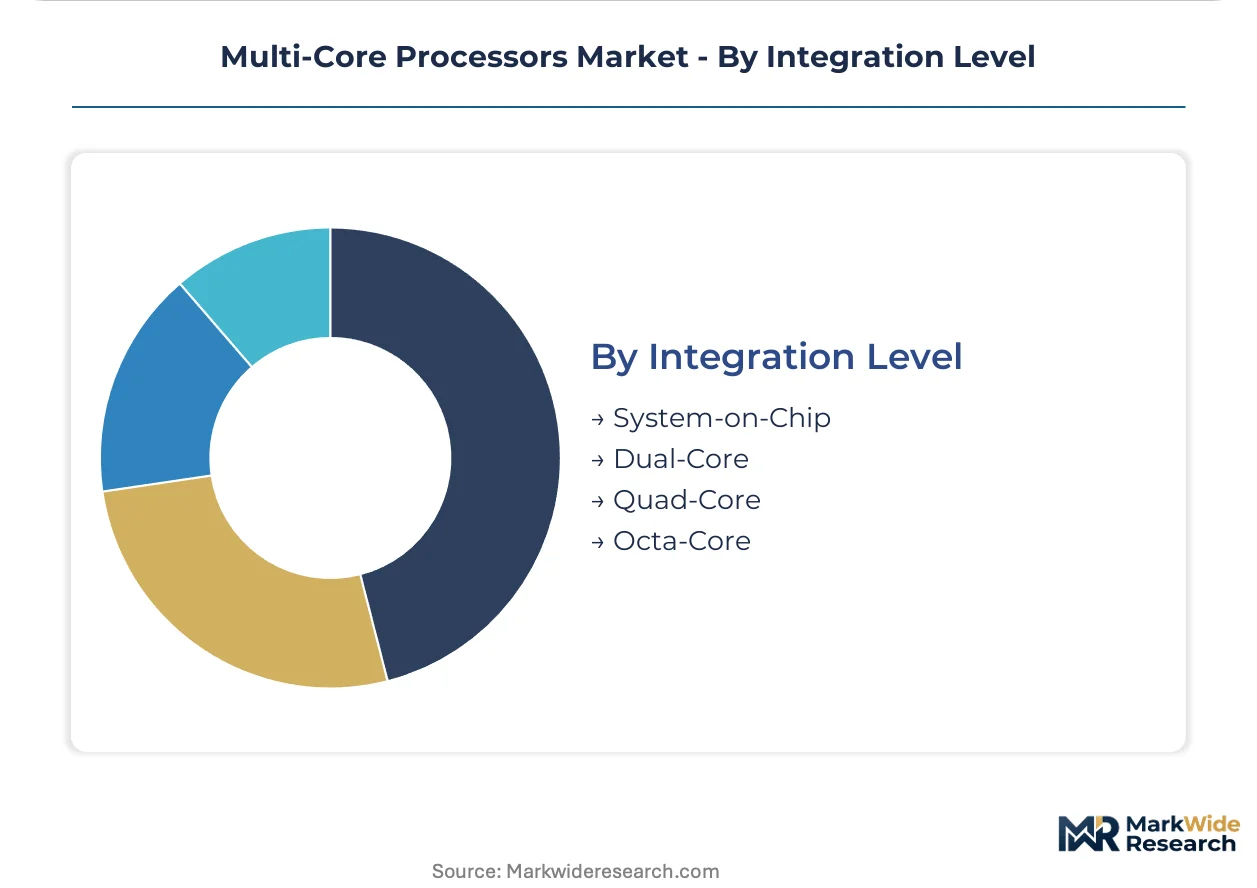
- System-on-Chip:Unified die designs integrate CPU, GPU, NPU, and modem functions through 3nm and 5nm processes. Apple, Qualcomm, and MediaTek dominate procurement for mobile and automotive platforms.
- Octa-Core:Eight-core configurations balance thread-level parallelism with thermal design power constraints in thin-client devices.
- Quad-Core:Mid-range smartphones and entry-level laptops standardize on four-core clusters with asymmetric big.LITTLE scheduling.
- Dual-Core:Cost-optimized industrial controllers and legacy point-of-sale systems sustain demand at mature process nodes.
System-on-Chip leads revenue concentration. Octa-Core gains share fastest in mid-tier consumer devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leading-edge fabrication concentrates in East Asia while advanced packaging and design expertise clusters in the United States. Taiwan and South Korea produce the majority of sub-5nm wafers, yet American hyperscalers commission the dominant share of custom multi-core silicon.
United States
Cloud capital expenditure drives demand for 64-core and 96-core server processors. The CHIPS and Science Act directs federal subsidies toward domestic foundry construction in Arizona and Texas. Intel operates advanced packaging facilities in New Mexico while NVIDIA anchors GPU accelerator design in Santa Clara.
Taiwan
TSMC fabricates the majority of smartphone and data center processors at 3nm and 5nm nodes. The National Development Council coordinates semiconductor supply chain resilience initiatives. Hsinchu Science Park hosts the densest concentration of leading-edge lithography capacity globally.
South Korea
Samsung Electronics pursues 3nm gate-all-around transistor production for mobile and high-performance computing. The K-Semiconductor Belt program incentivizes materials and equipment supplier clustering. Pyeongtaek hosts the world's largest memory and logic fabrication complex.
Germany
Automotive OEMs in Stuttgart and Munich procure 16-core functional safety processors for ECU consolidation. The European Chips Act subsidizes Intel's planned Magdeburg foundry and TSMC's Dresden joint venture. Bavaria concentrates embedded systems design for industrial automation.
China
Domestic foundries advance 7nm production despite lithography equipment access constraints. MIIT's integrated circuit industry guidelines prioritize self-sufficiency in mature-node processors. Shanghai and Beijing clusters focus on AI accelerator and server CPU design.
Multi-Core Processors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent margin structures. The market consolidates around three fabrication leaders while maintaining fragmented specialty tiers. IDM incumbents, fabless architects, and IP licensors represent the dominant strategic archetypes. Capacity expansion and heterogeneous integration partnerships constitute the primary competitive moves.
Among American incumbents, Intel Corporation exemplifies the integrated device manufacturer archetype with captive fabrication and packaging assets. NVIDIA Corporation and Qualcomm Technologies Inc. occupy positions as fabless designers dependent upon foundry partnerships for leading-edge production.
| Leading Market Players |
|---|
| Apple Inc. |
| MediaTek Inc. |
| Intel Corporation |
| Broadcom Inc. |
| NVIDIA Corporation |
| Advanced Micro Devices Inc. |
| ARM Holdings plc |
| NXP Semiconductors N.V. |
| Qualcomm Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices cascade through foundry pricing tiers, compressing margins at mature nodes while amplifying premium capture at sub-5nm where TSMC and Samsung Electronics exercise capacity discipline. EUV equipment depreciation schedules and South Korean memory pricing volatility propagate through multi-core processor cost structures, stratifying procurement economics between hyperscale direct-negotiation and distributor-mediated spot buying.
Pricing Analysis
Margin tightening in automotive-grade silicon reflects ISO 26262 functional safety certification premiums layered atop foundry wafer costs. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-grade processors separates medical device OEMs from gaming peripheral manufacturers. Cost-down pressure on mid-tier octa-core mobile SoCs accelerates because MediaTek and Qualcomm Technologies compete for India PLI scheme assembly volumes. Handset OEMs in Shenzhen and Hanoi exhibit highest price sensitivity, while FDA-validated diagnostic equipment manufacturers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Packaging and thermal engineering talent scarcity in Hsinchu, Pyeongtaek, and Chandler constrains advanced 3D stacking capacity expansion. Raw material dependencies span silicon wafers from Shin-Etsu, photoresists from JSR Corporation, and palladium for substrate plating from Russian supply corridors. Single-source vulnerability concentrates at EUV lithography systems where ASML Holding maintains effective monopoly. Distribution runs through authorized distributors for qualified automotive and medical segments, while spot markets serve consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU RoHS substance restrictions and REACH compliance create barrier-to-entry moats for processors qualified under dual chemical and sector-specific safety mandates. The cost-of-compliance story favors incumbents with validated legacy portfolios over unqualified challengers.
For Market Incumbents: Deepen heterogeneous integration partnerships with advanced packaging specialists in Taiwan to defend against ARM-based data center substitution. Expand captive 3D stacking capacity in Arizona and New Mexico to offset foundry margin compression. Prioritize FDA electromagnetic compatibility pre-certification for medical device processor lines to lock in diagnostic equipment sockets.
For New Entrants and Emerging Players: Launch via India PLI scheme assembly partnerships targeting mid-tier smartphone SoC white space. Penetrate industrial automation controllers in Bavaria and Stuttgart where extended temperature range specifications favor specialized designs over commoditized mobile derivatives. Pursue 5G modem-to-AP die-level integration for telecom infrastructure buildouts as the most penetrable segment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-qualified fabless designers in Germany and Japan with ISO 26262 lock-step core portfolios. Long-term viability hinges on ECU consolidation tailwinds persisting through the next technology refresh cycle. Monitor Intel Corporation foundry utilization rates as inflection indicator for merchant processor pricing power restoration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based Modular Architecture Development | Decouples compute and memory functions, enabling customized performance-thermal tradeoffs for automotive Tier-1 suppliers. |
| Direct Foundry Partnership with TSMC | Bypasses merchant processor vendors, allowing Amazon Web Services and Microsoft Azure to capture silicon customization value. |
| Functional Safety Certification Investment | ISO 26262 compliance creates premium positioning in Stuttgart and Munich automotive ECU consolidation programs. |
| Advanced Packaging Capacity Expansion | 3D stacking expertise in Hsinchu Science Park addresses heterogeneous integration bottlenecks constraining supply. |
| Software-Defined Feature Licensing | Transforms NVIDIA Corporation and Qualcomm Technologies revenue models toward recurring streams beyond hardware transactions. |
Study Parameters
Independent corroboration across semiconductor foundry utilization reports, hyperscaler capital expenditure disclosures, and automotive OEM procurement databases underwrites the qualitative findings. Primary interviews with fabless design executives, foundry yield engineering directors, automotive Tier-1 procurement leads, and medical device regulatory affairs specialists combined with secondary validation from SEC 10-K filings, EIA energy consumption data, and EU Chips Act implementation trackers. Bottom-up wafer shipment aggregation and top-down semiconductor equipment spending analysis triangulate volume estimates.
Comparable-period anchoring to historical foundry capacity expansion cycles and node migration timelines structured the projection framework. Segmentation dimensions span architecture type, integration level, end-use application, and regional fabrication cluster across the analysis window. CAGRs derive from wafer start forecasts, die-size efficiency trends, and ASP trajectory modeling. Industry-specific inputs include EUV machine delivery schedules and sovereign subsidy disbursement timelines.
Export control escalations on lithography equipment, sovereign subsidy program delays, and hyperscaler silicon insourcing acceleration are the dominant revision risks. Forecasts embed assumptions around foundry yield maturation curves and packaging capacity scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Data Processing Neuromorphic Chip Market