
 Plasmonic Chip Market | 2026-2036
Plasmonic Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmonic Chip Market Analytics
Modular chip-to-sensor bundling is expanding buyer choice across the plasmonic value chain. Plasmonic Biosensors Inc. leverages its vertical integration into nano-patterning to control cost structures for diagnostic OEMs. Agilent Technologies Inc. sustains technology leadership in surface plasmon resonance instrumentation through deep R&D allocation. Polariton Technologies specializes in telecom-grade tunable devices that anchor wavelength-selective switching demand.
Plasmonic chips integrate noble-metal nanostructures—typically gold or silver patterned at sub-wavelength scales—to confine and manipulate electromagnetic fields via collective electron oscillations, enabling real-time molecular detection without fluorescent labels. Active Plasmonic Chips dominate current revenue as electrically tunable architectures suit dynamic biochemical assays, while Graphene-based Plasmonics represents the fastest-emerging technology dimension due to its broadband tunability and CMOS compatibility. Passive Plasmonic Chips retain mature positioning in bulk refractive-index sensing where margin pools have compressed.
The FDA governs clinical diagnostic deployments of plasmonic sensors in the United States through premarket pathway requirements, while the EU MDR and CE marking framework shape market access for European healthcare end users. REACH compliance constrains material selection for gold and silver nanostructures, pushing manufacturers toward greener synthesis protocols. Stakeholders must monitor evolving ISO nanotechnology standards and national dual-use export controls as plasmonic devices bridge civilian sensing and secure communication applications.
Market Dynamics
Active plasmonic architectures are displacing passive substrates as healthcare OEMs prioritize real-time tunability in point-of-care diagnostics, compressing margins for legacy refractive-index sensor suppliers while concentrating procurement among vertically integrated nano-fabrication specialists.
Growth Catalysts
- EU MDR framework:Accelerated CE marking pathways for label-free diagnostic platforms are pulling plasmonic biosensors into clinical workflows across German and French hospital networks.
- CMOS-compatible graphene plasmonics:Semiconductor foundries in Taiwan and South Korea are integrating broadband-tunable nanostructures into standard silicon process nodes, collapsing prototyping costs for fabless sensor designers.
- Telecom wavelength-division multiplexing:Japanese carriers are deploying tunable plasmonic switches to densify fiber-optic backhaul, creating anchor demand for noble-metal nanostructure suppliers.
Market Restraints
- Gold nanostructure input volatility:Noble-metal spot price swings and REACH-mandated green synthesis protocols are elevating unit costs for European manufacturers.
- E-beam lithography supply concentration:Sub-100 nm patterning capacity clusters among specialized foundries in the United States and Germany, creating single-source vulnerability for high-resolution chip production.
- Fluorescence-based ELISA substitution:Mature enzyme-linked immunosorbent assay platforms retain entrenched clinical validation, slowing label-free displacement in budget-constrained health systems.
Strategic Opportunities
- India's CDSCO fast-track:Streamlined medical device registration for import-substituting diagnostics is opening procurement channels for plasmonic sensor OEMs targeting tier-2 city laboratories.
- Quantum-dot plasmonic hybridization:Convergence of colloidal quantum dots with metallic nanostructures is enabling single-molecule sensitivity thresholds for next-generation proteomics.
- Direct-to-researcher e-commerce:Modular chip-to-sensor bundling through specialized distributors is bypassing traditional instrumentation vendor channels in academic procurement.
Industry Challenges
- Nanofabrication technician scarcity:Cross-disciplinary expertise spanning electrodynamics, cleanroom processing, and biochemistry remains concentrated among doctoral-level specialists, constraining foundry expansion.
- FDA premarket notification timelines:510(k) clearance cycles for clinical plasmonic diagnostics extend 18-24 months, delaying revenue recognition for diagnostic platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmonic Chip Market |
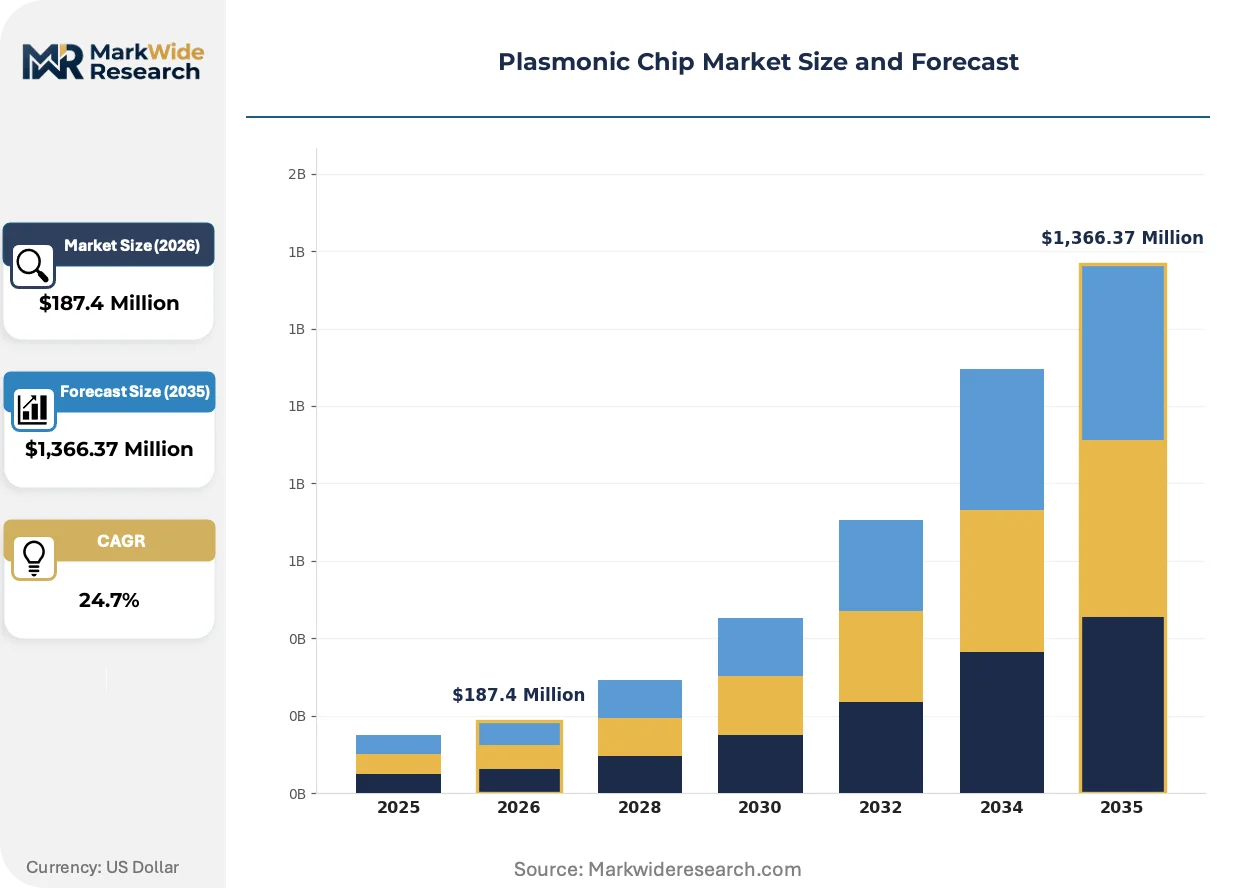
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,366.37 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Plasmonic Chips, Passive Plasmonic Chips, Tunable Plasmonic Chips, Nano-Plasmonic Devices Technology: Surface Plasmon Resonance, Metamaterials, Nanostructured Materials, Graphene-based Plasmonics Application: Biochemical Sensing, Telecommunication, Imaging Systems, Energy Harvesting End User: Healthcare, Telecommunications, Automotive, Research Institutions |
| Companies Covered | Plasmonic Biosensors Inc., Nanostructured and Amorphous Materials Inc., Polariton Technologies, Agilent Technologies Inc., Cytodiagnostics Inc., Nanopartz Inc., Nanospectra Biosciences Inc., Spherotech Inc., Nanocomposix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmonic Chip Market Evolving Landscape
Integration of electrically tunable nanostructures with standard semiconductor processes is collapsing the boundary between optical and electronic systems, while regulatory frameworks on both sides of the Atlantic accelerate clinical validation requirements.
Hybrid silicon-plasmonic modulators are decentralizing wavelength-selective switching from discrete optical components into co-packaged photonic-electronic systems. Data center operators in the United States are adopting these devices to collapse interconnect latency. This convergence is decentralizing traditional telecom equipment vendor roles as hyperscalers bring switch design in-house.
REACH restrictions on gold and silver nanomaterial synthesis are forcing European manufacturers toward aqueous-phase reduction protocols and biogenic templating methods. ECHA compliance costs are elevating entry barriers for smaller chemical suppliers. German and Swiss precision optics houses are responding by consolidating captive nano-patterning capabilities to shield proprietary formulations.
Research consortia are unbundling after-sales service from capital equipment contracts, selling sensor chips on per-assay consumption models instead. Academic core facilities and CROs in Japan are driving this transition. This reconfiguration is most visible in North American life sciences clusters where NIH funding pressures favor operational expenditure over capital outlay.
Plasmonic Chip Market Segmentation
Plasmonic chip architectures diverge sharply in fabrication complexity and end-use economics. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology platforms command sustainable margin structures.
Product Type:
Capital intensity escalates with electrical tunability requirements, separating programmable architectures from passive substrates.
- Active Plasmonic Chips:Electrically tunable architectures integrate voltage-controlled nanostructures for real-time refractive index modulation. Healthcare OEMs in the United States prioritize these platforms for point-of-care diagnostic workflows where dynamic assay control justifies premium unit economics.
- Tunable Plasmonic Chips:Wavelength-selective designs anchor telecom infrastructure upgrades through thermo-optic or electro-optic control mechanisms. Japanese carriers deploy these devices to densify fiber-optic backhaul capacity without discrete component replacement cycles.
- Passive Plasmonic Chips:Fixed-nanostructure substrates serve bulk refractive-index sensing with compressed margins and mature supply chains.
- Nano-Plasmonic Devices:Sub-wavelength confinement structures enable single-molecule detection thresholds in proteomics research.
Most installed capacity flows through Active Plasmonic Chips. Expansion is steepest in Tunable Plasmonic Chips.
Technology:
Intellectual property density and foundry compatibility determine which technology platforms attract semiconductor-scale investment.
- Graphene-based Plasmonics:Atomically thin carbon layers enable broadband tunability across infrared to terahertz frequencies with full CMOS process compatibility. Taiwan Semiconductor Manufacturing and South Korean foundries integrate these nanostructures into standard silicon nodes, collapsing prototyping costs for fabless designers targeting biochemical sensing applications.
- Surface Plasmon Resonance:Noble-metal film architectures remain the reference standard for label-free binding kinetics measurement in pharmaceutical development. German and Swiss precision optics houses dominate instrumentation supply for contract research organizations requiring regulatory-compliant validation data.
- Metamaterials:Artificially engineered electromagnetic properties enable negative refractive index phenomena for super-resolution imaging systems.
- Nanostructured Materials:Lithographically patterned noble-metal geometries serve cost-sensitive refractive-index sensing with established fabrication protocols.
Graphene-based Plasmonics is climbing the fastest as foundry integration accelerates. Surface Plasmon Resonance retains the largest installed base.
Application:
Regulatory pathway complexity and reimbursement structure shape which application verticals absorb new chip capacity.
- Biochemical Sensing:Label-free molecular detection platforms eliminate fluorescent tag requirements in clinical diagnostics and pharmaceutical quality control. FDA premarket notification pathways and EU MDR CE marking frameworks govern deployment timelines, with German hospital networks and United States academic medical centers anchoring early procurement.
- Telecommunication:Wavelength-division multiplexing and optical switching applications demand thermal stability and insertion loss minimization. Japanese and South Korean carriers drive specification requirements for telecom-grade device qualification.
- Imaging Systems:Super-resolution microscopy and near-field optical probes serve materials science and semiconductor metrology end uses.
- Energy Harvesting:Thermophotovoltaic and solar thermal conversion applications exploit plasmonic near-field enhancement for spectral control.
Biochemical Sensing commands the dominant share of qualified production capacity. Telecommunication is expanding most quickly as data center interconnect requirements intensify.
End User:
Procurement sophistication and volume scale separate institutional buyers from fragmented research-grade purchasers.
- Healthcare:Integrated diagnostic platform OEMs and hospital network procurement consortia specify performance validation protocols and multi-year supply agreements. United States health system purchasing organizations and German hospital chains concentrate demand for clinical-grade sensor chips.
- Research Institutions:Academic core facilities and national laboratories drive modular chip-to-sensor bundling preferences, favoring per-assay consumption models over capital equipment acquisition. NIH funding pressures in North America and Japan's RIKEN network accelerate this transition.
- Telecommunications:Carrier procurement specifications emphasize reliability certification and volume pricing tiers for infrastructure deployment.
- Automotive:Emerging LiDAR and in-cabin sensing applications represent nascent demand with unvalidated qualification protocols.
Healthcare absorbs the largest qualified volume. Research Institutions are gaining share fastest as funding models shift toward operational expenditure structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasmonic chip commercialization traces its industrial roots to early surface plasmon resonance instrumentation developed in Swedish and German university laboratories during the 1990s. These foundational research programs seeded the process engineering expertise now concentrated in precision optics clusters across Northern Europe and East Asia. Today, procurement patterns split between healthcare diagnostic platforms and telecom infrastructure upgrades, with regulatory acceleration in select jurisdictions reshaping geographic deployment timelines.
United States
FDA premarket notification pathways for clinical diagnostic platforms concentrate demand among Boston and San Francisco Bay Area medical device clusters. NIH funding pressures favor operational expenditure models over capital equipment acquisition at academic core facilities. The National Institute of Standards and Technology anchors metrology standardization efforts for nano-patterned noble-metal substrates.
Germany
EU MDR CE marking acceleration pulls plasmonic biosensors into hospital networks across Bavaria and North Rhine-Westphalia. ECHA REACH compliance costs elevate entry barriers for nanomaterial synthesis suppliers. Precision optics houses in Jena and Munich consolidate captive nano-patterning capabilities to shield proprietary formulations from regulatory disclosure.
Japan
Telecom wavelength-division multiplexing deployments by NTT and KDDI create anchor demand for tunable plasmonic switches. METI technology roadmaps prioritize CMOS-compatible photonic integration for domestic semiconductor foundries. The Tsukuba research corridor drives modular chip-to-sensor bundling preferences through RIKEN-funded proteomics facilities.
South Korea
Semiconductor foundries in Suwon and Pyeongtaek integrate graphene plasmonics into standard silicon process nodes. MFDS medical device registration pathways attract diagnostic platform developers seeking faster clinical validation than FDA timelines. Samsung and SK Hynix supply chain relationships accelerate fabless sensor designer access to volume production.
Taiwan
TSMC and United Microelectronics foundry services collapse prototyping costs for biochemical sensing startups targeting infrared detection applications. The Hsinchu Science Park clusters electrodynamics specialists with cleanroom fabrication technicians. National Tsing Hua University research partnerships bridge academic plasmonics into commercial nano-patterning workflows.
Plasmonic Chip Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fabrication complexity and regulatory certification depth. The vendor base stratifies into three tiers: vertically integrated specialists controlling nano-patterning and surface chemistry, instrumentation OEMs sourcing chips from captive or merchant suppliers, and research-grade material providers serving academic procurement. Three archetypes dominate competitive positioning: noble-metal nanostructure foundries, surface plasmon resonance platform developers, and graphene-CMOS integration specialists. Capacity expansion and strategic technology licensing represent the dominant competitive moves as participants seek to secure sub-100 nm patterning capacity.
Among North American platform developers, Agilent Technologies Inc. exemplifies the instrumentation-anchored archetype, while Cytodiagnostics Inc. occupies a merchant supplier position. Polariton Technologies represents the telecom-specialist vector with wavelength-selective device focus. These three companies illustrate how geographic clustering around regulatory hubs and foundry access shapes sustainable margin capture.
| Leading Market Players |
|---|
| Plasmonic Biosensors Inc. |
| Nanostructured and Amorphous Materials Inc. |
| Polariton Technologies |
| Agilent Technologies Inc. |
| Cytodiagnostics Inc. |
| Nanopartz Inc. |
| Nanospectra Biosciences Inc. |
| Spherotech Inc. |
| Nanocomposix Inc. |
| Others |
Value Network & Pricing Analysis
Captive nano-patterning capabilities at German and Swiss precision optics houses anchor both supply security and premium pricing power for clinical-grade plasmonic chips, insulating proprietary formulations from REACH-mandated disclosure while compressing margins for merchant foundry-dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from research-grade substrates and unvalidated raw nanomaterials. Price differentiation hinges on certification depth and volume scale, with healthcare OEMs absorbing premiums for premarket-validated chips while academic core facilities drive commoditization of passive substrates. Cost compression in the economy tier is intensifying because Taiwanese foundries are collapsing prototyping costs for graphene-CMOS designs. Research institutions exhibit highest price sensitivity; integrated diagnostic platform OEMs least.
Supply Chain Analysis
CE marking and FDA premarket notification requirements gate qualified supply to a narrow tier of vertically integrated specialists with regulatory affairs infrastructure. Geographic concentration clusters in Taiwan, South Korea, and Germany, where semiconductor foundries and precision optics houses command sub-100 nm patterning capacity. Raw material dependencies center on gold and silver nanostructures, e-beam lithography equipment, and CMOS-compatible graphene precursors. Single-source vulnerability pervades high-resolution patterning capacity concentrated among specialized foundries in the United States and Germany. Distribution runs through direct-to-researcher e-commerce channels and multi-year supply agreements with hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South Korean and Taiwanese foundry access offers 30-40 percent cost advantages over German captive production for pre-clinical research applications.
For Market Incumbents: Deepen backward integration into noble-metal nanostructure synthesis to offset REACH compliance cost elevation and gold spot price volatility. Lock sub-100 nm e-beam lithography capacity through multi-year foundry agreements before capacity constraints harden. Prioritize FDA 510(k) pathway investment to defend margin position against emerging graphene-CMOS substitutes. For New Entrants and Emerging Players: The premium-to-economy price-point gap in biochemical sensing substrates exceeds 400 percent, opening white-space at the mid-tier for CMOS-compatible designs with simplified regulatory positioning. Target India's CDSCO fast-track pathway for import-substituting diagnostics in tier-2 city laboratories. Pursue modular chip-to-sensor bundling through specialized distributors to bypass entrenched instrumentation vendor channels. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated nano-patterning specialists because regulatory certification depth and foundry capacity scarcity concentrate value in a handful of qualified players. Platform consolidation across European precision optics houses and East Asian foundry relationships offers 5-10 year viability as healthcare OEMs prioritize supply security over pure cost optimization. Watch for FDA breakthrough device designation grants as inflection indicators for clinical validation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Foundry Integration | Taiwan Semiconductor Manufacturing collapses prototyping costs for fabless biochemical sensor designers. |
| Regulatory Fast-Track Positioning | India's CDSCO streamlined registration opens procurement channels for diagnostic platform developers. |
| Captive Nano-Patterning Buildout | German precision optics houses shield proprietary formulations from ECHA REACH disclosure requirements. |
| Modular Chip-to-Sensor Bundling | Per-assay consumption models bypass traditional instrumentation vendor channels in academic procurement. |
| Graphene Plasmonics R&D Scale-Up | South Korean foundries integrate broadband-tunable nanostructures into standard silicon process nodes. |
Research Methodology
Direct dialogue with nano-fabrication technicians, diagnostic platform OEM procurement leads, biomedical engineers at academic core facilities, and regulatory affairs specialists at precision optics houses grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA CE marking databases, ECHA REACH compliance disclosures, and foundry capacity announcements from Taiwan and South Korea. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up volume modeling tracked active plasmonic chip, tunable plasmonic chip, passive substrate, and nano-plasmonic device shipments across healthcare, research institution, telecommunications, and automotive end users. Top-down validation anchored to semiconductor foundry capex disclosures and NIH extramural funding allocations for label-free detection platforms. CAGRs were derived from segment-level growth rate distributions weighted by qualified production capacity across the analysis window.
Caveats apply where FDA premarket notification timeline extensions, gold nanostructure input volatility, or e-beam lithography supply concentration could materially shift the outlook. Forecasts reflect assumptions about CMOS foundry integration pace and EU MDR CE marking acceleration. A model refresh is warranted upon material change in regulatory pathway timelines or noble-metal spot price trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Global Merchant Embedded Computing Market