
 Europe Laboratory Automation Market | 2026-2036
Europe Laboratory Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laboratory Automation Market Intelligence
German instrument manufacturing is expanding its footprint in liquid handling and robotic workstations for European life sciences. Tecan Group leverages its Zürich-engineered platforms to dominate automated pipetting across Swiss and German pharmaceutical labs. PerkinElmer sustains competitive positioning through detection and imaging specialization that anchors its presence in genomic screening workflows. Danaher Corporation operates an integrated portfolio spanning Beckman Coulter and Cytiva assets, extending its control over sample preparation and analytical automation.
Europe laboratory automation encompasses integrated hardware and software systems that execute repetitive analytical tasks with precision measured in microliter volumes and throughput rates exceeding thousands of samples daily, serving industrial and academic users seeking reproducible data generation and regulatory-compliant documentation. Automated pipetting systems and liquid handling robots capture the largest installed base, while artificial intelligence and microfluidics represent the fastest-expanding technology layers where margin pools deepen through software licensing and consumable lock-in. Pharmaceutical companies and clinical laboratories drive the bulk of current demand, though academic institutions are accelerating procurement as EU research funding prioritizes digital infrastructure.
EMA's In Vitro Diagnostic Regulation and CE marking requirements under the EU Medical Device Regulation shape product validation timelines and market access conditions for automated diagnostic platforms. REACH compliance and ECHA substance restrictions further influence material selection in instrument construction and consumable chemistry. Germany's national pharmaceutical regulator, France's ANSM, and the United Kingdom's MHRA each enforce country-specific quality protocols that vendors must navigate for national tender participation. Stakeholders must monitor how the EU AI Act's risk classification framework applies to machine-learning components embedded in analytical automation.
Market Dynamics
Pharmaceutical contract manufacturers in Germany and France are consolidating automated workflows under EMA's tightened quality frameworks, compressing vendor selection cycles and favoring integrated platform suppliers over modular point solutions.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Diagnostic laboratories across France and the United Kingdom are accelerating platform upgrades to meet post-2022 compliance deadlines, pulling forward replacement demand for automated sample processing systems.
- Artificial intelligence integration:Machine-learning modules embedded in liquid handling robots are reducing protocol development time for high-throughput screening applications in Swiss and German biotech clusters.
- Contract research organization density:Munich and Heidelberg's concentrated CRO infrastructure creates localized demand pull for robotic workstations capable of 24-hour unattended operation.
Market Restraints
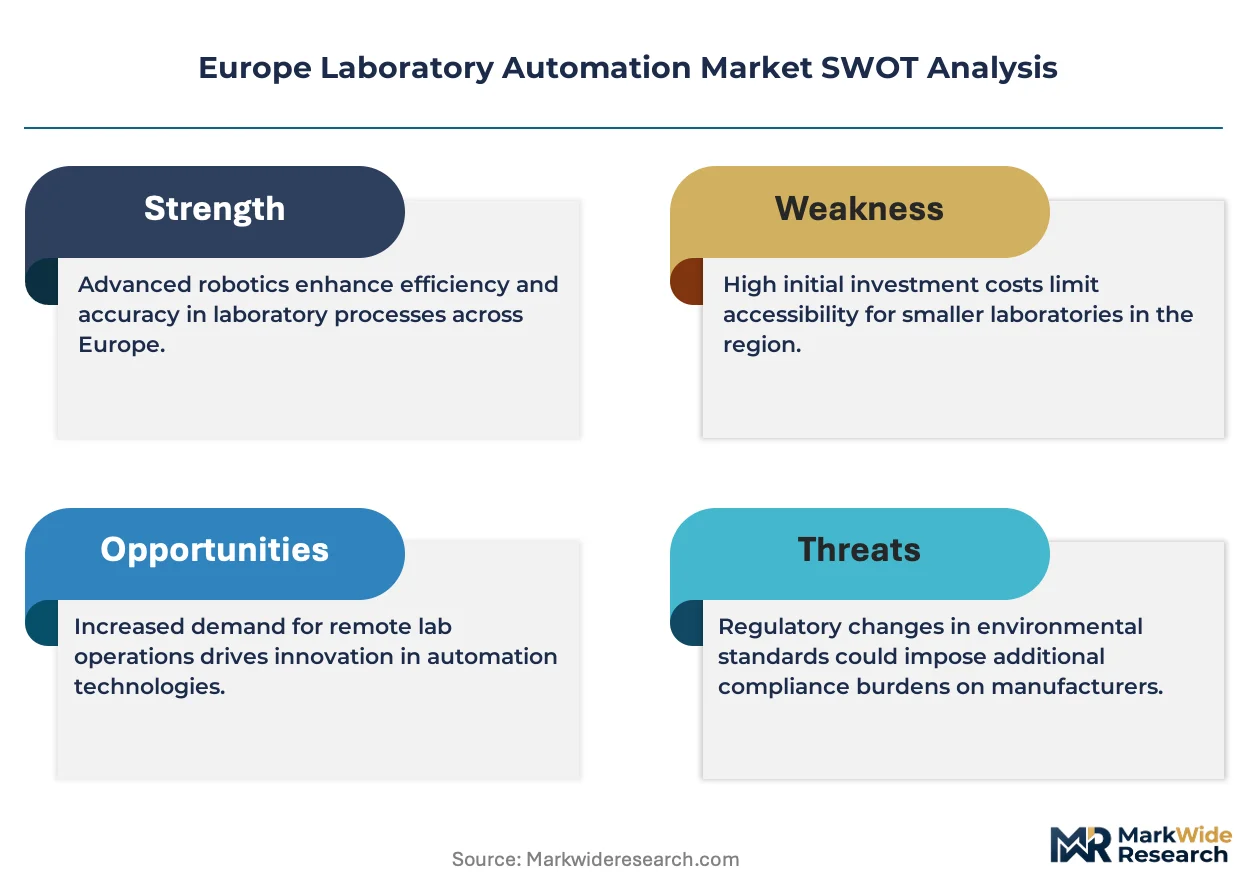
- Capital intensity threshold:Mid-sized clinical laboratories in Southern Europe face compressed ROI timelines when evaluating automated platform investments against manual protocol costs.
- Supply concentration in precision optics:German and Swiss instrument manufacturers depend on a limited supplier base for high-resolution imaging components used in automated detection modules.
- REACH substance restrictions:ECHA's evolving limits on fluorinated polymers constrain material selection for microfluidic consumables and liquid handling tips.
Strategic Opportunities
- EU AI Act risk classification:Vendors who pre-certify machine-learning diagnostic components gain tender advantages in public procurement processes across German university hospitals.
- Microfluidics-AI convergence:Combined platforms enabling real-time assay optimization capture premium pricing in genomic screening workflows at French pharmaceutical research sites.
- United Kingdom MHRA divergence pathway:Post-Brexit regulatory flexibility creates space for pilot deployments of novel automation architectures not yet CE-marked for EU markets.
Industry Challenges
- Mechatronics engineering scarcity:German automation vendors compete for specialized talent capable of integrating robotic kinematics with compliant software validation protocols.
- Legacy LIMS integration friction:Pharmaceutical quality systems built on decade-old data architectures resist seamless connectivity with modern cloud-native automation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laboratory Automation Market |
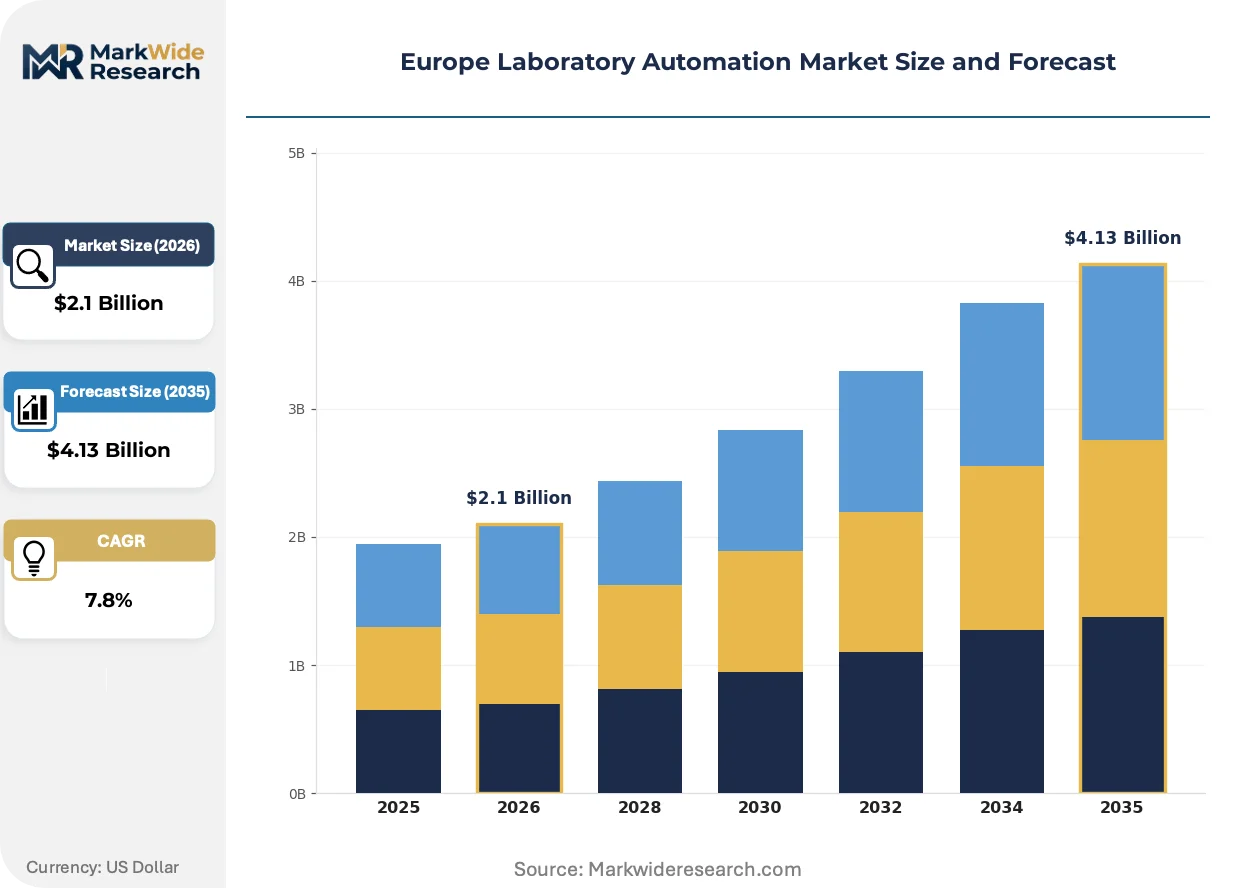
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Pipetting Systems, Plate Readers, Liquid Handling Robots, Sample Storage Solutions End User: Pharmaceutical Companies, Academic Institutions, Clinical Laboratories, Research Organizations Technology: Microfluidics, Robotics, Artificial Intelligence, Lab-on-a-Chip Application: Drug Discovery, Genomics, Proteomics, Quality Control |
| Companies Covered | Tecan Group, PerkinElmer, Danaher Corporation, Roche Diagnostics, Becton, Dickinson and Company, Thermo Fisher Scientific, Agilent Technologies, Eppendorf, Siemens Healthineers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laboratory Automation Market Strategic Shifts & Innovations
Convergence between microfluidic sample processing and machine-learning assay optimization is compressing development timelines for precision medicine applications across European research infrastructure.
Digital microfluidics is absorbing discrete liquid handling steps previously executed by robotic pipetting arms, enabling reaction miniaturization that reduces reagent consumption by orders of magnitude. Academic screening centers in the Netherlands and Denmark are piloting these platforms for CRISPR library preparation. The technology is absorbing market share from conventional fixed-tip pipetting in applications where volume precision below one microliter determines experimental validity.
EU AI Act's risk-based classification framework for medical device software is forcing vendors to restructure validation documentation for machine-learning components embedded in diagnostic automation. German notified bodies are extending review timelines for platforms exceeding Class IIa thresholds. High-complexity clinical laboratories in France are delaying procurement decisions pending clarity on conformity assessment pathways for adaptive algorithms.
Consolidated purchasing by pan-European pharmaceutical groups is compressing vendor negotiation cycles and unbundling traditional service contracts from hardware transactions. Procurement teams at Swiss and German headquarters now centralize automation specifications across distributed manufacturing and R&D sites. This concentration is visible most acutely in tender processes for high-throughput screening infrastructure where three-year total cost of ownership models displace capital expenditure evaluations.
Europe Laboratory Automation Market Segmentation
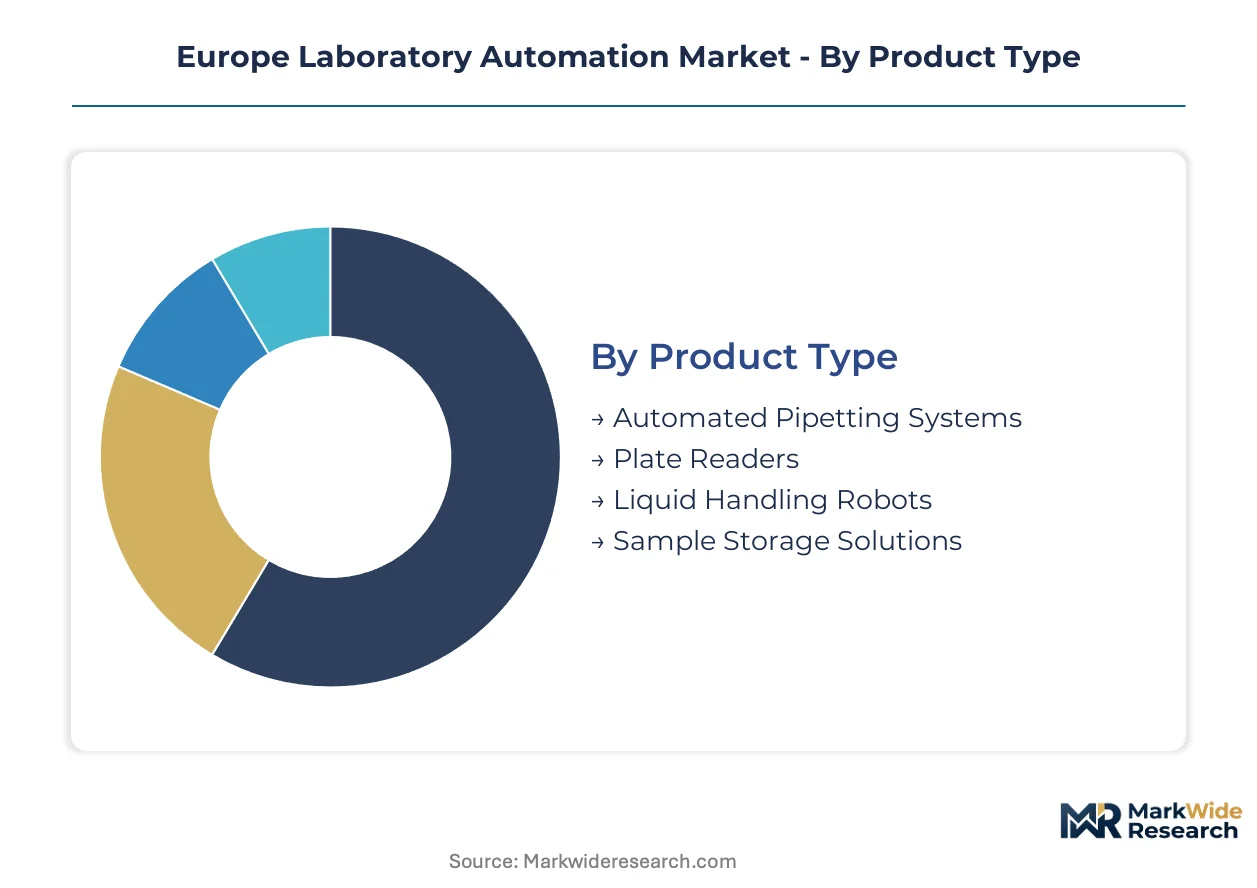
Laboratory automation in Europe fragments across hardware generations, user sophistication, and regulatory exposure. Each segmentation axis reveals distinct procurement patterns and margin structures that vendors must navigate.
Product Type:
Precision requirements and throughput demands differentiate instrument categories across German pharmaceutical manufacturing and French diagnostic networks.
- Liquid Handling Robots:Multi-axis robotic platforms execute sub-microliter transfers with 24-hour unattended operation protocols. Munich contract research organizations specify these for high-throughput screening workflows where EMA audit trails require full process documentation.
- Automated Pipetting Systems:Fixed-tip and disposable-tip configurations dominate routine sample preparation in clinical laboratories. United Kingdom hospital networks prioritize these for diagnostic platform upgrades under MHRA post-Brexit procurement frameworks.
- Plate Readers:Detection modules integrate absorbance, fluorescence, and luminescence measurements for assay endpoint analysis. Academic screening centers in the Netherlands deploy these for CRISPR validation studies.
- Sample Storage Solutions:Automated biorepositories manage temperature-controlled specimen archiving with barcode tracking. French university hospitals invest in these for longitudinal clinical study retention under CNIL data governance requirements.
Mature deployment sits with automated pipetting systems. Newer deployment is concentrated in liquid handling robots.
End User:
Procurement sophistication and validation burden separate customer tiers across the European automation landscape.
- Pharmaceutical Companies:Integrated quality systems and centralized purchasing functions drive specification of GMP-compliant platforms. Swiss and German headquarters consolidate automation decisions across distributed manufacturing sites.
- Clinical Laboratories:Diagnostic throughput pressures and IVDR compliance deadlines accelerate platform replacement cycles. French and United Kingdom laboratories lead procurement volume for automated sample processing.
- Academic Institutions:EU research infrastructure funding prioritizes digital laboratory investments. Dutch and Danish screening centers pilot microfluidic automation for genomic library preparation.
- Research Organizations:Heidelberg and Munich CRO clusters generate concentrated demand for robotic workstations with flexible protocol reconfiguration capabilities.
Revenue concentration rests with pharmaceutical companies. Volume expansion is climbing the fastest in academic institutions.
Technology:
Software integration depth and miniaturization capability define competitive positioning within each technology layer.
- Artificial Intelligence:Machine-learning modules embedded in liquid handling systems reduce protocol development time and enable adaptive assay optimization. German notified bodies extend review timelines for platforms exceeding EU AI Act Class IIa thresholds.
- Microfluidics:Digital microfluidic platforms absorb discrete pipetting steps, enabling reaction miniaturization that cuts reagent consumption. Netherlands academic centers pilot these for CRISPR workflows.
- Robotics:Kinematic systems integrate with laboratory information management systems for full workflow automation. German vendors compete for scarce mechatronics engineering talent to advance these platforms.
- Lab-on-a-Chip:Integrated microfabricated devices consolidate sample preparation and analysis on single substrates. French pharmaceutical research sites evaluate these for point-of-care diagnostic development.
Commercial maturity clusters around robotics. Patent activity and pilot deployments are expanding most quickly in artificial intelligence.
Application:
Regulatory stringency and data reproducibility requirements shape automation specifications across use cases.
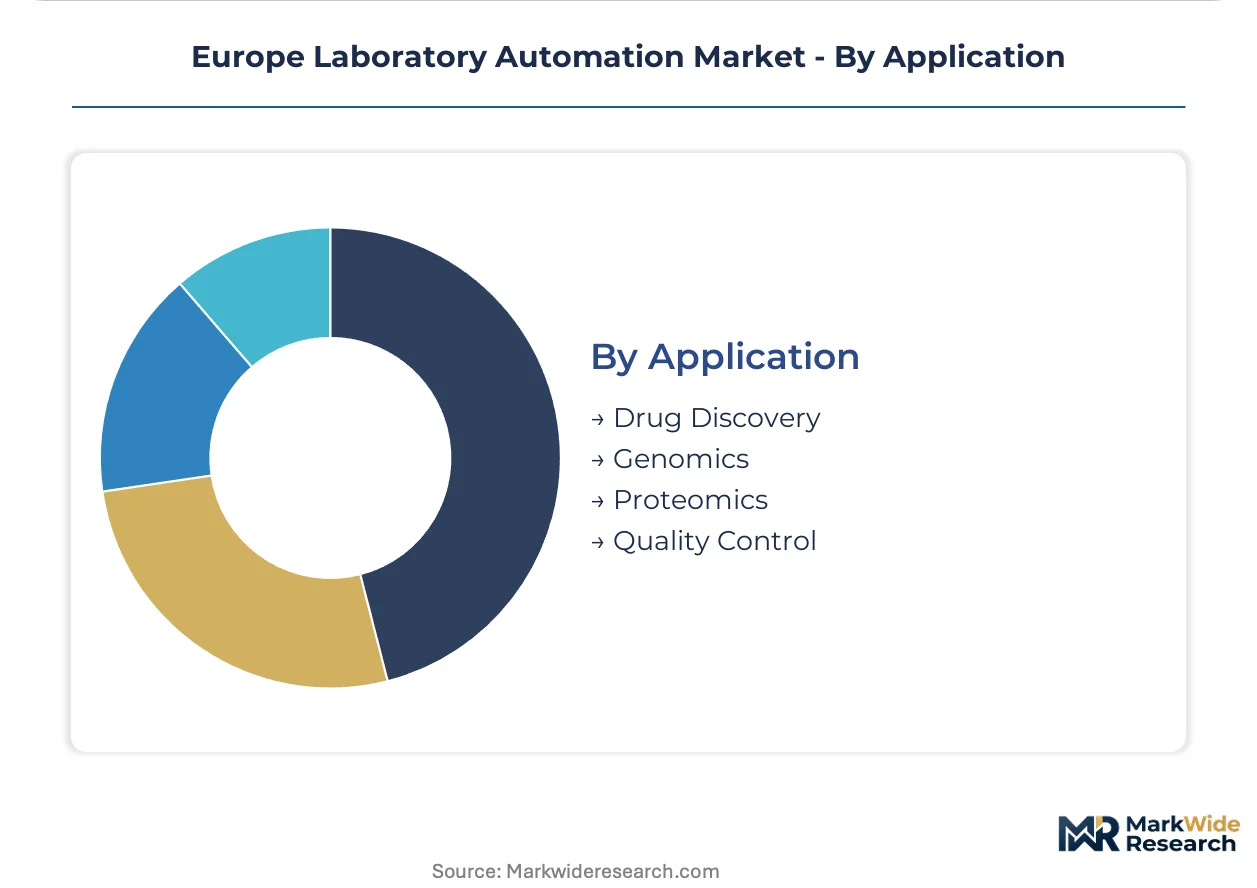
- Drug Discovery:High-throughput screening demands 24-hour robotic operation with plate handling speeds exceeding thousands of compounds daily. German CRO infrastructure concentrates demand for integrated screening platforms.
- Genomics:Next-generation sequencing library preparation requires precise reagent dispensing and contamination control. French research hospitals automate these workflows for precision medicine initiatives.
- Proteomics:Mass spectrometry sample preparation benefits from standardized liquid handling protocols. Swiss biotech clusters deploy automation to reduce manual variability in biomarker quantification.
- Quality Control:GMP-compliant documentation and batch release testing drive validated automation in pharmaceutical manufacturing. United Kingdom contract manufacturers invest following MHRA inspection emphasis on data integrity.
Established automation penetration sits with drug discovery. Investment momentum is gaining share fastest in genomics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics and mechatronics engineering talent concentrate in southern Germany and northern Switzerland, anchoring the continent's instrument manufacturing base for liquid handling and detection systems.
Germany
Contract research organizations in Munich and Heidelberg drive procurement of robotic workstations for 24-hour unattended screening workflows. The country's national pharmaceutical regulator enforces GMP-compliant documentation standards that compress vendor selection cycles. Bavaria's dense biotech cluster around Martinsried displaces manual protocols with AI-integrated sample handling platforms.
United Kingdom
Post-Brexit regulatory flexibility enables pilot deployments of novel automation architectures ahead of EU CE marking. MHRA inspection emphasis on data integrity accelerates investment in validated quality control automation. The Oxford-Cambridge arc concentrates demand for genomic library preparation systems serving precision medicine initiatives.
France
Diagnostic laboratories accelerate platform replacements to meet IVDR compliance deadlines, pulling forward demand for automated sample processing. ANSM enforces country-specific quality protocols for national tender participation. The Paris-Saclay research cluster evaluates microfluidic-AI convergence platforms for real-time assay optimization.
Switzerland
Swiss pharmaceutical headquarters centralize automation specifications across distributed European manufacturing sites. Swissmedic maintains stringent device approval timelines that favor pre-validated platform suppliers. The Zürich-Basel corridor dominates automated pipetting technology through integrated hardware-software portfolios.
Netherlands
Academic screening centers in Leiden and Utrecht pilot digital microfluidic platforms for CRISPR library preparation. EU research infrastructure funding prioritizes digital laboratory investments at Dutch universities. The Randstad biotech cluster absorbs discrete pipetting steps through reaction miniaturization technologies.
Europe Laboratory Automation Market Key Industry Players
Global majors compete with regional champions across precision engineering and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated life science conglomerates controlling full workflow stacks, specialized automation houses dominating discrete liquid handling functions, and emerging microfluidics players capturing niche volume-precision applications. Dominant competitive moves include portfolio diversification into AI-embedded software layers and strategic partnerships with academic screening centers for pilot deployment validation.
Among Swiss-engineered platform specialists, Tecan Group exemplifies the precision automation archetype through its dominance in automated pipetting across German pharmaceutical labs. PerkinElmer occupies a position representing detection and imaging specialization that anchors presence in genomic screening workflows. Danaher Corporation sits within the integrated conglomerate tier, extending control over sample preparation and analytical automation through its Beckman Coulter and Cytiva assets.
| Leading Market Players |
|---|
| Tecan Group |
| PerkinElmer |
| Danaher Corporation |
| Roche Diagnostics |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Eppendorf |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Mechatronics engineering talent concentration in southern Germany and northern Switzerland generates labor-cost differentials that widen pricing-tier spreads between precision-engineered robotic platforms and standardized pipetting systems. EMA compliance documentation requirements add validation overhead that vendors pass through to pharmaceutical buyers, compressing margins for mid-tier clinical laboratories in Southern Europe.
Pricing Analysis
Service-bundling unbundling now separates hardware transactions from multi-year validation support contracts across German CRO procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and software integration depth as primary differentiation drivers. Cost compression in economy-tier clinical systems is intensifying because mid-sized Southern European laboratories demand compressed ROI timelines. Academic institutions in the Netherlands and Denmark exhibit highest price sensitivity, while Swiss pharmaceutical headquarters demonstrate lowest sensitivity due to centralized TCO-based procurement.
Supply Chain Analysis
Dual-sourcing requirements mandated by German pharmaceutical manufacturers for precision optics components constrain single-source dependency risks in automated detection modules. Manufacturing concentration rests on Germany, Switzerland, and the United States for high-resolution imaging subsystems and robotic kinematics. Supply chains draw from fluorinated polymer suppliers facing ECHA REACH restrictions, precision-machined aluminum housings, and semiconductor-grade sensors. Tariff exposure on Swiss-engineered components shipped into EU member states creates procurement friction. Distribution runs through authorized dealer networks serving national tender processes, with direct OEM relationships dominating high-volume pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained mechatronics engineering capacity props pricing power for vendors controlling precision manufacturing capabilities, as German automation OEMs compete for scarce talent capable of integrating robotic kinematics with EU AI Act-compliant software validation.
For Market Incumbents: Cement control over liquid handling robotics through captive production of precision pipetting components in Bavaria, insulating margin structures from fluorinated polymer supply restrictions. Acquire specialized microfluidics capabilities to preempt displacement of fixed-tip pipetting by digital microfluidic platforms in Dutch academic screening centers. For New Entrants and Emerging Players: Enter via AI-embedded protocol optimization software serving French diagnostic laboratories awaiting clarity on EU AI Act Class IIa conformity pathways. Target United Kingdom hospital networks leveraging post-Brexit regulatory flexibility for pilot deployments of novel automation architectures not yet CE-marked. Pursue academic partnership validation models at Leiden and Utrecht screening centers to establish reference installations. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated precision automation specialists given EMA IVDR compliance deadline pull-forward effects on replacement demand. Long-term viability favors vendors controlling both hardware manufacturing and software validation documentation capabilities. Watch German notified body review timeline extensions for machine-learning diagnostic platforms as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Platform Development | Machine-learning modules embedded in Tecan and PerkinElmer systems reduce protocol development time for German biotech clusters. |
| Microfluidics Capability Acquisition | Digital microfluidic platforms absorb pipetting steps at Netherlands academic centers, threatening conventional robotic arm suppliers. |
| EU AI Act Pre-Certification | Early Class IIa validation documentation accelerates tender participation across German university hospital procurement processes. |
| Post-Brexit UK Pilot Deployments | MHRA regulatory flexibility enables novel automation architectures ahead of EU CE marking timelines. |
| Precision Optics Dual-Sourcing | German manufacturers mitigate single-source vulnerability through qualified secondary suppliers for high-resolution imaging components. |
Research Approach
EMA regulatory filings, EU Medical Device Regulation guidance documents, and ECHA substance restriction databases formed the secondary backbone, supplemented by customs trade data on precision instrument imports. Primary interviews with automation platform engineers, pharmaceutical quality assurance directors, CRO procurement managers, and German notified body representatives validated demand assumptions. Bottom-up and top-down triangulation reconciled vendor shipment data with end-user procurement records across Munich, Heidelberg, and Zürich biotech clusters.
Bottom-up modeling built country-level forecasts from individual platform category growth rates, while top-down analysis cross-checked aggregate market sizing against EU research infrastructure funding allocations. Segmentation dimensions spanned product type, end-user sophistication tier, technology integration depth, and application regulatory stringency. CAGRs derived from instrument replacement cycle analysis and EMA compliance deadline impacts. Forecast inputs included IVDR implementation timeline adherence rates and AI-embedded system adoption curves across French and German diagnostic networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA fluorinated polymer restriction expansions or EU AI Act risk-classification threshold revisions. Forecasts reflect assumptions on EMA audit trail documentation requirements and REACH substance limit evolution. A model refresh is warranted upon material change in German notified body review timelines for machine-learning diagnostic components.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Italy Marketing Automation Software Market
Automation
Global Field Force Automation Market
Automation
Helpdesk Automation Market
Automation
Indonesia Automation and Control System Market
Automation
US Workload Scheduling and Automation Market
Automation
Voice Picking Solutions Market
Automation
Modular Laboratory Automation Market
Automation
Global Cloud Automation Market
Automation
Universal Process Control Market
Automation
Elevator Control Market
Automation
Playout Automation Market
Automation
Global Zig-Bee Automation Market
Automation
Postal Automation System Market
Automation
Database Automation Market
Automation
Home Automation and Controls Market
Automation
Self Bag Drop Machine Market