
 E-Commerce Fulfillment Services Market | 2026-2036
E-Commerce Fulfillment Services Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Fulfillment Services Market Intelligence
India is fragmenting its fulfillment infrastructure across tier-two cities and industrial corridors outside Mumbai, Delhi, and Bangalore. Amazon.com, Inc. leverages captive warehouse networks to dominate last-mile density in North America. ShipBob, Inc. competes through distributed micro-fulfillment centers that position inventory within two-day delivery zones for mid-market merchants. FedEx sustains cross-border customs brokerage as a differentiated service layer against pure-play warehouse operators.
E-commerce fulfillment services encompass the integrated physical and digital infrastructure that receives, stores, processes, and dispatches online orders through automated sortation systems, warehouse management software, and multi-carrier shipping APIs. These services reduce order cycle times from click to delivery while minimizing inventory carrying costs for merchants lacking owned logistics assets. Warehousing and shipping together capture the largest value pools, though automation and AI within the technology segment represent the fastest-expanding margin opportunity as labor costs rise. Software solutions for inventory orchestration now determine competitive outcomes more than square footage alone, particularly for merchants selling across online stores and marketplaces simultaneously.
The EU's Digital Services Act and GDPR impose data governance obligations on fulfillment platforms processing consumer order information across borders. India's FSSAI and BIS standards regulate temperature-controlled storage for food and electronics categories respectively, shaping warehouse certification requirements. Stakeholders must monitor how platform liability rules and product safety certifications evolve, as compliance architecture will separate investable operators from stranded capacity.
Market Dynamics
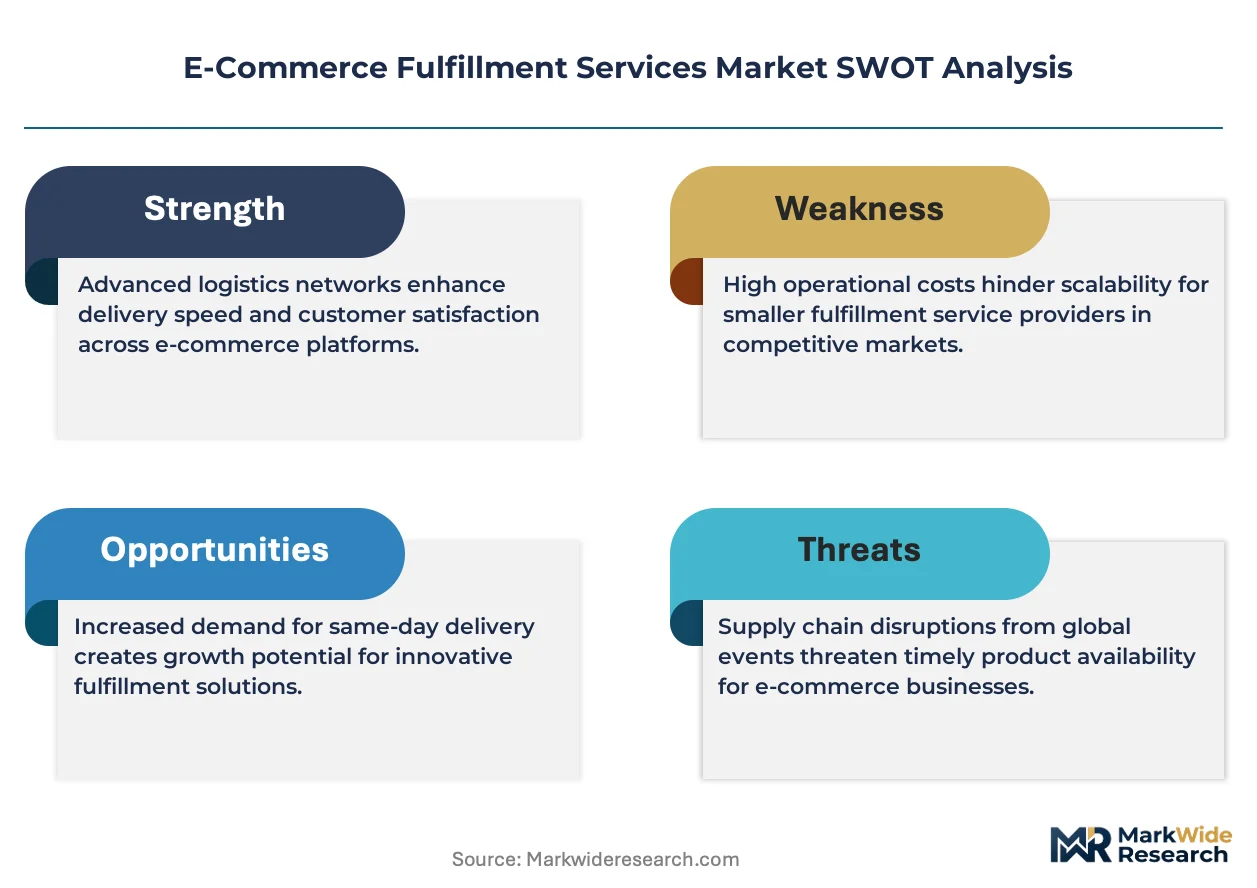
Same-day delivery promises from omnichannel retailers are compressing order cycle times and forcing fulfillment networks toward distributed micro-fulfillment nodes positioned within dense urban corridors rather than centralized regional hubs.
Growth Catalysts
- GDPR and EU Digital Services Act:Data governance mandates on cross-border order processing create compliance-driven demand for certified fulfillment platforms with auditable data architectures.
- Automated sortation systems:Robotic put-away and pick-to-light technologies reduce labor dependency in high-wage European and North American markets.
- India's tier-two urban corridors:Domestic e-commerce platforms expanding beyond Mumbai, Delhi, and Bangalore require localized warehouse certification under FSSAI and BIS standards.
Market Restraints
- Last-mile labor cost inflation:Wage pressure in Germany, the United Kingdom, and Japan compresses margins on free-shipping guarantees.
- Customs brokerage concentration:Cross-border e-commerce depends on a limited pool of licensed customs brokers in the United States and European Union.
- Warehouse automation capex intensity:Autonomous mobile robots and warehouse management software require capital deployment that mid-market merchants cannot self-fund.
Strategic Opportunities
- India's industrial corridors:Greenfield warehouse development in Pune, Hyderabad, and Ahmedabad offers first-mover positioning ahead of saturation in tier-one cities.
- CE marking convergence:Unified product safety certification across EU member states simplifies cross-border inventory pooling for electronics and medical device categories.
- Temperature-controlled pharma storage:Cold chain infrastructure for biologics and vaccines remains underdeveloped in Southern Europe and Eastern Europe.
Industry Challenges
- Warehouse management system integration:Legacy ERP architectures in established retailers resist API-based inventory orchestration with marketplace platforms.
- Multi-carrier shipping optimization:Real-time rate shopping across postal, parcel, and express networks requires data engineering capabilities scarce outside technology-native operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Fulfillment Services Market |
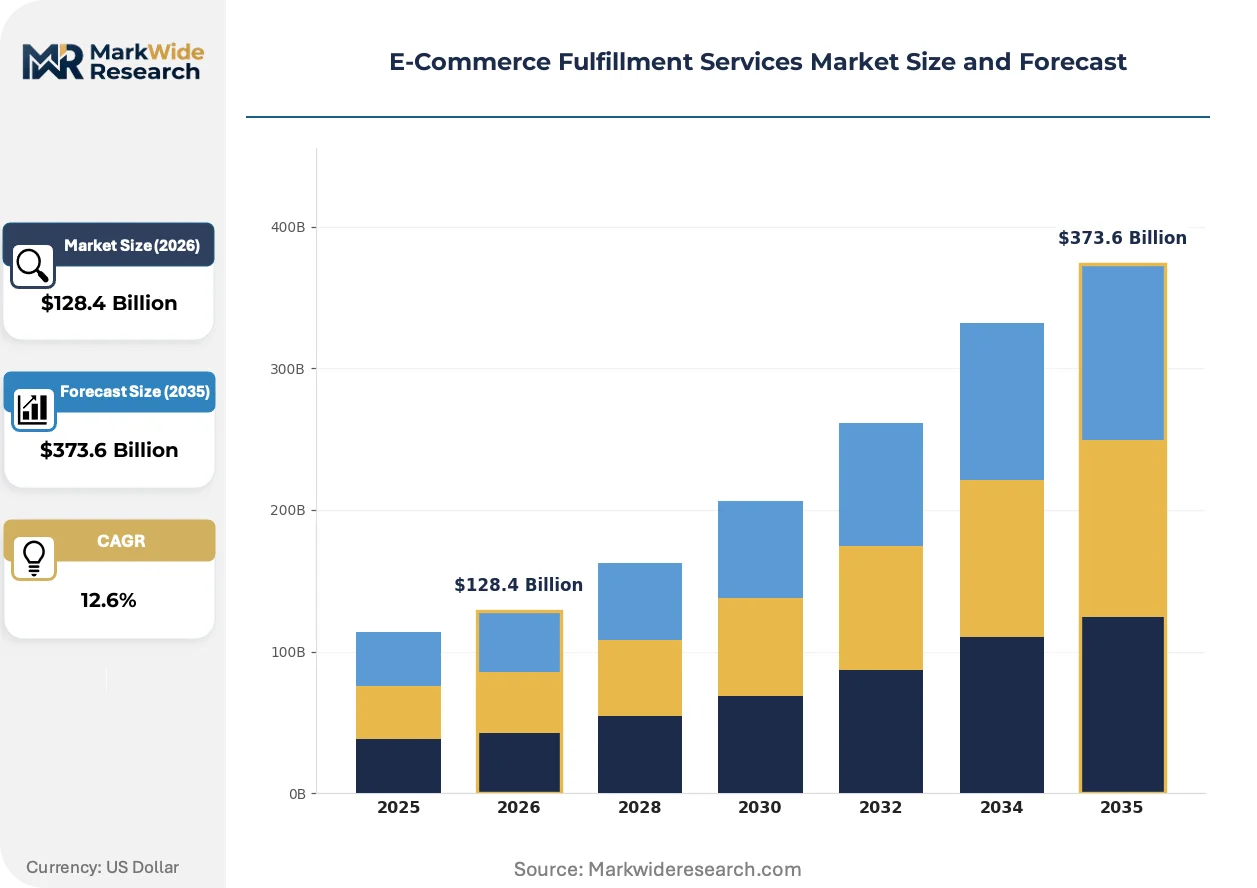
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $373.6 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Picking, Packing, Shipping Distribution Channel: Online Store, Mobile App, Marketplaces, Social Media End User: Small Businesses, Large Enterprises, Startups, Non-Profits Technology: Automation, Software Solutions, AI, IoT |
| Companies Covered | Amazon.com, Inc., ShipBob, Inc., FedEx, United Parcel Service of America, Inc., eFulfillment Service, Inc., Ingram Micro, Inc., Rakuten Super Logistics, Red Stag Fulfillment, Shipfusion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Fulfillment Services Market Strategic Shifts & Innovations
Artificial intelligence and warehouse robotics are compressing the gap between order capture and dispatch, while regulatory data governance and shifting merchant procurement models reshape competitive requirements.
Autonomous mobile robots equipped with machine vision are digitizing inventory movement within fulfillment centers. Mid-market apparel and consumer electronics merchants in the United States and Germany are deploying these systems at scale to offset wage inflation. The technology is digitizing labor allocation decisions that previously required human supervisors, enabling 24-hour operations in markets with restrictive labor regulations.
The EU's Digital Services Act imposes platform liability on logistics intermediaries processing consumer data across borders. Fulfillment operators must now maintain auditable data processing records and designate legal representatives in member states where they lack physical presence. Small and mid-sized marketplace sellers in France and Italy face compliance costs that favor partnership with larger certified platforms over independent warehouse arrangements.
Merchant procurement of fulfillment services is fragmenting from single-provider contracts toward multi-node strategies. Direct-to-consumer brands in the United Kingdom and Netherlands now distribute inventory across three or more warehouse locations to guarantee delivery speed promises. This pattern is most visible in fashion and beauty verticals where return rates exceed 30 percent and proximity to consumers reduces reverse logistics costs.
E-Commerce Fulfillment Services Market Segmentation
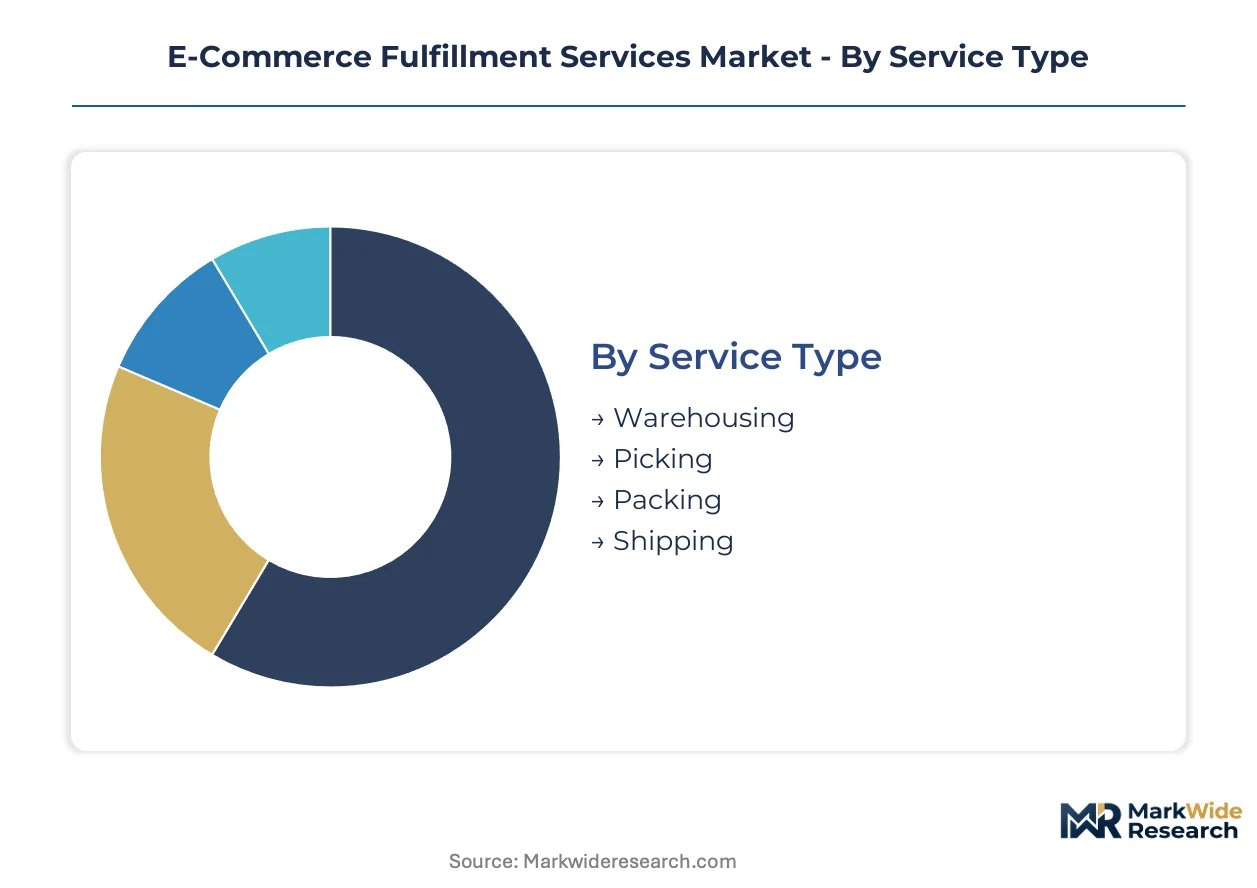
Segmentation in e-commerce fulfillment services reveals how operational complexity, channel diversity, and technology intensity create distinct value pools. Merchants select service configurations based on order velocity, SKU complexity, and delivery speed guarantees rather than one-size-fits-all contracts.
Service Type:
Cost tier differentiates fulfillment economics from fixed warehousing through variable picking and packing charges to hybrid shipping models.
- Warehousing:Climate-controlled storage infrastructure with bonded and non-bonded configurations handles inventory positioning for seasonal demand spikes. Concentrated demand from omnichannel apparel merchants in Germany and the United Kingdom drives requirements for flexible square footage contracts with 30-day cancellation terms.
- Picking:Order assembly operations combining zone-based batch picking with discrete order fulfillment reduce labor minutes per unit. Demand clusters around high-SKU-count electronics and beauty merchants in the United States requiring same-day cut-off extensions.
- Packing:Customized packaging workflows insert branded materials and right-size boxes to minimize dimensional weight charges. Sustainability mandates from France's AGEC law and Germany's Packaging Act reshape material specifications toward recycled content minimums.
- Shipping:Multi-carrier rate shopping and label generation integrate postal, parcel, and express networks through unified APIs. Cross-border merchants into the European Union depend on customs pre-clearance capabilities to meet delivery promises.
Warehousing commands the established base. The steepest expansion runs through picking automation as labor costs climb.
Distribution Channel:
Application context determines fulfillment workflow complexity from direct merchant control to platform-mediated transactions.
- Online Store:Merchant-owned websites with customized checkout flows require flexible API integrations for inventory synchronization and order routing. Direct-to-consumer brands in the Netherlands and United Kingdom prioritize warehouse management systems with real-time stock visibility across multiple nodes.
- Mobile App:Native application purchases with push notification delivery tracking demand lightweight SDK implementations and geolocation-based delivery estimation. Quick-commerce grocery operators in India's tier-two cities drive sub-two-hour fulfillment infrastructure investment.
- Marketplaces:Third-party platform sales through Amazon, Flipkart, and Zalando impose strict SLA requirements for shipping confirmation and delivery tracking upload. Compliance architecture separates qualified operators from suspended seller accounts.
- Social Media:In-app checkout through Instagram Shopping and TikTok Shop creates impulse purchase patterns with elevated return rates. Beauty and fashion verticals in the United Kingdom show 35-40 percent return incidence requiring proximal reverse logistics capacity.
Marketplaces anchor current volume concentration. Social commerce is climbing the fastest as discovery-to-purchase friction collapses.
End User:
Customer scale and procurement maturity shape service tier selection from self-serve software to dedicated account management.
- Small Businesses:Merchants with under 1,000 monthly orders prioritize all-inclusive per-unit pricing and minimal integration overhead. Shopify and WooCommerce plugin ecosystems dominate procurement in North American and European micro-merchant segments.
- Large Enterprises:High-volume retailers with complex SKU hierarchies negotiate dedicated warehouse space and custom SLA frameworks. Multi-node inventory distribution across three or more locations is now standard for fashion and electronics merchants in the United Kingdom and Germany.
- Startups:Venture-backed direct-to-consumer brands prioritize speed-to-market over unit economics, accepting premium fulfillment costs for rapid geographic expansion. India's domestic e-commerce platforms provide subsidized fulfillment to capture emerging brand relationships.
- Non-Profits:Donation-driven and mission-aligned merchants require cost-minimized solutions with transparent fee structures and carbon offset options. European charitable organizations face CSRD reporting requirements on supply chain emissions.
Large enterprises command the established base. Startups are gaining share fastest as venture funding cycles accelerate brand launches.
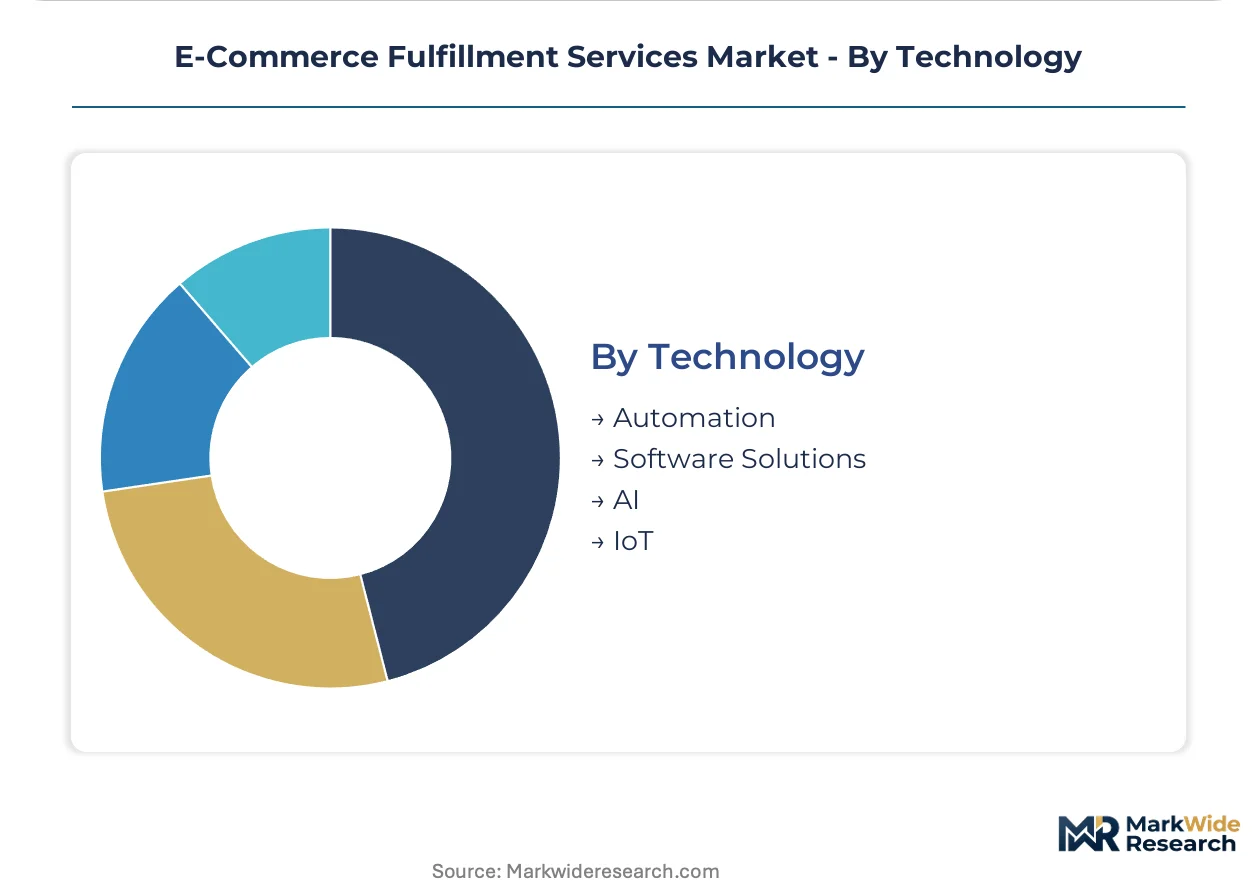
Technology:
Technology maturity separates labor-dependent operations from software-defined fulfillment networks with predictive capability.
- Automation:Autonomous mobile robots and robotic put-away systems digitize inventory movement within fulfillment centers. Deployment concentrates in high-wage German and United States markets where labor cost inflation exceeds 5 percent annually.
- Software Solutions:Warehouse management systems and order management platforms orchestrate inventory across multiple nodes with real-time visibility. API-first architectures determine competitive outcomes for merchants selling across online stores and marketplaces simultaneously.
- AI:Machine learning models optimize demand forecasting, labor scheduling, and delivery route planning from historical order patterns. Predictive inventory positioning reduces stockout incidence for seasonal apparel and electronics categories.
- IoT:Sensor networks track temperature, humidity, and location for high-value and perishable inventory segments. Pharmaceutical and fresh food merchants in Southern Europe require cold chain verification under GDP and HACCP standards.
Software solutions command the established base. AI is expanding most quickly as margin pressure demands predictive optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys fulfillment infrastructure for sub-two-hour grocery delivery, while Germany and the United States prioritize automated warehouse robotics to offset labor costs. This consumption-mix differential reflects divergent wage structures and urban density patterns.
United States
Mid-market merchants drive demand for distributed micro-fulfillment nodes within two-day delivery zones. OSHA warehouse safety standards and FTC consumer protection rules shape operator certification requirements. Chicago and Dallas industrial corridors host the densest concentration of automated sortation facilities serving omnichannel apparel brands.
Germany
Same-day delivery promises from fashion retailers compress order cycle times and force urban micro-fulfillment investment. REACH chemical safety regulations and the Packaging Act mandate recycled content minimums for outbound shipments. The Rhine-Ruhr and Stuttgart industrial regions concentrate temperature-controlled pharma storage under GDP standards.
India
Domestic e-commerce platforms expand fulfillment networks into Pune, Hyderabad, and Ahmedabad as tier-two urban corridors mature. FSSAI food safety standards and BIS electronics certification shape warehouse licensing requirements. Bangalore's Whitefield corridor anchors automated warehouse development for quick-commerce grocery operators.
United Kingdom
Direct-to-consumer brands distribute inventory across three or more warehouse nodes to guarantee delivery speed and minimize reverse logistics costs. CSRD emissions reporting requirements extend to supply chain partners. The Midlands logistics triangle and London periphery dominate multi-node fulfillment configuration for fashion and beauty verticals.
Japan
Labor cost inflation and restrictive employment regulations accelerate autonomous mobile robot deployment in fulfillment centers. METI industrial standards guide warehouse automation investment. The Kanto region surrounding Tokyo maintains the highest last-mile density for same-day delivery infrastructure serving dense urban populations.
E-Commerce Fulfillment Services Market Key Industry Players
Capability concentration sits with technology-native operators possessing AI-driven inventory orchestration; scale advantage sits with logistics incumbents commanding captive warehouse networks and customs brokerage licenses. The market structures around three tiers: integrated platform operators, pure-play fulfillment specialists, and carrier-affiliated warehouse networks. Dominant competitive moves include multi-node geographic expansion and strategic partnerships with marketplace platforms to secure merchant volume commitments.
Within the integrated platform tier, Amazon.com, Inc. exemplifies captive infrastructure control through owned warehouse networks and last-mile density. ShipBob, Inc. and Rakuten Super Logistics occupy positions among pure-play specialists serving mid-market merchants through distributed micro-fulfillment models. FedEx represents carrier-affiliated competitive positioning, leveraging cross-border customs brokerage as a differentiated service layer against warehouse-only operators.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| ShipBob, Inc. |
| FedEx |
| United Parcel Service of America, Inc. |
| eFulfillment Service, Inc. |
| Ingram Micro, Inc. |
| Rakuten Super Logistics |
| Red Stag Fulfillment |
| Shipfusion Inc. |
| Others |
Cost & Logistics Intelligence
Warehouse undercapacity in India's tier-two corridors is compressing contract terms and forcing merchants toward premium guaranteed-space agreements. This utilization squeeze simultaneously elevates pricing power for certified operators and accelerates automation capex as labor arbitrage fades.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with spot pricing emerging for seasonal overflow capacity in North American peak periods. Three-tier pricing structure across premium SLA, standard fulfillment, and economy deferred-delivery levels differentiates based on cut-off time guarantees and returns handling. Cost compression in mid-market segments is intensifying because Amazon's captive network sets reference pricing. Small businesses show highest price sensitivity, while venture-backed startups accept premium rates for speed-to-market.
Supply Chain Analysis
Tariff exposure between the United States and China is reshaping inventory positioning strategies for cross-border merchants. Warehouse automation hardware draws from Germany, Japan, and South Korea, while software solutions rest on cloud infrastructure concentrated in the United States and Ireland. Single-source vulnerability in customs brokerage licensing creates chokepoints for EU-bound shipments. Distribution runs through hub-and-spoke networks with last-mile density determining final-mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-commerce fulfillment sector is experiencing high-growth disruption as same-day delivery promises compress order cycle times and AI-driven inventory orchestration displaces legacy warehouse management paradigms.
For Market Incumbents: Entrench market position through captive last-mile density investments in North American urban corridors and accelerated certification under India's FSSAI and BIS standards. Automation capex in German and United States facilities offsets wage inflation threatening margin structures. API-first warehouse management architectures defend against technology-native entrants. For New Entrants and Emerging Players: Temperature-controlled pharma storage in Southern and Eastern Europe represents the most penetrable entry point given underdeveloped cold chain infrastructure. India's industrial corridors around Pune and Ahmedabad offer greenfield warehouse development ahead of saturation. Partnership with quick-commerce grocery operators provides volume anchor for sub-two-hour fulfillment networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated micro-fulfillment segments as autonomous mobile robot deployment scales. Long-term viability over the next decade favors operators with multi-node geographic presence and certified compliance architectures. Acquisition targets should demonstrate auditable data processing records under GDPR and EU Digital Services Act requirements. The signal to watch is merchant procurement fragmentation toward three or more warehouse nodes per brand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Node Geographic Expansion | Three or more warehouse locations guarantee delivery speed promises for UK fashion merchants. |
| API-First Platform Integration | Real-time inventory synchronization across online stores and marketplaces determines competitive outcomes. |
| Automation Technology Licensing | Robotic put-away systems reduce labor dependency in high-wage German and North American markets. |
| Cold Chain Infrastructure Partnership | GDP-certified temperature-controlled storage addresses biologics demand in Southern Europe. |
| Customs Brokerage Capability Acquisition | Licensed cross-border clearance differentiates against pure-play warehouse operators in EU markets. |
Research Approach
Initial hypotheses were tested against primary input from warehouse operations directors, e-commerce merchant procurement leads, logistics technology architects, and customs brokerage specialists and refined through secondary validation. Stakeholder interviews combined with customs trade databases, SEC filings from publicly traded operators, EU regulatory submission records, and Indian FSSAI certification registries. Bottom-up merchant demand modeling and top-down infrastructure capacity assessment provided triangulation.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions included service type, distribution channel, end-user scale, and technology maturity tier. CAGRs were derived from historical fulfillment volume trajectories and forward infrastructure investment pipelines. Forecast inputs incorporated labor cost inflation differentials and regulatory compliance cost burdens across geographies.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions on automation adoption curves and platform liability rule evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
FMCG B2B E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
United States E-Commerce Market