
 Mexico Surveillance Camera Market | 2026-2036
Mexico Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Surveillance Camera Market Insights
Video surveillance distribution is tilting toward system integrators and cloud-managed service providers as end-users shift from capital expenditure to operational expenditure models. Hangzhou Hikvision Digital Technology Co., Ltd. anchors its Mexico presence through localized warehousing and technical support centers. Dahua Technology Co., Ltd. competes aggressively on price-performance ratios in the mid-tier commercial segment. Axis Communications AB differentiates through cybersecurity-hardened firmware and open-platform architecture.
Surveillance cameras in Mexico encompass fixed and pan-tilt-zoom imaging devices that capture, encode, and transmit visual data over coaxial, Ethernet, or wireless networks, typically operating at resolutions from 2MP to 8MP with H.265 compression and ONVIF protocol compliance for interoperability. These systems serve commercial loss prevention, municipal public safety, and critical infrastructure perimeter monitoring. IP Cameras command the dominant share of new installations as analog infrastructure reaches end-of-life replacement cycles. Wireless technology segments are expanding fastest in retail and logistics campuses where trenching costs for cable runs prove prohibitive. Government end-user procurement remains the deepest margin pool due to bundled service requirements and certification barriers.
CONAPRED guidelines and municipal data protection protocols shape how surveillance operators manage biometric capture and citizen privacy in public deployments. Mexico's federal telecommunications regulator imposes equipment homologation requirements that filter non-certified hardware from official procurement channels. Stakeholders must monitor evolving municipal smart city ordinances that increasingly mandate encrypted storage and audit-ready footage retention policies.
Market Dynamics
IP camera infrastructure is displacing analog coaxial systems across Mexican commercial and municipal deployments, compressing replacement cycles and redistributing value capture toward system integrators capable of managing hybrid network transitions.
Growth Catalysts
- Smart city infrastructure mandates:Mexico City, Guadalajara, and Monterrey have enacted municipal ordinances requiring encrypted video retention and centralized command centers for public safety corridors.
- Commercial loss prevention budgets:Banking and retail verticals in Mexico are expanding capital allocations for perimeter monitoring and facial recognition integration at branch networks.
- CONAPRED privacy compliance frameworks:Federal guidelines on biometric data handling are creating certified procurement channels that filter non-compliant hardware from official tenders.
Market Restraints
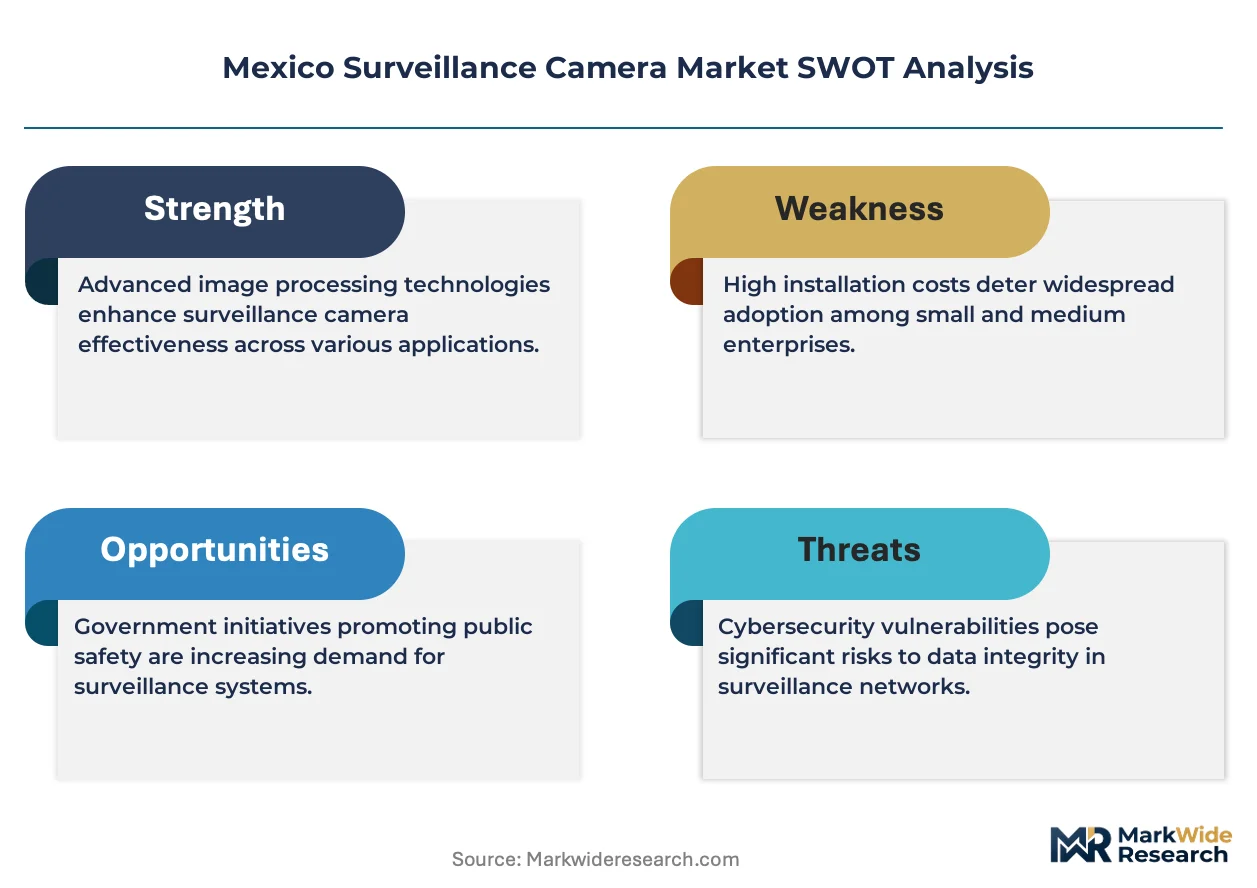
- Semiconductor input volatility:Image sensor and SoC pricing fluctuations from East Asian foundries compress hardware margins for distributors serving price-sensitive mid-tier commercial segments.
- Homologation certification timelines:Mexico's federal telecommunications regulator enforces equipment approval processes that delay product launches by 4-8 months for non-domestic manufacturers.
- Legacy analog infrastructure lock-in:Existing coaxial cable plant in older commercial buildings and government facilities creates switching cost barriers for full IP migration.
Strategic Opportunities
- Wireless campus deployments:Retail and logistics operators in Baja California and Nuevo León are adopting battery-powered and solar-enabled cameras where trenching costs for Ethernet runs exceed hardware expenditure.
- Cloud-managed service models:Small and mid-sized commercial end-users are migrating from capital purchase to subscription-based video surveillance-as-a-service through regional system integrators.
- Critical infrastructure perimeter monitoring:Energy and transportation authorities are expanding thermal imaging and analytics-enabled deployments at pipeline corridors and port facilities.
Industry Challenges
- Cybersecurity firmware expertise:Local system integrators face capability gaps in hardening camera firmware against network intrusion, creating dependency on vendor-provided security patches.
- Interoperability standardization delays:Incomplete ONVIF Profile T adoption across Mexican-installed base complicates multi-vendor system architecture and centralized management platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Surveillance Camera Market |
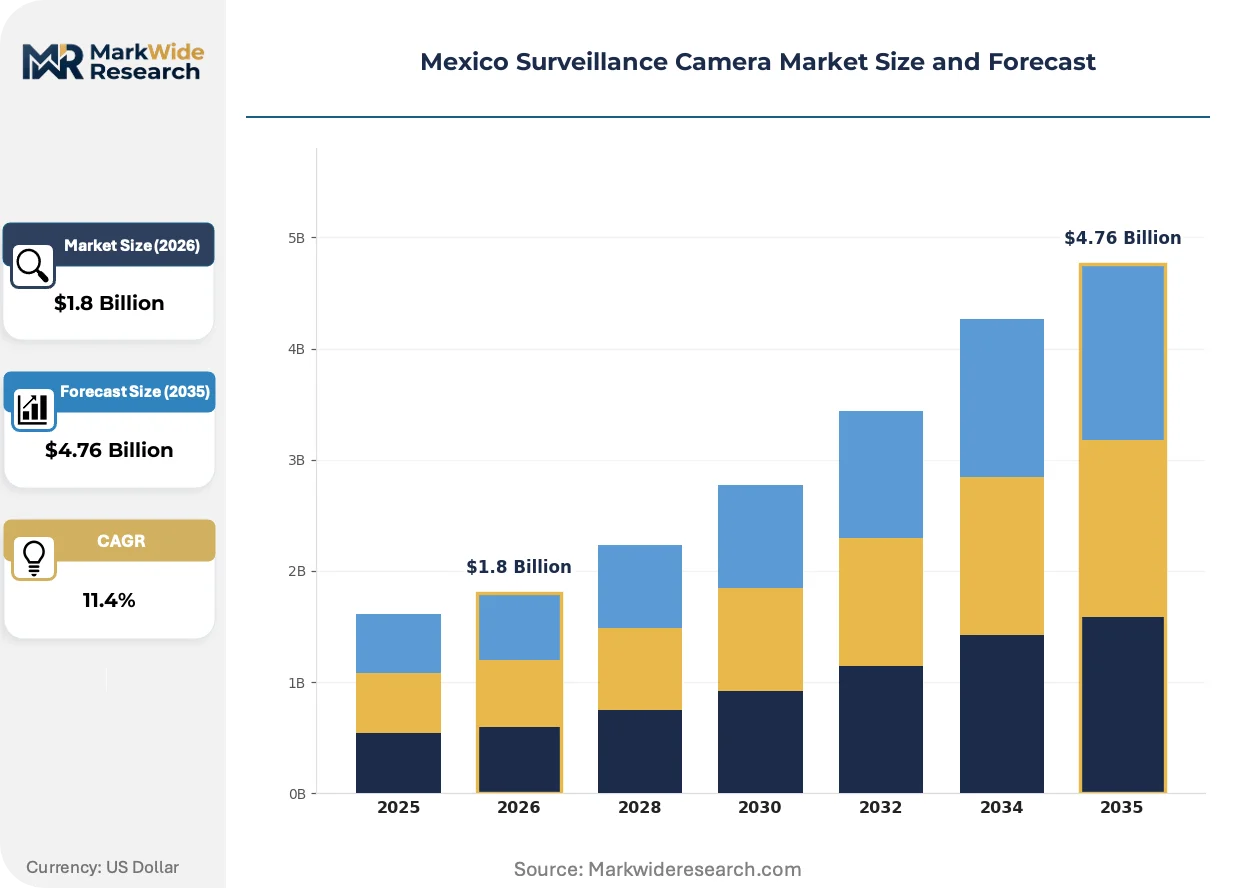
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Analog Cameras, PTZ Cameras, Thermal Cameras Technology: Wired, Wireless, Optical, Infrared End User: Commercial, Residential, Industrial, Government Installation Type: Indoor, Outdoor, Covert, Public Space |
| Companies Covered | Axis Communications AB, Bosch Security Systems Incorporated, Dahua Technology Co., Ltd, Hangzhou Hikvision Digital Technology Co., Ltd., Panasonic Corporation, Eagle Eye Networks, Honeywell International Inc, Motorola Solutions, Inc., Arlo Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Surveillance Camera Market Trends and Innovations
Edge analytics processing is redistributing computational load from centralized servers to camera hardware, enabling real-time event detection without bandwidth saturation of municipal fiber networks.
Artificial intelligence inference engines embedded at the camera level are migrating from server-based architectures to on-device chipsets. Large retail operators in Mexico City and Guadalajara are deploying these units for occupancy counting and queue management. This compression of processing geography is reducing latency for loss prevention alerts and lowering recurring cloud storage expenditure.
CONAPRED guidelines on biometric data protection are mandating encrypted storage and access audit trails for public space deployments. Municipal procurement specifications now require hardware vendors to demonstrate compliance before tender eligibility. Banking and transportation verticals are responding by prioritizing firmware-hardened platforms with tamper-evident logging capabilities.
Buyer preference is gravitating toward bundled installation and maintenance contracts rather than discrete hardware procurement. Regional system integrators in Nuevo León and Jalisco are capturing this shift by offering multi-year service agreements with guaranteed uptime commitments. This transformation is most visible among mid-tier commercial operators lacking internal IT security expertise.
Mexico Surveillance Camera Market Segmentation
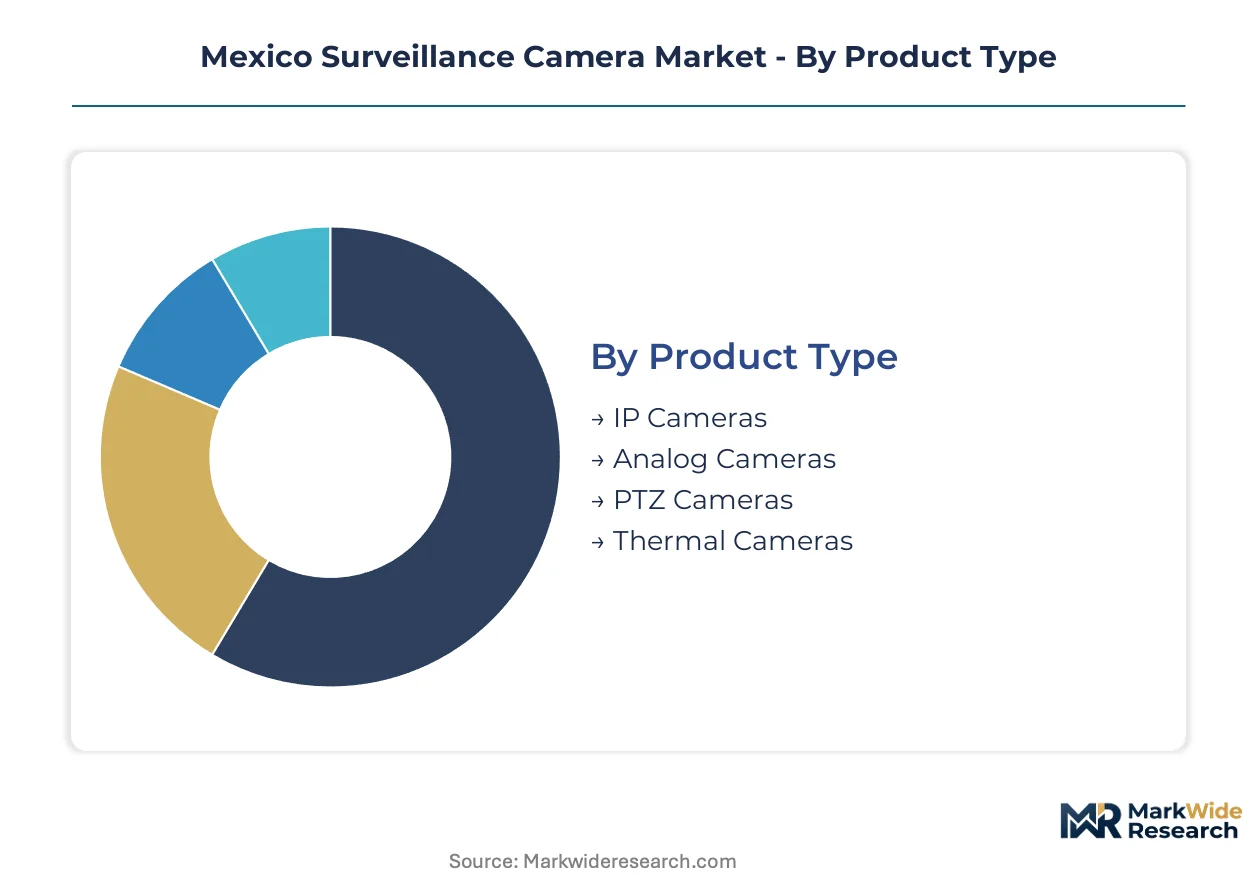
Segmentation in the Mexico surveillance camera market reveals how procurement priorities diverge across infrastructure maturity, compliance requirements, and total cost of ownership calculations. Understanding these fault lines enables vendors to align product portfolios with the specific technical and commercial constraints shaping each buyer category.
Product Type:
Mature analog infrastructure coexists with rapidly scaling IP deployments across Mexican commercial and municipal estates, creating a bifurcated replacement cycle landscape.
- IP Cameras:Network-addressable devices delivering 2MP to 8MP resolution with H.265 compression and ONVIF protocol compliance. Banking branch networks and retail corridors in Mexico City concentrate procurement here, driven by centralized management requirements and CONAPRED audit trail mandates.
- Analog Cameras:Coaxial-connected legacy devices operating on CVBS or HD-TVI protocols. Older government facilities and budget-constrained commercial buildings in Guadalajara retain these systems, constrained by switching costs of full infrastructure replacement.
- PTZ Cameras:Motorized pan-tilt-zoom units with optical magnification ranges.
- Thermal Cameras:Heat-signature detection systems for perimeter monitoring.
IP Cameras retains volume leadership; Thermal Cameras holds the steepest expansion curve.
Technology:
Cost tier differentiation separates capital-intensive wired deployments from operational-expenditure-friendly wireless alternatives, particularly in greenfield installations.
- Wired:Ethernet or coaxial cable infrastructure delivering guaranteed bandwidth and power-over-Ethernet compatibility. Municipal command centers and critical infrastructure sites in Monterrey specify these for reliability guarantees under federal telecommunications homologation requirements.
- Wireless:Wi-Fi, cellular, or proprietary radio-frequency links enabling rapid deployment without trenching. Logistics campuses in Baja California and Nuevo León adopt these where terrain or lease terms prohibit permanent cable installation.
- Optical:Visible-spectrum imaging dependent on ambient or supplemental lighting.
- Infrared:Night-vision capable systems with IR LED illumination arrays.
Wired technology commands the installed base; Wireless is gaining share fastest among new commercial deployments.
End User:
Customer type segmentation maps directly to margin structure, with government procurement bundling service requirements that filter out pure hardware vendors.
- Government:Municipal, state, and federal agencies deploying public safety and critical infrastructure monitoring. Mexico City's smart city ordinances mandate encrypted retention and centralized command centers, creating certified procurement channels with extended service obligations.
- Commercial:Banking, retail, and hospitality operators prioritizing loss prevention and liability documentation. Branch networks in Guadalajara and Monterrey expand facial recognition integration budgets.
- Industrial:Manufacturing and energy facilities requiring perimeter and process monitoring.
- Residential:Single-family and multi-unit dwellings with consumer-grade or prosumer installations.
Government end use captures the deepest margin pool; Commercial verticals show the steepest volume climb.
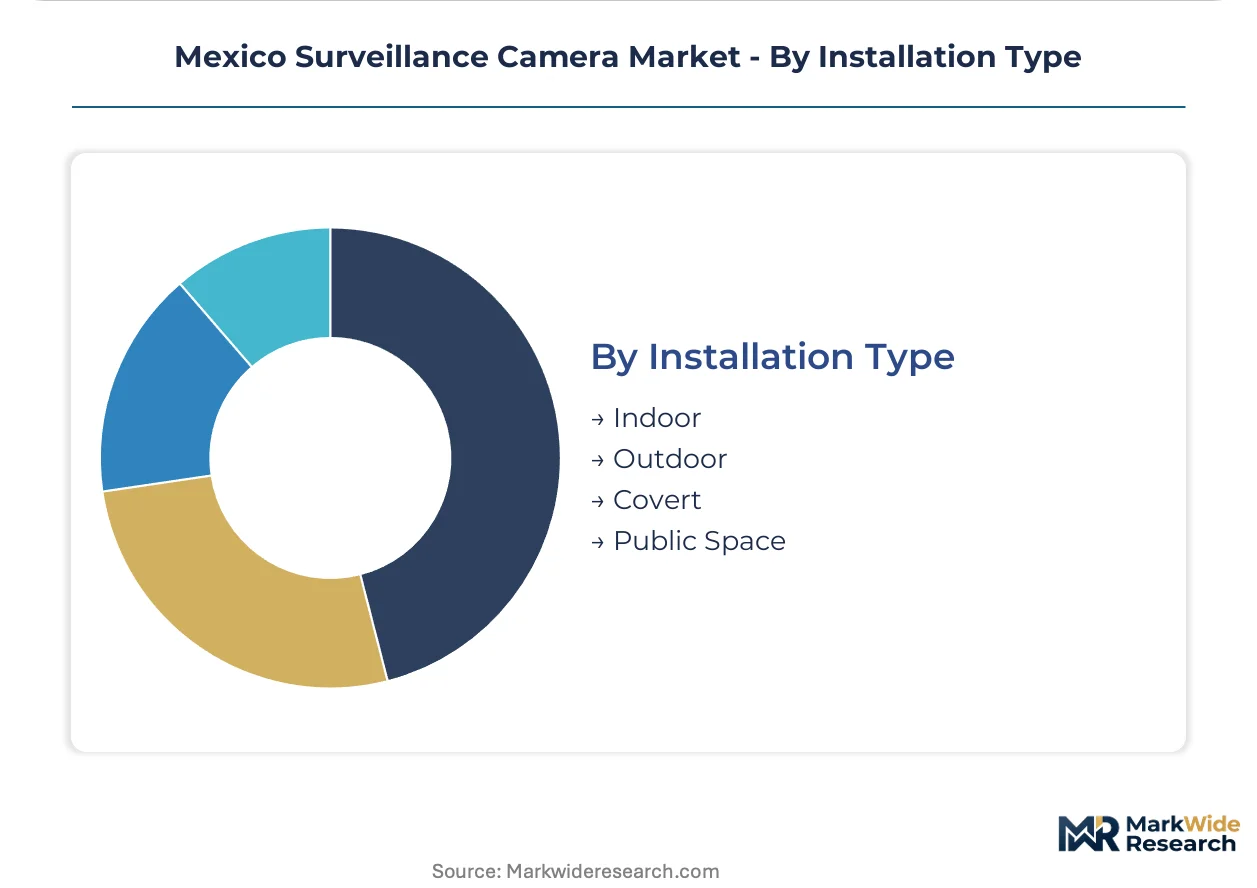
Installation Type:
Application environment dictates hardware specification, with outdoor and public space deployments imposing weatherproofing and vandal-resistance requirements that indoor installations avoid.
- Outdoor:Weather-sealed housings with IP66 or IP67 ratings operating across temperature extremes. Port facilities and pipeline corridors in energy-producing states specify these with thermal imaging overlays for perimeter breach detection.
- Public Space:Street-facing and transit-adjacent deployments subject to CONAPRED biometric data guidelines. Mexico City metro stations and Guadalajara BRT corridors require tamper-evident logging and encrypted storage compliance.
- Indoor:Climate-controlled environment installations with reduced enclosure ratings.
- Covert:Disguised or miniaturized form factors for investigative applications.
Outdoor installation type maintains the largest footprint; Public Space is climbing the fastest on smart city ordinance acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro commands premium pricing power through smart city ordinance mandates, while Northern Border States operate on thinner margins constrained by cross-border procurement arbitrage. This geographic asymmetry shapes vendor prioritization and service bundling strategies across the national footprint.
Mexico City Metro
The capital's public safety corridors and banking branch networks drive demand for encrypted retention and centralized command infrastructure. The federal telecommunications regulator enforces equipment homologation that filters non-certified hardware from municipal tenders. Iztapalapa and Cuauhtémoc boroughs concentrate deployments where CONAPRED audit trail mandates shape procurement specifications.
Nuevo León
Monterrey's industrial perimeter monitoring and logistics campuses accelerate thermal imaging adoption for pipeline and port facility security. State-level smart city initiatives align with federal infrastructure programs to compress vendor qualification timelines. Apodaca and Santa Catarina manufacturing zones anchor wireless deployment growth where trenching costs exceed hardware expenditure.
Jalisco
Guadalajara's retail corridors and hospitality verticals expand facial recognition integration budgets for loss prevention applications. Municipal data protection protocols require tamper-evident logging capabilities in public space installations. Zapopan's commercial districts concentrate mid-tier commercial procurement where system integrators capture recurring service revenue.
Bajío Region
Querétaro and Guanajuato automotive manufacturing clusters drive demand for process monitoring and perimeter surveillance at assembly plants and supplier parks. Industrial end-users prioritize cybersecurity-hardened firmware to protect intellectual property. León's leather goods sector and Silao's vehicle production facilities represent contrasting deployment scales within the same procurement framework.
Northern Border States
Baja California and Chihuahua logistics operators adopt battery-powered and solar-enabled cameras where lease terms prohibit permanent infrastructure investment. Cross-border supply chain monitoring creates demand for thermal imaging at warehousing complexes. Tijuana and Ciudad Juárez commercial corridors face pricing pressure from parallel import channels that circumvent official distribution networks.
Mexico Surveillance Camera Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing volume through original equipment relationships. The Mexican surveillance camera market structures around three tiers: multinational platform vendors with localized technical support, regional system integrators bundling installation and maintenance, and price-focused distributors serving mid-tier commercial replacement cycles. Competitive moves concentrate on service contract bundling and cybersecurity certification acquisition rather than hardware differentiation alone.
Within the multinational platform tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. represent the Chinese-origin contingent that has established localized warehousing and technical support infrastructure. Axis Communications AB occupies a position exemplifying the European cybersecurity-hardened firmware archetype with open-platform architecture positioning. These three anchors illustrate how geographic origin correlates with competitive emphasis: scale and localization against premium security positioning.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Security Systems Incorporated |
| Dahua Technology Co., Ltd |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Panasonic Corporation |
| Eagle Eye Networks |
| Honeywell International Inc |
| Motorola Solutions, Inc. |
| Arlo Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian image sensor foundries is compressing hardware margins for Mexican distributors while simultaneously accelerating vendor consolidation around localized technical support capabilities. This utilization imbalance feeds directly into pricing posture: suppliers with captive warehousing in Nuevo León command premium positioning against competitors dependent on trans-Pacific shipment schedules.
Pricing Analysis
The customization-premium spread separates firmware-hardened units with CONAPRED audit trail compliance from standard IP cameras sold through distributor channels. Project-based pricing dominates government tenders where bundled installation and multi-year service obligations inflate total contract values. Certification level and after-sales service bundling drive price differentiation, with cybersecurity-hardened platforms capturing premium positioning. Cost compression in mid-tier commercial segments is intensifying because semiconductor input volatility from East Asian foundries squeezes distributor margins. Small and mid-sized commercial operators show highest price sensitivity, while federal and municipal agencies demonstrate lowest sensitivity due to encrypted retention mandates.
Supply Chain Analysis
Tariff exposure between China and Mexico dominates supply chain risk calculations for non-domestic manufacturers navigating federal telecommunications homologation timelines. Component sourcing concentrates in China, Taiwan, and South Korea for image sensors, SoC chipsets, and optical lens assemblies. Raw material dependencies span CMOS wafers, rare-earth magnet components for PTZ motors, and aluminum extrusions for weather-sealed housings. Single-source vulnerability in advanced image sensor fabrication creates procurement fragility for vendors lacking multi-foundry relationships. Distribution runs through regional system integrators in Jalisco and Nuevo León who bundle hardware procurement with installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cybersecurity firmware engineering represents the critical skill gap constraining local system integrators from capturing premium government contracts. Vendors who resolve this scarcity through vendor partnerships or in-house capability investment will outcompete hardware-only distributors.
For Market Incumbents: Build switching-cost moats through multi-year service agreements with guaranteed uptime commitments that embed proprietary management platforms. Deepen backward integration into localized warehousing and technical support infrastructure to compress replacement cycle response times. Defend against emerging cloud-managed service providers by hardening firmware cybersecurity credentials and acquiring CONAPRED compliance certifications ahead of tender requirements.
For New Entrants and Emerging Players: Build out wireless campus deployment capabilities targeting retail and logistics operators in Baja California and Nuevo León where trenching costs exceed hardware expenditure. Battery-powered and solar-enabled camera systems represent the most penetrable product category given infrastructure constraints at logistics campuses. Pursue channel partnerships with regional system integrators rather than direct distribution to bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-managed video surveillance-as-a-service offerings as subscription models displace capital purchase cycles. Long-term viability favors platform vendors with recurring revenue streams over hardware-dependent distributors. Acquisition targets should demonstrate CONAPRED compliance certification and established municipal procurement relationships. Monitor homologation approval timelines at Mexico's federal telecommunications regulator as an inflection indicator for product launch velocity and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| CONAPRED Compliance Certification | Unlocks municipal tender eligibility and filters non-compliant hardware from official procurement channels. |
| Localized Technical Support Infrastructure | Reduces replacement cycle response times and captures premium pricing in government service contracts. |
| Cloud-Managed Service Platform Launch | Addresses mid-tier commercial migration from capital expenditure to operational expenditure procurement models. |
| Wireless Campus Deployment Capability | Targets logistics and retail verticals in Baja California and Nuevo León with infrastructure-constrained sites. |
| Cybersecurity Firmware Hardening Investment | Differentiates against price-focused competitors as municipal ordinances mandate encrypted retention and audit trails. |
Research Methodology
A spread of perspectives from municipal procurement officers, system integrator technical directors, banking security executives, federal telecommunications regulator staff, and retail loss prevention managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs import records, SEC filings of multinational platform vendors, homologation approval databases, and municipal smart city ordinance documentation. Bottom-up installation volume estimates triangulated against top-down procurement budget allocations across government, commercial, and industrial end-use segments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, technology, end user, installation environment, and regional procurement cluster. Modeled CAGRs derived from historical replacement cycle patterns, infrastructure investment trajectories, and regulatory compliance timeline compressions. Forecast inputs incorporated semiconductor pricing volatility indices and municipal ordinance adoption curves for encrypted retention mandates.
Practitioners should monitor homologation approval delays, CONAPRED guideline revisions, and East Asian foundry capacity utilization for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
North America Pedestrian Detection Systems Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market