
 Brazil Surveillance Camera Market | 2026-2036
Brazil Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Surveillance Camera Market Insights
Transportation sector procurement is shifting toward intelligent traffic management and metro surveillance systems across Brazilian state capitals. Intelbras anchors its position through deep domestic manufacturing scale and channel control in the SMB segment. Hanwha Vision differentiates via AI-powered analytics integration for critical infrastructure clients. Hikvision competes aggressively on cost-optimized IP camera portfolios tailored to Latin American price sensitivity.
Surveillance cameras are optoelectronic devices that capture, process, and transmit video imagery through charge-coupled device or complementary metal-oxide semiconductor sensors, typically operating across visible and near-infrared spectra with resolutions from 2 to 8 megapixels for security monitoring and situational awareness. Their primary commercial purpose centers on real-time threat detection, forensic evidence collection, and operational oversight across physical environments. Dome cameras and bullet cameras occupy the mature volume tier, while PTZ cameras command premium positioning in perimeter defense and large-area monitoring where motorized optical zoom and pan-tilt functionality justify higher expenditure. IP technology leads technology migration as analog installations depreciate, though wireless deployments face bandwidth constraints in Brazil's uneven fiber-backbone geography.
ANVISA governs data handling in health facility surveillance, while LGPD mandates encryption and retention protocols that filter non-compliant hardware from public tenders. The national telecommunications regulator ANATEL certifies radio-frequency equipment, creating a dual-approval pathway for wireless camera systems. Stakeholders must monitor evolving municipal procurement rules and federal public-security digitization budgets to anticipate demand inflections.
Market Dynamics
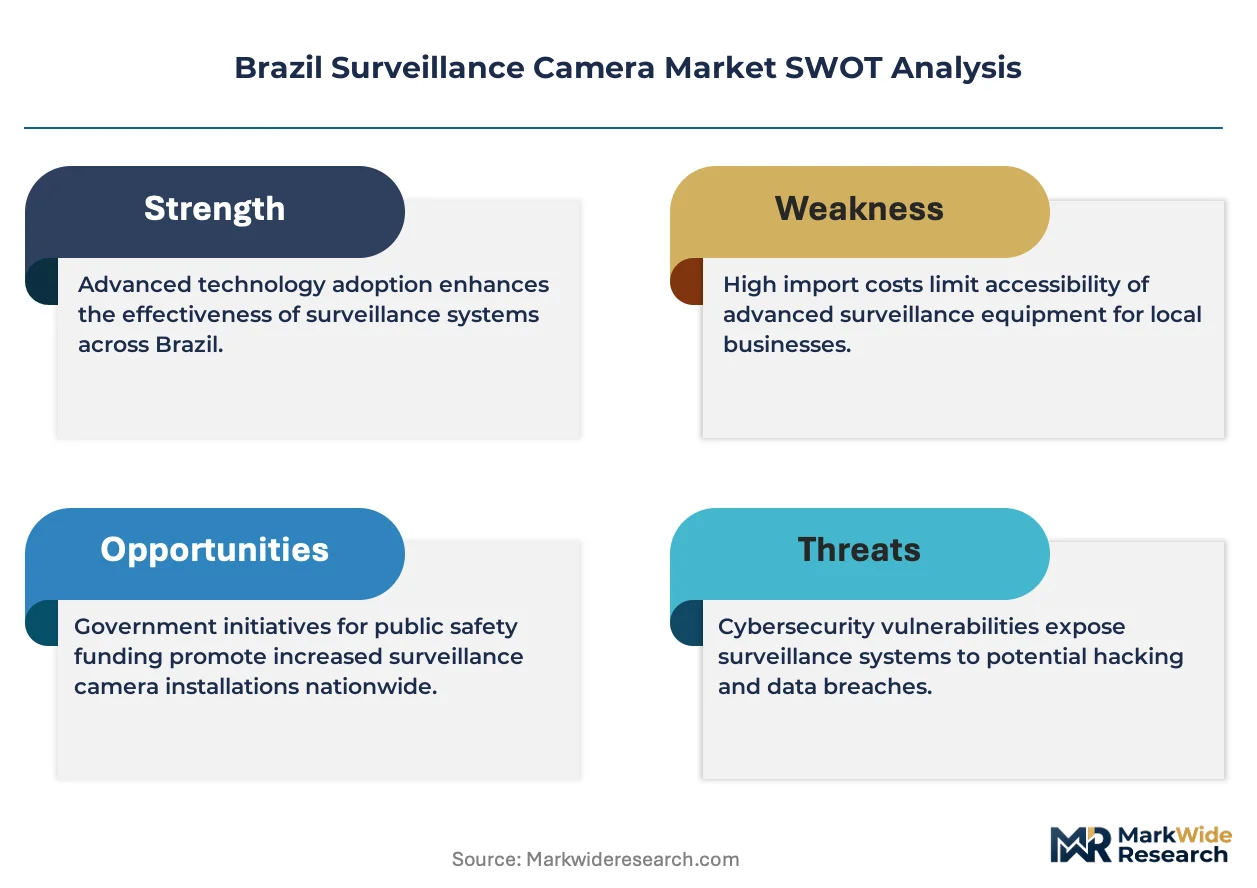
The Brazil surveillance camera market pivots on LGPD compliance mandates that filter non-certified hardware from federal procurement channels, compressing vendor margins while elevating encryption-native suppliers into public-sector tenders.
Growth Catalysts
- Smart city digitization:São Paulo and Rio de Janeiro municipal programs are accelerating networked video deployments for traffic management and public safety infrastructure.
- ANVISA health-facility mandates:Hospital and clinic surveillance systems must meet data-handling protocols, creating replacement cycles for non-compliant legacy installations.
- Federal infrastructure budgets:Public safety digitization priorities in transportation corridors are channeling capital toward metro and highway monitoring systems.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC pricing fluctuations compress hardware margins for cost-optimized IP camera portfolios.
- Wireless bandwidth constraints:Uneven fiber-backbone geography across Brazil's interior limits deployment of cloud-connected surveillance architectures.
- Dual-approval pathway friction:ANATEL radio-frequency certification layered atop LGPD encryption requirements extends product launch timelines for imported equipment.
Strategic Opportunities
- Northeast corridor underpenetration:Recife, Fortaleza, and Salvador municipal budgets remain below smart-city deployment thresholds, offering first-mover positioning.
- AI-analytics convergence:Edge-computing video processors combined with behavioral recognition algorithms open premium pricing in critical infrastructure segments.
- Channel disintermediation:Direct-to-installer digital platforms are bypassing traditional distributor markups in the SMB segment.
Industry Challenges
- LGPD certification timeline compression:Encryption protocol validation cycles lag behind municipal tender deadlines, disqualifying otherwise qualified bidders.
- Legacy analog integration friction:Hybrid deployment architectures strain technical support resources and dilute margin on retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Surveillance Camera Market |
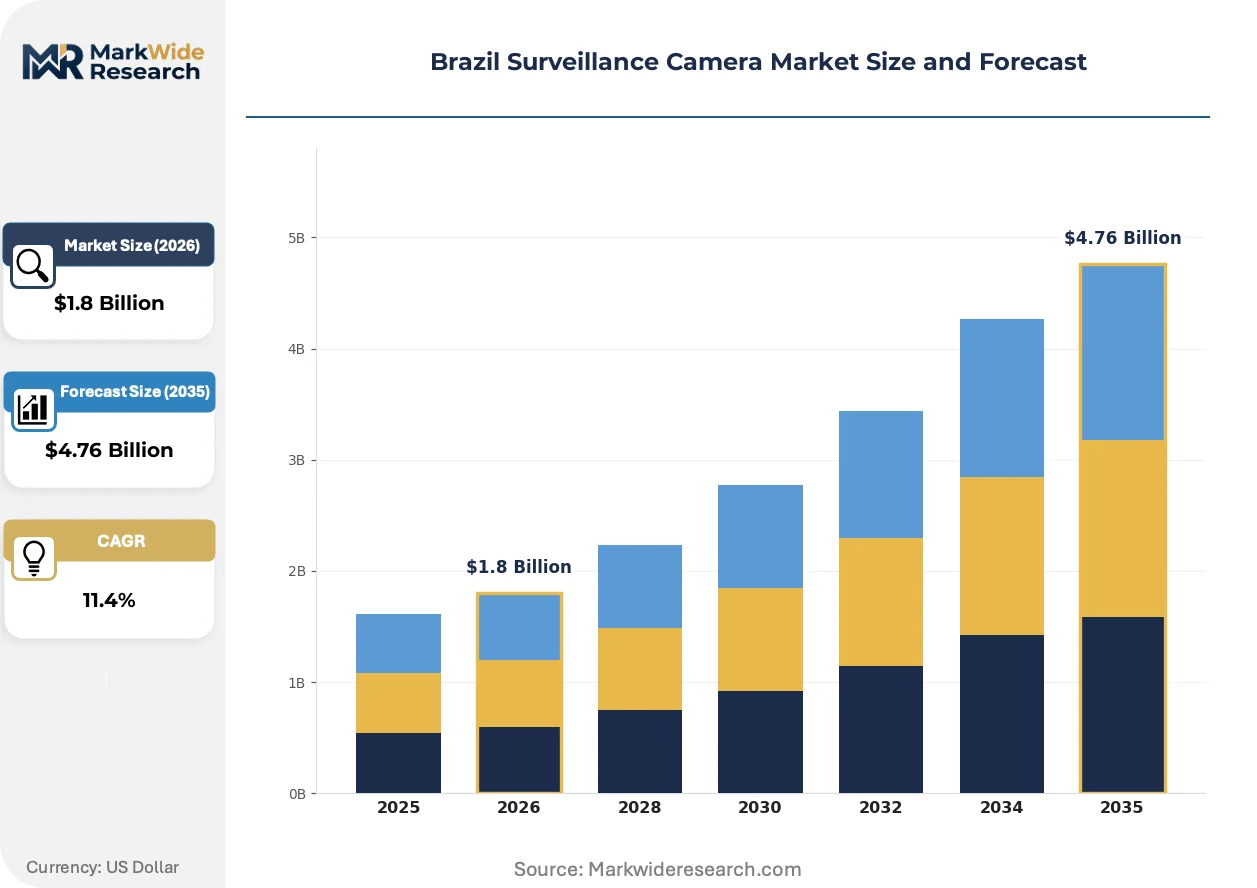
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, C-Mount Cameras Technology: Analog, IP, Wireless, Thermal End User: Residential, Commercial, Government, Transportation Installation Type: Indoor, Outdoor, Mobile, Hybrid |
| Companies Covered | Hanwha Vision, Intelbras, Hikvision, ACTi Corporation, Axis Communications, Dahua Technology, Bosch Security Systems, Honeywell, Teledyne FLIR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Surveillance Camera Market Trends and Innovations
Edge-native AI processing is compressing cloud dependency in Brazilian deployments, while regulatory encryption mandates and procurement centralization are reshaping competitive access to public-sector revenue pools.
On-device video analytics is consolidating around neural-network accelerators embedded in IP camera SoCs. State transportation departments and metro operators are adopting these systems for real-time incident detection without fiber-backbone dependency. This consolidation is compressing centralized server infrastructure requirements and shifting value capture toward edge-hardware vendors.
LGPD Article 50 mandates encryption standards for personal data processing in surveillance contexts. Hardware vendors must demonstrate cryptographic module compliance to participate in federal tenders. Municipal smart-city programs in southeastern state capitals are prioritizing pre-certified equipment, accelerating vendor consolidation around domestic assembly partners with established ANVISA and ANATEL track records.
Centralized procurement consortia are displacing fragmented municipal purchasing across Brazilian state capitals. State-level public safety secretariats are aggregating volume and standardizing specifications, compressing vendor negotiation leverage. This concentration is most visible in São Paulo and Minas Gerais, where multi-year framework agreements now cover networked video infrastructure for entire metropolitan regions.
Brazil Surveillance Camera Market Segmentation
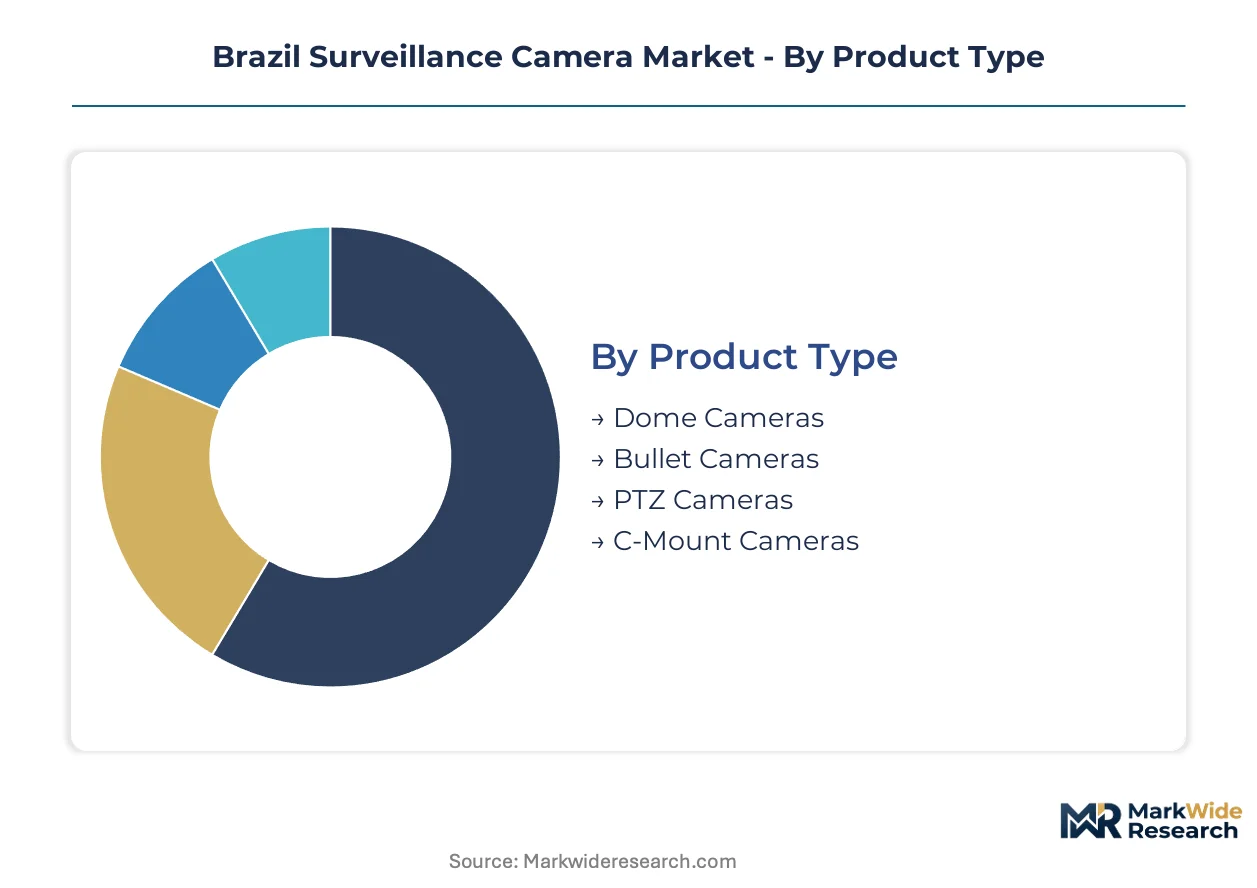
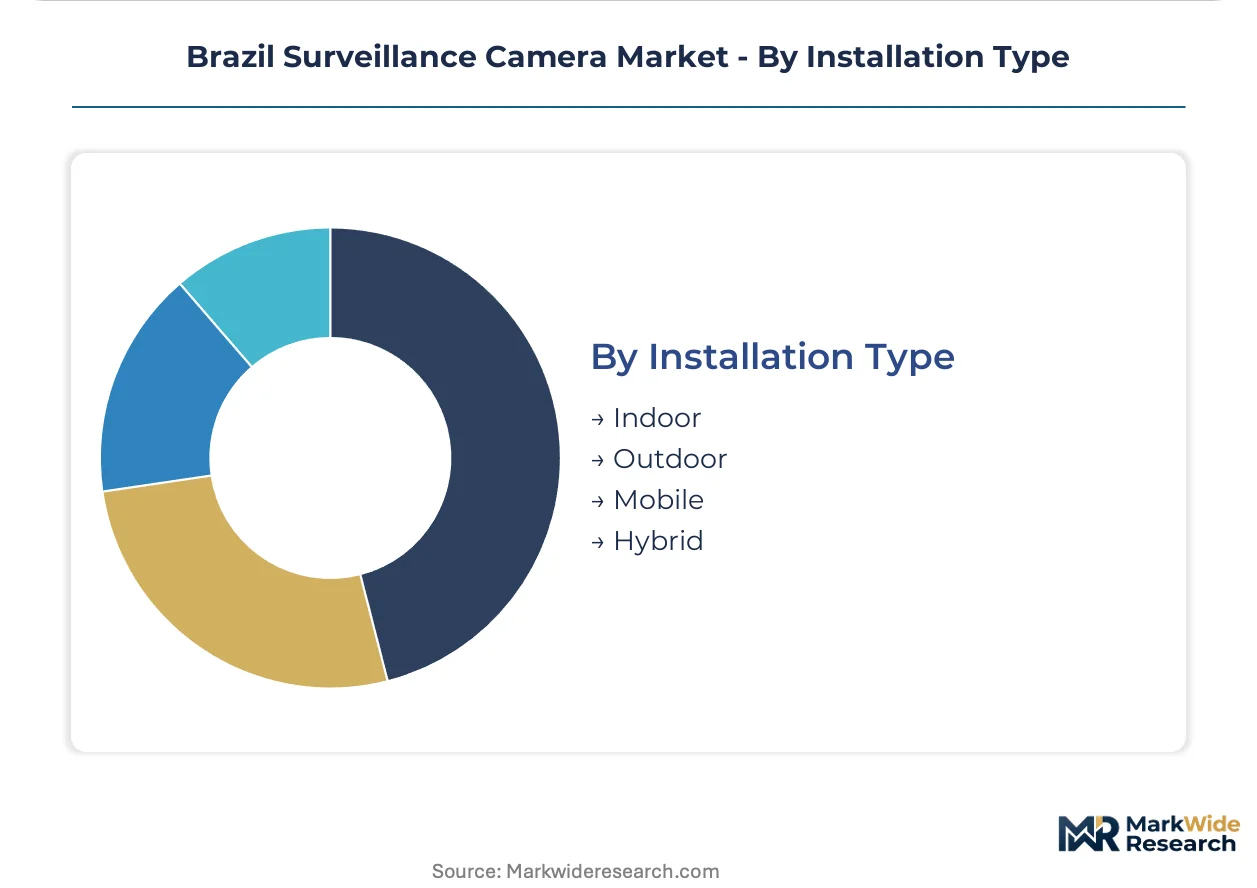
Brazil's surveillance camera market fragments across four critical dimensions that determine procurement specifications, compliance pathways, and margin structures. Product type and technology choices dictate LGPD certification requirements, while end-user concentration shapes pricing power and channel access.
Product Type:
Different housing configurations command distinct price tiers based on environmental sealing, motorized functionality, and installation complexity.
- Dome Cameras:Hemispherical enclosures with vandal-resistant polycarbonate domes suit indoor retail and hospitality deployments across São Paulo shopping districts. Municipal smart-city tenders in Rio de Janeiro specify these for metro station platforms where tamper resistance outweighs optical reach requirements.
- Bullet Cameras:Cylindrical weather-sealed housings with integrated infrared illuminators dominate perimeter defense applications. Federal highway monitoring contracts through Minas Gerais transportation corridors favor bullet form factors for their cost-optimized long-range visibility.
- PTZ Cameras:Pan-tilt-zoom motorized units with optical zoom ranges serve critical infrastructure clients requiring active operator control.
- C-Mount Cameras:Modular lens-interchangeable systems address specialized industrial inspection and scientific imaging niches with custom optics requirements.
Bullet cameras lead volumes today; PTZ cameras are gaining share fastest in federal infrastructure tenders.
Technology:
Signal processing architecture determines network integration depth, cybersecurity posture, and regulatory compliance burden for Brazilian deployments.
- IP Cameras:Network-addressable devices with H.265 compression and Power-over-Ethernet connectivity anchor new installations in government and transportation verticals. LGPD Article 50 encryption mandates favor IP-native cryptographic modules over retrofit analog-to-digital converters.
- Wireless Cameras:Wi-Fi and cellular backhaul systems bypass fiber dependency in Brazil's interior municipalities. ANATEL radio-frequency certification creates dual-approval friction that extends launch timelines for imported equipment.
- Analog Cameras:Coaxial-cable legacy systems persist in residential retrofits and budget-constrained SMB installations.
- Thermal Cameras:Uncooled microbolometer sensors detect heat signatures for perimeter intrusion detection in energy facilities and border monitoring applications.
IP technology commands the steepest expansion trajectory; analog retains residual share in price-sensitive residential replacement cycles.
End User:
Procurement authority and compliance stringency vary sharply across buyer categories, filtering vendor access and margin realization.
- Government:Federal public safety secretariats and state-level procurement consortia aggregate volume through multi-year framework agreements. LGPD and ANVISA dual certification requirements compress qualified vendor pools while elevating encryption-native suppliers.
- Transportation:State departments of transit and metro operators demand edge-native analytics for real-time incident detection without fiber-backbone dependency. São Paulo and Rio de Janeiro corridor expansions channel capital toward intelligent traffic management systems.
- Commercial:Retail chains, banking branches, and logistics facilities drive standardized multi-site deployments with centralized monitoring requirements.
- Residential:Individual homeowners and small apartment complexes prioritize cost-optimized cloud-connected systems through installer channels.
Government vertical concentrates premium pricing power; transportation applications are climbing the fastest on federal infrastructure budget allocations.
Installation Type:
Environmental exposure and mobility requirements dictate housing specifications, power architectures, and maintenance protocols.
- Outdoor:IP66/IP67-rated enclosures with integrated heaters and wipers withstand tropical humidity and temperature cycling across Brazil's climatic zones. Federal highway and perimeter defense specifications mandate these for reliability in uncontrolled environments.
- Indoor:Climate-controlled deployments in healthcare, education, and corporate facilities prioritize discrete form factors and acoustic dampening over environmental sealing.
- Mobile:Vehicle-mounted systems with shock isolation and battery backup serve law enforcement patrol units and transit fleet monitoring.
- Hybrid:Dual-environment architectures supporting both fixed and temporary deployments address event security and construction site monitoring needs.
Outdoor installations dominate absolute unit volumes; mobile configurations are expanding most quickly on public safety fleet modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly operations are migrating toward states with streamlined ANATEL certification pathways and established electronics manufacturing clusters, compressing cost-of-compliance gaps between imported and locally integrated systems.
São Paulo
Municipal smart-city tenders for metro station platforms and traffic corridor monitoring dominate procurement volumes. LGPD Article 50 encryption mandates filter non-certified hardware from state-level framework agreements. The ABC Paulista industrial corridor anchors domestic integration facilities serving southeastern public-sector demand.
Rio de Janeiro
Port security digitization and favela pacification infrastructure drive networked video deployments across metropolitan zones. ANVISA protocols for hospital surveillance create replacement cycles in the city's healthcare cluster. Copacabana and Barra da Tijuca commercial districts concentrate retail banking branch security upgrades.
Minas Gerais
Federal highway monitoring contracts through the BR-040 and BR-381 transportation corridors channel capital toward bullet-camera perimeter systems. State procurement consortia aggregate volume through multi-year agreements. Belo Horizonte's technology park hosts edge-analytics integration labs serving critical infrastructure clients.
Rio Grande do Sul
Manufacturing facility surveillance for automotive and food-processing plants sustains commercial demand. ANATEL radio-frequency certification requirements extend launch timelines for imported wireless equipment. Porto Alegre's industrial suburbs concentrate SMB installer networks and distributor warehousing.
Bahia
Underpenetrated municipal budgets in Salvador and surrounding municipalities offer first-mover positioning for certified equipment vendors. Petrobras energy facility perimeter security drives thermal-camera deployments. The state's uneven fiber-backbone geography limits cloud-connected architectures in interior municipalities.
Brazil Surveillance Camera Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic integrators controlling SMB channels and multinational OEMs anchoring federal infrastructure tenders. The vendor base concentrates around three tiers: encryption-native suppliers with ANVISA track records, cost-optimized IP camera portfolios targeting price-sensitive verticals, and edge-analytics specialists commanding premium positioning in critical infrastructure. Strategic moves center on backward integration into domestic assembly and channel disintermediation through direct-to-installer digital platforms.
Among Asia-Pacific-based equipment fabricators, Hanwha Vision and Hikvision occupy positions within the federal tender-qualified tier, while Intelbras anchors the domestic integration segment with established certification pathways. These three exemplify the competitive archetypes reshaping vendor access to public-sector revenue pools: encryption-native compliance leadership, cost-optimized portfolio scale, and deep channel control through localized assembly partnerships.
| Leading Market Players |
|---|
| Hanwha Vision |
| Intelbras |
| Hikvision |
| ACTi Corporation |
| Axis Communications |
| Dahua Technology |
| Bosch Security Systems |
| Honeywell |
| Teledyne FLIR |
| Others |
Pricing and Supply Chain Analysis
Embedded systems engineers concentrated in São Paulo's ABC Paulista corridor command wage premiums that compress pricing-tier spreads between domestically assembled and fully imported surveillance equipment. Labor-cost differentials between this southeastern cluster and northeastern assembly alternatives widen margin headroom for vendors pursuing economy-tier positioning without sacrificing LGPD certification compliance.
Pricing Analysis
Distributor markups of 15-25 percentage points separate factory-gate pricing from installer-facing tiers across Brazilian surveillance channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by encryption module certification grade and ANVISA track record depth. Price erosion runs through economy-tier IP cameras as Intelbras and Hikvision compress hardware margins for municipal tender participation. SMB installers exhibit highest price sensitivity, while federal infrastructure consortia prioritize encryption-native suppliers regardless of premium positioning.
Supply Chain Analysis
Freight costs from Shenzhen and Seoul anchor landed-cost structures for image sensor and SoC shipments entering Santos port. Manufacturing concentration in China, South Korea, and Taiwan feeds Brazilian domestic assembly operations with CMOS sensors and neural-network accelerators. Single-source vulnerability around advanced edge-analytics processors from Taiwan-based foundries exposes vendors to allocation constraints during semiconductor upcycles. Distribution runs through São Paulo-based national distributors serving state-level procurement consortia and direct-to-installer digital platforms targeting SMB retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as LGPD Article 50 mandates filter non-compliant hardware from federal tenders, redirecting procurement gravity toward encryption-native suppliers with established ANVISA and ANATEL certification pathways.
For Market Incumbents: Cement ANVISA and ANATEL certification leadership through backward integration into São Paulo-based domestic assembly facilities. Deepen channel control over northeastern installer networks before municipal budget expansion in Recife and Salvador accelerates competitive entry. Threat substitution from cloud-native surveillance architectures without edge-native encryption compliance elevates certified hardware premiums. For New Entrants and Emerging Players: Launch via direct-to-installer digital platforms bypassing traditional distributor markups in the SMB residential segment. Target underpenetrated municipal budgets in Bahia and Pernambuco where fiber-backbone constraints favor wireless-certified equipment with ANATEL pre-approval. White-space positioning in thermal-camera perimeter security for Petrobras energy facilities offers premium pricing outside federal tender consolidation. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic integrators with established LGPD certification pathways but limited AI-analytics R&D depth. Long-term viability over a 5-10 year window hinges on edge-computing video processor capabilities displacing centralized server infrastructure. Signal to monitor: state-level procurement consortia aggregation rates in Minas Gerais and Rio de Janeiro as inflection indicators for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Expansion | LGPD and ANATEL compliance acceleration compresses launch timelines for federal tenders. |
| Edge-Native AI Integration | Neural-network accelerators in IP camera SoCs reduce fiber-backbone dependency in interior municipalities. |
| Direct-to-Installer Platform Launch | Digital channel disintermediation captures SMB margin pools outside distributor-controlled networks. |
| Thermal Camera Portfolio Extension | Uncooled microbolometer systems address energy facility perimeter security beyond price-commoditized IP volumes. |
| Northeast Corridor Channel Buildout | First-mover positioning in Salvador and Recife municipal markets ahead of smart-city budget inflections. |
Research Methodology
Coverage spans Brazil's southeastern, northeastern, and southern state clusters, with primary inputs from each region's procurement consortia and installer networks. Primary interviews with municipal smart-city program directors, federal public safety secretariat procurement officers, hospital facility managers under ANVISA jurisdiction, and SMB surveillance installers combined with secondary validation from ANATEL certification databases, LGPD regulatory filings, and federal infrastructure budget appropriations records. Bottom-up unit demand triangulation across product type, technology, and end-user segments reconciled with top-down value estimates from state-level framework agreement disclosures.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects and regulatory-driven replacement cycles. Segmentation modeling spans product type, signal processing architecture, end-user vertical, and installation environment, with additional dimensioning by encryption certification tier and domestic assembly content ratio. CAGRs derived from logistic adoption curves fitted to municipal procurement pipeline data and federal transportation corridor monitoring deployment schedules.
Several conditions sit outside the modeled scope, including potential LGPD enforcement intensity variations across electoral cycles and unannounced semiconductor export restriction measures affecting image sensor supply. Forecasts reflect documented assumptions regarding municipal budget execution rates and ANATEL certification timeline stability. Stakeholders should weight assumptions against their own operating context and monitor state-level procurement centralization velocity as a demand revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Smart Security Camera Market