
 AI Surveillance System Market | 2026-2036
AI Surveillance System Market Size, Share, and Industry Trends Forecast 2026-2036
AI Surveillance System Market Insights
Public-sector procurement for urban safety infrastructure is consolidating around multi-year framework contracts with single-vendor accountability. Hikvision leverages integrated manufacturing scale to dominate camera hardware supply for municipal deployments across Asia. Axis Communications differentiates through open-architecture software partnerships that reduce vendor lock-in for European government buyers. NEC Corporation specializes in biometric algorithm refinement for high-throughput transit environments where accuracy thresholds exceed commercial norms.
An AI surveillance system integrates machine vision processors, edge-computing nodes, and neural-network inference engines to automate detection, classification, and alerting across video streams in real time. These systems typically operate at latency thresholds below 150 milliseconds to enable preemptive response in critical infrastructure and public venue applications. Camera Systems and Video Analytics command the dominant share of deployed value, while Edge Computing deployments are expanding fastest as agencies prioritize localized data processing to satisfy data-sovereignty constraints. Facial Recognition technology leads in government end-user segments, though Anomaly Detection is gaining traction in commercial logistics and retail loss-prevention applications where pattern-deviation sensitivity drives return on investment.
The EU AI Act and GDPR impose strict conformity assessments on biometric identification systems sold into European government and commercial channels. China's SAMR and GB standards mandate domestic encryption protocols and data-localization requirements for public-security procurement tenders. India's proposed Digital Personal Data Protection framework and BIS certification pathways for electronic safety equipment are reshaping vendor qualification criteria. Stakeholders must monitor regulatory divergence between jurisdictions where biometric deployment permissions, algorithmic audit requirements, and cross-border data-flow restrictions are fragmenting product standardization and complicating global rollout strategies.
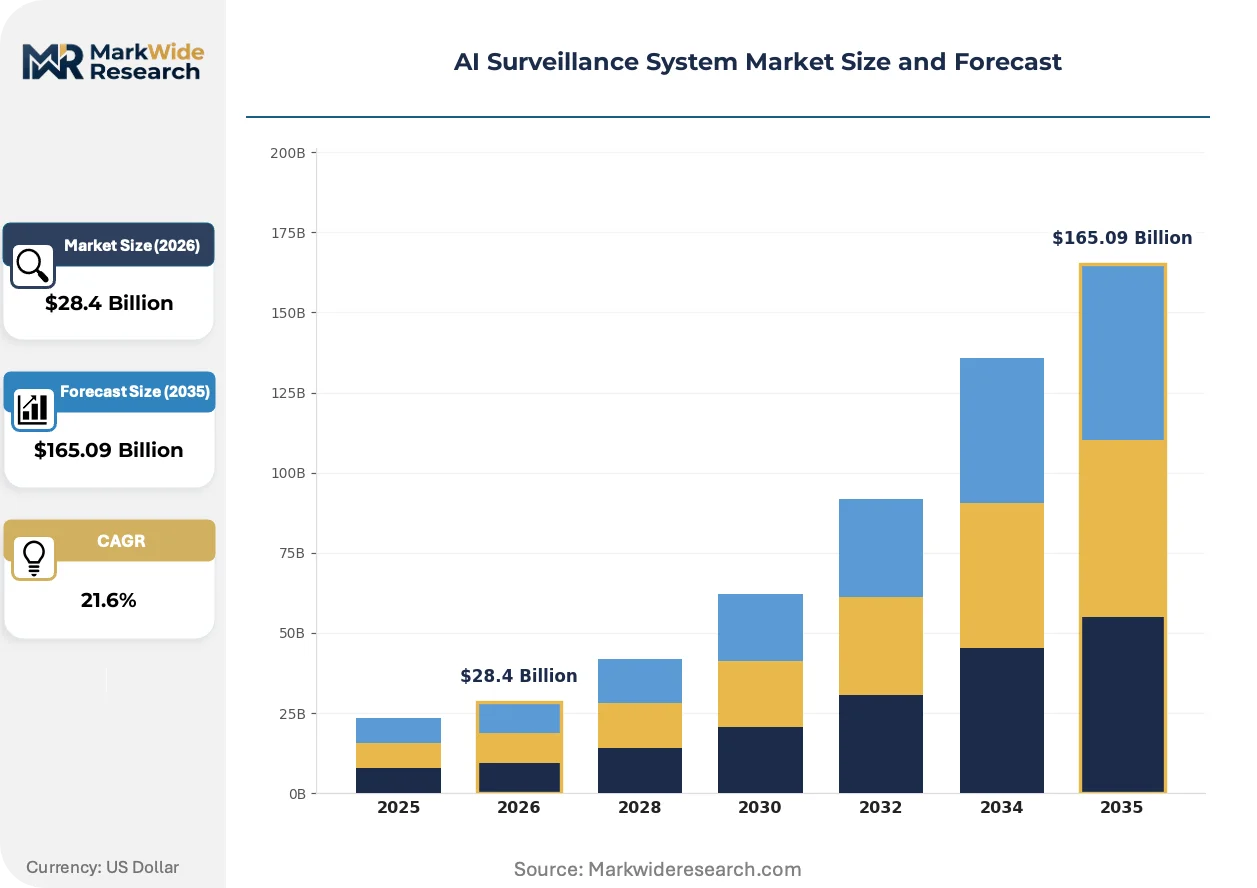
Market Dynamics
Smart city infrastructure mandates in China's eastern coastal provinces are consolidating procurement around multi-year framework contracts that demand single-vendor accountability for integrated hardware-software deployments.
Growth Catalysts
- EU AI Act compliance deadlines:European government buyers are accelerating replacement cycles for legacy biometric systems to meet conformity assessment requirements ahead of enforcement phases.
- Edge computing localization:Data-sovereignty constraints in public safety networks are driving municipal agencies toward on-premise inference nodes that process video streams without cross-border transmission.
- Transit authority biometric mandates:High-throughput transportation hubs in Japan and South Korea are deploying facial recognition gates that exceed commercial accuracy thresholds for passenger flow optimization.
Market Restraints
- GB standards encryption fragmentation:China's SAMR-mandated domestic cryptographic protocols prevent interoperability with internationally certified hardware, forcing vendors to maintain parallel product lines.
- GPU and NPU supply concentration:Neural processing unit fabrication for edge inference engines depends on concentrated advanced semiconductor foundry capacity in Taiwan and South Korea.
- Biometric false-positive technical ceilings:Algorithmic accuracy gains in unconstrained environments face diminishing returns against occlusion, lighting variance, and demographic bias correction requirements.
Strategic Opportunities
- India's Digital Personal Data Protection framework:BIS certification pathways for electronic safety equipment create first-mover qualification advantages for vendors establishing local testing partnerships.
- Anomaly detection in logistics:Commercial warehouse operators are deploying behavioral analytics for loss prevention where pattern-deviation sensitivity drives measurable ROI without privacy-sensitive biometric capture.
- 5G-integrated edge nodes:Convergence of millimeter-wave connectivity with containerized inference engines enables real-time alerting across distributed camera networks without fiber backhaul dependency.
Industry Challenges
- Multimodal systems integration complexity:Municipal buyers struggle to unify legacy analog camera infrastructure with AI-enabled digital backends, requiring costly middleware development or complete hardware refresh cycles.
- Algorithmic audit talent scarcity:Compliance with EU AI Act conformity assessments demands specialized personnel capable of documenting bias testing, risk classification, and post-market monitoring protocols that most system integrators lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Surveillance System Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $165.09 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Access Control, Motion Sensors, Video Analytics Deployment: On-premises, Cloud-based, Hybrid, Edge Computing End User: Residential, Commercial, Government, Transportation Technology: Facial Recognition, Object Detection, Anomaly Detection, Thermal Imaging |
| Companies Covered | Hikvision, Dahua Technology, Axis Communications, Bosch Security Systems, Huawei Technologies, NEC Corporation, Honeywell International, Milestone Systems, Genetec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Surveillance System Market Trends and Innovations
Neural network compression techniques and federated learning architectures are reshaping how surveillance systems balance inference accuracy against edge hardware constraints and data-privacy requirements.
Transformer-based vision models optimized for edge deployment are electrifying real-time object tracking capabilities. Railway operators in Germany and France are piloting these architectures for platform safety monitoring where sub-100-millisecond latency prevents passenger incidents. The technology is compressing the performance gap between cloud-based analytics and localized processing, enabling agencies to satisfy GDPR data-localization mandates without sacrificing detection fidelity.
The EU AI Act's risk-based classification system for biometric identification imposes mandatory conformity assessments on systems deployed in publicly accessible spaces. European vendors are restructuring product roadmaps to segregate high-risk facial recognition offerings from lower-tier video analytics, creating modular certification pathways that reduce compliance recertification costs. Government buyers in France and the Netherlands now require documented algorithmic audit trails as standard tender evaluation criteria.
Framework contracting is consolidating vendor relationships around multi-year single-source agreements that bundle hardware refresh, software licensing, and maintenance into unified spend commitments. System integrators in China's Jiangsu and Zhejiang provinces are displacing transactional camera procurement with subscription-based analytics services where municipal buyers pay per monitored square kilometer rather than per device installed. This model transfers technology obsolescence risk from public agencies to vendors while locking in decade-long revenue streams.
AI Surveillance System Market Segmentation
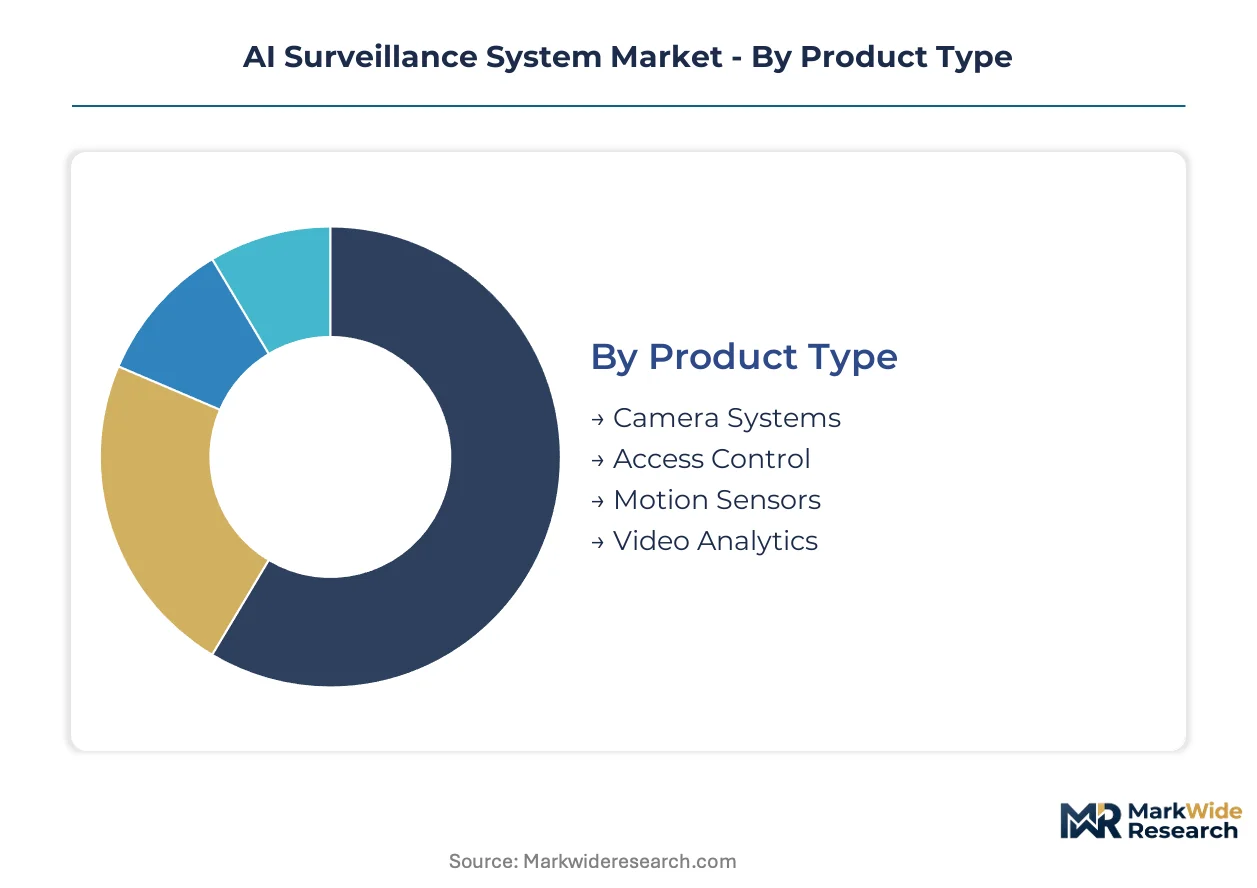
Segmentation in the AI surveillance system market reveals divergent capital requirements, deployment architectures, and compliance obligations across product tiers. Procurement patterns vary sharply between government integrators seeking multi-year framework contracts and commercial buyers prioritizing rapid ROI from loss-prevention analytics.
Product Type:
Capital intensity peaks in integrated hardware-software bundles where municipal procurement demands single-vendor accountability for decade-long service lifecycles.
- Camera Systems:Machine vision processors and neural-network inference engines embed directly into IP camera housings, processing video streams at sub-150-millisecond latency thresholds. Demand concentrates in China's eastern coastal provinces where Jiangsu and Zhejiang municipal governments fund integrated public safety networks under smart city infrastructure mandates. These deployments require substantial upfront hardware investment but lock in recurring analytics subscription revenue.
- Video Analytics:Software layers automate detection, classification, and alerting across distributed camera networks through containerized inference engines. European government buyers prioritize open-architecture platforms that reduce vendor lock-in and satisfy EU AI Act conformity assessment requirements for algorithmic audit trails. Capital requirements skew toward software development and certification rather than physical manufacturing.
- Access Control:Biometric authentication gates for high-throughput transit environments.
- Motion Sensors:Perimeter detection devices triggering edge-based alert protocols.
Camera Systems absorb the bulk of installed capacity; Video Analytics is expanding most quickly as agencies shift from hardware ownership to subscription-based monitoring services.
Deployment:
Data-sovereignty constraints and latency requirements determine whether inference processing occurs locally, centrally, or across distributed architectures.
- Edge Computing:On-premise inference nodes process video streams without cross-border transmission, satisfying GDPR data-localization mandates and China's GB standards on biometric data localization. Railway operators in Germany and France pilot transformer-based vision models on these nodes for platform safety monitoring where sub-100-millisecond latency prevents passenger incidents. Deployment requires specialized neural processing unit hardware but eliminates recurring cloud egress fees.
- On-premises:Fully localized server infrastructure behind agency firewalls.
- Cloud-based:Centralized processing enabling rapid algorithm updates across distributed estates.
- Hybrid:Tiered architectures routing sensitive biometric analysis locally while pushing archival storage to cloud tiers.
Edge Computing deployments are gaining share fastest as data-sovereignty regulations tighten; On-premises retains dominance in classified government facilities with air-gapped security requirements.
End User:
Procurement sophistication and compliance burden scale with the sensitivity of captured biometric data and the criticality of protected infrastructure.
- Government:Public-sector agencies operate under the strictest algorithmic audit requirements, with EU AI Act risk-based classifications mandating conformity assessments for facial recognition in publicly accessible spaces. Framework contracting consolidates vendor relationships around multi-year single-source agreements bundling hardware refresh, software licensing, and maintenance. India's proposed Digital Personal Data Protection framework and BIS certification pathways reshape qualification criteria for equipment tenders.
- Transportation:High-throughput hubs in Japan and South Korea deploy facial recognition gates exceeding commercial accuracy thresholds for passenger flow optimization.
- Commercial:Warehouse operators and retail chains deploy behavioral analytics for loss prevention where pattern-deviation sensitivity drives measurable ROI.
- Residential:Consumer-grade devices with localized processing and minimal cloud dependency.
Government end users command the highest per-site deployment values; Commercial segments are climbing the fastest as anomaly detection applications proliferate in logistics and retail.
Technology:
Algorithmic maturity and regulatory permissibility vary sharply across biometric, object-centric, and environmental sensing modalities.
- Facial Recognition:Biometric identification systems face the most restrictive regulatory treatment under EU AI Act high-risk classifications and China's SAMR-mandated domestic encryption protocols. NEC Corporation and specialized vendors refine algorithms for transit environments where accuracy thresholds exceed commercial norms. European vendors now segregate high-risk offerings from lower-tier video analytics to create modular certification pathways.
- Anomaly Detection:Pattern-deviation algorithms gain traction in commercial logistics and retail loss-prevention applications where sensitivity drives return on investment without privacy-sensitive biometric capture. These systems detect behavioral irregularities in warehouse workflows or point-of-sale environments.
- Object Detection:Real-time classification of vehicles, weapons, or abandoned packages in public venues.
- Thermal Imaging:Temperature-based sensing for perimeter security and health screening applications.
Facial Recognition retains revenue concentration in government segments; Anomaly Detection represents the steepest expansion trajectory as commercial buyers prioritize privacy-preserving analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the highest procurement velocity for integrated public safety networks, while European and North American jurisdictions fragment demand across divergent regulatory compliance frameworks.
China
Jiangsu and Zhejiang provinces drive municipal spending on smart city infrastructure through multi-year framework contracts bundling hardware and analytics subscriptions. SAMR-mandated GB standards enforce domestic encryption protocols and data-localization requirements for biometric systems deployed in public-security networks. Shanghai anchors the eastern coastal cluster where integrated manufacturing scale supports rapid deployment of edge-computing nodes for localized video processing.
Germany
Railway operators Deutsche Bahn and municipal transit authorities pilot transformer-based vision models for platform safety monitoring requiring sub-100-millisecond latency thresholds. The EU AI Act imposes mandatory conformity assessments on biometric identification systems deployed in publicly accessible spaces, with German regulators accelerating replacement cycles for legacy installations. Berlin and the Ruhr industrial corridor concentrate demand for open-architecture video analytics that satisfy GDPR data-localization mandates without vendor lock-in.
United States
Critical infrastructure operators and federal security agencies procure edge-computing deployments for air-gapped facilities with classified processing requirements. Federal procurement guidelines emphasize supply chain security screening for neural processing unit components sourced from concentrated advanced semiconductor foundry capacity. Texas and California host the primary integration hubs where system vendors customize inference engines for Department of Homeland Security and transportation authority biometric mandates.
India
Municipal corporations in Maharashtra and Karnataka issue tenders for electronic safety equipment under the proposed Digital Personal Data Protection framework reshaping vendor qualification criteria. BIS certification pathways create first-mover advantages for equipment manufacturers establishing local testing partnerships. Delhi-NCR and Bengaluru concentrate pilot deployments of facial recognition gates for high-throughput transit environments where accuracy thresholds exceed commercial norms.
Japan
East Japan Railway Company and Tokyo Metro deploy facial recognition systems exceeding commercial accuracy thresholds for passenger flow optimization in congested hub stations. METI guidelines on AI system safety influence procurement specifications for real-time anomaly detection in logistics and retail applications. The Kanto region around Tokyo anchors demand for high-throughput biometric authentication gates integrated with existing fare collection infrastructure.
AI Surveillance System Market Competitive Landscape
Chinese producers anchor one tier through integrated manufacturing scale and municipal framework contracting dominance; European specialists hold differentiated positions in open-architecture software partnerships. The vendor base stratifies across three archetypes: hardware-integrated platform providers, modular software specialists, and biometric algorithm refiners. Consolidation pressures intensify as government buyers demand single-vendor accountability for decade-long service lifecycles. Strategic moves concentrate on local certification partnerships and edge-computing hardware customization for data-sovereignty compliance.
Within the integrated platform tier, Hikvision and Dahua Technology exemplify manufacturing-scale archetypes serving municipal procurement across Asia. Axis Communications occupies a position representing modular, open-architecture approaches that reduce vendor lock-in for European government buyers constrained by EU AI Act compliance requirements. NEC Corporation anchors the biometric specialization segment, with its algorithm refinement focus addressing high-throughput transit environments where accuracy thresholds exceed commercial deployment norms.
| Leading Market Players |
|---|
| Hikvision |
| Dahua Technology |
| Axis Communications |
| Bosch Security Systems |
| Huawei Technologies |
| NEC Corporation |
| Honeywell International |
| Milestone Systems |
| Genetec |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers and private-equity-rolled-up specialists anchor pricing discipline through captive control over neural processing unit supply and municipal framework contracting leverage. This ownership pattern concentrates supply-side bargaining power in China's eastern coastal clusters while forcing European and North American buyers to absorb premium tariffs for compliant edge-computing hardware.
Pricing Analysis
Volume concentrates in integrated camera-hardware bundles where municipal procurement locks in decade-long service commitments, while margin accretion shifts toward subscription-tiered video analytics software. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified biometric systems from open-architecture middleware and commodity IP camera hardware. Cost compression in standard-tier edge nodes is intensifying because concentrated NPU foundry capacity in Taiwan and South Korea constrains component supply. Commercial warehouse operators exhibit highest price sensitivity, whereas government transit authorities prioritize accuracy thresholds over unit economics.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Shanghai, and Hangzhou feed hub-and-spoke fulfillment patterns across Asia-Pacific municipal procurement networks. Neural processing unit fabrication draws from concentrated advanced semiconductor foundry capacity in Taiwan and South Korea, while camera lens assemblies and edge-computing enclosures source from vertically integrated Chinese manufacturing clusters. Single-source vulnerability in GPU and NPU supply creates procurement risk for vendors serving EU AI Act compliance deadlines. Distribution runs through municipal system integrators in Jiangsu and Zhejiang provinces who bundle hardware refresh cycles with analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural processing unit foundry constraints prop pricing power for vendors with secured wafer allocation, making supply security the decisive competitive variable across the projection horizon.
For Market Incumbents: Extend framework contracting dominance by locking multi-year municipal analytics subscriptions before EU AI Act recertification waves disrupt vendor relationships. Deepen backward integration into edge-computing node assembly to offset NPU supply concentration risk from Taiwan and South Korea foundries. Prioritize algorithmic audit trail documentation to satisfy French and Dutch tender evaluation criteria. For New Entrants and Emerging Players: Mid-tier commercial logistics operators represent the most penetrable buyer archetype, as warehouse loss-prevention deployments lack incumbent lock-in and prioritize rapid ROI over biometric certification complexity. Target India's BIS certification pathway partnerships to establish qualification advantages ahead of Digital Personal Data Protection framework enforcement. Lead with anomaly detection software layers that bypass hardware-integrated platform competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular software specialists with EU AI Act conformity assessment capabilities in Germany and the Netherlands. Five-to-ten-year viability hinges on regulatory divergence management across GDPR, SAMR-mandated GB standards, and emerging Indian certification frameworks. Watch for municipal framework contract renewal waves as inflection indicators for incumbent pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Customization | Tailored NPU configurations satisfy China's SAMR data-localization mandates for Jiangsu municipal tenders. |
| Algorithmic Audit Trail Documentation | Documented bias testing protocols meet EU AI Act conformity assessment requirements for Deutsche Bahn deployments. |
| Local Certification Partnership Formation | BIS testing alliances in Maharashtra create first-mover qualification advantages under India's proposed data protection framework. |
| Subscription-Based Analytics Migration | Per-square-kilometer pricing models transfer technology obsolescence risk from Zhejiang public agencies to vendors. |
| Open-Architecture Platform Development | Software partnerships reduce vendor lock-in for Berlin municipal buyers constrained by GDPR data-localization requirements. |
Research Methodology
Regulatory filings from EU AI Act implementation documents, China's SAMR procurement tender databases, and BIS certification pathway announcements formed the secondary backbone. Municipal procurement officers in Jiangsu and Zhejiang provinces, system integration specialists serving German railway operators, and edge-computing hardware procurement leads at Indian transit authorities provided primary field perspectives. Bottom-up camera deployment tallies and top-down smart city infrastructure budget allocations underwent cross-validation.
Bottom-up unit economics modeled camera system, video analytics, and edge-computing node shipments across deployment type, end-user segment, and technology modality. Analytical frameworks incorporated latency threshold requirements, data-sovereignty constraint intensity, and algorithmic audit complexity as industry-specific forecast inputs. CAGRs derived from municipal framework contract renewal patterns and commercial logistics adoption curves across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NPU supply disruption, regulatory divergence between GDPR and SAMR-mandated encryption protocols, and municipal budget reallocation cycles. Forecasts reflect documented assumptions regarding procurement velocity in China's eastern coastal provinces and EU AI Act enforcement phasing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
China Video Surveillance Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
United States Surveillance Camera Market