
 US Rigid Thermoform Plastic Packaging Market | 2026-2036
US Rigid Thermoform Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Rigid Thermoform Plastic Packaging Market Intelligence
Post-consumer recycled PET integration is reconfiguring thermoforming lines across the US packaging base. Amcor plc leverages multi-layer extrusion expertise to anchor supply relationships with national food brands. Genpak LLC specializes in hinged-container formats for the foodservice channel. Pactiv Evergreen Inc. dominates retail-ready tray production through its integrated sheet extrusion network.
US rigid thermoform plastic packaging comprises shaped polymer sheets—typically PET, PVC, PS, or PP—heated and vacuum- or pressure-formed into permanent three-dimensional containers with wall thicknesses generally exceeding ten mils, engineered for structural integrity, product visibility, and barrier protection across food, medical, and consumer applications. Clamshells command the largest product-type position due to their theft-deterrent properties and produce-retail penetration, while skin packaging represents the fastest-expanding segment as protein processors adopt film-backed board systems for case-ready meat display. Food containers capture the deepest margin pools where customized barrier specifications and extended shelf-life functionality justify premium positioning.
FDA food-contact notifications, EPA recycled-content procurement guidelines, and OSHA workplace chemical exposure limits collectively shape material selection, line conversion investments, and plant-level compliance spending across US thermoforming operations. State-level extended producer responsibility frameworks in California, Oregon, and Maine are fragmenting feedstock access and forcing multi-site producers to maintain distinct resin qualification protocols. Stakeholders must monitor emerging post-consumer content mandates and assess captive recycling infrastructure against distributed supply alternatives.
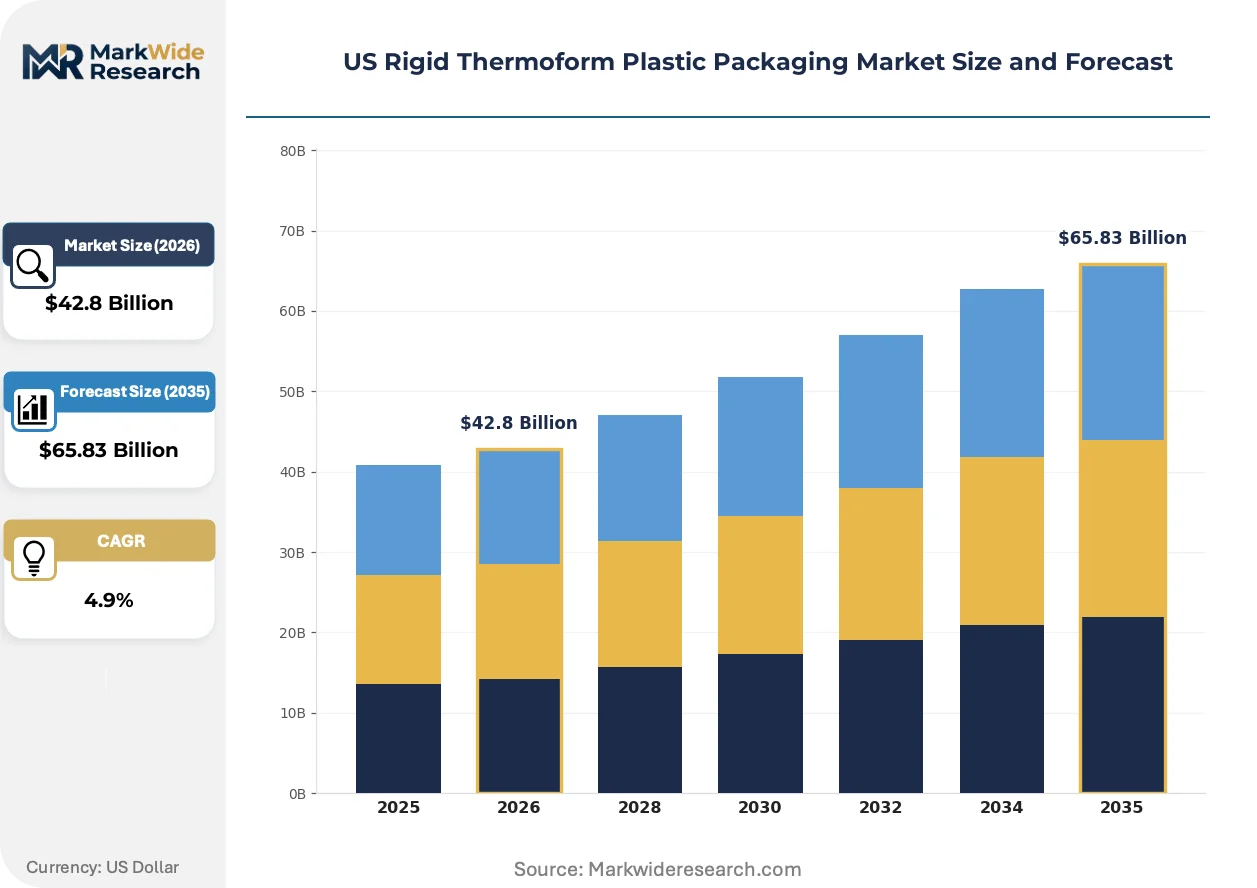
Market Dynamics
Post-consumer recycled PET integration is forcing thermoforming lines across the US to reconfigure extrusion and forming equipment, creating capital allocation tension between compliance readiness and margin preservation.
Growth Catalysts
- Extended Producer Responsibility mandates:California, Oregon, and Maine are accelerating post-consumer content thresholds, compelling resin qualification investments that lock in supplier relationships.
- Foodservice tamper-evident adoption:Clamshell formats with integrated security features are capturing produce and prepared-meal segments as theft-deterrence becomes a procurement priority.
- Southeastern manufacturing corridor concentration:Georgia, North Carolina, and South Carolina are attracting integrated sheet extrusion and thermoforming investments due to resin terminal access and logistics infrastructure.
Market Restraints
- Recycled PET feedstock volatility:Bottle bale quality inconsistency and collection infrastructure gaps create resin specification uncertainty that elevates scrap rates and reprocessing costs.
- FDA food-contact notification friction:Tightened compliance thresholds for recycled content claims extend qualification timelines and increase regulatory consulting expenditure.
- Alternative substrate competition:Fiber-based molded pulp formats are displacing thermoformed trays in select produce and egg applications where wet-strength performance improves.
Strategic Opportunities
- Medical device sterile barrier expansion:Thermoformed trays with multi-layer barrier structures are penetrating orthopedic and surgical kit packaging as sterilization validation protocols mature.
- Captive recycling infrastructure:Integrated collection-to-sheet operations in the Southeast corridor offer feedstock security distinct from distributed post-consumer bale markets.
- OSHA workplace chemical exposure alignment:Styrene and vinyl chloride monomer monitoring investments position early adopters for accelerated permitting in constrained manufacturing zones.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Operating expertise for barrier-adhesive-structural layer sequencing is concentrated among aging workforce cohorts with limited apprenticeship pipeline depth.
- Legacy ERP integration with track-and-trace systems:FDA food-contact lot genealogy requirements are forcing middleware investments that strain IT capital budgets at mid-scale thermoforming operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Rigid Thermoform Plastic Packaging Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $65.83 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshells, Skin Packaging, Food Containers End User: Food & Beverage, Healthcare, Electronics, Consumer Goods Material: PET, PVC, PS, PP Application: Storage, Transportation, Display, Shelf Life Extension |
| Companies Covered | Pactiv Evergreen Inc., Genpak LLC, Amcor plc, Display Pack, Huhtamaki Oyj, Sonoco Products Company, Anchor Packaging LLC, EasyPak, Dart Container Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Rigid Thermoform Plastic Packaging Market Strategic Shifts & Innovations
Digital twin simulation is virtualizing thermoforming process development, compressing tooling iteration cycles and enabling remote optimization of forming temperature and vacuum profiles across distributed production networks.
Digital twin platforms are virtualizing mold flow and sheet sag prediction for complex deep-draw geometries. Protein processors and medical device manufacturers are adopting these tools to reduce aluminum prototype tooling expenditure. The technology is virtualizing traditional cut-and-try development methodologies that previously required physical mold iterations.
FDA's updated food-contact substance notification process is tightening evidentiary standards for recycled content migration testing. Thermoformers must now submit extended-use temperature simulation data and secondary recycling stream composition analysis. Food container segments with hot-fill and retort applications face the steepest compliance cost escalation.
Consolidated buying desks at national food retail chains are compressing supplier qualification cycles and unbundling technical service from unit pricing negotiations. Regional thermoformers without dedicated account engineering resources are losing shelf-space allocation to integrated packaging suppliers. The Southeastern manufacturing corridor exhibits the most pronounced buyer concentration effects.
US Rigid Thermoform Plastic Packaging Market Segmentation
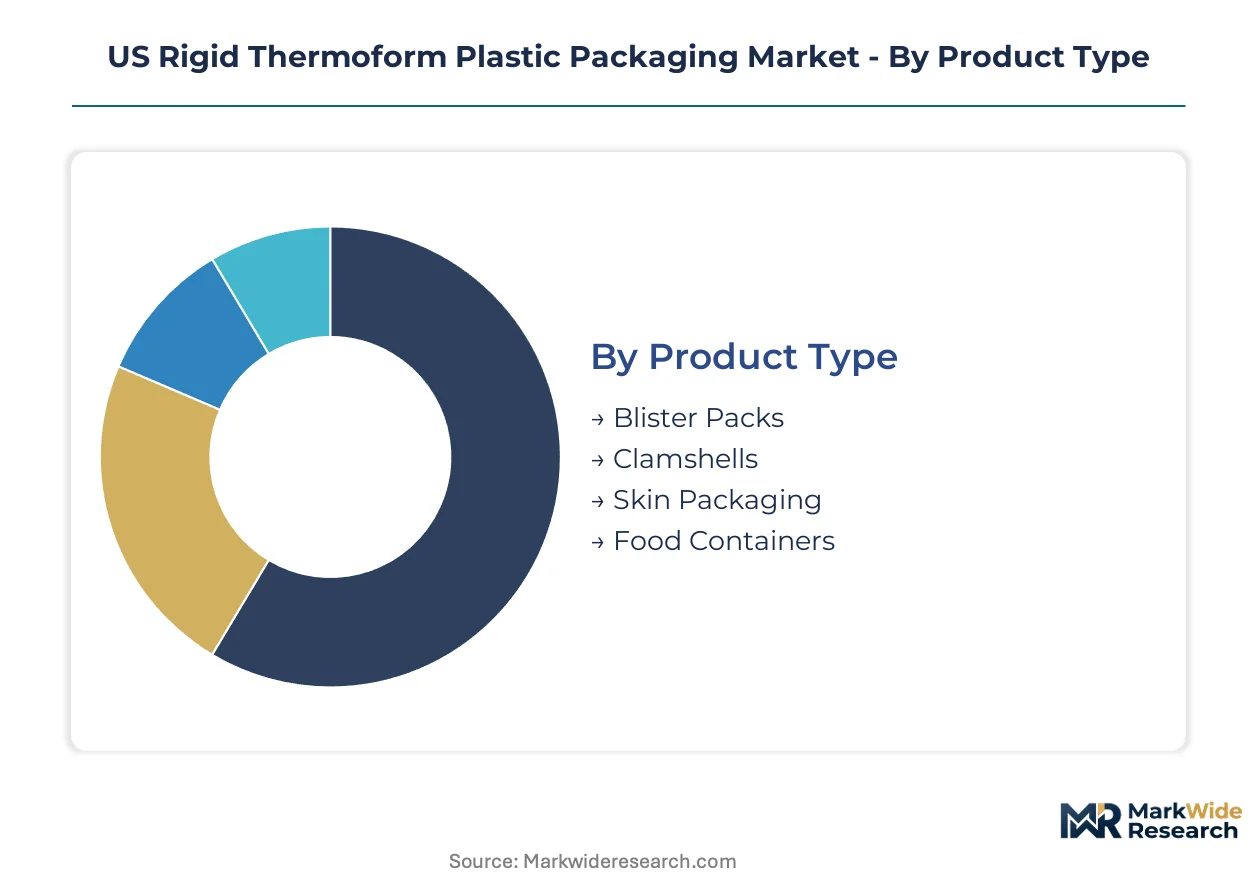
Segmentation in US rigid thermoform plastic packaging reveals how material specifications, product formats, and end-use requirements fragment procurement patterns across distinct buyer ecosystems. Each dimension carries unique compliance burdens and margin structures that reshape competitive positioning.
Product Type:
Formats span theft-deterrent retail security to protein preservation systems, with each configuration demanding specialized tooling and barrier engineering.
- Clamshells:Hinged, two-piece containers with integral locking mechanisms dominate produce and electronics retail. Georgia and North Carolina thermoforming operations supply national grocery chains where theft reduction drives procurement specifications.
- Skin Packaging:Vacuum-sealed film-to-board systems for case-ready meat display are penetrating protein processing plants. The format's oxygen barrier properties satisfy extended retail case life requirements while eliminating foam tray displacement costs.
- Blister Packs:Formed cavities sealed to printed card stock serve pharmaceutical unit-dose and small electronics packaging. PVC and PET formulations predominate where product visibility and child-resistance specifications converge.
- Food Containers:Lidded trays and bowls for prepared meals and deli applications require hot-fill and retort compatibility. FDA food-contact notification compliance costs concentrate margin capture among integrated sheet extruders.
The dominant share belongs to Clamshells, while Skin Packaging is gaining share fastest as protein processors convert from foam alternatives.
End User:
Customer procurement sophistication varies sharply, with national account engineering resources determining supplier qualification success.
- Food & Beverage:National retail chains and foodservice distributors drive volume through consolidated buying desks. Southeastern manufacturing corridor proximity to resin terminals enables just-in-time delivery commitments that lock in multi-year supply agreements.
- Healthcare:Medical device manufacturers and pharmaceutical packagers impose sterile barrier validation protocols. Multi-layer thermoformed trays for orthopedic kits command premium positioning where ethylene oxide sterilization compatibility is mandatory.
- Electronics:ESD-sensitive component packaging and retail clamshells for consumer devices require static-dissipative formulations. California and Texas electronics manufacturing clusters source through qualified vendor lists with restricted resin approval processes.
- Consumer Goods:Cosmetics, hardware, and toy packaging segments prioritize shelf impact and theft deterrence. Shorter product lifecycles accelerate tooling amortization pressures on mid-scale thermoforming operations.
Food & Beverage commands the deepest volume pools, though Healthcare exhibits the steepest margin expansion trajectory as sterilization validation protocols mature.
Material:
Resin selection balances clarity, barrier performance, and recycled content compliance against FDA food-contact and state EPR mandates.
- PET:Amorphous and crystalline grades deliver optical clarity and oxygen barrier for food containers and blister packs. Post-consumer recycled feedstock integration is reconfiguring extrusion lines across the Southeast as California and Oregon content thresholds tighten.
- PVC:Rigid formulations serve pharmaceutical blister packs and medical device trays where sterilization compatibility and cost efficiency converge. Vinyl chloride monomer exposure monitoring investments position compliant producers for OSHA-constrained manufacturing zones.
- PS:High-impact and oriented polystyrene grades dominate low-cost foodservice and consumer goods applications. Fiber-based molded pulp substitution is displacing PS trays in select produce and egg segments where wet-strength performance improves.
- PP:High-barrier coextruded structures penetrate hot-fill and retort food applications. The material's microwave compatibility and extended temperature stability justify premium positioning in prepared meal segments.
PET retains the largest installed base, while PP is climbing the fastest as hot-fill and retort applications expand.
Application:
Functional requirements determine barrier specifications, with shelf-life extension commanding the most complex multi-layer engineering.
- Storage:Stackable trays and lidded containers for warehouse and cold-chain distribution prioritize dimensional stability and nesting efficiency. Foodservice operators in the Southeast specify tamper-evident closures for prepared meal inventory.
- Shelf Life Extension:Modified atmosphere packaging with oxygen scavenger integration and high-barrier EVOH layers retards spoilage in protein and produce applications. FDA migration testing requirements for recycled content claims escalate qualification costs.
- Display:Retail-ready formats with printed graphics integration and theft-deterrent features secure shelf space allocation. National grocery chains compress supplier qualification cycles and unbundle technical service from unit pricing.
- Transportation:Dunnage trays and protective containers for automotive and electronics components absorb shock and prevent ESD damage. Reusable format adoption is displacing single-use thermoformed dunnage in closed-loop manufacturing systems.
Shelf Life Extension captures the most sophisticated barrier engineering investment, though Display applications drive the highest tooling velocity for format refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consolidated buying desks at national food retail chains concentrate procurement leverage in the Southeastern manufacturing corridor. Georgia, North Carolina, and South Carolina host integrated sheet extrusion and thermoforming investments that lock in multi-year supply agreements.
Georgia
Foodservice distributors and prepared-meal processors drive clamshell format demand across Atlanta and Savannah logistics hubs. EPA recycled-content procurement guidelines shape resin qualification protocols for post-consumer PET integration. The Interstate 85 corridor attracts thermoforming operations seeking proximity to Port of Savannah resin terminal access.
North Carolina
Produce retail chains and protein processors specify tamper-evident skin packaging for case-ready meat display. OSHA workplace chemical exposure limits for styrene monomer influence plant-level monitoring investments in Charlotte and Raleigh-Durham manufacturing zones. The Research Triangle anchors digital twin simulation adoption for tooling development compression.
South Carolina
Automotive and electronics manufacturers source dunnage trays and ESD-sensitive component packaging from Greenville-Spartanburg operations. State-level extended producer responsibility frameworks remain less stringent than California or Oregon, permitting operational flexibility for multi-site producers. The Upstate region concentrates reusable format development for closed-loop manufacturing systems.
California
Pharmaceutical blister pack demand and medical device sterile barrier requirements concentrate in San Diego and Los Angeles manufacturing clusters. The state's post-consumer content mandates force distinct resin qualification protocols that fragment feedstock access for multi-site producers. CalRecycle enforcement tightens compliance thresholds for recycled content claims in food-contact applications.
Texas
Electronics retail clamshells and consumer goods packaging serve Dallas-Fort Worth and Austin manufacturing hubs. FDA food-contact notification friction extends qualification timelines for hot-fill and retort food containers produced along the I-35 corridor. Houston petrochemical infrastructure supplies virgin resin streams that compete with recycled PET feedstock economics.
US Rigid Thermoform Plastic Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply relationships. National food brands and retail chains consolidate procurement through integrated packaging suppliers with dedicated account engineering resources. Three archetypes dominate: integrated sheet extruders with captive resin networks, format specialists in hinged containers or sterile barriers, and regional thermoformers serving localized foodservice distributors. Competitive moves center on multi-layer coextrusion capacity expansion and captive recycling infrastructure deployment.
Within the integrated extrusion tier, Amcor plc and Pactiv Evergreen Inc. exemplify scale-driven positioning through upstream resin control. Genpak LLC occupies a specialist position in foodservice channel formats. These three companies anchor the competitive structure that regional thermoformers must navigate without equivalent technical service resources.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Amcor plc |
| Display Pack |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Anchor Packaging LLC |
| EasyPak |
| Dart Container Corporation |
| Others |
Cost & Logistics Intelligence
Resin terminal concentration along the Gulf Coast and Southeastern logistics corridors positions integrated sheet extruders to capture margin pools that fragmented regional thermoformers cannot access. Post-consumer recycled PET feedstock volatility compresses pricing power for mid-scale operators lacking captive collection infrastructure.
Pricing Analysis
Cost-plus contracts indexed to virgin PET resin futures dominate procurement between national food brands and integrated packaging suppliers. Price differentiation hinges on FDA food-contact notification tier and volume scale, with hot-fill and retort-compatible containers commanding premium positioning. Pricing pressure stems from consolidated buying desks at national retail chains unbundling technical service from unit pricing. Foodservice distributors exhibit the highest price sensitivity, while medical device manufacturers prioritize sterile barrier validation over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated extruders strain working capital for regional thermoformers competing on thin margins. Feedstock sourcing draws from domestic bottle bale collection networks, Canadian reprocessing facilities, and Mexican virgin resin streams. Single-source vulnerability concentrates in post-consumer PET flake supply where collection infrastructure gaps create specification uncertainty. Distribution runs through Southeastern manufacturing corridor consolidation with just-in-time delivery commitments locking in multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer content mandates across California, Oregon, and Maine are accelerating capital reallocation toward compliant infrastructure faster than legacy equipment depreciation cycles allow. This regulatory inflection compresses qualification timelines and elevates technical barriers to entry.
For Market Incumbents: Insulate margin position through captive recycling infrastructure deployment in the Southeastern corridor where resin terminal access lowers feedstock logistics costs. Accelerate multi-layer coextrusion technician apprenticeship pipelines to address workforce scarcity that threatens barrier-adhesive-structural layer sequencing expertise. Defend against fiber-based molded pulp substitution in produce applications by emphasizing theft-deterrent clamshell functionality.
For New Entrants and Emerging Players: Medical device sterile barrier expansion in orthopedic and surgical kit packaging represents the most penetrable entry point given sterilization validation protocol maturation and premium margin pools. Regional foodservice distributors without dedicated account engineering resources offer white-space access where national integrated suppliers have deprioritized technical service investment. Pursue digital twin simulation partnerships with Research Triangle engineering firms to compress tooling development cycles without aluminum prototype expenditure.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated sheet extruders with captive resin networks and FDA food-contact notification expertise that national retail chains require for multi-year supply agreements. Long-term viability hinges on post-consumer recycled content compliance readiness across tightening state EPR frameworks. Watch CalRecycle enforcement actions against recycled content claim violations as the signal for qualification cost escalation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Deployment | Integrated collection-to-sheet operations in Georgia and North Carolina secure feedstock against bale market volatility. |
| Multi-Layer Coextrusion Capacity Expansion | Barrier-adhesive-structural layer sequencing capability captures medical device sterile barrier premium positioning. |
| Digital Twin Simulation Adoption | Virtual mold flow prediction compresses aluminum prototype tooling expenditure for protein processor clients. |
| FDA Food-Contact Notification Investment | Extended-use temperature simulation data submission accelerates qualification timelines for hot-fill applications. |
| Southeastern Manufacturing Corridor Consolidation | Proximity to Port of Savannah resin terminals enables just-in-time delivery commitments locking national accounts. |
Research Approach
Initial hypotheses were tested against primary input from thermoforming plant managers, national food brand procurement directors, medical device packaging engineers, and resin reprocessing facility operators and refined through secondary validation. Bottom-up demand modeling triangulated against top-down macroeconomic indicators incorporated SEC 10-K filings from integrated packaging suppliers, EPA recycled-content procurement guideline documents, FDA food-contact substance notification databases, and customs trade data on resin imports. Stakeholder interviews explored capital allocation tension between compliance readiness and margin preservation.
Demand-supply balance framing anchored the analytical framework across the projection horizon with segmentation modeled by product type, material specification, end-use application, and regional manufacturing corridor concentration. CAGRs derived from installed capacity expansion announcements, resin qualification investment pipelines, and buyer concentration effects in consolidated retail procurement. Forecast inputs incorporated post-consumer recycled PET integration timelines and state EPR mandate implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in resin commodity price cycles, interest rate environments affecting capital equipment financing, or logistics cost structures would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and collection infrastructure buildout pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market