
 Organic Rice Market | 2026-2036
Organic Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Rice Market Outlook
Consolidation among North American supermarket chains is realigning procurement volumes toward fewer, larger suppliers with certified organic handling capacity. Lundberg Family Farms leverages its multi-generational organic heritage and California processing infrastructure to secure long-term retail contracts. KRBL Limited anchors its position through integrated milling and aging facilities in India that supply premium basmati to Middle Eastern importers. Olam International competes across origination, processing, and distribution nodes on four continents.
Organic rice denotes grain cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, meeting certification standards that mandate soil health protocols and buffer zones from conventional fields. The grain serves food manufacturers, foodservice operators, and direct consumers seeking residue-free carbohydrate sources with traceable provenance. Long grain and basmati varieties dominate value pools in export markets where aroma and elongation properties command price premiums. Specialty stores and online retail channels represent the fastest-growing distribution pathways as direct-to-consumer subscription models bypass traditional wholesale markups.
The USDA National Organic Program, EU organic regulations under the European Commission, and India's APEDA organic certification framework collectively shape market access through divergent residue limits and inspection protocols. Compliance costs and transition-period yield penalties deter smallholder conversion in Southeast Asia, constraining supply elasticity. Stakeholders must monitor evolving equivalency agreements between major importing blocs that could abruptly reroute trade flows.
Market Dynamics
Organic rice supply chains face acute pressure from tightening residue thresholds under the USDA National Organic Program and EU organic regulations, forcing processors to rebuild sourcing networks around certified handling infrastructure rather than spot-market procurement.
Growth Catalysts
- EU organic regulations:Tightening pesticide residue limits under the European Commission's updated organic framework are pushing Middle Eastern and European importers toward certified Indian basmati suppliers with integrated traceability systems.
- Specialty retail chains:North American and European grocers are expanding dedicated organic grain sections, creating shelf-space pull that rewards suppliers with multi-year certification histories and regional processing assets.
- Direct-to-consumer subscription models:Online retail channels are bypassing traditional wholesale markups, enabling smaller mills to capture margin previously lost to distributor tiers.
Market Restraints
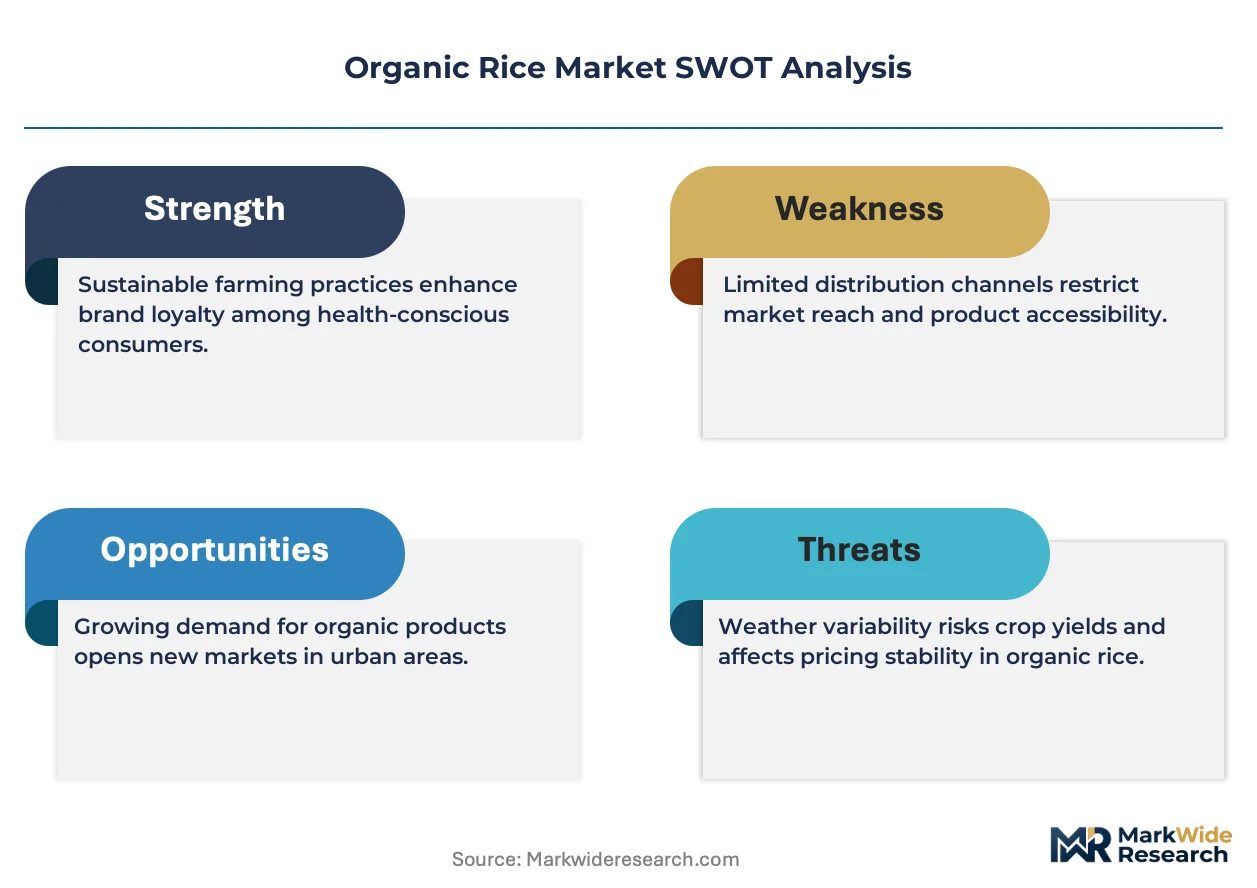
- Transition-period yield penalties:The three-year organic conversion window mandated by certification bodies imposes revenue losses on conventional growers considering switchover, particularly in water-stressed districts of Punjab and Haryana.
- Input cost volatility:Organic manure and biopesticide prices fluctuate with fossil fuel markets, compressing margins for growers locked into fixed-price export contracts.
- Inspection protocol fragmentation:Divergent residue limits between USDA National Organic Program, EU organic regulations, and India's APEDA organic certification framework force exporters to maintain parallel compliance systems.
Strategic Opportunities
- Underpenetrated foodservice channels:Institutional buyers in Saudi Arabia and the UAE are developing organic procurement mandates for hospital and university catering contracts.
- Carbon credit stacking:Methane-reduced rice cultivation protocols are qualifying for voluntary carbon markets, creating secondary revenue streams for growers with verified measurement systems.
- Blockchain-enabled provenance:Distributed ledger systems are unifying certification records, farm-level data, and shipment documentation into single-source traceability platforms that command retail premiums.
Industry Challenges
- Certification timeline compression:The three-year transition period creates working capital strain for smallholders who must maintain operations while yields drop and input costs rise.
- Buffer zone enforcement:Mandatory separation distances from conventional fields are reducing plantable acreage in densely cultivated river delta regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Rice Market |
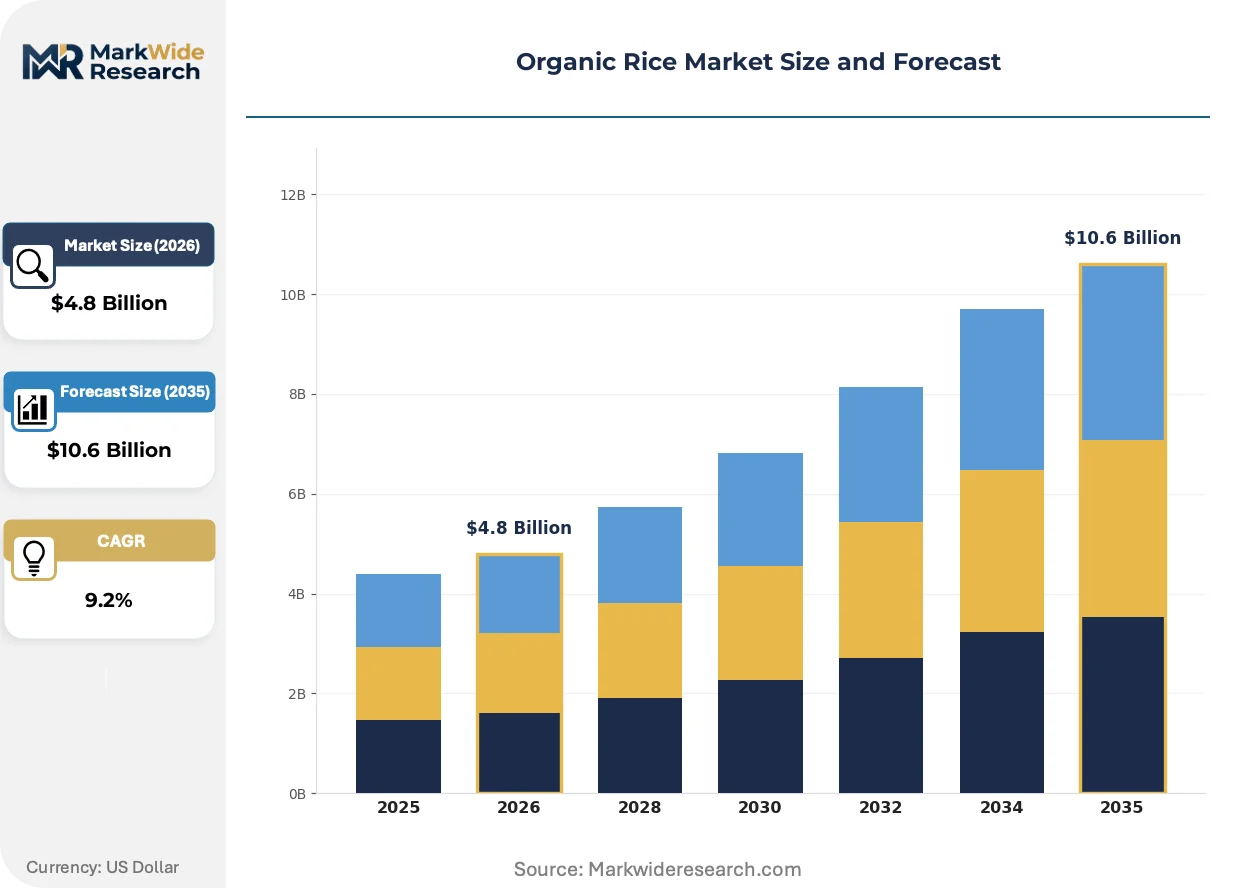
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Short Grain, Jasmine, Basmati End Use Industry: Food & Beverage, Restaurants, Retail Stores, Organic Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Package Type: Bags, Boxes, Bulk, Recyclable Packaging |
| Companies Covered | Riceland Foods, Inc., Charoen Pokphand Foods Public Company Limited, Lundberg Family Farms, Ebro Foods, S.A., China National Cereals, Oils and Foodstuffs Corporation, LT Foods Limited, Olam International Limited, Ricegrowers Limited, KRBL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Rice Market Strategic Shifts
Organic rice markets are experiencing fundamental restructuring around traceability infrastructure and procurement centralization, with technology investments shifting from yield optimization to verification and certification management systems.
Blockchain-based supply chain platforms are unifying previously siloed certification records, farm audit data, and shipment documentation into immutable ledgers. European importers and premium North American retailers are mandating these systems for contract eligibility. This unification is compressing the information advantage previously held by integrated traders with proprietary sourcing networks.
The EU Green Deal's Farm to Fork Strategy is tightening pesticide residue thresholds and expanding mandatory origin labeling requirements for organic grains entering European customs territory. Processing clusters in India are responding by investing in in-house laboratory testing capacity rather than relying on third-party certifiers. Basmati exporters serving German and Dutch buyers face the steepest compliance ramps.
Subscription-based direct purchasing is displacing traditional wholesale distribution for household organic rice buyers. Specialty online retailers and farm-direct platforms are capturing urban consumers in California, New York, and London who prioritize traceable provenance over shelf convenience. This channel shift is most visible among millennial and Gen-Z demographics with established organic purchasing habits.
Organic Rice Market Segmentation
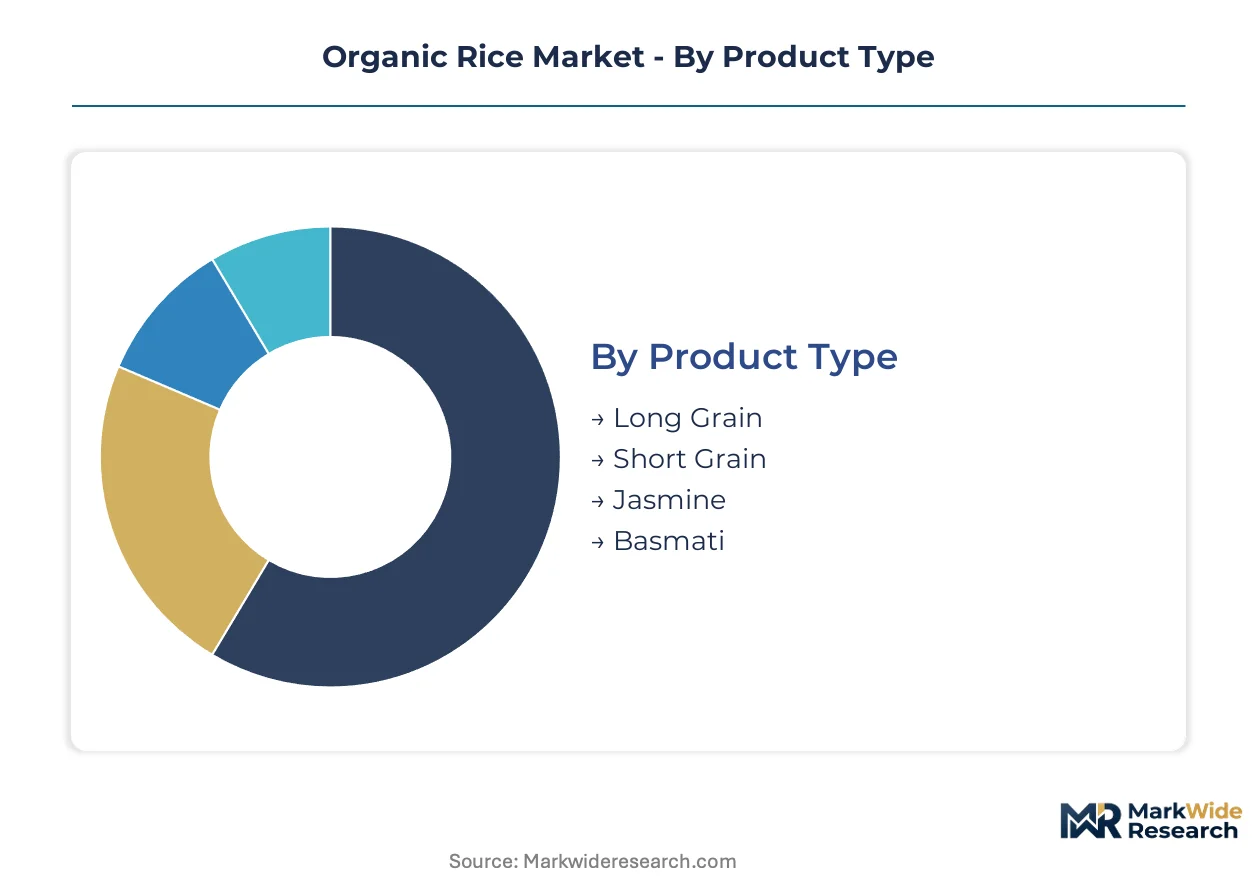
Organic rice segmentation reveals how certification standards, aroma profiles, and channel access determine margin capture across the value chain. Grain variety and distribution pathway together shape which suppliers qualify for premium retail placement versus commodity foodservice contracts.
Product Type:
Integration depth varies sharply across varieties, with aromatic specialty grains commanding standalone premium positioning while commodity long grain serves as an embedded ingredient in processed foods.
- Basmati:Aromatic long-grain variety distinguished by elongation upon cooking and distinctive nutty fragrance. Indian export clusters in Punjab and Haryana supply premium-grade basmati to Middle Eastern importers under India's APEDA organic certification framework, with EU residue thresholds tightening eligibility requirements.
- Long Grain:Standard slender kernel rice lacking aromatic compounds, valued for neutral flavor absorption and cost efficiency. Demand concentrates in North American food manufacturing where it functions as an embedded carbohydrate base for organic frozen meals and ready-to-eat bowls.
- Short Grain:Plump, sticky-textured kernels suited to sushi and pudding applications. Japanese and Korean organic standards govern quality specifications for export-grade short grain.
- Jasmine:Thai-origin aromatic variety with floral notes and soft, clingy texture. Thailand's national organic certification program and EU equivalency agreements shape export viability.
Volume placements concentrate in Long Grain; the faster expansion belongs to Basmati.
End Use Industry:
Cost tier stratification separates institutional procurement with rigid specifications from discretionary consumer purchases where provenance commands price elasticity.
- Food & Beverage:Ingredient procurement by organic processed food manufacturers for cereals, baby food, and plant-based beverages. USDA National Organic Program handling requirements force dedicated supply chain segregation.
- Restaurants:Foodservice operators sourcing certified organic rice for menu differentiation in urban centers. Saudi Arabia and UAE hospital and university catering contracts are developing organic procurement mandates.
- Retail Stores:Packaged grain sales through supermarket chains and independent grocers. Specialty retail chains across Germany and the Netherlands are expanding dedicated organic grain sections.
- Organic Products:Branded finished goods positioned explicitly around organic certification, including subscription-based direct-to-consumer platforms.
Procurement volumes cluster in Food & Beverage; Restaurants are climbing the fastest as institutional mandates proliferate.
Distribution Channel:
Customer type determines whether suppliers capture margin through direct relationships or surrender value to intermediary tiers.
- Online Retail:Direct-to-consumer subscription models and specialty e-commerce platforms. California, New York, and London urban consumers with established organic purchasing habits drive channel expansion.
- Supermarkets:Consolidated North American and European grocery chains with centralized procurement. Multi-year certification histories and regional processing assets determine contract eligibility.
- Specialty Stores:Independent natural food retailers and organic cooperatives. These channels reward traceable provenance and small-batch milling credentials.
- Wholesale:Bulk distribution to foodservice distributors and industrial processors. Traditional wholesale markups are compressing as alternative channels proliferate.
Supermarkets retain the largest throughput; Online Retail is gaining share fastest among millennial and Gen-Z demographics.
Package Type:
Supply concentration in sustainable materials is reshaping packaging procurement as EU Green Deal requirements extend to organic grain imports.
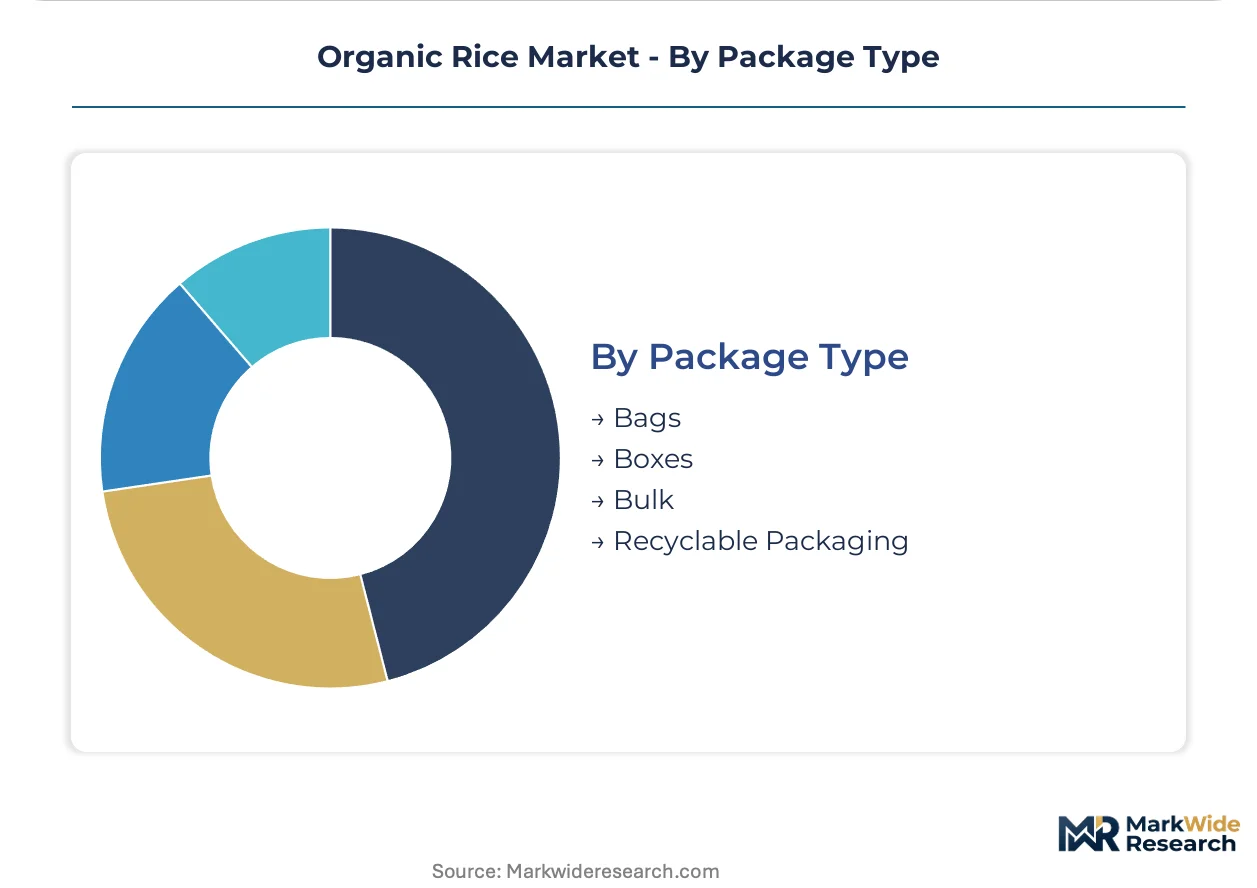
- Bags:Standard woven polypropylene or paper packaging for retail and foodservice volumes. Conventional bag specifications face pressure from retailer sustainability mandates.
- Recyclable Packaging:Compostable films, paper-based laminates, and reusable container systems. German and Dutch buyers are mandating these formats for contract eligibility under Farm to Fork Strategy alignment.
- Bulk:Unpackaged grain for institutional procurement and food manufacturing. Food & Beverage processors favor bulk to minimize per-unit packaging costs.
- Boxes:Rigid cardboard packaging for premium retail presentation and gift assortments. Specialty stores and online retail channels favor boxed formats for shelf differentiation.
Bulk shipments dominate foodservice procurement; Recyclable Packaging shows the steepest expansion trajectory as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates export-oriented demand for premium organic basmati, with processing clusters in Punjab and Haryana supplying Middle Eastern and European buyers. Specialty retail chains in Germany and the Netherlands are expanding organic grain sections, tightening residue thresholds under EU Green Deal mandates. The United States, Saudi Arabia, and Thailand round out the five-country demand map.
India
Punjab and Haryana export clusters supply premium basmati to UAE and Saudi Arabian importers seeking certified organic grains. India's APEDA organic certification framework governs export eligibility, with residue testing protocols tightening ahead of EU equivalency reviews. Processing facilities in Amritsar and Karnal are investing in in-house laboratory capacity to bypass third-party bottlenecks.
Germany
Retail chains Rewe and Edeka are dedicating expanded shelf space to certified organic grains, pulling volume from suppliers with multi-year certification histories. The EU Green Deal's Farm to Fork Strategy mandates stricter pesticide residue thresholds and origin labeling for organic imports. Hamburg and Rotterdam serve as the primary entry points for Indian basmati bound for German distribution centers.
United States
California and Arkansas growers serve domestic food manufacturers and direct-to-consumer subscription platforms. The USDA National Organic Program requires three-year conversion periods and buffer zones from conventional fields, constraining supply elasticity in the Sacramento Delta. Lundberg Family Farms leverages multi-generational organic heritage to secure long-term contracts with Whole Foods and Kroger divisions.
Saudi Arabia
Hospital and university catering contracts are developing organic procurement mandates, creating institutional demand channels previously absent. The Saudi Food and Drug Authority aligns import standards with EU organic regulations, favoring Indian suppliers with integrated traceability systems. Jeddah and Riyadh distribution hubs are certifying dedicated organic handling infrastructure to meet inbound shipment requirements.
Thailand
Jasmine rice exports to European premium retailers are expanding under national organic certification programs with EU equivalency agreements. The Department of Agriculture enforces organic standards for export-grade aromatic varieties, with Chiang Mai and Ubon Ratchathani provinces concentrating grower cooperatives. Processing mills in the Central Plains are adopting blockchain traceability to capture retail premiums from German and Dutch buyers.
Organic Rice Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and carbon credit stacking. The vendor base stratifies across integrated multinational traders, regional millers with captive aging facilities, and family-owned operations leveraging multi-generational certification histories. Three archetypes dominate: scale-driven originators with four-continent processing networks, specialty basmati suppliers with Punjab-Haryana integration, and heritage California growers with retail contract lock-in. Competitive moves concentrate on backward integration into certified handling infrastructure and strategic partnerships with blockchain traceability platforms.
Within the integrated multinational tier, Olam International Limited and Charoen Pokphand Foods Public Company Limited exemplify scale-driven origination spanning milling, aging, and distribution nodes. Among specialty basmati suppliers, KRBL Limited and LT Foods Limited occupy positions anchored by Punjab-based processing clusters serving Middle Eastern importers. Lundberg Family Farms represents the heritage-grower archetype, leveraging California infrastructure to secure North American retail contracts.
| Leading Market Players |
|---|
| Riceland Foods, Inc. |
| Charoen Pokphand Foods Public Company Limited |
| Lundberg Family Farms |
| Ebro Foods, S.A. |
| China National Cereals, Oils and Foodstuffs Corporation |
| LT Foods Limited |
| Olam International Limited |
| Ricegrowers Limited |
| KRBL Limited |
| Others |
Value Chain & Pricing Dynamics
Blockchain-enabled traceability systems are compressing information asymmetries between growers and premium buyers, simultaneously raising compliance costs for smallholders and concentrating pricing power among integrated processors with in-house laboratory capacity. This technological shift redraws cost curves across the value chain while rewarding suppliers who control certified handling infrastructure from farm gate to export terminal.
Pricing Analysis
Volume placements cluster in commodity long grain sold through food manufacturing contracts, while margin capture concentrates in aromatic basmati varieties commanding retail premiums. Three-tier pricing structure across premium certified organic, transitional organic, and conventional grades reflects certification history and residue testing rigor. Pricing pressure stems from input cost volatility in organic manure and biopesticide markets, compressing margins for growers locked into fixed-price export contracts. Foodservice distributors exhibit highest price sensitivity due to rigid institutional procurement budgets, whereas direct-to-consumer subscription buyers demonstrate lowest elasticity for traceable provenance.
Supply Chain Analysis
Direct-to-retail channels handle premium basmati demand from German and Dutch buyers, while bulk wholesale distribution serves North American food manufacturing procurement. Geographic supply concentrates in India, Thailand, and the United States, with Punjab-Haryana clusters, Chiang Mai cooperatives, and Sacramento Delta growers anchoring respective regional flows. Raw material dependencies center on certified organic seed stock, organic manure inputs, and biopesticide formulations. Single-source vulnerability runs through Indian export clusters serving Middle Eastern importers under APEDA certification frameworks. Distribution runs through integrated multinational traders with four-continent processing networks, regional millers with captive aging facilities, and heritage growers with retail contract lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic rice market is becoming a vertical-integration race, with backward control over certified handling infrastructure and in-house testing capacity emerging as the decisive competitive lever.
For Market Incumbents: Hedge against margin compression by securing long-term offtake agreements with Punjab-Haryana grower cooperatives before EU equivalency reviews tighten eligibility. Invest in parallel USDA and EU organic certification systems to bypass inspection protocol fragmentation that delays shipments. Control regional processing assets in target markets to reduce exposure to logistics chokepoints and tariff exposure on finished goods. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting California and New York urban demographics with established organic purchasing habits, bypassing wholesale distributor markups entirely. Target underpenetrated foodservice channels in Saudi Arabia and UAE where hospital and university catering contracts are developing organic procurement mandates without entrenched supplier relationships. Pursue carbon credit stacking through methane-reduced cultivation protocols to create secondary revenue streams that offset transition-period yield penalties. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated multinational traders seeking Punjab-Haryana processing capacity and multi-generational certification histories. Over a five-to-ten year horizon, vertically integrated specialists with blockchain traceability platforms and in-house laboratory testing capacity demonstrate strongest viability. Monitor EU-India organic equivalency agreement negotiations as the critical inflection signal that could abruptly reroute trade flows and revalue certification assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Handling Infrastructure | Captures margin previously surrendered to third-party organic certifiers and reduces inspection bottlenecks under EU Green Deal mandates. |
| Blockchain Traceability Platform Deployment | Unifies APEDA, USDA, and EU certification records into immutable ledgers that command retail premiums from Rewe and Edeka buyers. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional wholesale markups in North American and European distribution tiers while building proprietary customer data assets. |
| Carbon Credit Stacking Program | Qualifies methane-reduced rice cultivation for voluntary carbon markets, creating secondary revenue streams for transition-period growers. |
| In-House Laboratory Testing Capacity Investment | Reduces dependency on third-party certifiers as EU residue thresholds tighten ahead of Farm to Strategy implementation deadlines. |
Study Parameters
Multi-period observation of certification conversion timelines, residue threshold adjustments, and retail shelf-space allocations anchored the trend analysis, supplemented by interviews with organic certification body auditors, export processing cluster managers, Middle Eastern import procurement officers, and North American specialty retail category buyers. Secondary validation drew from USDA National Organic Program enforcement data, EU Commission organic regulation updates, APEDA export statistics, and trade flow databases. Bottom-up grower conversion modeling and top-down retail demand projections were triangulated against processing capacity utilization rates.
Input-output matrices mapped grain variety, certification tier, distribution channel, and end-use industry against geographic supply clusters and regulatory framework equivalencies across the analysis window. CAGRs were derived from segmented volume and value projections incorporating transition-period yield penalty assumptions, buffer zone enforcement impacts on plantable acreage, and channel shift acceleration in direct-to-consumer platforms. Forecast inputs included EU-India organic equivalency negotiation timelines, Saudi Food and Drug Authority alignment trajectories with EU standards, and blockchain traceability adoption curves among premium European retailers.
The model assumes a particular technology adoption path for blockchain-enabled provenance systems; alternative pathways for distributed ledger integration or regulatory recognition of alternative verification methods would alter the outlook. Forecasts reflect assumptions regarding certification timeline compression, inspection protocol harmonization, and carbon market qualification standards that remain subject to policy revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Maize Market
Grains
Paraguay Grains Market
Grains
Organic Wheat Flour Market
Grains
Green Pea Grits Market
Grains
Asia Pacific Wheat Protein Market
Grains
Pea Grits Market
Grains
Torrified Wheat Market
Grains
Cultured Wheat Market
Grains
Organic Rice Flour Market
Grains
White Rice Flour Market
Grains
00 Flour Market
Grains
Global Quinoa Market
Grains
GCC Basmati Rice Market
Grains
Mexico Rice Market
Grains
Wheat Flour Market
Grains
United States Maize Market