
 Auto Keratometer Market | 2026-2036
Auto Keratometer Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Keratometer Market Analysis
Optical-grade polymers are displacing legacy metal housings in keratometer construction, which is broadening the addressable market for cost-efficient portable units. Nidek Co., Ltd. leverages in-house lens grinding capabilities to sustain premium positioning across Asian markets. Carl Zeiss Meditech AG anchors its portfolio on integrated diagnostic workstations that bundle keratometry with wavefront aberrometry.
An auto keratometer measures corneal curvature and refractive power through Placido disk reflection or Scheimpflug tomography, typically resolving curvature to 0.01 diopter precision across 3-9 mm optical zones; ophthalmologists and optometrists deploy these instruments to quantify astigmatism prior to cataract extraction or toric intraocular lens implantation. Digital Keratometers now lead unit shipments among product types, while Advanced Imaging Systems command the highest installed-base margins due to software-recurring revenue streams. Contact Lens Fitting applications show the fastest volume growth as scleral and orthokeratology lens protocols require precise eccentricity mapping.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) Class IIa requirements govern commercial access, with CE marking under the MDR now mandating clinical evidence summaries that extend registration timelines. Japan's PMDA enforces QMS conformity audits for imported ophthalmic devices, filtering out smaller manufacturers lacking Japanese regulatory infrastructure. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify cloud-connected keratometers under stricter cybersecurity and clinical validation protocols.
Market Dynamics
The auto keratometer market pivots on the FDA's 510(k) clearance pathway, which compresses commercialization timelines for Placido disk and Scheimpflug-based systems while filtering out undercapitalized entrants lacking clinical validation infrastructure.
Growth Catalysts
- Aging Demographics:Cataract surgery volumes in the United States, Germany, and Japan drive replacement demand for high-precision curvature mapping instruments.
- EU MDR Clinical Evidence Mandate:Stricter CE marking requirements under the Medical Device Regulation favor established manufacturers with robust quality management systems.
- Scleral Lens Protocol Expansion:Orthokeratology and specialty contact lens fitting protocols require eccentricity mapping that manual keratometers cannot deliver.
Market Restraints
- Optical-Grade Polymer Input Volatility:Specialized polymer housings face price pressure from petrochemical feedstock fluctuations.
- Japanese Regulatory Infrastructure Barrier:PMDA-mandated QMS conformity audits exclude smaller manufacturers lacking local compliance capabilities.
- Wavefront Aberrometry Substitution:Integrated diagnostic workstations bundle keratometry with competing technologies, compressing standalone unit demand.
Strategic Opportunities
- Cloud-Connected Device Reclassification:Software-as-a-medical-device frameworks create first-mover advantage for cybersecurity-validated platforms.
- Portable Unit Cost Reduction:Polymer housing substitution enables point-of-care deployment in underserved eye clinic networks.
- Recurring Revenue Software Models:Advanced imaging systems with subscription-based analytics separate hardware margins from service lifetime value.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Medical device quality management system audits extend product launch schedules by twelve to eighteen months.
- Legacy System Integration Complexity:Electronic health record interoperability requirements demand costly software bridge development for installed base upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Keratometer Market |
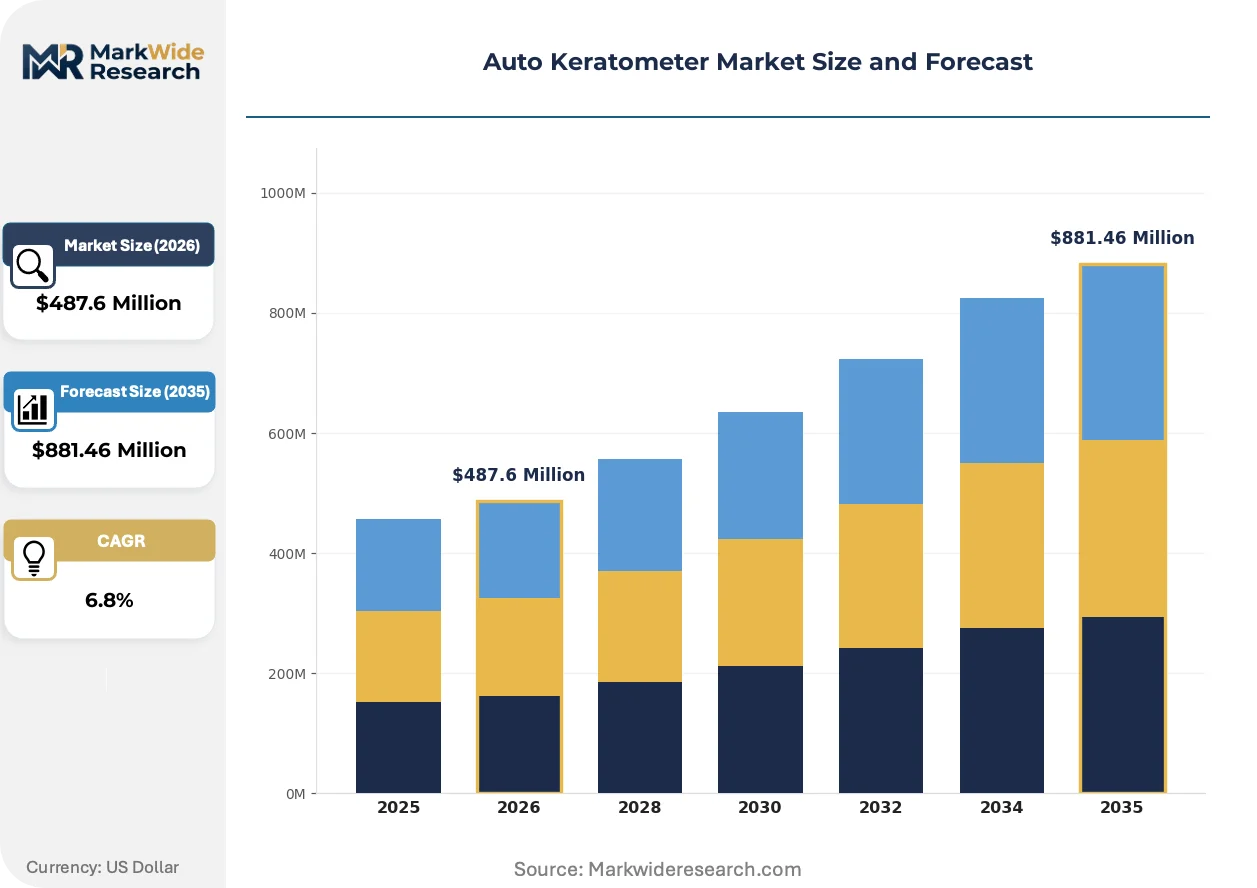
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Keratometers, Digital Keratometers, Automatic Keratometers, Advanced Imaging Systems Application: Vision Correction, Ophthalmic Diagnostics, Research Purposes, Contact Lens Fitting End User: Hospitals, Eye Clinics, Research Laboratories, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Medical Supply Stores |
| Companies Covered | Nidek Co., Ltd., Topcon Corporation, TOMEY CORPORATION, GRAND SEIKO, Carl Zeiss Meditech AG, Potec, BON Optic, Righton, Luneau Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Keratometer Market Emerging Trajectories
Scheimpflug tomography is converging with artificial intelligence-driven curvature analysis, reshaping how ophthalmic diagnostics compress examination time while expanding measurable optical zones.
Placido disk reflection technology is converging with machine learning pattern recognition algorithms. High-volume cataract surgery centers in the United States adopt these systems to reduce per-patient examination time. The convergence is compressing technician training requirements while expanding addressable clinic throughput.
The EU Medical Device Regulation now mandates clinical evidence summaries for Class IIa ophthalmic diagnostics. Manufacturers must submit post-market surveillance data that extends registration timelines by eight to fourteen months. Integrated diagnostic workstation vendors absorb these costs most readily, consolidating competitive position against standalone keratometer specialists.
After-sales service unbundling is disrupting traditional equipment procurement in German university hospital networks. Leasing arrangements with per-procedure analytics fees replace capital purchase models. This shift concentrates vendor selection power among procurement consortia managing multi-site ophthalmology departments.
Auto Keratometer Market Segmentation
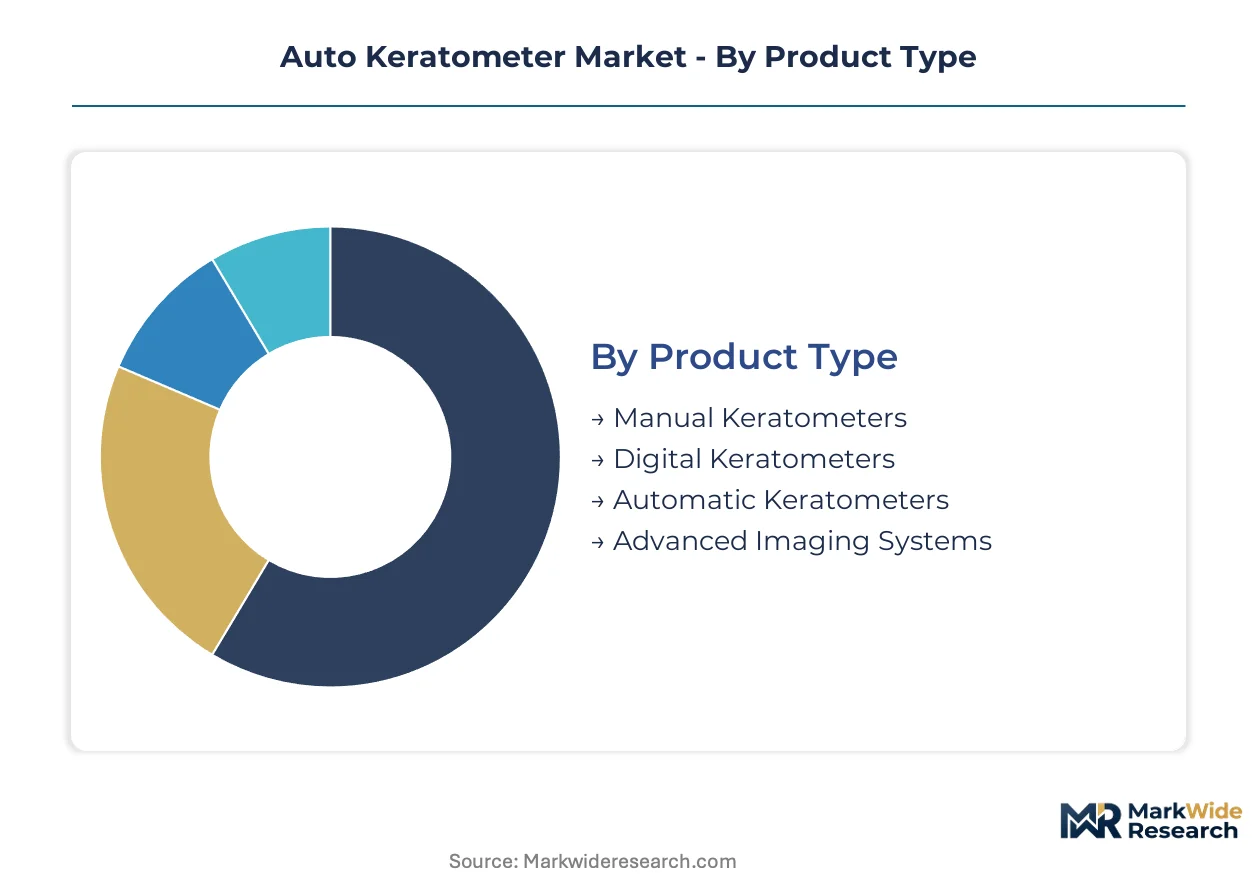
Auto keratometer segmentation reveals how hardware sophistication, clinical workflow integration, and procurement channel economics fragment addressable demand. Manufacturers calibrate portfolio depth across these dimensions to capture replacement cycles versus greenfield expansion.
Product Type:
Standardization dominates at the base of this spectrum, while premium tiers compete on software-integrated diagnostic depth and optical precision.
- Manual Keratometers:Mechanical mire-ring systems requiring operator interpretation of reflected Placido disk images. Demand concentrates in emerging-market training hospitals and resource-constrained settings where capital budgets exclude electronic systems. Price sensitivity and technician training burdens constrain upgrade velocity.
- Digital Keratometers:Electronic capture with onboard display and basic data storage, bridging manual technique and full automation. Eye clinics in Germany and Japan deploy these units for high-volume screening workflows where technician throughput limits capacity. These systems capture the largest unit shipment volumes across the forecast window.
- Automatic Keratometers:Motorized alignment with automated curvature calculation and print output. Research laboratories in the United States specify these instruments for reproducible longitudinal studies requiring minimal operator variance.
- Advanced Imaging Systems:Scheimpflug tomography or combined Placido-Scheimpflug platforms with cloud connectivity and AI-assisted curvature mapping. Subscription-based analytics separate hardware margins from service lifetime value.
Most installed capacity flows through Digital Keratometers. Expansion is steepest in Advanced Imaging Systems.
Application:
Clinical utility intensity varies sharply across this dimension, from elective vision correction to mandatory preoperative measurement.
- Vision Correction:Preoperative assessment for LASIK, PRK, and phakic intraocular lens candidacy. United States refractive surgery centers drive demand for wavefront-integrated keratometry that maps higher-order aberrations beyond sphere and cylinder.
- Ophthalmic Diagnostics:Disease monitoring for keratoconus, post-graft astigmatism, and corneal ectasia progression. German university hospitals anchor procurement volume for multi-modal diagnostic workstations bundling keratometry with anterior segment OCT.
- Research Purposes:Longitudinal corneal biomechanics studies and pharmaceutical trial endpoints. Contract research organizations specify calibrated instruments with traceable metrology certificates.
- Contact Lens Fitting:Scleral, orthokeratology, and specialty lens protocols requiring precise eccentricity and sagittal height mapping. This application climbs the fastest as specialty lens protocols displace conventional soft lens fitting in Japan and the United States.
Diagnostic workflows absorb the largest hardware footprint. Contact Lens Fitting gains share fastest as specialty protocols proliferate.
End User:
Procurement authority and replacement cadence diverge between institutional capital budgets and distributed clinical practice purchasing.
- Hospitals:Integrated health systems with centralized biomedical engineering and EHR interoperability requirements. United States hospital networks prioritize FDA 510(k)-cleared devices with HL7 connectivity.
- Eye Clinics:Independent optometry and ophthalmology practices with fragmented purchasing authority. German clinic consortia are consolidating vendor selection power through multi-site leasing arrangements.
- Research Laboratories:Academic medical centers and contract research organizations demanding calibrated precision and audit trails. ISO 17025 metrology compliance filters supplier eligibility.
- Educational Institutions:Optometry schools and technician training programs sourcing durable training instruments with replaceable components. Price elasticity exceeds clinical settings by substantial margins.
Eye Clinics represent the broadest addressable base. Research Laboratories command the highest per-unit specification intensity.
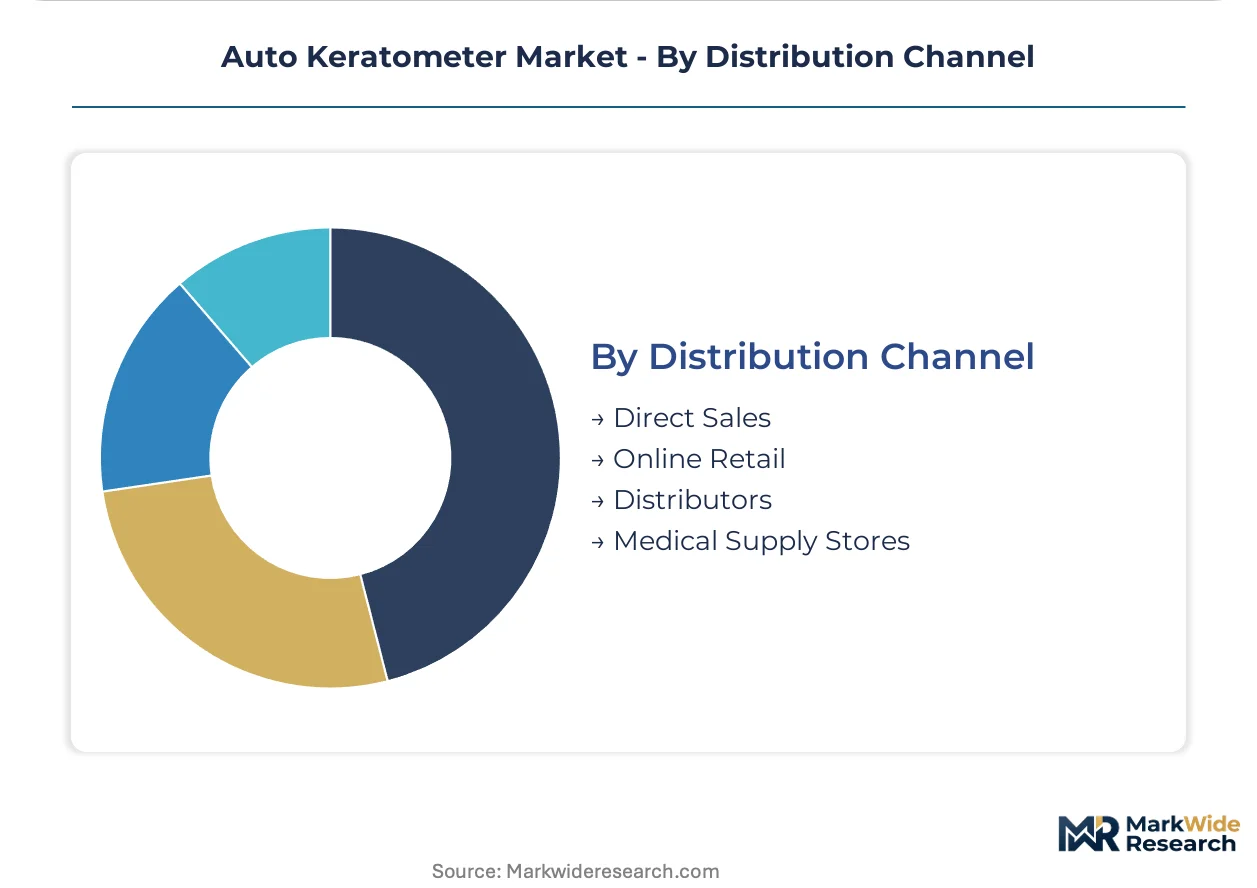
Distribution Channel:
Channel selection reflects capital intensity, geographic density of clinical demand, and aftermarket service requirements.
- Direct Sales:Manufacturer field representatives managing enterprise accounts and integrated workstation deployments. Carl Zeiss Meditech AG and Nidek Co., Ltd. maintain direct presence in Japan, Germany, and the United States for high-value system sales.
- Online Retail:E-commerce platforms serving small-practice and educational buyers with standardized portable units. Regulatory compliance documentation burdens limit this channel to lower-risk device classifications.
- Distributors:Regional medical device specialists providing local installation, training, and service coverage. PMDA-mandated QMS conformity audits in Japan filter distributor eligibility to established players with Japanese regulatory infrastructure.
- Medical Supply Stores:Brick-and-mortar procurement for emergency replacement and consumable accessories. This channel captures minimal system revenue but sustains aftermarket part availability.
Distributors handle the largest transaction volume. Direct Sales concentrates the highest-value integrated workstation placements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital networks anchor procurement volume for integrated diagnostic workstations, while aging demographics across Japan and the United States sustain replacement demand for high-precision curvature mapping instruments.
United States
Cataract surgery volumes and refractive surgery center expansion drive instrument replacement cycles. FDA 510(k) clearance pathways compress commercialization timelines for Placido disk and Scheimpflug-based systems. High-volume surgery centers in California and Texas adopt machine learning-enhanced keratometry to reduce per-patient examination time.
Germany
Multi-site ophthalmology departments consolidate vendor selection power through leasing arrangements with per-procedure analytics fees. EU MDR Class IIa requirements mandate clinical evidence summaries that extend registration timelines. University hospital networks in Bavaria and North Rhine-Westphalia anchor demand for multi-modal diagnostic workstations bundling keratometry with anterior segment OCT.
Japan
Specialty contact lens protocols for orthokeratology and scleral lenses require precise eccentricity mapping that manual systems cannot deliver. PMDA enforces QMS conformity audits for imported ophthalmic devices, filtering out smaller manufacturers lacking Japanese regulatory infrastructure. Tokyo and Osaka metropolitan clusters concentrate procurement for automated corneal topography systems.
United Kingdom
Independent optometry practices with fragmented purchasing authority drive demand for cost-efficient portable units. MHRA post-Brexit regulatory alignment with EU MDR frameworks shapes device registration pathways. London and Southeast England eye clinic networks expand adoption of polymer-housed portable keratometers for point-of-care deployment.
India
Emerging-market training hospitals source manual and digital keratometers where capital budgets exclude full automation. CDSCO medical device registration requirements for Class B and C ophthalmic diagnostics filter supplier eligibility. Maharashtra and Karnataka state medical colleges concentrate demand for durable training instruments with replaceable components.
Auto Keratometer Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and integrated diagnostic workstation portfolios. The vendor base stratifies into three tiers: premium-tier integrated workstation specialists, mid-tier standalone automated system manufacturers, and economy-tier portable unit assemblers. Dominant competitive moves include strategic partnerships for EHR interoperability software and geographic expansion through distributor networks with local QMS conformity capabilities.
Among Japanese ophthalmic device manufacturers, Nidek Co., Ltd., Topcon Corporation, and TOMEY CORPORATION exemplify the premium-tier archetype with in-house optical component capabilities. These entities occupy positions where lens grinding expertise and integrated diagnostic depth separate hardware margins from recurring software revenue. Carl Zeiss Meditech AG anchors the German precision optics tradition within the integrated workstation segment. The competitive dynamic situates polymer-housing portable specialists against metal-construction legacy incumbents as cost efficiency pressures reshape point-of-care deployment economics.
| Leading Market Players |
|---|
| Nidek Co., Ltd. |
| Topcon Corporation |
| TOMEY CORPORATION |
| GRAND SEIKO |
| Carl Zeiss Meditech AG |
| Potec |
| BON Optic |
| Righton |
| Luneau Technology Group |
| Others |
Supply Flow & Price Mechanics
Captive lens grinding capabilities at Nidek Co., Ltd. and Carl Zeiss Meditech AG anchor both supply security and premium pricing power, insulating these manufacturers from optical-grade polymer volatility while compressing margin headroom for polymer-dependent portable assemblers.
Pricing Analysis
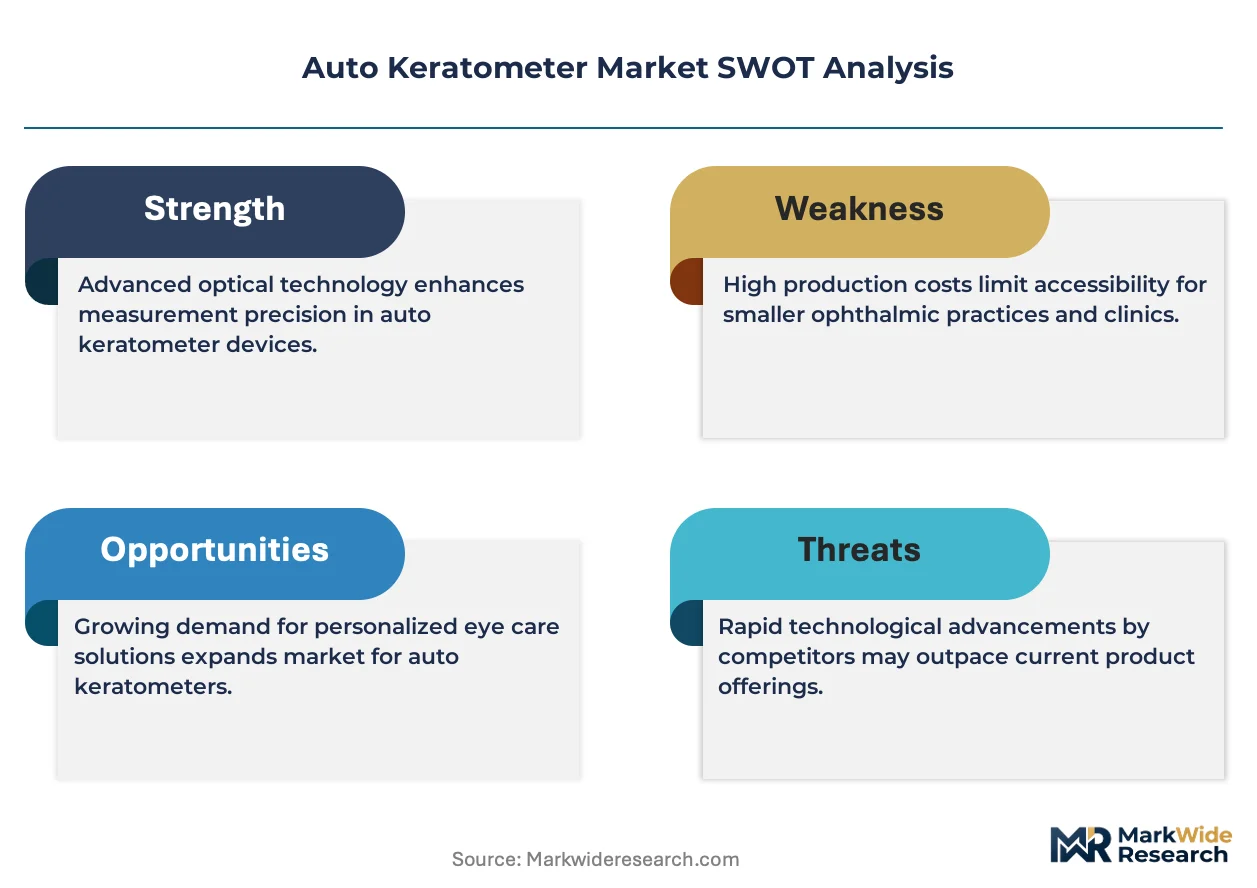
Optical-grade polymer feedstock pass-through dominates cost structures for portable unit manufacturers, while in-house optical component production insulates integrated workstation vendors. Three-tier pricing structure across premium, standard, and economy levels separates Scheimpflug-AI platforms from digital keratometers and manual training instruments. Pricing pressure stems from wavefront aberrometry bundling that compresses standalone keratometer demand. Eye clinics in Germany and Japan show lowest price sensitivity for diagnostic workstations, while Indian training hospitals drive economy-tier volume.
Supply Chain Analysis
Reverse-logistics flows for refurbished Scheimpflug systems concentrate in Germany and Japan, where university hospitals and metropolitan eye clinic networks sustain secondary equipment markets. Optical-grade polymer housings draw from petrochemical feedstocks in the United States and Germany, while precision lens grinding equipment sources from Japan. Single-source vulnerability sits with Japanese regulatory infrastructure for PMDA QMS conformity audits. Distribution runs through regional medical device specialists providing local installation and service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between Japan's stringent PMDA compliance costs and India's CDSCO registration pathways, where differential regulatory burden creates 12-18 month timeline advantages for portable unit entrants.
For Market Incumbents: Deepen in-house lens grinding capabilities to defend against polymer-housing portable specialists eroding mid-tier share. Expand direct sales presence in German university hospital networks before multi-site leasing consortia consolidate vendor selection power. Prioritize FDA 510(k) cybersecurity validation for cloud-connected platforms ahead of potential software-as-a-medical-device reclassification. For New Entrants and Emerging Players: Capture the Indian training hospital segment where CDSCO Class B registration filters out capital-constrained competitors lacking durable instrument portfolios. Target Maharashtra and Karnataka state medical colleges with replaceable-component digital keratometers. Pursue distributor partnerships with established Japanese regulatory infrastructure to bypass PMDA QMS audit barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier standalone automated system manufacturers because EU MDR clinical evidence mandates are extending registration timelines beyond smaller players' capital endurance. Five-to-ten year viability hinges on software-recurring revenue separation from hardware margins. Monitor FDA software-as-a-medical-device classification guidance for cloud-connected keratometers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Premarket notification for cloud-connected platforms anticipates software-as-a-medical-device reclassification by FDA. |
| EU MDR Clinical Evidence Pathway | Post-market surveillance data submission extends CE marking timelines for Class IIa ophthalmic diagnostics. |
| Hospital System Partnership | Multi-site leasing arrangements with per-procedure analytics fees consolidate vendor selection power in Germany. |
| Software Companion Development | AI-assisted curvature mapping subscriptions separate hardware margins from service lifetime value. |
| Reimbursement Strategy | Cataract surgery volume-linked instrument replacement cycles anchor demand in United States hospital networks. |
Methodological Framework
Direct dialogue with ophthalmology department heads, biomedical engineering directors, GPO contracts managers, and optical device procurement leads grounded qualitative insights, cross-referenced against FDA 510(k) filings, PMDA approval databases, EU MDR notified body records, and hospital capital expenditure disclosures. Bottom-up and top-down triangulation validated segment-level estimates.
Bottom-up modeling calibrated unit shipment trajectories by product type, application intensity, and end-user procurement authority across the analysis window, while top-down approaches tested aggregate market boundaries against refractive surgery volume correlations and cataract procedure replacement cycles. CAGRs derived from logistic adoption curves for Scheimpflug-AI platforms and linear replacement patterns for digital keratometers.
Regulatory timeline delays, polymer feedstock volatility, and wavefront aberrometry substitution acceleration are the dominant revision risks to installed base and revenue forecasts. Practitioners should monitor FDA software classification guidance, EU MDR notified body capacity constraints, and Japanese specialty contact lens protocol expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Auto-Injectors Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Capnography Devices Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Global Vaginal Speculum Market