
 MRI-Compatible IV Infusion Pump Systems Market | 2026-2036
MRI-Compatible IV Infusion Pump Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MRI-Compatible IV Infusion Pump Systems Market Foresight
The capital-intensity divergence between MRI-compatible pump specialists and diversified infusion device manufacturers is bifurcating competitive dynamics in this market. Iradimed Corporation leverages its dedicated non-magnetic motor technology to dominate the high-acuity radiology segment. B. Braun Melsungen AG sustains broad hospital system relationships that anchor its cross-selling of MRI-conditional pump configurations. Fresenius Kabi AG competes through integrated medication delivery ecosystems that extend from standard care into specialized imaging environments.
MRI-compatible IV infusion pump systems are electromechanical drug delivery devices engineered with non-ferrous materials, shielded circuitry, and filtered power supplies to operate within static magnetic fields exceeding 1.5 Tesla without image artifact generation or projectile risk. These systems enable continuous therapeutic administration during diagnostic or interventional MRI procedures, eliminating the clinical compromise of interrupting sedation, anesthesia, or chemotherapy for patient transport. Smart Pumps lead product type revenue due to dose-error reduction software and EMR interoperability commanding premium placement in academic medical centers. Wireless technology represents the fastest-expanding segment as hospitals prioritize remote monitoring and pump fleet integration with radiology information systems.
FDA 510(k) clearance pathways for electromagnetic compatibility, IEC 60601-1-2 Edition 4.1 electromagnetic disturbance standards, and MDR CE marking requirements in Europe collectively elevate engineering barriers and extend product development timelines for new entrants. These frameworks shape demand by limiting approved vendor pools to manufacturers with demonstrated magnetic field resilience documentation. Stakeholders must monitor evolving MRI field strength migration toward 7 Tesla clinical installations and assess whether existing pump shielding architectures accommodate next-generation scanner deployments without hardware redesign.
Market Dynamics
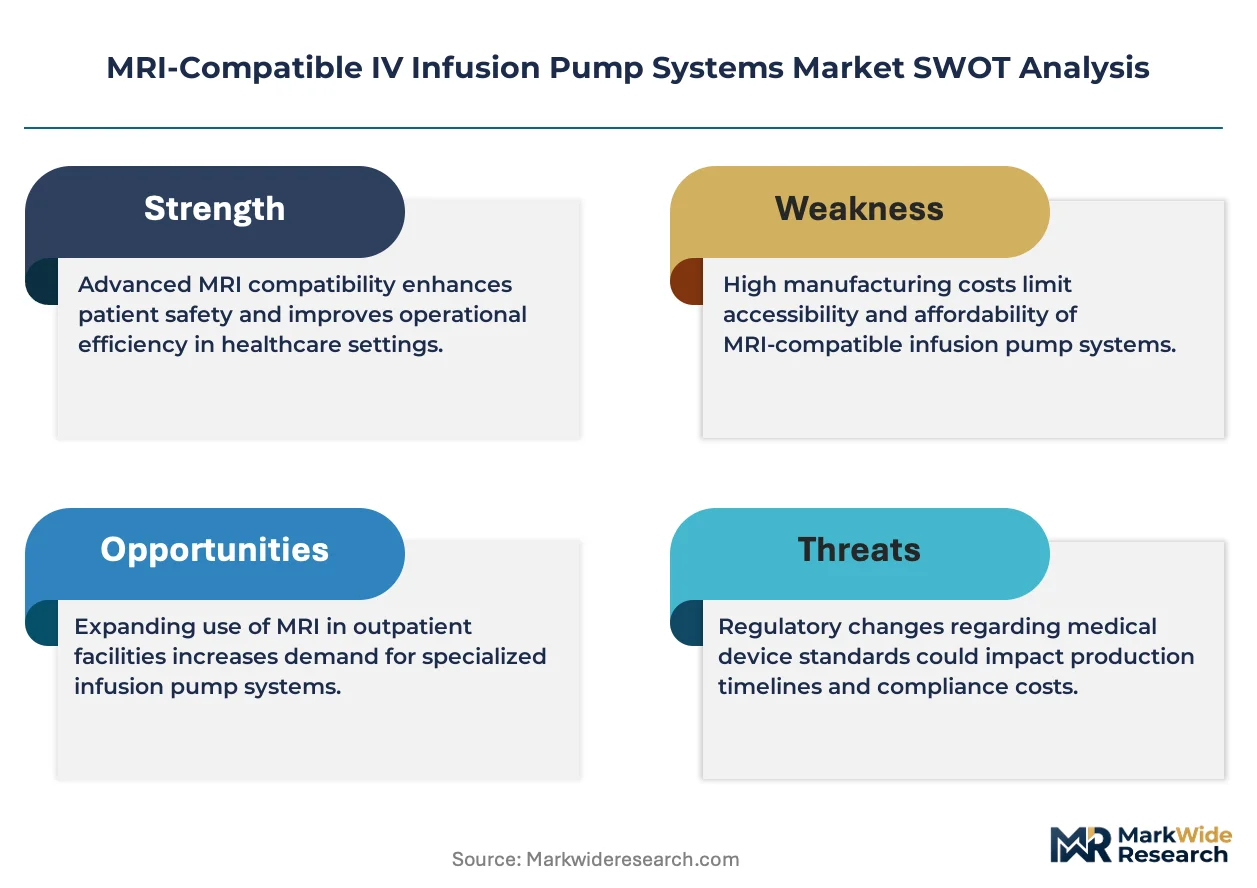
Migration toward 7 Tesla clinical MRI installations is bifurcating pump shielding requirements, forcing manufacturers to choose between incremental field-strength adaptation and fundamental electromagnetic architecture redesign.
Growth Catalysts
- Image-Guided Therapy Reimbursement:Medicare coverage expansion for intra-MRI interventions in the United States is accelerating hospital capital allocation toward compatible infusion infrastructure.
- FDA Electromagnetic Compatibility Pathways:Streamlined 510(k) review timelines for devices demonstrating IEC 60601-1-2 Edition 4.1 compliance are reducing time-to-market for qualified manufacturers.
- Non-Ferrous Motor Advancement:Ceramic and polymer-composite motor technologies are eliminating magnetic field distortion risks that previously constrained pump placement proximity.
Market Restraints
- Specialized Component Sourcing:Neodymium-free magnetic alloys and mu-metal shielding fabrics concentrate supply among Japanese and German specialty metallurgy suppliers.
- Certification Cost Structure:FDA electromagnetic compatibility testing and MDR CE marking technical documentation requirements impose six-figure validation expenses per product variant.
- Scanner Compatibility Fragmentation:Proprietary RF pulse sequences across Siemens Healthineers, GE HealthCare, and Philips MRI platforms necessitate pump-specific electromagnetic validation.
Strategic Opportunities
- Pediatric Oncology Centers:Underpenetrated demand for sedation-maintained chemotherapy delivery during diagnostic imaging creates white space in academic children's hospitals.
- Wireless Pump Fleet Integration:Convergence of Bluetooth Low Energy protocols with radiology information systems enables real-time dose tracking without tethered connections.
- India Diagnostic Imaging Expansion:CDSCO streamlined medical device registration pathways and hospital infrastructure investments in Maharashtra and Karnataka open procurement channels.
Industry Challenges
- Electromagnetic Engineering Talent Scarcity:Cross-functional expertise spanning high-field physics, infusion therapy, and embedded systems engineering concentrates among a limited specialist pool.
- Legacy Scanner Integration Complexity:Retrofitting MRI-compatible pumps into installed 1.5 Tesla systems with outdated RF shielding requires site-specific electromagnetic remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI-Compatible IV Infusion Pump Systems Market |
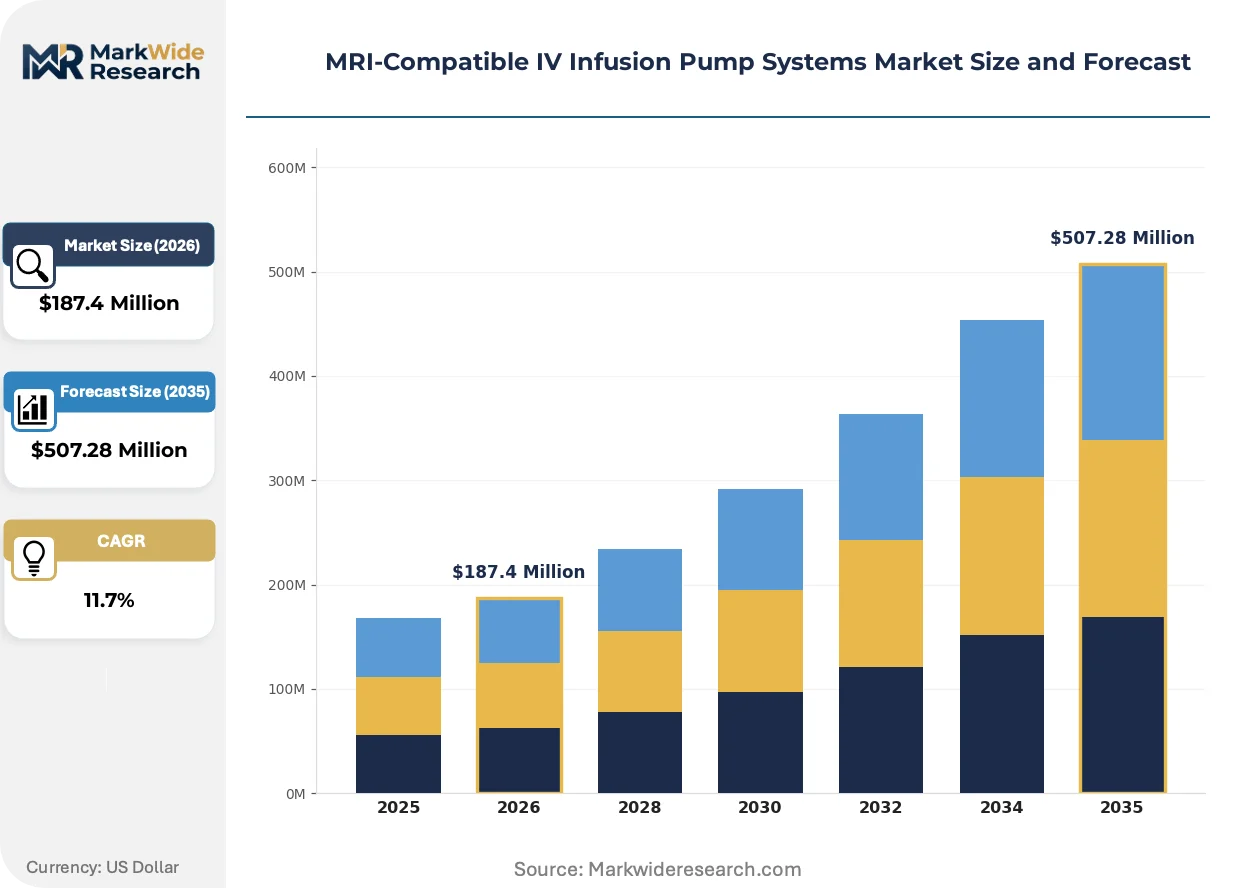
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pumps, Manual Pumps, Portable Pumps, Prefilled Pumps End User: Hospitals, Outpatient Clinics, Emergency Departments, Home Healthcare Technology: Electromechanical, Wireless, Magnetic, Infusion Management Software Application: Chemotherapy, Pain Management, Anesthesia, Nutritional Support |
| Companies Covered | Iradimed Corporation, B. Braun Melsungen AG, Fresenius Kabi AG, Baxter International Inc., Becton Dickinson and Company, Smiths Medical, Arcomed AG, Medtronic plc, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI-Compatible IV Infusion Pump Systems Market Shifts & Advancements
Three interconnected developments are compressing product lifecycles and redrawing competitive boundaries in MRI-compatible infusion technology.
Shielded power supply architectures are bifurcating the installed base between hospitals demanding 7 Tesla readiness and those optimizing for 1.5-3 Tesla operational cost. Academic medical centers in Germany and Japan are prioritizing field-strength headroom for research applications, while community hospitals in the United States defer capital replacement. This technology divergence is compressing mid-tier pump margins as buyers polarize between premium field-agnostic systems and legacy-compatible economy configurations.
MDR CE marking requirements in Europe are extending technical documentation obligations and post-market surveillance intensity for electromagnetic disturbance compliance. Manufacturers must now maintain clinical evidence portfolios across multiple MRI field strengths rather than single-point validation. The regulatory burden falls most heavily on mid-cap device specialists lacking diversified compliance infrastructure, advantaging conglomerates with pan-European regulatory affairs capabilities.
Hospital pharmacy departments are consolidating pump procurement authority away from decentralized radiology purchasing, centralizing fleet standardization decisions. This shift compresses vendor switching cycles and elevates total-cost-of-ownership analytics over unit price. The pattern is most visible in United States integrated delivery networks and German hospital federations, where formulary alignment across imaging and infusion therapy departments is becoming a contractual prerequisite.
MRI-Compatible IV Infusion Pump Systems Market Segmentation
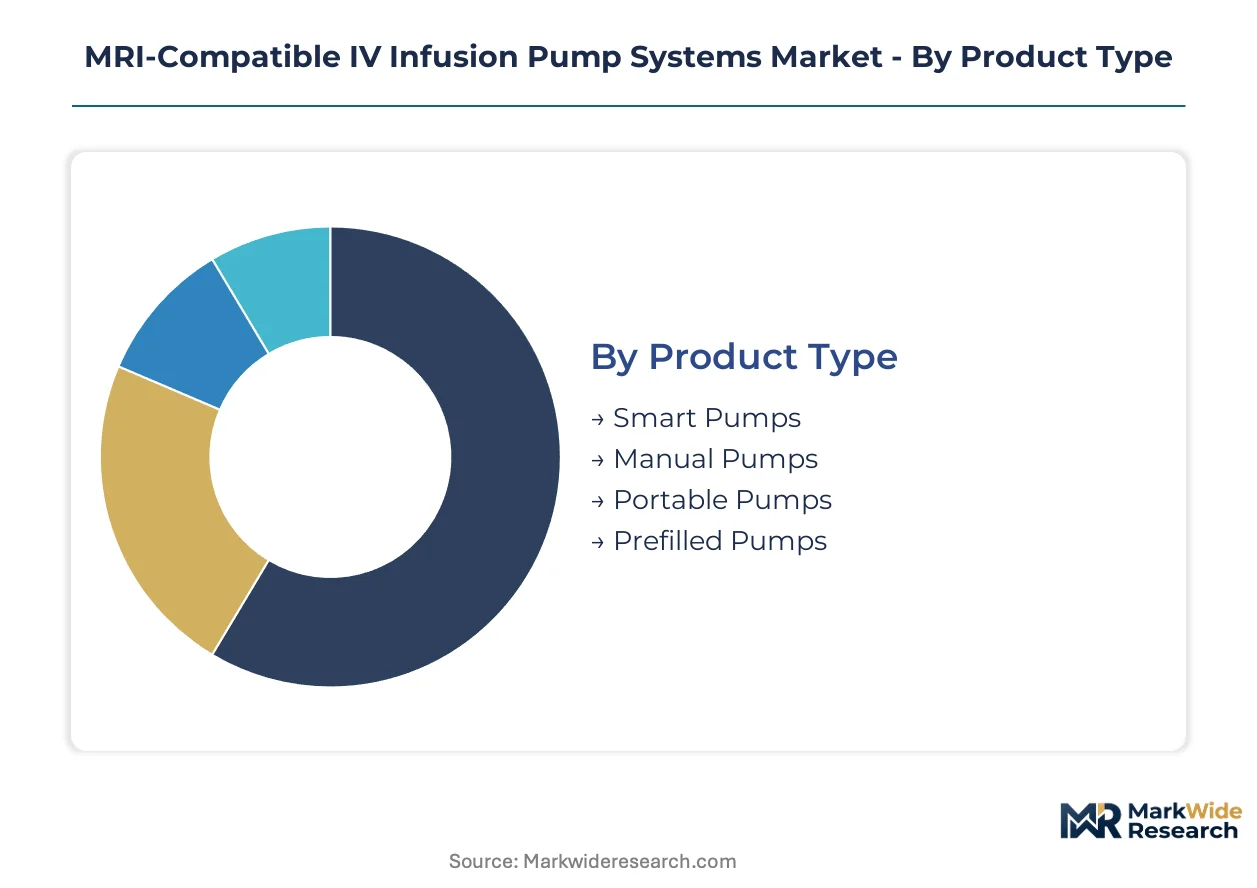
MRI-compatible IV infusion pump systems segment across four critical dimensions that determine electromagnetic shielding requirements, regulatory pathways, and procurement authority. Each category reflects distinct engineering constraints and clinical use cases that shape vendor positioning and hospital capital allocation decisions.
Product Type:
FDA electromagnetic compatibility testing requirements and IEC 60601-1-2 Edition 4.1 standards create divergent certification burdens across pump architectures, concentrating procurement among configurations with demonstrated field resilience documentation.
- Smart Pumps:Electromechanical drug delivery systems integrate dose-error reduction software and EMR interoperability with shielded non-ferrous motor housings. Demand concentrates in academic medical centers across the United States and Germany where EMR integration commands premium placement and radiology-pharmacy formulary alignment is tightening.
- Portable Pumps:Battery-operated configurations with filtered DC power supplies enable patient transport between imaging suites without interruption of therapeutic delivery. Adoption is climbing fastest in Japanese emergency departments and United States outpatient clinics where workflow flexibility outweighs stationary precision requirements.
- Manual Pumps:Spring-driven or elastomeric balloon mechanisms eliminate electromagnetic compatibility concerns entirely through passive operation. These devices serve as backup systems in legacy 1.5 Tesla installations with outdated RF shielding across community hospitals in Germany.
- Prefilled Pumps:Single-use disposable units with preloaded medication chambers reduce pharmacy compounding labor and contamination risk. These systems penetrate pediatric oncology centers in the United States where sedation-maintained chemotherapy protocols demand rapid deployment.
Established volume favors Smart Pumps; emerging adoption favors Portable Pumps.
End User:
Procurement authority is migrating from decentralized radiology departments toward centralized hospital pharmacy and supply chain functions, reshaping vendor relationship dynamics and fleet standardization requirements.
- Hospitals:Integrated delivery networks and hospital federations dominate capital allocation for MRI-compatible infusion infrastructure. Radiology departments in the United States, Germany, and Japan anchor installed base concentration where 7 Tesla migration is bifurcating shielding requirements between research and community settings.
- Outpatient Clinics:Freestanding imaging centers and ambulatory surgery facilities prioritize cost-optimized 1.5 Tesla compatibility over field-strength headroom. German outpatient radiology chains and United States ambulatory surgery centers are expanding procurement as Medicare reimbursement for image-guided therapy broadens.
- Emergency Departments:Trauma and stroke protocols requiring immediate MRI access without patient transport drive demand for portable electromagnetic-compatible systems. Japanese tertiary emergency centers lead adoption where time-critical intervention protocols integrate real-time imaging.
- Home Healthcare:Post-acute and palliative care settings utilize simplified MRI-conditional pumps for patients requiring ongoing sedation or pain management during outpatient imaging. This segment remains underpenetrated due to reimbursement complexity and caregiver training requirements in the United States.
Capital concentration sits with Hospitals; reimbursement expansion unlocks Outpatient Clinics.
Technology:
Component sourcing constraints and engineering talent scarcity are forcing technology architecture choices that balance electromagnetic resilience against supply chain vulnerability.
- Wireless:Bluetooth Low Energy protocols enable remote pump monitoring and dose tracking without tethered connections to radiology information systems. This architecture is expanding most quickly in United States academic medical centers prioritizing fleet integration and real-time data capture.
- Electromechanical:Conventional motor-driven systems with shielded power supplies and filtered circuitry represent the installed base majority. Ceramic and polymer-composite motor technologies from Japanese and German specialty suppliers are displacing legacy ferrous components.
- Magnetic:Pump mechanisms utilizing magnetic levitation or non-contact drive systems eliminate mechanical wear and friction in high-field environments. These systems remain niche due to neodymium-free magnetic alloy sourcing concentration.
- Infusion Management Software:Dose calculation algorithms, drug library databases, and interoperability middleware operate independently of pump hardware. Pharmacy information system vendors in Germany and the United States are extending into this layer to capture recurring revenue.
Installed base dominance belongs to Electromechanical; connectivity investment flows to Wireless.
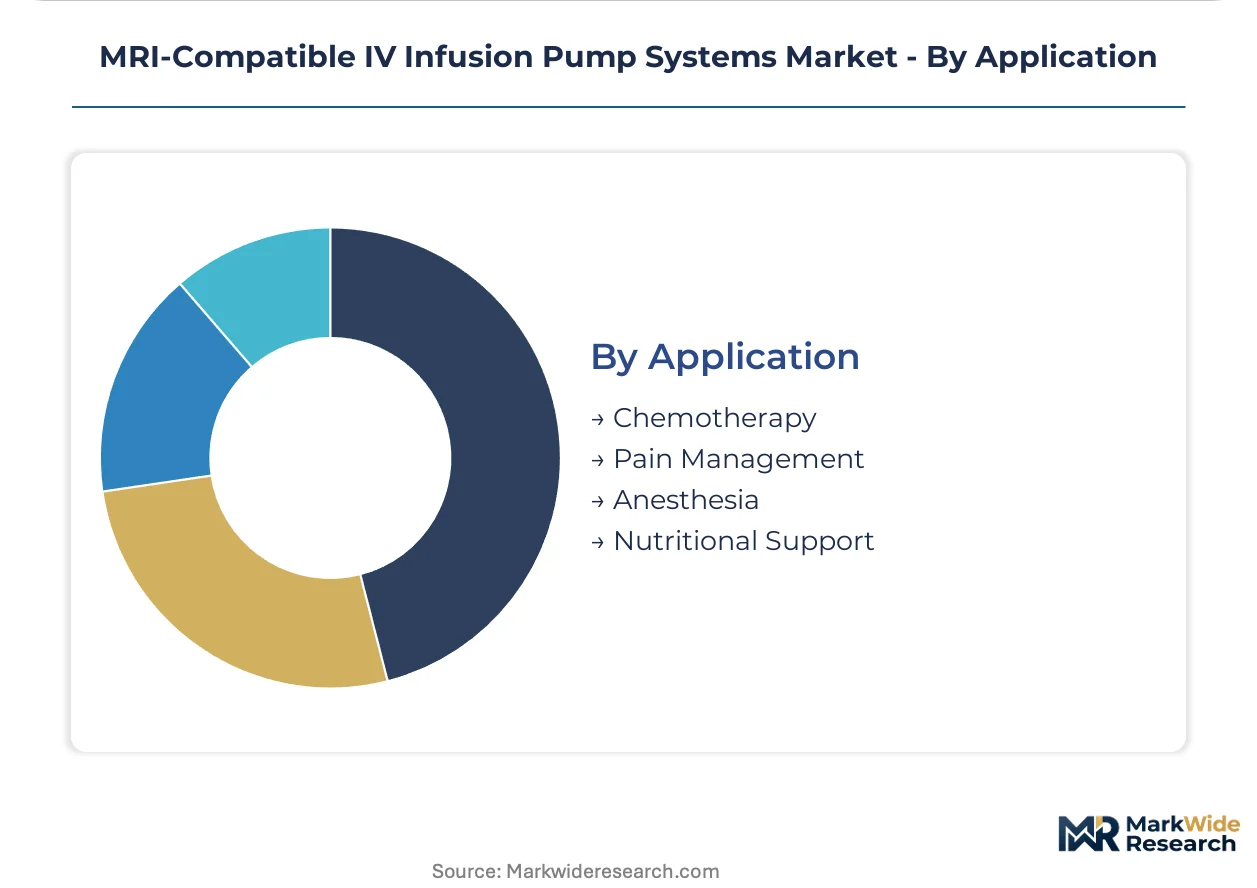
Application:
Clinical protocol requirements determine pump placement proximity to magnet bore, driving electromagnetic shielding specifications and motor technology selection.
- Chemotherapy:Continuous cytotoxic drug delivery during diagnostic imaging maintains therapeutic plasma levels without sedation interruption. Pediatric oncology centers in the United States and academic hospitals in Germany are prioritizing MRI-compatible protocols for central nervous system tumor surveillance.
- Anesthesia:Propofol and sedative infusion during functional MRI and interventional procedures demands precise flow control and immediate titration capability. Japanese anesthesia departments lead adoption of 7 Tesla-ready systems for research applications.
- Pain Management:Opioid and local anesthetic delivery for chronic pain patients undergoing spinal and joint imaging requires moderate-precision pumps with broad scanner compatibility. United States pain clinics drive volume in this segment.
- Nutritional Support:Enteral and parenteral nutrition during prolonged imaging sessions serves immobilized and sedated patients. This application remains secondary due to lower acuity and alternative feeding schedule flexibility.
Protocol complexity elevates Chemotherapy; reimbursement density supports Anesthesia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in MRI-compatible infusion systems tilt toward net imports in emerging diagnostic markets while Germany, Japan, and the United States retain manufacturing surpluses in non-ferrous motor components and shielded power supply assemblies.
United States
Medicare coverage expansion for intra-MRI interventions accelerates hospital capital allocation toward compatible infusion infrastructure. FDA electromagnetic compatibility testing requirements under 510(k) pathways shape vendor qualification pools. Academic medical centers in Boston and Rochester prioritize 7 Tesla-ready pump procurement for research applications.
Germany
Hospital federations centralize pump procurement authority across imaging and infusion therapy departments, elevating total-cost-of-ownership analytics. MDR CE marking requirements extend technical documentation obligations for electromagnetic disturbance compliance. Industrial clusters in Baden-Württemberg and Bavaria concentrate specialty metallurgy suppliers for neodymium-free magnetic alloys.
Japan
Tertiary emergency centers integrate MRI-compatible pumps into time-critical stroke and trauma protocols requiring immediate imaging access. METI standards for medical device electromagnetic compatibility align with IEC 60601-1-2 Edition 4.1 frameworks. Ceramic and polymer-composite motor technology development concentrates in Nagoya and Osaka manufacturing corridors.
India
CDSCO streamlined medical device registration pathways open procurement channels as hospital infrastructure investments expand in Maharashtra and Karnataka. Diagnostic imaging capacity additions in Mumbai and Bengaluru drive first-time compatible pump installations. Import dependency for shielded power supply components persists due to limited domestic specialty electronics fabrication.
United Kingdom
NHS procurement frameworks emphasize fleet standardization across radiology and pharmacy departments, compressing vendor switching cycles. MHRA alignment with MDR technical documentation requirements extends post-market surveillance obligations. London and Manchester academic medical centers anchor demand concentration for smart pump configurations with EMR interoperability.
MRI-Compatible IV Infusion Pump Systems Market Competitive Landscape
Concentration sits with diversified infusion device conglomerates possessing pan-regional regulatory affairs infrastructure and established hospital system relationships. The vendor base spans three tiers: dedicated MRI-compatible pump specialists with proprietary non-magnetic motor architectures, diversified medical technology conglomerates leveraging cross-selling across standard and conditional pump configurations, and regional device assemblers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships for electromagnetic compatibility testing validation and portfolio diversification into wireless connectivity modules for radiology information system integration.
Among dedicated specialists, Iradimed Corporation exemplifies the focused non-magnetic motor technology archetype, while B. Braun Melsungen AG and Fresenius Kabi AG occupy positions within the diversified conglomerate tier, leveraging broad hospital system relationships and integrated medication delivery ecosystems respectively. These three anchors represent the competitive spectrum from pure-play electromagnetic engineering to cross-platform infusion therapy coverage.
| Leading Market Players |
|---|
| Iradimed Corporation |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| Baxter International Inc. |
| Becton Dickinson and Company |
| Smiths Medical |
| Arcomed AG |
| Medtronic plc |
| ICU Medical |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with Japanese and German specialty metallurgy suppliers lock in neodymium-free magnetic alloy access while fixing component costs against raw material volatility. These arrangements bind MRI-compatible pump manufacturers to predictable pricing corridors for shielded power supply assemblies, even as FDA electromagnetic compatibility testing fees escalate.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Academic medical centers in the United States and Germany absorb premium tier positioning for 7 Tesla-ready systems with EMR interoperability, while community hospitals in India and outpatient clinics in the United Kingdom prioritize economy configurations with 1.5 Tesla compatibility. Cost compression in the mid-tier segment is intensifying because MDR CE marking documentation obligations and FDA 510(k) pathway fees concentrate compliance investment among diversified conglomerates. Price differentiation hinges on electromagnetic field resilience certification grade and wireless fleet integration capability, with pharmacy-led procurement committees exhibiting highest price sensitivity versus radiology departments prioritizing performance headroom.
Supply Chain Analysis
Japan and Germany anchor specialty component manufacturing for ceramic and polymer-composite motor technologies and mu-metal shielding fabrics. China and South Korea feed printed circuit board assemblies and filtered power supply electronics into final pump assembly. The supply chain draws from concentrated neodymium-free magnetic alloy sourcing that creates single-source vulnerability when geopolitical trade restrictions disrupt metallurgy flows. Distribution runs through hospital GPO contracts in the United States, hospital federation frameworks in Germany, and tertiary procurement centers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from wireless infusion management software platforms that decouple monitoring functionality from hardware sales, threatening recurring revenue capture.
For Market Incumbents: Shield proprietary non-magnetic motor architectures through patent thickets in ceramic and polymer-composite drive technologies. Deepen backward integration into shielded power supply component fabrication to reduce Japanese and German supplier dependency. Priority investment targets IEC 60601-1-2 Edition 4.1 pre-certification for 7 Tesla field strength headroom before academic medical center replacement cycles accelerate. For New Entrants and Emerging Players: Differentiate on pediatric oncology center specialization where sedation-maintained chemotherapy protocols during diagnostic imaging remain underpenetrated. Target Maharashtra and Karnataka hospital infrastructure investments in India where CDSCO streamlined registration pathways reduce time-to-first-sale. Lead with portable pump configurations emphasizing battery-operated workflow flexibility over stationary precision for emergency department stroke and trauma protocols. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap electromagnetic engineering specialists possessing demonstrated FDA 510(k) clearance portfolios and IEC 60601-1-2 compliance documentation. Long-term viability in this market rests on regulatory moat durability rather than manufacturing scale. Watch for inflection signals in 7 Tesla clinical installation announcements from Siemens Healthineers, GE HealthCare, and Philips platforms that would trigger pump shielding architecture replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Electromagnetic Compatibility Submission | Accelerates market access for 7 Tesla-ready pump configurations in United States academic medical centers. |
| MDR CE Marking Pathway Investment | Extends addressable market coverage across German hospital federations and NHS procurement frameworks. |
| Hospital System Partnership | Locks in fleet standardization decisions as pharmacy departments consolidate pump procurement authority. |
| Wireless Connectivity Module Development | Enables Bluetooth Low Energy integration with radiology information systems for real-time dose tracking. |
| Reimbursement Strategy Alignment | Captures Medicare coverage expansion for intra-MRI interventions driving capital allocation. |
Research Methodology
The analysis maps smart pump, portable pump, manual pump, and prefilled pump sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. Primary intelligence combined with secondary validation from FDA 510(k) filings, IEC 60601-1-2 certification databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Consistency checks validated volume and value outputs against external benchmarks including installed MRI base expansion rates and electromagnetic compatibility certification timelines. The analytical framework models pump placement proximity to magnet bore, shielding architecture specifications, and motor technology selection throughout the projection horizon. CAGRs derived from segmented adoption curves weighted by reimbursement density and regulatory pathway completion rates, with specific inputs from ceramic motor technology maturation and wireless protocol standardization trajectories.
Material uncertainties — FDA electromagnetic compatibility testing requirement revisions, IEC standard edition updates, and 7 Tesla clinical installation pace — sit outside the modeled envelope. Forecasts reflect assumptions about hospital capital allocation continuity and specialty metallurgy supply stability. Recalibration cycles align with material shifts in Medicare coverage determinations and MDR CE marking enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Composite Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Arthroscopy Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Bariatric Beds Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
North America Pen Needles Market
Medical Devices
Global Body Contouring Devices Market