
 North America Superhydrophobic Coating Market | 2026-2036
North America Superhydrophobic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
North America Superhydrophobic Coating Market Analytics
The EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) is rebalancing capital allocation across the North American superhydrophobic coating supply base. P2i Ltd leverages its plasma-enhanced deposition expertise to serve medical device OEMs with regulatory-compliant barrier films. Rust-Oleum (NeverWet) anchors the consumer-accessible segment through mass retail distribution of spray-applied formulations. NEI Corporation differentiates via nanocomposite architectures that meet MIL-SPEC durability thresholds for defense contractors.
Superhydrophobic coatings are thin-film surface treatments engineered with contact angles exceeding 150 degrees and roll-off angles below 10 degrees, typically incorporating fluorinated polymers, silica nanoparticles, or hierarchical micro-nano topographies to achieve extreme water repellency for corrosion prevention, anti-icing, and self-cleaning functions. Fluoropolymer formulations command premium positioning due to their chemical inertness and longevity in outdoor exposure, while silica-based alternatives gain traction in electronics where optical clarity and thermal stability matter. Spray coating technology dominates manufacturing throughput for automotive and textile applications, whereas vacuum coating occupies the precision electronics segment where film uniformity requirements are most stringent.
The EPA enforces VOC limits under 40 CFR Part 59 that constrain solvent-borne formulation options, while OSHA's Hazard Communication Standard governs workplace exposure to fluorinated chemistries during application. Health Canada's PMRA parallel registration requirements for antimicrobial claims create a dual-compliance burden for suppliers serving cross-border medical device markets. Stakeholders must monitor the convergence of state-level green chemistry mandates in California and New York with federal procurement specifications to anticipate which formulation platforms will retain market access.
Market Dynamics
EPA's evolving VOC emission standards under the Clean Air Act are compelling coating manufacturers to abandon solvent-borne formulations and rebuild supply chains around water-borne and low-solvent chemistries, reshaping competitive positioning across the North American value chain.
Growth Catalysts
- Clean Air Act compliance deadlines:EPA's 40 CFR Part 59 enforcement is accelerating reformulation investments, opening procurement windows for compliant suppliers.
- Aerospace de-icing demand:United States maintenance operations are expanding ice-phobic wing surface applications to reduce operational downtime and fuel consumption.
- California semiconductor packaging:Electronics manufacturers in the state's technology corridor are adopting moisture barrier coatings for advanced chip protection.
Market Restraints
- Fluorinated chemistry input costs:Perfluorinated compound feedstock volatility constrains margin stability for premium formulation tiers.
- Canadian dual-registration burden:Health Canada's PMRA antimicrobial claim requirements create parallel compliance costs for cross-border medical device suppliers.
- Durability-performance trade-off:Silica-based alternatives lack the longevity of fluoropolymer systems in outdoor exposure applications.
Strategic Opportunities
- New York green chemistry mandates:State-level procurement preferences are creating first-mover advantage for bio-based formulation platforms.
- Defense MIL-SPEC contracts:Nanocomposite architectures meeting military durability thresholds represent high-margin, long-term revenue streams.
- Plasma-enhanced deposition convergence:Medical device OEMs are integrating barrier film technology with existing sterilization workflows.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in fluoropolymer-silica hybrid systems remains concentrated among a limited talent pool.
- Application equipment capex:Vacuum coating systems for electronics-grade film uniformity require substantial capital deployment.
- OSHA exposure compliance:Hazard Communication Standard training and monitoring infrastructure adds operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Superhydrophobic Coating Market |
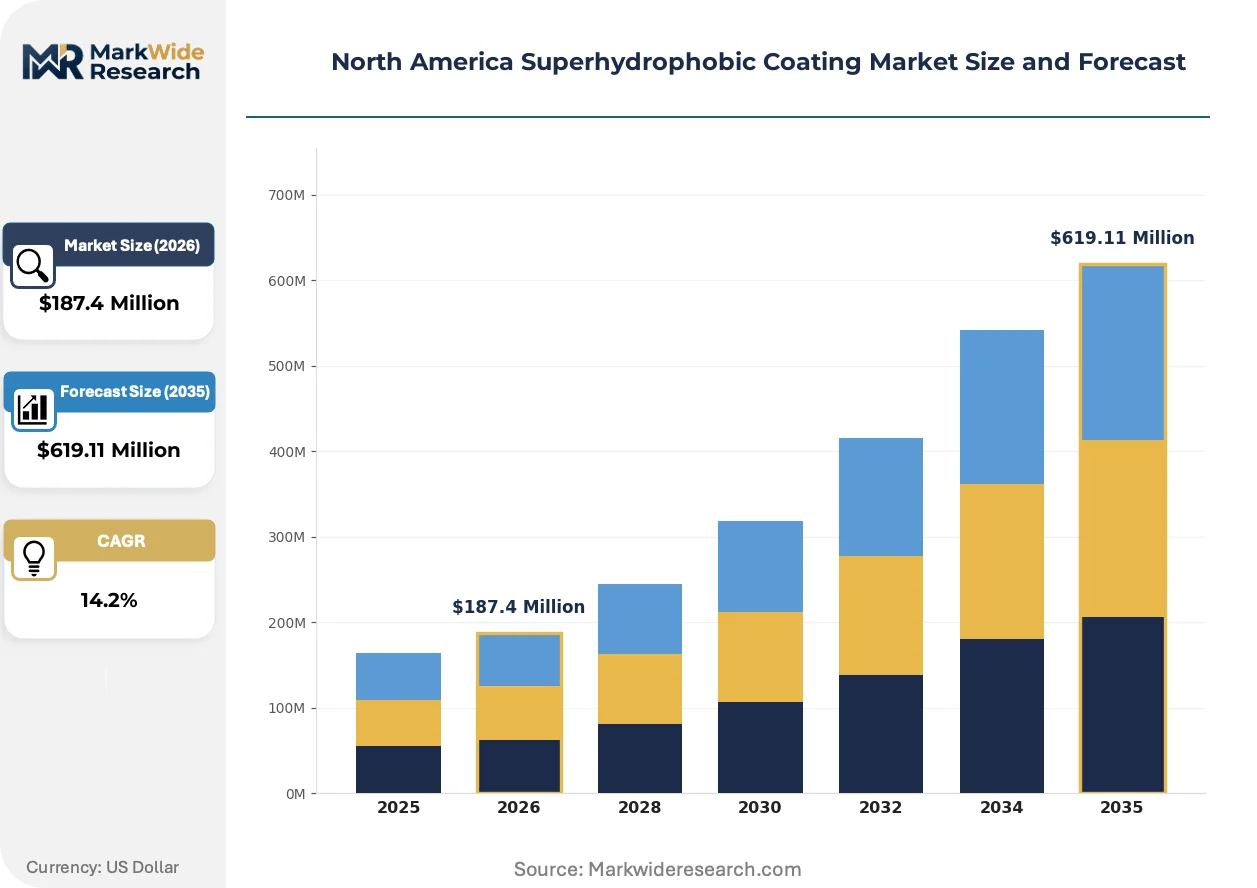
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica-Based, Polyurethane, Fluoropolymer, Ceramics Application: Automotive, Electronics, Textiles, Medical End User: Manufacturers, Research Institutes, Hospitals, Consumers Technology: Spray Coating, Dip Coating, Brush Coating, Vacuum Coating |
| Companies Covered | Rust-Oleum (NeverWet), P2i Ltd, UltraTech International Inc., NEI Corporation, Aculon, Inc., 3M Company, BASF SE, The Sherwin-Williams Company, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Superhydrophobic Coating Market Evolving Landscape
Water-borne superhydrophobic chemistries are overtaking solvent-borne platforms as the dominant formulation architecture, driven by regulatory pressure and end-user sustainability mandates across North American industrial markets.
Spray-deposited fluoropolymer-nanoparticle composites are overtaking conventional dip-coating methods for automotive and textile applications, enabling faster throughput and reduced material waste. Tier 1 suppliers in Michigan and Ontario are retrofitting lines to accommodate these systems. The technology is overtaking legacy batch processes by compressing cure cycles from hours to minutes.
California's green chemistry initiative is converging with federal procurement specifications to create a unified compliance threshold for coating suppliers. Formulators must now satisfy both state-level substance restrictions and defense contractor performance standards simultaneously. Medical device manufacturers operating across the US-Canada border face the steepest adaptation burden.
Direct technical service relationships are displacing traditional distributor intermediaries in the precision electronics segment. Semiconductor packaging engineers in San Jose and Austin now specify coatings through collaborative development agreements rather than catalog procurement. This pattern is most visible among fabs pursuing sub-7nm process nodes where moisture protection tolerances tighten.
North America Superhydrophobic Coating Market Segmentation
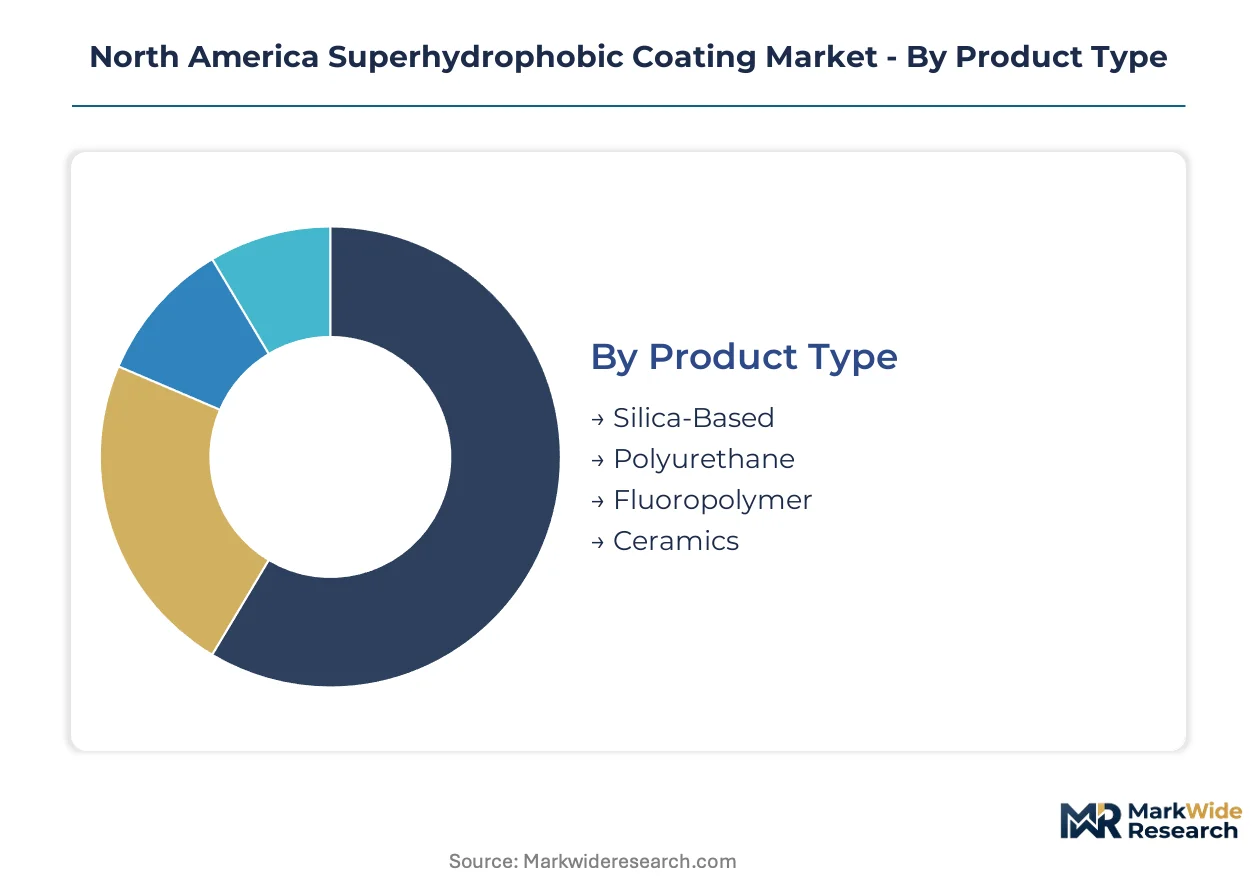
Superhydrophobic coating procurement patterns diverge sharply across formulation chemistry, deposition method, and end-use durability requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier priorities across the North American value chain.
Product Type:
Reformulation cycles are accelerating as EPA VOC deadlines force coating manufacturers to abandon legacy solvent-borne platforms and validate water-borne alternatives without sacrificing contact angle performance.
- Fluoropolymer:Perfluorinated polymer architectures deliver contact angles exceeding 160 degrees with exceptional chemical inertness. Aerospace maintenance operations in the United States specify these formulations for ice-phobic wing surfaces where longevity under thermal cycling justifies premium positioning despite feedstock volatility.
- Silica-Based:Hierarchical micro-nano topographies formed from colloidal silica nanoparticles achieve optical clarity above 90% transmission. Electronics manufacturers in California's technology corridor favor these systems for semiconductor packaging where thermal stability and refractive index matching outweigh outdoor durability constraints.
- Polyurethane:Hybrid organic-inorganic networks balance abrasion resistance with substrate adhesion across flexible substrates. Automotive trim suppliers specify these for interior applications where mechanical wear dominates environmental exposure.
- Ceramics:Sol-gel derived oxide layers withstand temperatures exceeding 500°C in industrial exhaust environments. Power generation equipment OEMs deploy these for turbine blade protection where thermal shock resistance is paramount.
Volume placements concentrate in Fluoropolymer; the faster expansion belongs to Silica-Based.
Application:
End-use durability specifications create tiered procurement thresholds that separate military-grade contracts from consumer-accessible retail channels.
- Electronics:Sub-7nm semiconductor fabs demand moisture barriers with film thickness uniformity below 50 nanometers. Collaborative development agreements between San Jose packaging engineers and coating suppliers are displacing traditional catalog procurement.
- Automotive:Exterior trim and sensor housing applications require UV stability across 10-year warranties. Michigan-based Tier 1 suppliers retrofit lines for spray-deposited composites that compress cure cycles from hours to minutes.
- Medical:Implantable device OEMs integrate plasma-enhanced barrier films with existing sterilization workflows. Health Canada's PMRA parallel registration requirements create compliance burdens for cross-border suppliers.
- Textiles:Performance apparel brands specify wash-durable treatments exceeding 50 cycles. Mass retail distribution channels favor spray-applied formulations with simplified consumer application protocols.
Procurement value concentrates in Electronics; Medical exhibits the steepest expansion trajectory as device miniaturization intensifies moisture protection requirements.
End User:
Customer technical sophistication determines whether coatings are specified through direct development partnerships or distributor intermediaries.
- Manufacturers:Integrated production facilities specify coatings at the design stage with embedded quality protocols. Defense contractors impose MIL-SPEC durability thresholds that nanocomposite architectures must satisfy for contract eligibility.
- Research Institutes:National laboratories and university centers validate novel deposition chemistries before commercial scale-up. Federal procurement specifications increasingly incorporate California green chemistry substance restrictions.
- Hospitals:Sterile processing departments specify antimicrobial barrier films for surgical instruments and equipment surfaces.
- Consumers:DIY applicators purchase spray formulations through mass retail channels with simplified surface preparation instructions.
Contract volume concentrates in Manufacturers; Research Institutes are gaining share fastest as federal funding accelerates advanced materials validation.
Technology:
Capital equipment requirements stratify the supplier base between precision electronics-grade systems and high-throughput industrial lines.
- Spray Coating:Pneumatic and electrostatic systems dominate automotive and textile manufacturing throughput. Reduced material waste and faster line speeds are displacing legacy dip-coating batch processes.
- Vacuum Coating:Physical vapor deposition and plasma-enhanced systems achieve film uniformity for semiconductor packaging. Substantial capital deployment requirements limit supplier participation in this precision segment.
- Dip Coating:Immersion methods persist for complex geometries where spray coverage is inconsistent. Batch processing constraints limit adoption in high-volume manufacturing environments.
- Brush Coating:Manual application survives in repair and maintenance operations where equipment mobility outweighs throughput efficiency.
Installed base concentrates in Spray Coating; Vacuum Coating is climbing the fastest as sub-7nm node production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-Trade Zone 37 in Los Angeles anchors coating concentration through duty-deferred raw material imports serving aerospace and electronics clusters. State-level green chemistry mandates in California and New York are converging with federal procurement specifications to reshape supplier access across the continent.
United States
Aerospace maintenance operations in Washington State and Texas deploy ice-phobic wing surface treatments to reduce fuel consumption and operational downtime. EPA's 40 CFR Part 59 enforcement under the Clean Air Act is accelerating reformulation investments toward water-borne chemistries. California's technology corridor from San Jose to San Diego concentrates semiconductor packaging demand for moisture barrier coatings at sub-7nm nodes.
Canada
Medical device OEMs in Ontario integrate plasma-enhanced barrier films with sterilization workflows for implantable products. Health Canada's PMRA imposes parallel antimicrobial claim registration requirements that duplicate compliance costs for cross-border suppliers. Toronto-Waterloo corridor research institutes validate novel deposition chemistries before commercial scale-up.
Mexico
Automotive Tier 1 suppliers in Nuevo León retrofit coating lines for spray-deposited composites serving US assembly plants. Mexico's environmental regulator SEMARNAT enforces VOC limits that align with EPA standards for integrated North American supply chains. Querétaro's aerospace cluster attracts specialty coating operations seeking proximity to Bombardier and GE Aviation facilities.
North America Superhydrophobic Coating Market Competitive Landscape
United States producers anchor the premium formulation tier; Canadian and European specialists hold positions in precision deposition segments. The vendor base stratifies across three tiers: diversified chemical conglomerates with coating divisions, mid-cap nanomaterial specialists, and single-product application technology firms. Competitive moves concentrate on regulatory-compliant reformulation partnerships and plasma-enhanced deposition licensing agreements.
Within the diversified chemical tier, BASF SE and PPG Industries occupy positions exemplifying scale-driven supply security for automotive and industrial accounts. Among application-technology specialists, P2i Ltd and NEI Corporation represent archetypes of regulatory-first positioning—P2i anchoring medical device barrier films, NEI occupying defense contractor nanocomposite specifications. Rust-Oleum (NeverWet) sits within the consumer-accessible vector through mass retail distribution of spray-applied formulations.
| Leading Market Players |
|---|
| Rust-Oleum (NeverWet) |
| P2i Ltd |
| UltraTech International Inc. |
| NEI Corporation |
| Aculon, Inc. |
| 3M Company |
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Others |
Value Network & Pricing Analysis
California's green chemistry mandates and federal procurement convergence are forcing reformulation investments that compress margins for solvent-borne incumbents while rewarding compliant suppliers with pricing power on water-borne platforms.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent aerospace maintenance orders from standard industrial procurement. Three-tier pricing structure across premium fluoropolymer, mid-grade silica-based, and economy polyurethane levels reflects certification grade and volume scale differentiation. Cost compression in the premium tier is intensifying because perfluorinated feedstock volatility constrains margin stability. Automotive Tier 1 suppliers exhibit highest price sensitivity due to warranty cost pass-through pressures, while defense contractors show lowest sensitivity given MIL-SPEC performance thresholds.
Supply Chain Analysis
Single-source vulnerability sits with Chinese colloidal silica nanoparticle feedstock for electronics-grade formulations. Manufacturing concentration centers on the United States, Germany, and Japan for fluoropolymer resin synthesis. Raw material dependencies include perfluorinated compounds, hierarchical silica architectures, and plasma deposition gases. Tariff exposure on Chinese nanoparticle imports threatens cost structures for California semiconductor packaging suppliers. Distribution runs through direct technical service relationships in precision electronics and mass retail channels for consumer spray formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist scarcity props pricing for compliant water-borne platforms, creating supply-constrained conditions that favor incumbents with validated EPA pathways.
For Market Incumbents: Hedge against fluorinated chemistry input volatility through backward integration into water-borne resin synthesis or long-term offtake agreements with German and Japanese feedstock suppliers. Reinforce regulatory compliance infrastructure to defend procurement windows as EPA 40 CFR Part 59 enforcement tightens.
For New Entrants and Emerging Players: Mid-tier automotive sensor housing suppliers represent an underserved buyer archetype seeking UV-stable coatings at compressed cure cycles. Plasma-enhanced deposition licensing for medical device OEMs offers the most penetrable entry vector. Pursue collaborative development agreements rather than catalog distribution to bypass incumbent channel control.
For Investors and Strategic Acquirers: The window for entry favors nanocomposite specialists with validated MIL-SPEC durability thresholds. Long-term viability hinges on dual-compliance capability for California green chemistry mandates and federal procurement specifications. Monitor EPA enforcement intensity as the inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Partnership | Water-borne platform validation with EPA 40 CFR Part 59 compliance secures aerospace procurement access. |
| Plasma Deposition Licensing | Medical device OEM integration with sterilization workflows captures implantable barrier film demand. |
| Backward Integration | In-house perfluorinated resin production mitigates feedstock volatility for premium fluoropolymer tiers. |
| Direct Technical Service | Collaborative development agreements with San Jose packaging engineers displace distributor intermediaries. |
| MIL-SPEC Certification | Nanocomposite durability validation unlocks defense contractor long-term revenue streams. |
Research Methodology
Independent corroboration across formulation chemists at coating manufacturers, procurement leads at Michigan automotive Tier 1 suppliers, and regulatory affairs directors at medical device OEMs underwrites the qualitative findings. Secondary validation draws from EPA 40 CFR filings, Health Canada PMRA registration databases, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on fluorinated compound imports. Bottom-up segment sizing triangulates with top-down market reconstruction across formulation chemistry, deposition technology, and end-use durability tiers.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include formulation chemistry tier, deposition method precision grade, end-use durability specification, and state-level regulatory cluster. CAGRs derive from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs incorporate EPA enforcement timeline assumptions and semiconductor node transition rates for moisture barrier demand.
Revisions become necessary when EPA accelerates VOC compliance deadlines, Chinese export restrictions on colloidal silica materialize, or aerospace maintenance budgets contract sharply. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Coating Equipment Market
Coatings
Electrical Insulation Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
OEM Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Coating Resins Market
Coatings
North America Concrete Floor Coatings Market