
 Piping Systems Market | 2026-2036
Piping Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Piping Systems Market Analysis
A widening capital-intensity gap between integrated instrumentation providers and pure-play pipe fabricators is redrawing competitive boundaries in piping systems. Siemens AG leverages its digital twin and flow-measurement portfolio to bundle intelligent piping diagnostics with hardware contracts. Pentair plc anchors its position through filtration-integrated piping solutions for water treatment infrastructure. KROHNE Group differentiates via electromagnetic flow sensor technology embedded directly into metallic pipe segments for oil and gas custody transfer.
Piping systems encompass engineered conduit networks fabricated from metallic, thermoplastic, or composite materials, designed to transport fluids and gases under specified pressure ratings typically ranging from 150 psi to over 10,000 psi in process industries. These assemblies incorporate valves, fittings, pumps, and sensors to regulate flow, prevent leakage, and enable real-time monitoring across industrial, commercial, and municipal installations. Metallic pipes in steel and copper dominate high-pressure oil and gas applications where thermal cycling and mechanical stress resistance determine service life. Plastic pipes in PVC and HDPE are capturing share in water supply and HVAC systems due to lower installation weight and reduced corrosion maintenance. Composite pipe segments remain niche but command premium positioning in offshore installations where strength-to-weight ratios justify higher material costs.
EPA lead and copper rules in the United States mandate infrastructure replacement timelines that compress municipal procurement cycles for compliant piping materials. REACH substance restrictions in Europe and China's GB standards for drinking water contact materials are converging to limit phthalate plasticizers and heavy metal stabilizers in polymer pipe formulations. Stakeholders must monitor regulatory divergence between ASME pressure vessel codes and emerging ISO lifecycle assessment standards to avoid compliance-driven margin erosion on cross-border projects.
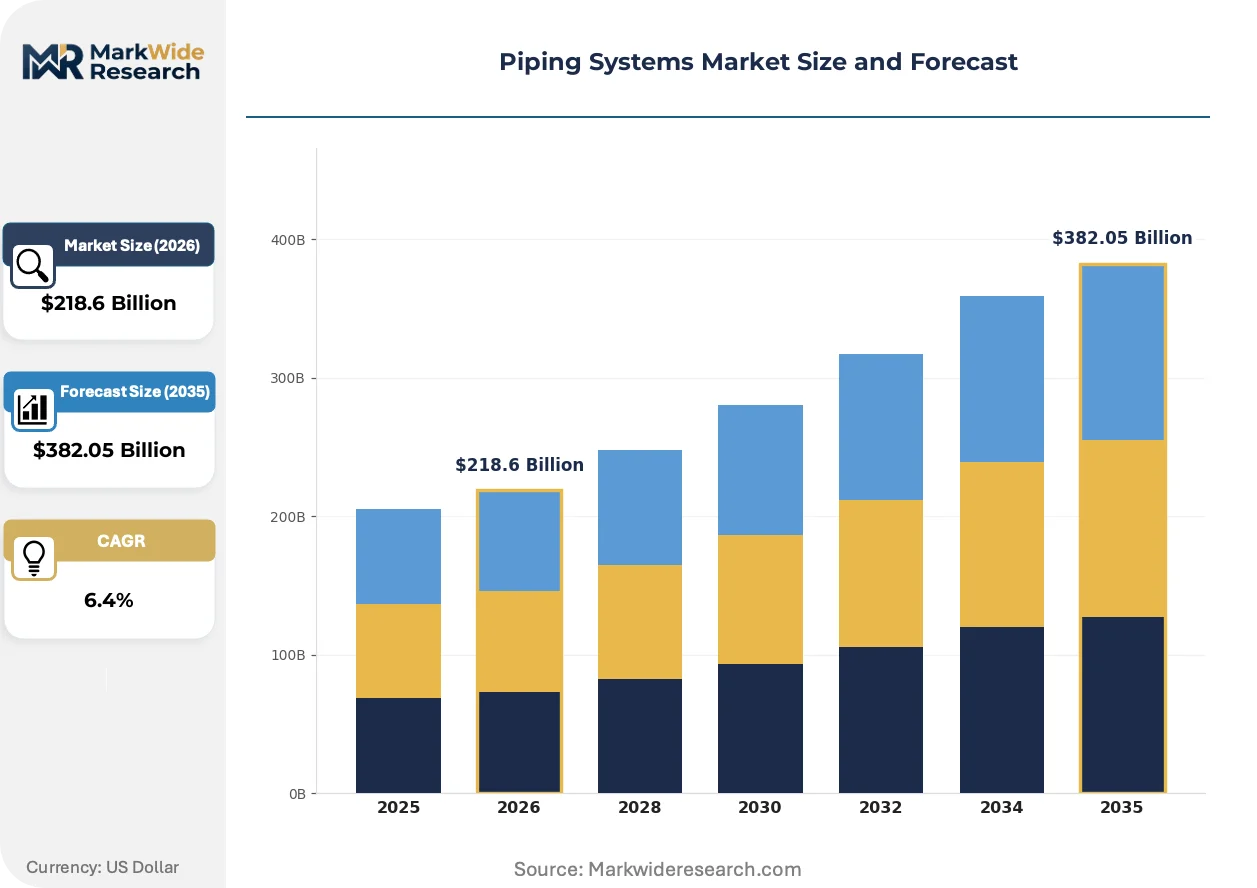
Market Dynamics
Corrosion-resistant polymer formulations are displacing legacy metallic infrastructure across municipal water networks, compressing replacement cycles and redrawing supplier qualification criteria for contractors and utilities.
Growth Catalysts
- EPA Lead and Copper Rule revisions:US municipalities face compressed replacement timelines for lead service lines, accelerating procurement of compliant copper and polymer alternatives.
- China's petrochemical corridor expansion:High-pressure metallic systems command sustained demand from ethylene crackers and refinery complexes in Ningbo, Dalian, and Shanghai clusters.
- EU Green Deal procurement mandates:Recyclable HDPE and PEX formulations gain preference in district heating retrofits across German and Dutch utility networks.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock fluctuations compress margin predictability for thermoplastic pipe extruders.
- Specialty steel supply concentration:Seamless alloy pipe for ultra-high-pressure oil and gas applications depends on limited German and Japanese mill capacity.
- Welding certification bottlenecks:ASME Section IX qualified welder shortages extend project commissioning timelines in North American process industries.
Strategic Opportunities
- India's AMRUT 2.0 urban water schemes:Underpenetrated smart metering integration creates demand for sensor-embedded distribution networks in 500+ cities.
- Electrofusion joining systems:Convergence of RFID traceability with automated fusion equipment reduces installation labor hours for HDPE gas distribution.
- Carbon border adjustment mechanisms:EU CBAM incentivizes low-carbon metallic pipe sourcing from electric-arc-furnace producers.
Industry Challenges
- Polymer formulation compliance:Divergent REACH, GB standards, and state-level US requirements multiply certification burdens for multi-territory suppliers.
- Legacy metallic infrastructure interoperability:New composite and polymer segments require custom transition fittings to interface with century-old cast-iron networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piping Systems Market |
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $382.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Pipes, Plastic Pipes, Composite Pipes, Concrete Pipes Application: Water Supply, Oil & Gas, Chemical Transport, HVAC Systems Material: Steel, PVC, HDPE, Copper Installation Type: Above Ground, Below Ground, Onshore, Offshore |
| Companies Covered | Siemens AG, KROHNE Group, Emerson Electric Co, Metso Outotec Corporation, Endress+Hauser AG, Honeywell International Inc, General Electric Company, Pentair plc, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piping Systems Market Emerging Trajectories
Digital instrumentation embedded directly into pipe walls is collapsing the distinction between passive conduit and active monitoring infrastructure, enabling predictive maintenance contracts that shift revenue from hardware to recurring service streams.
Glass-reinforced epoxy (GRE) pipe is displacing carbon steel in offshore produced water and sour service applications. Norwegian and Brazilian deepwater operators specify GRE for its immunity to CO2 corrosion and weight reduction on platform structures. This displacement is compressing the addressable market for corrosion-resistant alloy metallurgies in subsea tiebacks.
REACH substance restrictions on phthalate plasticizers and heavy metal stabilizers are forcing reformulation of flexible PVC compounds for potable water contact. German compounders and Italian processors face accelerated R&D cycles to maintain CE marking eligibility. The restriction most severely impacts soft PVC gasket and connector segments serving Southern European irrigation markets.
Performance-based service agreements are supplanting unit-price contracting for large-diameter water transmission projects. Australian water utilities and UK water companies now specify leakage-rate guarantees rather than material specifications, transferring operational risk to EPC contractors. This behavioral shift concentrates procurement authority among integrated solution providers capable of underwriting long-term performance bonds.
Piping Systems Market Segmentation
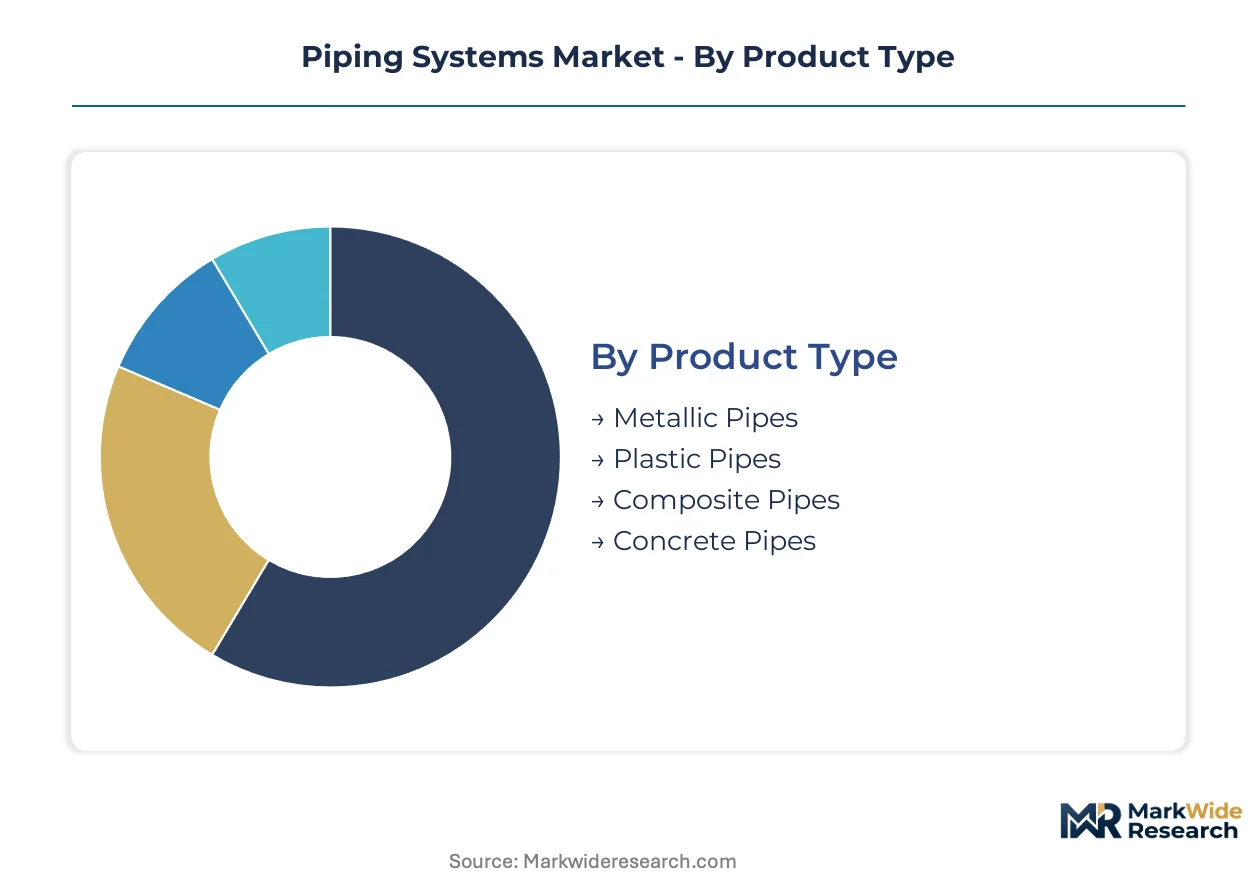
Segmentation in piping systems reveals divergent margin structures across material technologies and installation environments. Procurement patterns differ sharply between municipal utilities prioritizing lifecycle cost and process industries demanding pressure-rated performance.
Product Type:
Margin pools concentrate in corrosion-resistant formulations where specification authority sits with engineering contractors rather than commodity distributors.
- Metallic Pipes:Fabricated from carbon steel, stainless steel, and specialty alloys to withstand pressure ratings exceeding 10,000 psi in process applications. Demand concentrates in China's Ningbo and Dalian petrochemical clusters where ethylene crackers require seamless alloy pipe for high-temperature cracking operations.
- Plastic Pipes:Extruded from thermoplastic polymers including PVC, HDPE, and PEX for pressure ratings below 250 psi. Procurement accelerates in German and Dutch district heating networks where EU Green Deal mandates favor recyclable HDPE formulations over legacy metallic infrastructure.
- Composite Pipes:Glass-reinforced epoxy laminates offering strength-to-weight ratios superior to steel for offshore environments.
- Concrete Pipes:Reinforced cement cylinders for large-diameter gravity-flow sewage and stormwater systems.
The dominant share belongs to metallic pipes, while plastic pipes are gaining share fastest as municipal corrosion-resistant retrofits accelerate.
Application:
Volume concentration follows infrastructure replacement cycles, with regulatory compliance deadlines compressing procurement timelines in water supply networks.
- Water Supply:Distribution networks for potable water, fire protection, and irrigation spanning municipal, commercial, and agricultural end-uses. US municipalities face compressed replacement timelines under EPA Lead and Copper Rule revisions, accelerating procurement of compliant copper and polymer service lines in cities including Chicago, Milwaukee, and Newark.
- Oil & Gas:Production gathering lines, transmission pipelines, and refinery process piping for hydrocarbon transport. Brazilian and Norwegian deepwater operators specify glass-reinforced epoxy for produced water handling, displacing carbon steel in platform structures.
- Chemical Transport:Process piping for corrosive fluids and high-purity applications in pharmaceutical and specialty chemical plants.
- HVAC Systems:Chilled water, heating hot water, and refrigerant distribution in commercial and institutional buildings.
Water supply commands the largest installed base, though oil and gas applications retain the highest value per linear meter.
Material:
Supply concentration varies by feedstock access, with polymer formulations vulnerable to ethylene price volatility and steel tied to electric-arc furnace capacity.
- Steel:Carbon and alloy grades for high-pressure process piping, with seamless pipe depending on limited German and Japanese mill capacity for ultra-high-pressure oil and gas applications.
- PVC:Rigid polyvinyl chloride for drainage, irrigation, and electrical conduit where REACH substance restrictions on phthalate plasticizers force compound reformulation.
- HDPE:High-density polyethylene for water distribution and gas transmission, with electrofusion joining systems reducing installation labor hours.
- Copper:Seamless tube for potable water service lines and medical gas systems, commanding premium positioning where lead replacement mandates apply.
Steel retains structural dominance in process industries, while HDPE expands most quickly in municipal infrastructure.
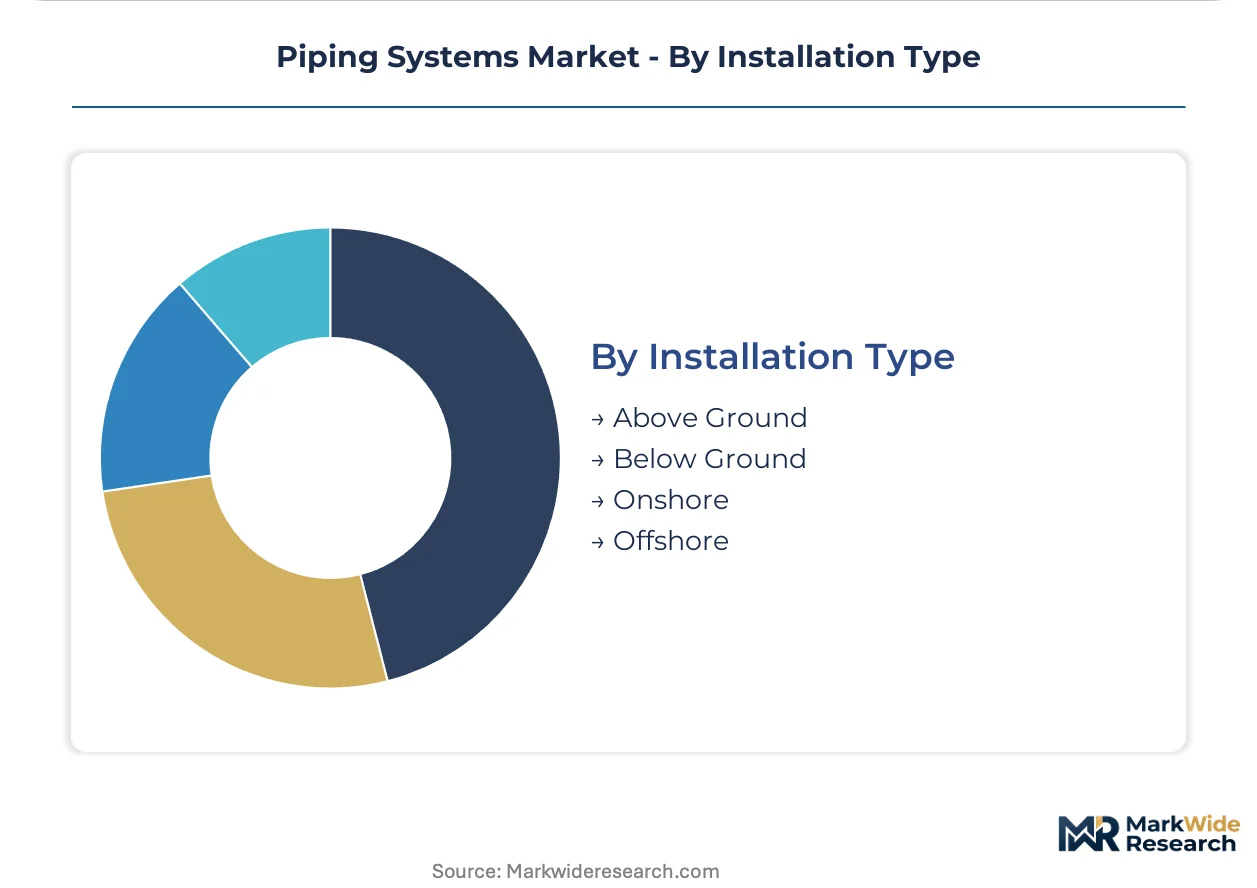
Installation Type:
Project economics diverge sharply between accessible urban environments and remote offshore locations where logistics dominate total installed cost.
- Above Ground:Exposed piping in process plants, commercial buildings, and bridge crossings where thermal expansion and seismic bracing determine support spacing.
- Below Ground:Direct-buried municipal water, sewer, and gas distribution requiring corrosion protection and cathodic monitoring systems.
- Onshore:Transmission pipelines across varied terrain where welding certification bottlenecks extend commissioning timelines in North American projects.
- Offshore:Platform and subsea installations where composite pipe segments command premium positioning based on strength-to-weight ratios.
Below-ground installation represents the largest addressable volume, while offshore applications sustain the steepest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities in Germany and the Netherlands demonstrate the lowest price elasticity, accepting premium recyclable formulations under EU Green Deal mandates. Chinese petrochemical operators show intermediate sensitivity, prioritizing pressure-rated performance over material cost. US municipal buyers face the highest budget constraints, compressing procurement timelines under EPA compliance deadlines.
United States
EPA Lead and Copper Rule revisions are compressing replacement timelines for lead service lines in Chicago, Milwaukee, and Newark. Municipal procurement cycles have shortened from 18 months to 8 months for compliant copper and polymer alternatives. The Great Lakes region concentrates demand for corrosion-resistant infrastructure retrofits.
Germany
REACH substance restrictions and EU Green Deal procurement mandates are redirecting district heating networks toward recyclable HDPE formulations. German utilities in the Ruhr industrial corridor specify lifecycle-cost contracts over unit-price bidding. Bavarian compounders face accelerated R&D cycles to maintain CE marking eligibility for phthalate-free PVC compounds.
China
GB standards for drinking water contact materials are converging with European restrictions to limit heavy metal stabilizers in polymer formulations. Ningbo, Dalian, and Shanghai petrochemical clusters sustain demand for seamless alloy pipe in ethylene cracker operations. The Yangtze River Delta dominates high-pressure metallic procurement for refinery expansion projects.
Brazil
ANVISA drinking water regulations are tightening migration limits for plasticizer compounds in PVC distribution networks. Deepwater operators offshore Rio de Janeiro specify glass-reinforced epoxy for produced water handling, displacing carbon steel in platform structures. The Santos Basin pre-salt fields command premium positioning for corrosion-resistant composite segments.
India
BIS certification requirements for potable water contact materials are multiplying compliance burdens for multi-territory suppliers. AMRUT 2.0 urban water schemes in 500-plus cities create demand for sensor-embedded distribution networks. Maharashtra and Gujarat industrial corridors concentrate procurement for smart metering integration in underpenetrated municipal systems.
Piping Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive boundaries. Integrated instrumentation providers bundle intelligent diagnostics with hardware contracts, while pure-play fabricators compete on extrusion scale and welding certification capacity. Three archetypes dominate: multinational industrial conglomerates with digital twin portfolios, filtration-integrated solution providers, and electromagnetic flow sensor specialists. M&A activity concentrates on sensor-embedded pipe technology, while capacity expansion targets electric-arc-furnace steel sourcing for EU CBAM compliance.
Among German-based industrial conglomerates, Siemens AG and KROHNE Group occupy positions at the technology-intensive end of the competitive spectrum. Siemens exemplifies the integrated instrumentation archetype through its digital twin and flow-measurement portfolio. KROHNE represents the sensor-embedded specialization vector, with electromagnetic technology integrated directly into metallic pipe segments. Pentair plc anchors the filtration-integrated tier, bundling water treatment solutions with distribution hardware. These three companies illustrate the strategic divergence between hardware-centric and service-centric revenue models.
| Leading Market Players |
|---|
| Siemens AG |
| KROHNE Group |
| Emerson Electric Co |
| Metso Outotec Corporation |
| Endress+Hauser AG |
| Honeywell International Inc |
| General Electric Company |
| Pentair plc |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Seamless alloy pipe capacity utilization above 85% at German and Japanese mills creates asymmetric pricing power for ultra-high-pressure oil and gas applications. This concentration anchors price floors for metallic systems while compressing margin pools for distributors unable to secure mill-direct allocations. Scale economies in HDPE extrusion, conversely, fragment supplier power and intensify cost competition among regional thermoplastic fabricators.
Pricing Analysis
Service-contract bundling drives lifetime value, with predictive maintenance agreements capturing recurring revenue streams that exceed original hardware margins by multiples. Project-based contracting dominates municipal water procurement, though performance-based leakage guarantees are displacing unit-price bidding in Australian and UK utility markets. Price differentiation hinges on ASME Section IX welding certification tiers and digital twin integration depth. Cost compression in standard-grade thermoplastic segments reflects ethylene feedstock volatility and Chinese extrusion overcapacity. Municipal utilities in the US Great Lakes region exhibit highest price sensitivity due to compressed EPA compliance timelines, while German district heating operators accept recyclable HDPE premiums under EU Green Deal mandates.
Supply Chain Analysis
Strategic stockpiling of specialty steel feedstock prevails among oil and gas EPC contractors, contrasting with just-in-time resin procurement by municipal pipe distributors. Primary metallic supply concentrates in Germany, Japan, and South Korea for seamless alloy pipe, while HDPE resin production clusters in Saudi Arabia, China, and the US Gulf Coast. Raw material dependencies include ethylene and propylene feedstocks, copper cathode, and glass fiber roving for composite laminates. Single-source vulnerability haunts ultra-high-pressure applications where ASME-qualified mill capacity is constrained. Distribution runs through engineering-procurement-construction contractors for process industries and regional utility distributors for municipal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piping systems market sits in early-cycle expansion as regulatory replacement mandates across US, EU, and Chinese jurisdictions compress procurement timelines and accelerate material substitution toward corrosion-resistant formulations.
For Market Incumbents: Shield installed-base revenue by embedding electromagnetic flow sensors and digital twin diagnostics into metallic pipe contracts before pure-play fabricators achieve instrumentation parity. Prioritize backward integration into electric-arc-furnace steel sourcing to preempt EU CBAM compliance cost disadvantages. Consolidate welding certification capacity in North America to capture ASME Section IX qualified welder premiums. For New Entrants and Emerging Players: Differentiate on sensor-embedded distribution networks for India's AMRUT 2.0 urban water schemes, where smart metering integration remains underpenetrated across 500-plus cities. Target electrofusion joining system automation for HDPE gas distribution, converging RFID traceability with reduced labor-hour economics. Pursue direct contracting with Maharashtra and Gujarat municipal corporations bypassing legacy distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated instrumentation providers bundling predictive maintenance with hardware contracts, suggesting superior cash flow quality versus pure-play extrusion or fabrication. Acquisition focus should center on electromagnetic sensor specialists and electrofusion equipment manufacturers with established utility channel relationships. Monitor EU CBAM implementation pace as inflection indicator for low-carbon metallic pipe sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electric-Arc-Furnace Steel | Secures low-carbon feedstock for EU CBAM compliance without tariff exposure. |
| Sensor-Embedded Pipe Technology Acquisition | Collapses hardware-service boundary and enables predictive maintenance contracts. |
| Electrofusion Joining System Automation | Reduces HDPE installation labor hours while embedding RFID traceability. |
| ASME Section IX Welding Certification Expansion | Captures premium positioning in North American process industry projects. |
| Smart Metering Integration Partnership | Penetrates India's AMRUT 2.0 urban water schemes with underpenetrated demand. |
Methodological Framework
Desk research of trade association databases, customs filings, and regulatory dockets preceded structured interviews with municipal utility procurement directors, EPC contractor project managers, pipe fabricator plant engineers, and petrochemical facility maintenance heads. Secondary validation drew from ASME code documentation, EPA enforcement records, EU Green Deal procurement guidelines, and SEC 10-K disclosures of publicly traded industrial conglomerates. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity checks.
Variance decomposition across material type, pressure rating tier, installation environment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level elasticity modeling against infrastructure replacement cycle timing and petrochemical capacity expansion schedules. Modeled inputs included ethylene price forecasting, electric-arc-furnace capacity buildout trajectories, and ASME welder certification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of lead service line replacement timelines or unexpected specialty steel mill capacity additions would require recalibration. Forecasts reflect documented assumptions regarding feedstock price trajectories and certification bottleneck persistence. Practitioners should keep alternative scenarios live as EU CBAM implementation pace and Chinese GB standard convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Residential and Commercial Smart Glass Market