
 Middle East and Africa Agricultural Pheromones Market | 2026-2036
Middle East and Africa Agricultural Pheromones Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Agricultural Pheromones Market Foresight
Modular dispenser formats are consolidating buyer preference across the Middle East and Africa Agricultural Pheromones Market, with growers favoring season-long bundled systems over single-application purchases. BASF SE leverages its polymer-matrix expertise to sustain premium positioning in controlled-release formulations. Suterra LLC anchors regional supply through its Dubai distribution hub, serving Israeli and Jordanian stone-fruit orchards. Russell IPM Ltd. competes on cost-engineered monitoring traps tailored to smallholder vegetable cooperatives in Morocco and Tunisia.
Agricultural pheromones are semiochemical compounds synthesized to mimic natural insect signaling molecules, typically deployed through polyethylene tube dispensers or membrane laminates at doses measured in milligrams per hectare to disrupt pest mating cycles or concentrate populations for removal. Their primary commercial purpose is precision pest suppression that eliminates off-target ecological damage while preserving beneficial insect populations and meeting export-market residue standards. Mating disruption commands structural priority in product-type revenue pools due to its labor efficiency in large-scale Saudi date plantations and South African citrus estates. Crop protection dominates application-level demand as integrated pest management protocols displace calendar spraying in Egyptian export grape operations. Online stores represent the fastest-expanding distribution channel, with Israeli agritech platforms and South African farm-input e-commerce portals reducing extension-agent dependence for pheromone ordering and timing guidance.
South Africa's Department of Agriculture enforces residue monitoring aligned with EU MRL schedules, compelling citrus and table-grape exporters toward biocontrol verification. Israel's Plant Protection and Inspection Services mandates pheromone buffer zones near organic-certified farms, directly shaping dispenser placement protocols and product registration requirements. Egypt's Agricultural Pesticide Committee has accelerated temporary biocontrol approvals for red palm weevil management in Ismailia and Damietta governorates. Stakeholders must monitor how Gulf standardization bodies harmonize pheromone efficacy labeling across Saudi Arabia, the UAE, and Oman, as divergent registration timelines currently fragment procurement planning for multinational crop-protection distributors.
Market Dynamics
EU phytosanitary residue limits are compressing conventional insecticide use across Middle East and Africa export horticulture, redirecting procurement toward biocontrol verification systems and pheromone-based mating disruption protocols.
Growth Catalysts
- Red palm weevil biocontrol mandates:Egypt's Agricultural Pesticide Committee has accelerated temporary approvals for pheromone-based management in Ismailia and Damietta governorates, creating immediate demand pull from date palm cooperatives.
- EU MRL alignment enforcement:South Africa's Department of Agriculture, Land Reform and Rural Development has tightened maximum residue limits on conventional insecticides, compelling citrus and table-grape exporters toward verified biocontrol alternatives.
- Polyethylene tube dispenser bundling:Saudi date plantation operators are consolidating season-long procurement contracts for modular dispenser systems, reducing per-hectare application labor by eliminating repeat field visits.
Market Restraints
- Petrochemical input volatility:Polyethylene and polymer-matrix raw material costs fluctuate with Gulf petrochemical feedstock pricing, compressing formulation margins for controlled-release dispensers.
- Registration timeline fragmentation:Divergent efficacy labeling requirements across Saudi Arabia, the UAE, and Oman force multinational distributors to maintain parallel compliance dossiers, extending product launch cycles.
- Conventional spraying substitution inertia:Smallholder vegetable cooperatives in Morocco and Tunisia retain calendar-spray habits due to lower upfront capital requirements and established extension-agent relationships.
Strategic Opportunities
- Israeli-Jordanian stone-fruit corridor:Untapped pheromone penetration in northern Israel and Jordan Valley orchards offers expansion potential as regional distribution hubs mature.
- Online agritech platform integration:Israeli farm-input e-commerce portals and South African digital procurement channels are reducing extension-agent dependence for pheromone ordering and timing guidance.
- Organic buffer zone mandates:Israel's Plant Protection and Inspection Services now requires pheromone-treated perimeters near certified organic operations, creating mandated demand for dispenser placement services.
Industry Challenges
- Semiochemical formulation expertise scarcity:Regional universities produce limited synthetic chemists trained in insect signaling molecule replication, constraining local R&D capacity.
- Climate-adapted release rate calibration:Desert temperature extremes in Gulf Cooperation Council states degrade dispenser performance predictability, requiring accelerated field validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Agricultural Pheromones Market |
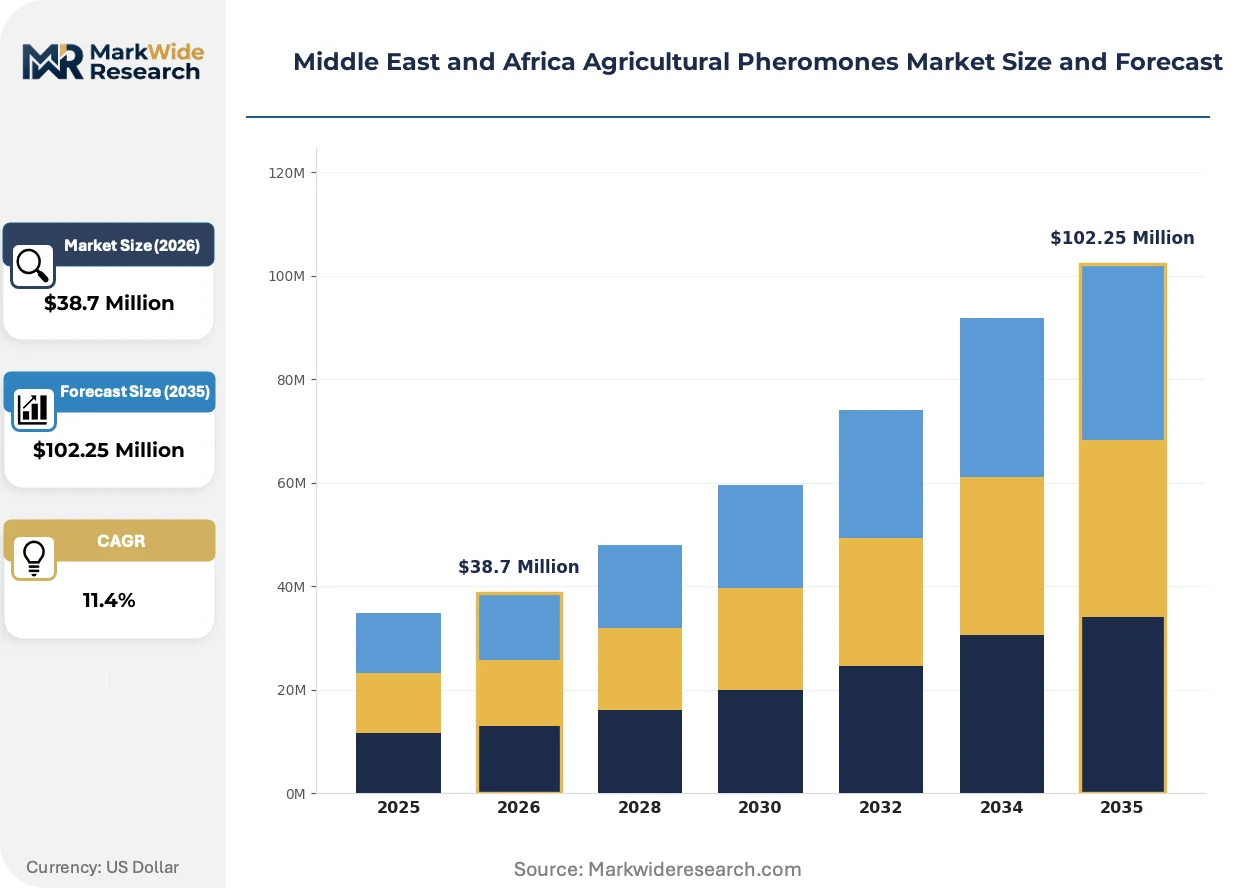
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
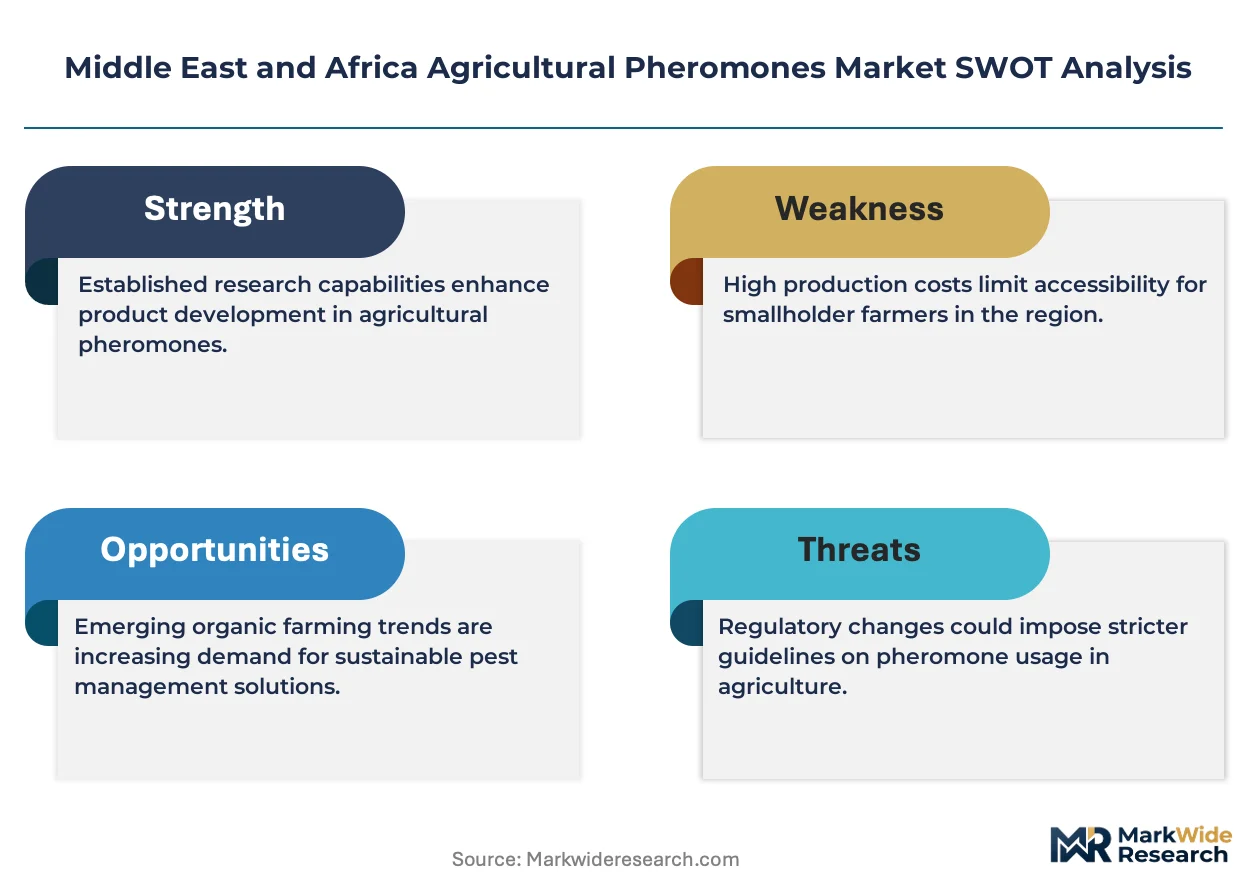
| Segmentation | Product Type: Insect Pheromones, Mating Disruption, Monitoring Traps, Attractants Application: Crop Protection, Pest Management, Soil Improvement, Pollination Enhancement End Use Industry: Agriculture, Horticulture, Forestry, Organic Farming Distribution Channel: Online Stores, Distributors, Retail Outlets, Direct Sales |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., BASF SE, Suterra LLC, Russell IPM Ltd., Provivi, Inc., ISCA Technologies, Koppert Biological Systems, Biobest Group NV, Bedoukian Research, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Agricultural Pheromones Market Shifts & Advancements
Precision pest suppression technologies are converging with digital agriculture platforms across Middle East and Africa horticulture, compressing the gap between biological intervention and data-driven timing optimization.
Controlled-release polymer-matrix dispensers are integrating IoT-enabled field monitoring systems. Israeli citrus estate managers now deploy sensor networks alongside membrane laminates to verify mating disruption coverage. This convergence is integrating real-time efficacy measurement into procurement specifications, shifting supplier selection criteria toward telemetry compatibility.
South Africa's Department of Agriculture enforces residue monitoring schedules aligned with EU MRL frameworks. Citrus and table-grape exporters must maintain biocontrol verification documentation for port-of-entry inspection. Egyptian export grape operations are responding by embedding pheromone protocols into integrated pest management certification audits.
Season-long bundled dispenser systems are displacing single-application purchases across Saudi date plantations and South African citrus estates. Procurement managers now specify milligram-per-hectare dosing contracts with performance guarantees. This preference compression is most visible in the Nile Delta horticulture belt, where export-oriented producers face synchronized EU phytosanitary entry requirements.
Middle East and Africa Agricultural Pheromones Market Segmentation
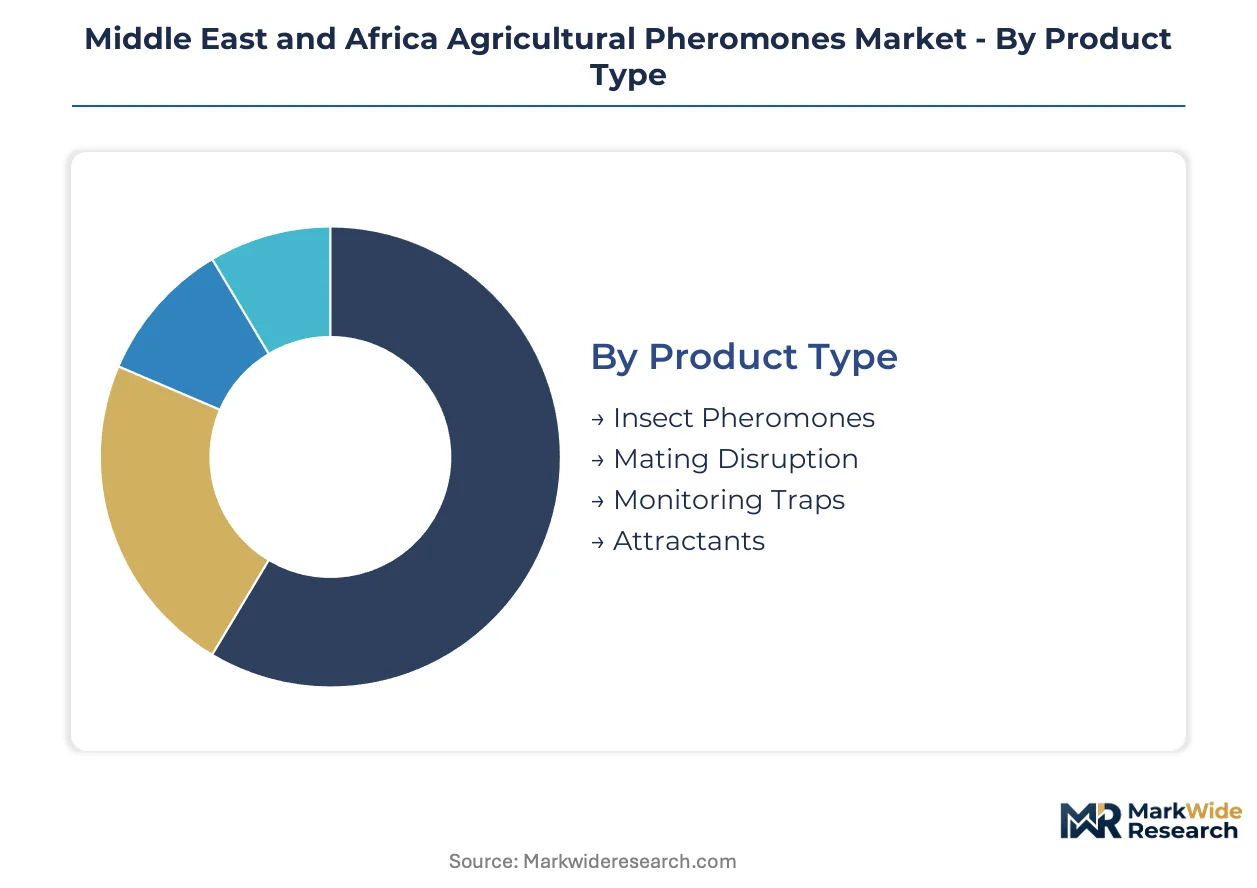
Pheromone deployment patterns across Middle East and Africa horticulture diverge sharply between standalone mating disruption systems and integrated monitoring networks. Segmentation clarity enables suppliers to match formulation release rates with specific crop protection protocols and distribution channel capabilities.
Product Type:
Standalone pheromone systems dominate Saudi date plantations, while integrated monitoring-trap networks serve Egyptian export grape operations requiring real-time pest density verification.
- Mating Disruption:Polyethylene tube dispensers release synthetic sex pheromones at controlled rates to confuse male insect location of females. Saudi date plantation operators in Al-Qassim and Al-Ahsa governorates specify season-long bundled contracts to eliminate repeat field visits during peak summer temperatures.
- Monitoring Traps:Sticky-board or bucket traps baited with species-specific aggregation pheromones enable population threshold monitoring. Egyptian Nile Delta grape exporters deploy these near packing houses to generate EU phytosanitary inspection documentation.
- Insect Pheromones:General-class signaling molecule formulations target lepidopteran and coleopteran pests across South African citrus estates.
- Attractants:Food-based kairomone blends supplement sex pheromones in Israeli stone-fruit orchards for multi-species capture.
Mating Disruption leads volumes today; Monitoring Traps is gaining share fastest.
Application:
Cost-tier segmentation separates premium biocontrol verification systems from baseline pest suppression for domestic-market producers.
- Crop Protection:Field-scale pheromone deployment integrates with integrated pest management protocols to displace calendar spraying. South African table-grape exporters in the Western Cape maintain biocontrol verification documentation for EU port-of-entry inspection compliance.
- Pest Management:Targeted mating disruption and mass-trapping programs address specific invasive species. Egypt's Agricultural Pesticide Committee mandates pheromone-based red palm weevil management in Ismailia and Damietta governorate date cooperatives.
- Soil Improvement:Nematode pheromone applications remain experimental across Moroccan vegetable cooperatives.
- Pollination Enhancement:Honeybee aggregation pheromone dispensers support Israeli almond orchard yields during flowering windows.
Crop Protection commands the premium tier; Pest Management shows steepest expansion trajectory.
End Use Industry:
Customer-type segmentation distinguishes export-oriented certification-driven demand from domestic-market price-sensitive procurement.
- Agriculture:Broad-acre field crops including wheat and maize utilize pheromone monitoring for stem-borer management. Moroccan smallholder cooperatives in the Souss-Massa region favor cost-engineered trap formats over controlled-release dispensers.
- Horticulture:High-value fruit and vegetable operations require residue-free pest suppression for EU market access. Jordan Valley date and citrus producers face Israeli Plant Protection and Inspection Services buffer zone mandates near organic-certified farms.
- Forestry:Pine processionary moth monitoring in Morocco's Middle Atlas cedar forests uses low-density trap networks.
- Organic Farming:Certified operations mandate pheromone-treated perimeters to prevent conventional pesticide drift contamination.
Horticulture leads volumes today; Organic Farming is climbing the fastest.
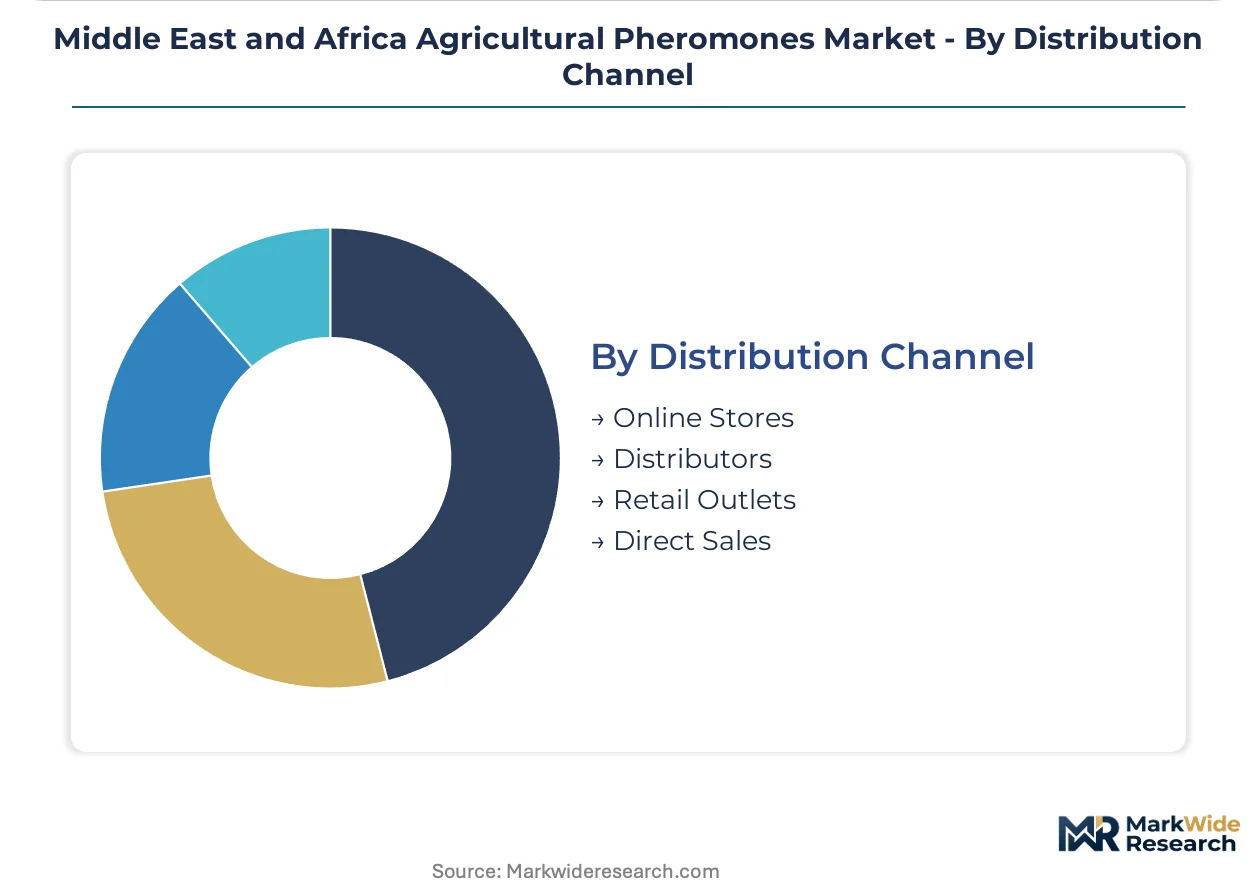
Distribution Channel:
Supply concentration patterns favor distributor-led technical support for complex dispenser calibration, while digital platforms capture repeat reordering.
- Online Stores:Israeli agritech platforms and South African farm-input e-commerce portals reduce extension-agent dependence for pheromone ordering and timing guidance. Real-time weather integration enables precise application window recommendations.
- Distributors:Regional stocking points in Dubai and Johannesburg provide technical field support for dispenser placement protocols. Suterra LLC anchors Middle East supply through its Dubai hub serving Israeli and Jordanian stone-fruit orchards.
- Retail Outlets:Moroccan and Tunisian agricultural cooperatives source monitoring traps through local farm supply stores.
- Direct Sales:Large Saudi date plantation operators negotiate milligram-per-hectare dosing contracts directly with formulation manufacturers.
Distributors lead volumes today; Online Stores is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli research institutions pioneered semiochemical synthesis for agricultural applications during the 1980s, establishing technical foundations that now diffuse across Middle East and Africa horticulture operations. Regional demand clusters around export-oriented producers facing EU phytosanitary compliance pressures.
Saudi Arabia
Date palm plantations in Al-Qassim and Al-Ahsa governorates drive dispenser procurement volumes, with growers specifying season-long bundled systems to reduce summer field labor. The Ministry of Environment, Water and Agriculture promotes integrated pest management protocols through extension programs. Riyadh-based procurement offices negotiate direct milligram-per-hectare dosing contracts with formulation suppliers.
South Africa
Western Cape table-grape and citrus exporters maintain biocontrol verification documentation for EU port-of-entry inspections. The Department of Agriculture, Land Reform and Rural Development enforces residue limits aligned with EU MRL schedules. Stellenbosch and Paarl estate managers embed pheromone protocols into integrated pest management certification audits.
Egypt
Nile Delta grape and citrus producers face synchronized EU phytosanitary entry requirements, concentrating demand in export-oriented cooperatives. The Agricultural Pesticide Committee accelerated temporary biocontrol approvals for red palm weevil management in Ismailia and Damietta governorates. Alexandria-based packing houses deploy monitoring traps near export facilities to generate inspection documentation.
Israel
Stone-fruit orchards in the Jordan Valley and northern growing regions require pheromone-treated buffer zones near organic-certified farms. The Plant Protection and Inspection Services mandates dispenser placement protocols through direct regulation. Tel Aviv agritech platforms reduce extension-agent dependence by integrating real-time weather data into application timing recommendations.
United Arab Emirates
Date palm operations in Abu Dhabi and Al Ain expand mating disruption coverage as red palm weevil infestations threaten heritage groves. The Ministry of Climate Change and Environment coordinates with Gulf standardization bodies on efficacy labeling harmonization. Dubai distribution hubs serve as regional supply anchors for Israeli and Jordanian orchard operations.
Middle East and Africa Agricultural Pheromones Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and controlled-release calibration capabilities. The vendor base stratifies into three tiers: multinational chemical conglomerates with polymer-matrix expertise, specialized semiochemical manufacturers with regional distribution infrastructure, and cost-engineered trap suppliers serving smallholder cooperatives. Dominant competitive moves include backward integration into captive polymer supply and technology licensing partnerships with Israeli agritech platforms.
Within the multinational tier, BASF SE and Shin-Etsu Chemical Co., Ltd. represent premium-positioned formulation capabilities. Suterra LLC anchors Middle East supply chain presence through its Dubai distribution hub. Among specialized regional operators, Russell IPM Ltd. occupies a cost-engineered position serving Moroccan and Tunisian vegetable cooperatives.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| BASF SE |
| Suterra LLC |
| Russell IPM Ltd. |
| Provivi, Inc. |
| ISCA Technologies |
| Koppert Biological Systems |
| Biobest Group NV |
| Bedoukian Research, Inc. |
| Others |
Supply & Pricing Matrix
Polymer-matrix formulation sophistication separates premium controlled-release dispensers from commodity polyethylene tube alternatives, with this bifurcation driving divergent procurement patterns across Saudi date plantations and Moroccan smallholder cooperatives. BASF SE and Shin-Etsu Chemical Co. command formulation premiums through captive polymer expertise, while Russell IPM Ltd. competes on cost-engineered trap formats that sacrifice release-rate precision for upfront affordability.
Pricing Analysis
Milligram-per-hectare dosing contracts with performance guarantees dominate Saudi and South African procurement, with pricing stratifies across premium controlled-release formulations, standard bundled dispenser systems, and economy monitoring traps. Price differentiation rests on polymer-matrix calibration precision and season-long efficacy documentation. Cost compression in economy tiers is intensifying because Moroccan and Tunisian vegetable cooperatives prioritize upfront capital minimization over lifecycle performance. Export-oriented Egyptian grape producers show least price sensitivity due to EU phytosanitary compliance premiums.
Supply Chain Analysis
Single-source vulnerability sits with Gulf petrochemical feedstock suppliers for polyethylene raw materials, forcing formulation margins to fluctuate with regional hydrocarbon pricing. Manufacturing concentration centers on Germany, Japan, and the United States for advanced polymer-matrix synthesis, while China and India supply baseline dispenser components. Supply chain risk manifests as tariff exposure on Israeli-Jordanian corridor shipments through Dubai distribution hubs. Distribution runs through Suterra LLC's Dubai hub for regional technical support, supplemented by direct manufacturer relationships with large Saudi plantation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Egyptian and South African export horticulture operators shift procurement toward biocontrol verification systems with documented residue compliance.
For Market Incumbents: Hedge against polyethylene feedstock volatility through backward integration into captive polymer supply or long-term offtake agreements with Gulf petrochemical producers. Defensive consolidation should prioritize acquisition of Israeli agritech platforms with IoT-enabled dispenser monitoring capabilities to preserve premium positioning against telemetry-integrated entrants. For New Entrants and Emerging Players: Digital platform integration with real-time weather data offers a technology-first wedge into Israeli and South African online agritech procurement channels. White-space targets include untapped Jordan Valley stone-fruit orchards and Egyptian Nile Delta cooperatives transitioning from calendar spraying. Go-to-market execution should emphasize extension-agent-independent ordering systems with automated application timing guidance. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized semiochemical manufacturers possessing regional distribution infrastructure and temporary biocontrol approval relationships with Egypt's Agricultural Pesticide Committee. Long-term viability favors targets with demonstrated efficacy data under desert temperature extremes. Watch for harmonization of Gulf standardization body labeling requirements as inflection signal for procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive raw material sourcing insulates BASF SE and Shin-Etsu Chemical Co. from Gulf petrochemical price volatility. |
| IoT-Enabled Dispenser Monitoring | Israeli citrus estate sensor networks verify mating disruption coverage and shift procurement toward telemetry-compatible suppliers. |
| Temporary Biocontrol Approval Expansion | Egypt's Agricultural Pesticide Committee accelerated red palm weevil pheromone approvals, creating immediate demand pull from date cooperatives. |
| Online Agritech Platform Partnerships | Israeli and South African farm-input e-commerce portals reduce extension-agent dependence for pheromone ordering guidance. |
| Regional Distribution Hub Establishment | Suterra LLC's Dubai hub anchors Middle East supply chain presence for Israeli and Jordanian stone-fruit orchard operations. |
Research Methodology
Multiple input streams — primary interviews with formulation chemists, plantation procurement managers, and regulatory affairs specialists at Egypt's Agricultural Pesticide Committee and South Africa's Department of Agriculture — were reconciled against secondary validation from EU MRL compliance databases, customs import records for polyethylene raw materials, and Gulf standardization body efficacy labeling drafts. Bottom-up demand modeling across Saudi date plantations, Egyptian export grape operations, and South African citrus estates was cross-checked against top-down market sizing from regional biocontrol verification documentation trends.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type (mating disruption, monitoring traps, attractants), application (crop protection, pest management), and distribution channel (online stores, distributors, direct sales). CAGRs were derived from installed base growth in dispenser systems and replacement cycle analysis for season-long bundled contracts. Industry-specific forecast inputs included EU phytosanitary inspection volume trends and red palm weevil infestation spread patterns across Gulf Cooperation Council date plantations.
The model holds under sustained EU MRL enforcement and temporary biocontrol approval continuity; deviation in Gulf petrochemical feedstock pricing or harmonization timeline delays would shift volume trajectories. Forecasts reflect documented assumptions regarding extension-agent displacement rates and online platform penetration curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Neem Extract Market