
 Asia Pacific Electric Three-Wheelers Market | 2026-2036
Asia Pacific Electric Three-Wheelers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Three-Wheelers Market Analytics
India's PLI scheme for automotive manufacturing is rebalancing the cost-of-entry calculus for electric three-wheeler producers, favoring domestic battery pack and powertrain assembly. Mahindra & Mahindra Ltd. leverages its established rural dealership network to push passenger e-rickshaws into semi-urban catchments. Bajaj Auto Ltd. anchors its position through captive production of lithium-ion compatible chassis platforms. Piaggio & C. SpA competes on European-derived design standards adapted for Asian road conditions.
Asia Pacific electric three-wheelers are battery-powered, three-wheeled commercial vehicles typically rated between 1,000–2,000 kg gross vehicle weight, employing hub-mounted or mid-drive electric motors with regenerative braking systems for urban freight and passenger haulage. Passenger configurations dominate unit volumes across Bangladesh, India, and Nepal, while cargo variants command higher per-unit margins due to fleet procurement contracts from e-commerce logistics providers. Lithium-ion power sources are displacing lead-acid alternatives where total cost of ownership calculations include battery replacement cycles and residual value recovery.
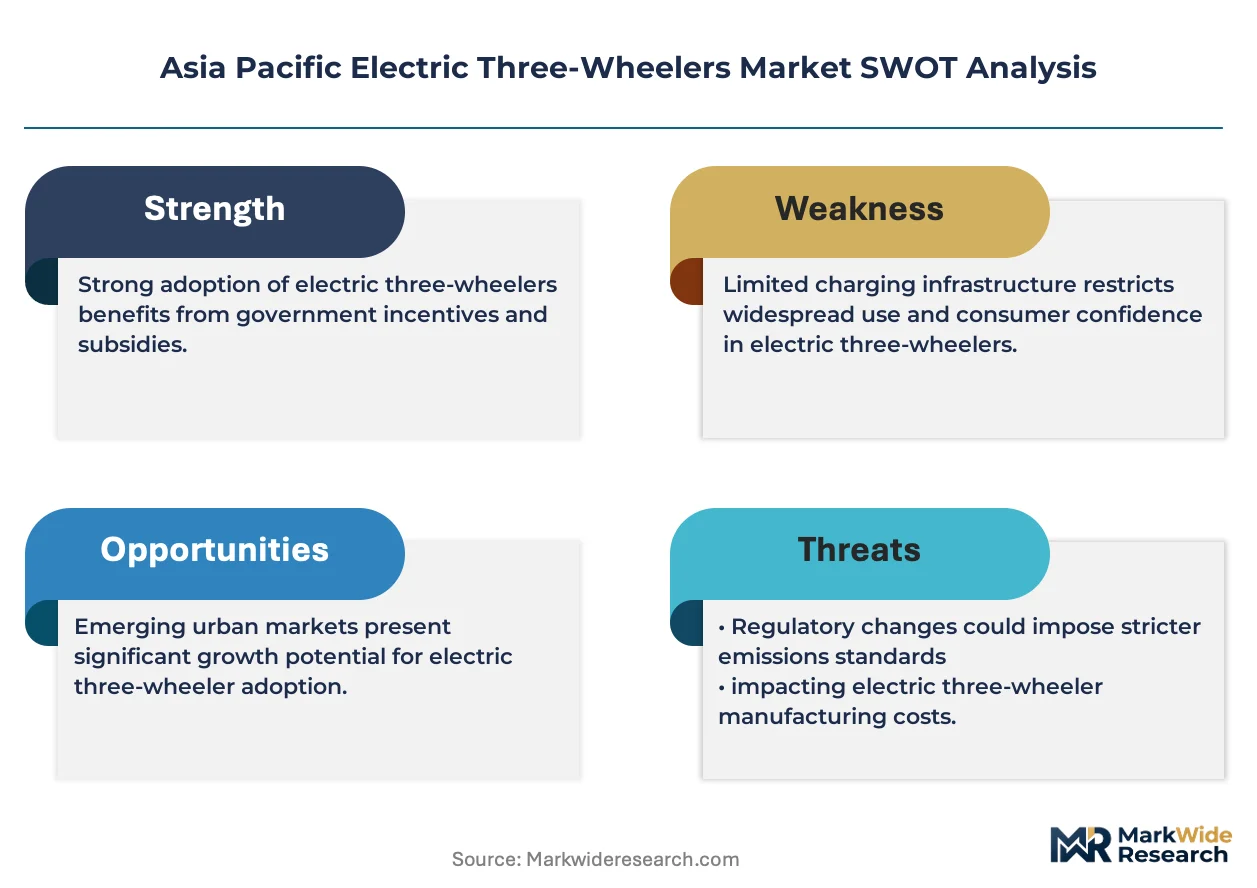
India's BIS certification mandates and CEA technical standards for battery swapping interoperability shape product design requirements for manufacturers selling across multiple Indian states. Bangladesh's energy regulator and Thailand's industrial standards body impose parallel but non-harmonized safety protocols that fragment compliance costs for regional assemblers. Stakeholders must monitor how subsidy taper schedules and battery mineral supply agreements interact to determine viable production scale points.
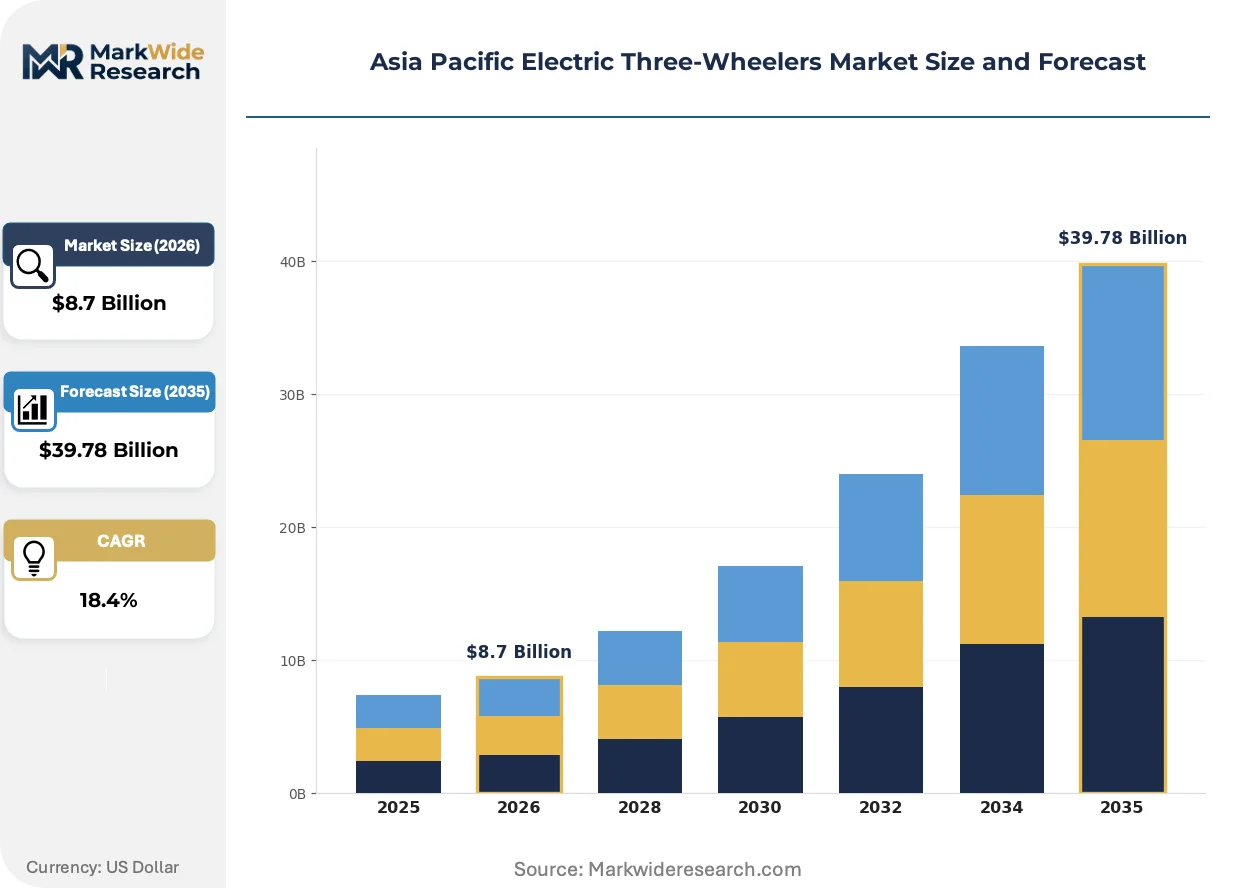
Market Dynamics
India's PLI scheme for automotive manufacturing is compressing payback periods for fleet operators while Bangladesh's tightening emissions norms accelerate diesel displacement. This regulatory momentum concentrates investment around domestic battery pack assembly and powertrain localization.
Growth Catalysts
- India's PLI scheme for automotive manufacturing:Production-linked incentives favor domestic battery pack and powertrain assembly, lowering cost-of-entry for regional assemblers.
- Last-mile logistics fleets:E-commerce logistics providers across India and Southeast Asia are replacing diesel counterparts with electric cargo variants at accelerating pace.
- Hub-mounted electric motors:Regenerative braking systems paired with hub-mounted configurations reduce maintenance cycles and improve urban freight efficiency.
Market Restraints
- Lithium-ion mineral supply concentration:Battery mineral supply agreements concentrate around limited geographies, creating input cost volatility for regional assemblers.
- Non-harmonized safety protocols:Bangladesh's energy regulator and Thailand's industrial standards body impose parallel but incompatible certification requirements.
- Lead-acid residual value recovery:Legacy lead-acid power sources retain price advantage in total cost calculations where battery replacement cycles dominate.
Strategic Opportunities
- Tier-2 and tier-3 Indian cities:Charging infrastructure gaps are narrowing fastest in semi-urban catchments, creating first-mover positioning for passenger e-rickshaw deployment.
- Battery swapping interoperability:India's CEA technical standards for battery swapping create regulatory tailwind for modular powertrain business models.
- European-derived design standards:Adaptation of crash-tested chassis platforms for Asian road conditions opens premium positioning in safety-conscious fleet procurement.
Industry Challenges
- BIS certification timeline compression:India's BIS certification mandates for multi-state sales create compliance bottlenecks for assemblers without established testing partnerships.
- Power electronics skill scarcity:Hub-mounted and mid-drive motor integration requires specialized technicians absent in traditional internal combustion service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Three-Wheelers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger, Cargo, Utility, Entertainment End User: Ride-Sharing, Logistics, Personal Use, Commercial Power Source: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Others Design: Compact, Mid-Size, Full-Size, Custom |
| Companies Covered | Mahindra & Mahindra Ltd., Bajaj Auto Ltd., Piaggio & C. SpA, Atul Auto Ltd., Hero Electric, Kinetic Engineering Ltd., Lohia Auto Industries, YC Electric, Saera Electric Auto Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Three-Wheelers Market Evolving Landscape
Product architecture is converging around modular battery platforms while regulatory pressure on emissions intensifies procurement specification changes. Fleet operators now prioritize total cost of ownership calculations over upfront capital outlay.
Modular battery swapping systems are unifying fleet operator economics across passenger and cargo configurations. Logistics providers in India's tier-2 cities are adopting standardized 2.5 kWh swap packs at scale. This interoperability is compressing downtime costs and enabling asset-light fleet expansion without captive charging infrastructure.
India's CEA technical standards for battery swapping interoperability are mandating connector and communication protocol uniformity across state boundaries. Manufacturers must redesign battery management systems to comply with multi-state certification requirements. Cargo variant producers targeting e-commerce logistics contracts face the steepest redesign timelines.
Fleet procurement is consolidating around residual value guarantees and battery lifecycle contracts rather than outright purchase. Third-party fleet management providers in Bangladesh and Nepal are offering powertrain-as-a-service models. This shift is most visible among e-commerce logistics providers operating high-utilization routes in dense urban corridors.
Asia Pacific Electric Three-Wheelers Market Segmentation
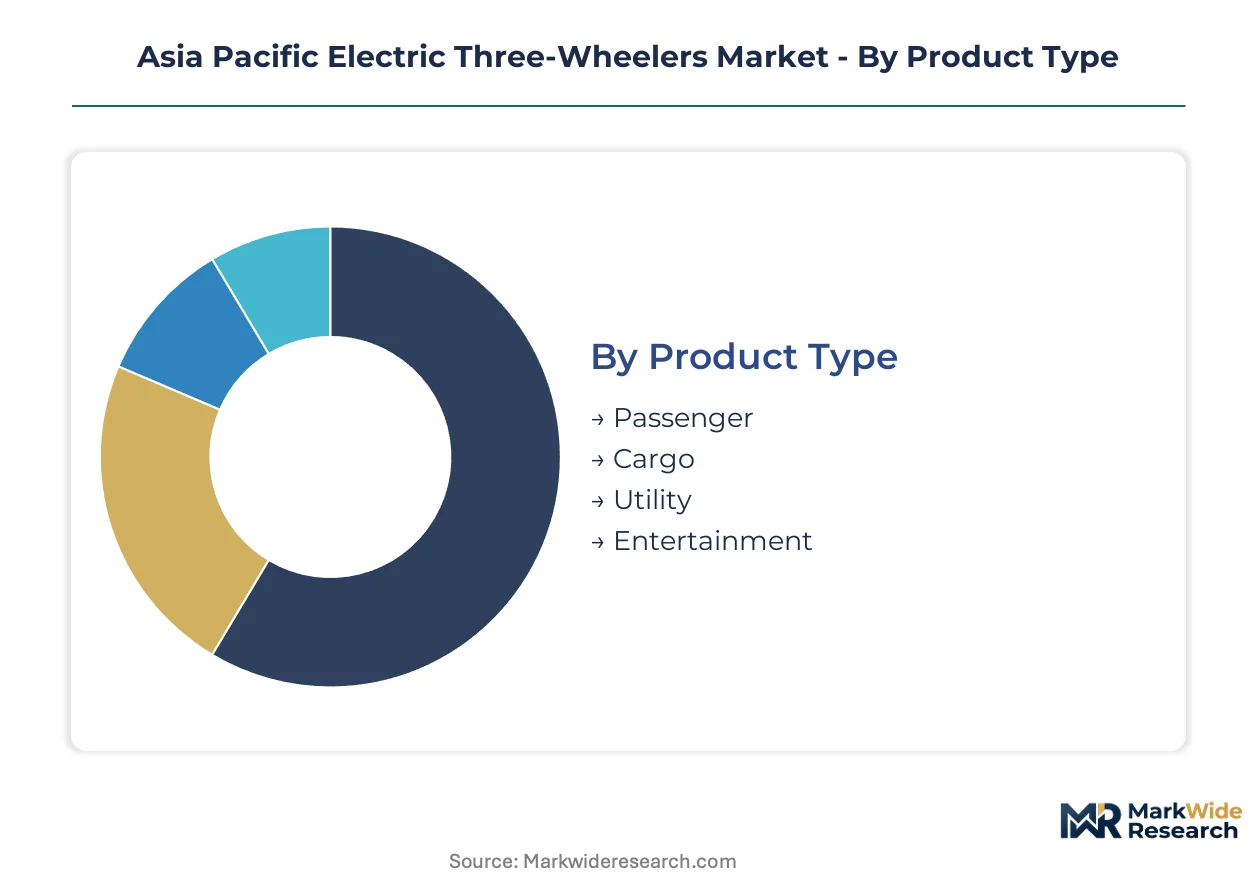
Electric three-wheeler purchasing decisions split sharply between passenger haulage economics and cargo fleet specifications. Battery chemistry choices and chassis sizing further fragment procurement patterns across India's tier-2 cities and Bangladesh's urban corridors.
Product Type:
Hub-mounted motor configurations and gross vehicle weight ratings define functional boundaries between urban mobility and freight applications.
- Passenger:Configurations rated for 4-6 occupants with weather protection canopies dominate unit volumes across Bangladesh, India, and Nepal. BIS certification requirements for multi-state sales compress design timelines for assemblers targeting semi-urban catchments.
- Cargo:Flatbed and enclosed-box variants rated 1,000-2,000 kg GVW command premium positioning through fleet procurement contracts from e-commerce logistics providers. India's PLI scheme for automotive manufacturing favors domestic chassis assembly for this segment.
- Utility:Convertible passenger-cargo platforms serve mixed-use operators in tier-3 Indian markets where vehicle utilization rates fluctuate seasonally.
- Entertainment:Open-air sightseeing configurations with enhanced lighting and audio systems target tourism clusters in Thailand and Vietnam.
Passenger configurations lead on scale; cargo variants lead on momentum through logistics fleet electrification.
End User:
Customer procurement sophistication varies from individual owner-operators to centralized fleet managers with total cost of ownership modeling capabilities.
- Ride-Sharing:Aggregator-affiliated drivers in Delhi, Dhaka, and Bangkok prioritize battery swapping compatibility to minimize downtime between fares. CEA technical standards for interoperability reduce asset stranding risk.
- Logistics:Last-mile delivery contractors for regional e-commerce platforms specify regenerative braking and telematics integration. Bangladesh's tightening emissions norms accelerate diesel displacement in this user category.
- Personal Use:Individual owners in tier-2 Indian cities select lead-acid configurations where upfront capital constraints dominate purchasing calculus.
- Commercial:Small fleet proprietors operating 5-15 vehicles across multiple routes favor modular battery platforms for operational flexibility.
Logistics users are expanding most quickly; personal use retains volume concentration.
Power Source:
Battery chemistry selection determines replacement cycle economics and residual value recovery trajectories for asset owners.
- Lithium-Ion:Energy density advantages enable extended range for hub-mounted motor configurations serving high-utilization routes. Mineral supply agreement concentration creates input cost volatility for regional assemblers.
- Lead-Acid:Established recycling infrastructure and lower acquisition costs sustain penetration where battery replacement cycles dominate total cost calculations.
- Nickel-Metal Hydride:Thermal stability characteristics suit tropical operating conditions in Southeast Asian climates with limited active battery management.
- Others:Emerging sodium-ion and solid-state prototypes target fleet operator trials in India's automotive manufacturing corridors.
Lithium-ion leads on technology transition; lead-acid retains installed base scale.
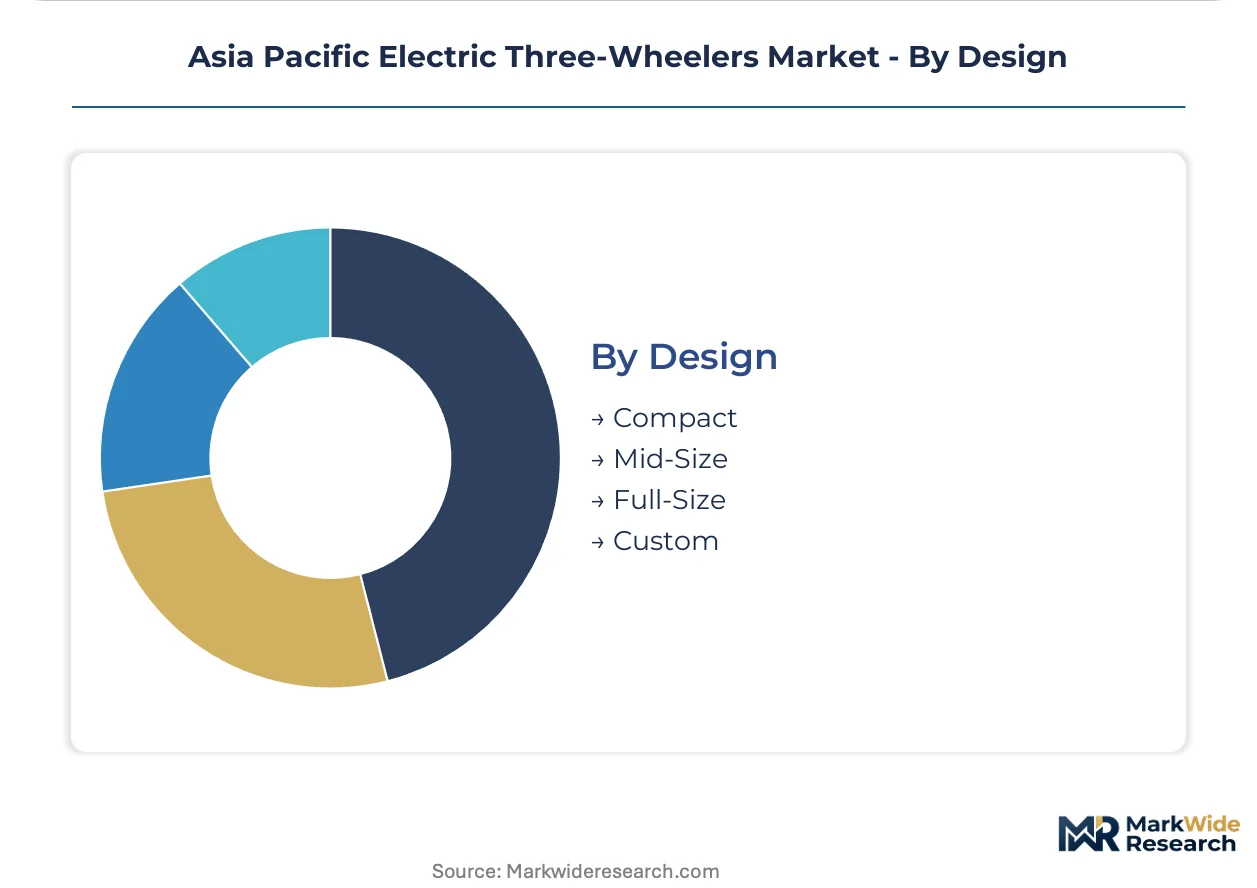
Design:
Chassis dimensional categories align with road width constraints and parking availability across dense urban versus semi-urban operating environments.
- Compact:Sub-2.5 meter lengths navigate narrow lanes in Old Dhaka and Varanasi's historic districts where turning radius constraints dominate.
- Mid-Size:Balanced wheelbase configurations serve as the default specification for Indian tier-2 city operators.
- Full-Size:Extended cargo beds and reinforced suspension systems target e-commerce logistics providers with standardized pallet loading requirements.
- Custom:Specialized refrigerated or hazardous-material configurations serve niche pharmaceutical and chemical transport contracts.
Mid-size designs lead on volume ubiquity; compact configurations gain share fastest through urban densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled assembly workforces in India's automotive corridors and Bangladesh's emerging industrial zones anchor regional production capacity. Vietnam's electronics manufacturing clusters and Thailand's component supplier networks feed into cross-border supply chains. Indonesia's nickel processing capabilities and the Philippines' mineral refining infrastructure complete the battery material ecosystem spanning the region.
India
Fleet electrification in tier-2 and tier-3 cities drives demand concentration alongside e-commerce logistics expansion. The PLI scheme for automotive manufacturing compresses payback periods for commercial operators. Manufacturing clusters in Maharashtra and Gujarat host domestic battery pack assembly lines serving multi-state distribution networks.
Bangladesh
Dhaka's dense urban corridors generate passenger configuration volumes while tightening emissions norms accelerate diesel displacement. The national energy regulator imposes safety protocols that shape product certification timelines. Industrial zones around Chittagong attract regional assemblers targeting export-adjacent production.
Thailand
Bangkok's last-mile delivery networks specify telematics-integrated cargo variants for high-utilization routes. The industrial standards body maintains certification requirements that fragment compliance costs for foreign entrants. Eastern Economic Corridor manufacturing hubs concentrate power electronics component suppliers.
Vietnam
Hanoi and Ho Chi Minh City tourism clusters sustain entertainment configuration demand with enhanced lighting specifications. Electronics manufacturing capabilities in northern provinces support battery management system assembly. Provincial industrial parks attract joint ventures targeting ASEAN market access.
Indonesia
Jakarta's urban freight corridors drive cargo variant procurement from logistics providers with standardized pallet requirements. Nickel processing infrastructure in Sulawesi and Maluku feeds regional battery material supply chains. Surabaya manufacturing zones host emerging assembly operations for domestic market distribution.
Asia Pacific Electric Three-Wheelers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across passenger and cargo configuration segments. Market structure tilts toward consolidation among established automotive manufacturers with captive distribution networks, while regional assemblers fragment across price-sensitive tiers. Three archetypes dominate: legacy two-wheeler diversifiers, dedicated electric commercial vehicle startups, and European design-origin transplants. Competitive moves center on domestic battery pack localization partnerships and multi-state certification pre-positioning ahead of subsidy taper schedules.
Among India-based conglomerates, Mahindra & Mahindra Ltd. and Bajaj Auto Ltd. exemplify legacy automotive diversifiers leveraging established rural dealership infrastructure. Piaggio & C. SpA represents European design-origin positioning adapted for regional road conditions. These three anchors illustrate divergent strategic postures: domestic manufacturing scale, captive component production, and imported design standards respectively.
| Leading Market Players |
|---|
| Mahindra & Mahindra Ltd. |
| Bajaj Auto Ltd. |
| Piaggio & C. SpA |
| Atul Auto Ltd. |
| Hero Electric |
| Kinetic Engineering Ltd. |
| Lohia Auto Industries |
| YC Electric |
| Saera Electric Auto Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
E-commerce logistics providers with centralized fleet procurement now dominate volume contracting, compressing margins through powertrain-as-a-service bundling that separates hardware from energy costs. This buyer concentration shifts pricing power toward operators with residual value guarantee capabilities.
Pricing Analysis
Bundled battery lifecycle contracts now compete against unbundled upfront purchase models across fleet segments. Three-tier pricing structure across premium lithium-ion, standard lead-acid, and economy refurbished configurations reflects BIS certification tier and telematics integration depth. Pricing pressure stems from subsidy taper schedules accelerating pre-buying behavior. Individual owner-operators in tier-3 Indian markets exhibit highest price sensitivity; logistics fleet managers prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
Skilled technician shortages in Maharashtra and Gujarat assembly corridors constrain power electronics integration throughput. Battery cell supply concentrates in China, South Korea, and domestic Indian pack assembly operations. Nickel and cobalt feedstocks draw from Indonesia's processing infrastructure and Philippine refining operations. Single-source vulnerability in lithium carbonate refining creates input cost volatility. Distribution runs through state-level dealership networks with multi-state certification pre-positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation signals a late-cycle quality transition as logistics operators specify crash-tested chassis and telematics-integrated powertrains over bare-metal configurations.
For Market Incumbents: To counter dedicated electric commercial vehicle startups with asset-light battery swapping models, legacy manufacturers should deepen captive lithium-ion cell sourcing through joint ventures with Indonesian nickel processors and accelerate BIS certification pre-positioning across Maharashtra, Gujarat, and Tamil Nadu distribution networks. For New Entrants and Emerging Players: Enter via Bangladesh's tightening emissions compliance window where diesel displacement creates fleet replacement demand absent entrenched incumbent service infrastructure. Target Dhaka-Chittagong logistics corridors with hub-mounted motor cargo variants certified to the national energy regulator's safety protocols. Lead with powertrain-as-a-service pricing to bypass capital-constrained fleet operator acquisition barriers. For Investors and Strategic Acquirers: Diversified automotive conglomerates with captive battery pack assembly are the most active acquirer in this space, seeking modular platform capabilities. Long-term viability rests on residual value guarantee infrastructure and mineral supply agreement security. Signal to monitor: India's PLI scheme taper schedule and subsequent fleet operator pre-buying velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell access from Indonesian nickel processing corridors for domestic pack assembly. |
| Platform Standardization | Enables CEA-compliant battery swapping interoperability across state boundaries for fleet operators. |
| Backward Integration | Captures hub-mounted motor production in Gujarat automotive corridors to reduce import dependency. |
| Charging Infrastructure Partnership | Accelerates tier-2 and tier-3 city coverage gaps narrowing fastest for passenger e-rickshaw deployment. |
| Geographic Manufacturing Footprint | Positions Chittagong assembly operations to serve Bangladesh's diesel displacement regulatory momentum. |
Research Methodology
Direct dialogue with fleet procurement managers at e-commerce logistics providers, battery pack assembly plant managers in Maharashtra and Gujarat, BIS certification testing laboratory directors, and tier-2 city dealership operators grounded qualitative findings. Secondary validation drew from India's CEA technical standards publications, BIS certification registries, state-level electric vehicle policy documents, and automotive production databases. Bottom-up unit shipment estimates triangulated against top-down addressable fleet replacement calculations.
Segmented projections across passenger, cargo, and utility configurations incorporated power source chemistry transitions and gross vehicle weight class distributions throughout the forecast period. CAGRs derived from logistic curve adoption modeling calibrated to PLI scheme incentive trajectories and charging infrastructure build-out rates. Key inputs included fleet operator total cost of ownership sensitivity thresholds and battery mineral supply agreement concentration indices.
Inputs from regulatory filing databases and production facility surveys were available through the study window; gaps in real-time fleet utilization telemetry and informal sector owner-operator purchasing data introduce uncertainty bands around tier-3 city penetration assumptions. Forecasts embed assumptions regarding subsidy schedule continuity and nickel processing capacity expansion timelines. Material deviation in India's PLI taper velocity or Indonesian export restriction implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market