
 Belgium Solar E-Bike Market | 2026-2036
Belgium Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Solar E-Bike Market Insights
Aftermarket service revenue for solar panel maintenance and battery health diagnostics is fragmenting across regional bike shops and specialized e-mobility technicians. Veloci leverages its domestic assembly network to control spare parts distribution in Wallonia. Cowboy anchors premium direct-to-consumer positioning through proprietary app-integrated fleet management tools. Minerva competes on heritage brand recognition while extending service partnerships with Flemish cycling cooperatives.
A Belgium solar e-bike integrates photovoltaic cells into frame surfaces or detachable panels, converting sunlight into electrical energy stored in lithium-ion or solid-state battery packs to power pedal-assist motors typically rated between 250W and 500W for urban and touring applications. The product type dimension shows urban e-bikes occupying the dominant volume position due to last-mile delivery contracts, while folding e-bikes represent the fastest-growing structural category as apartment dwellers in Brussels and Ghent prioritize storage efficiency. Battery type segmentation reveals lithium-ion sustaining cost-competitive manufacturing, with solid-state configurations emerging as the high-margin technology frontier for premium positioning.
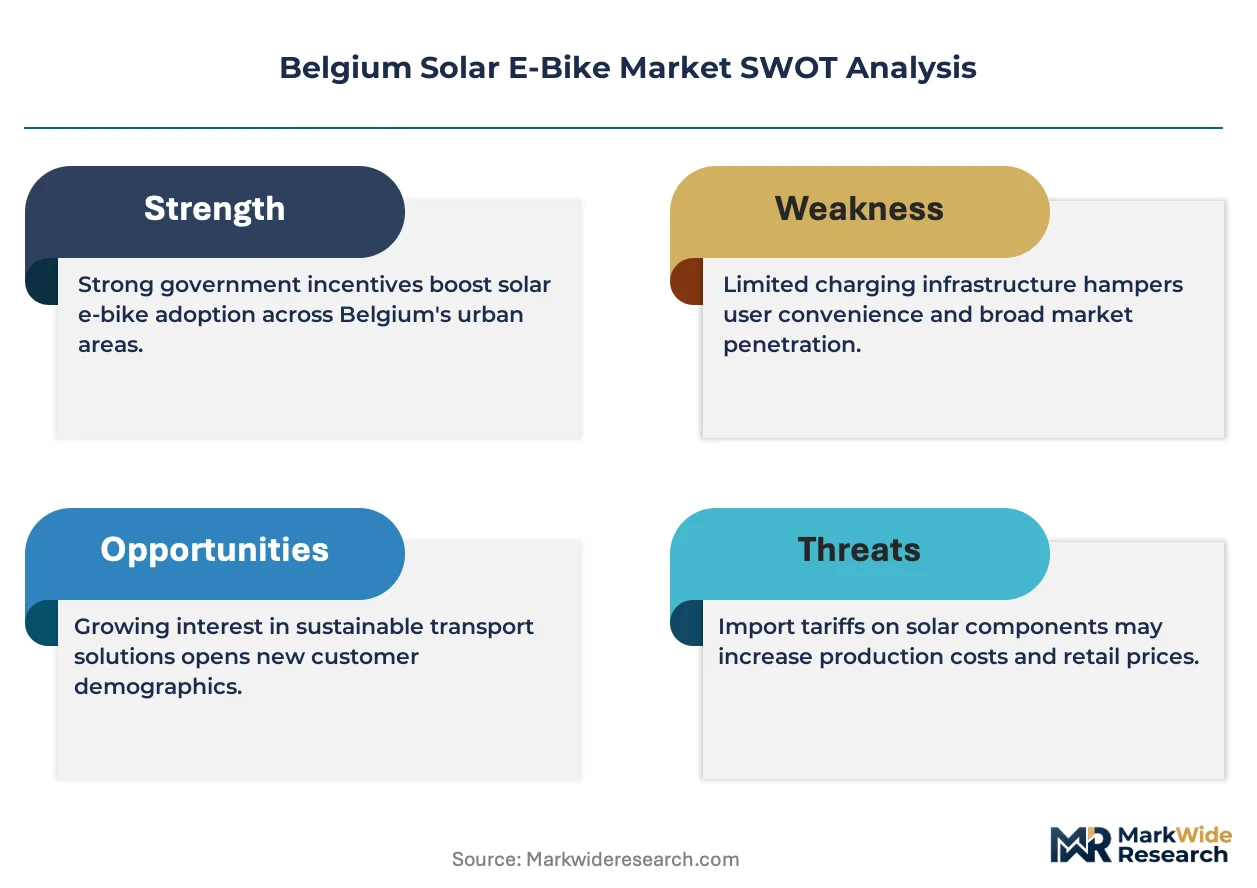
Flanders Region mobility subsidies, Belgium's federal tax deductibility framework for employer-provided bicycles, and EU Green Deal-aligned carbon accounting standards collectively shape procurement incentives and product certification requirements for solar e-bike vendors. The national regulator and regional transport authorities enforce CE marking compliance alongside emerging battery passport traceability obligations under EU Battery Regulation delegated acts. Stakeholders must monitor whether Brussels-Capital Region extends its current low-emission zone restrictions to cover light commercial pedal-assist vehicles, as this policy trajectory would restructure fleet buyer specifications and charging infrastructure deployment priorities.
Market Dynamics
Federal bicycle allowance reform and municipal zero-emission delivery mandates in Brussels and Antwerp are restructuring fleet procurement specifications toward photovoltaic-integrated frame designs.
Growth Catalysts
- EU Green Deal carbon accounting standards:Fleet operators in Brussels face mandatory Scope 3 emission disclosures that favor solar-assisted electric mobility over conventional e-bikes.
- Flanders Region mobility subsidies:Provincial cycling infrastructure density supports daily solar-assisted commuting across Ghent, Leuven, and Antwerp corridors.
- Photovoltaic integration in frame-integrated charging:Advances in flexible solar cell lamination enable continuous battery topping during daylight riding hours.
Market Restraints
- Lithium-ion raw material volatility:Cobalt and nickel price swings compress manufacturing margins for battery pack suppliers serving Belgian assemblers.
- Wallonia spare parts distribution concentration:Domestic assembly networks control aftermarket access, fragmenting service coverage in rural provinces.
- CE marking compliance complexity:Battery passport traceability obligations under EU Battery Regulation delegated acts extend certification timelines for new market entrants.
Strategic Opportunities
- Brussels-Capital low-emission zone expansion:Pending restrictions on light commercial pedal-assist vehicles would restructure fleet buyer specifications toward higher-capacity solar charging systems.
- Folding e-bike apartment storage demand:Urban dwellers in Ghent and Brussels prioritize compact photovoltaic configurations that detach for indoor parking.
- Flemish cycling cooperative service partnerships:Heritage brand extensions through cooperative maintenance networks unlock rural commuter segments outside major metropolitan zones.
Industry Challenges
- Solid-state battery manufacturing scale-up:High-margin technology frontier requires capital-intensive cleanroom production facilities absent from Belgian industrial base.
- Battery health diagnostic technician scarcity:Regional bike shops lack trained personnel for photovoltaic system troubleshooting and lithium-ion degradation assessment.
- Employer-provided bicycle tax deductibility documentation:Federal framework complexity creates administrative friction for HR departments administering fleet conversion programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Solar E-Bike Market |
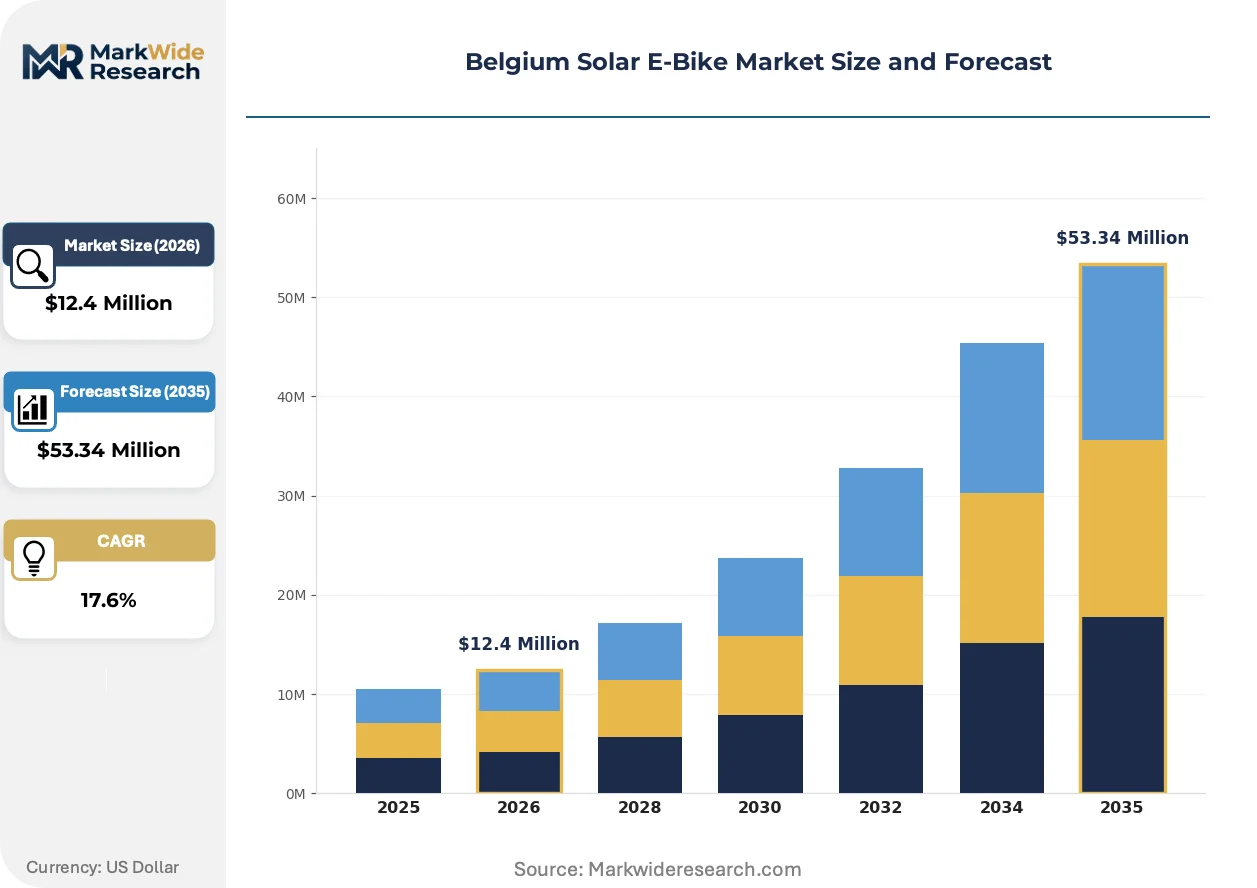
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $53.34 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urban E-Bikes, Mountain E-Bikes, Folding E-Bikes, Hybrid E-Bikes Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Solid-State Charging Method: Solar Charging, Grid Charging, Regenerative Braking, Home Charging User Demographic: Young Adults, Commuters, Tourists, Eco-Conscious Consumers |
| Companies Covered | Veloci, Venilu, Oxford, Minerva, Granville, Cowboy, Belgocycle, Bnewable, Ellio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Solar E-Bike Market Trends and Innovations
App-integrated fleet management tools and proprietary charging algorithms are compressing operational visibility gaps between vehicle telemetry and depot energy management systems.
Perovskite-enhanced photovoltaic cells laminated onto carbon fiber frame surfaces are digitizing real-time energy yield monitoring through embedded IoT sensors. Brussels-based courier fleets pilot these systems to optimize route planning around solar exposure patterns. The technology is digitizing dispatch coordination by feeding charge-state predictions directly into fleet management dashboards.
EU Battery Regulation delegated acts mandate battery passport traceability from cell manufacturing through end-of-life recycling. Belgian importers face accelerated documentation requirements for lithium-ion packs entering Flanders and Wallonia. Premium positioning segments absorb compliance costs through extended producer responsibility fees passed to fleet buyers.
Direct-to-consumer channel preference among urban commuters is displacing traditional bike shop intermediaries for initial purchase decisions. Cowboy and comparable vendors capture Brussels and Antwerp demand through subscription-style maintenance bundles. Flanders Region sees the fastest channel rotation as digital-native buyers prioritize app-based service scheduling over cooperative repair networks.
Belgium Solar E-Bike Market Segmentation
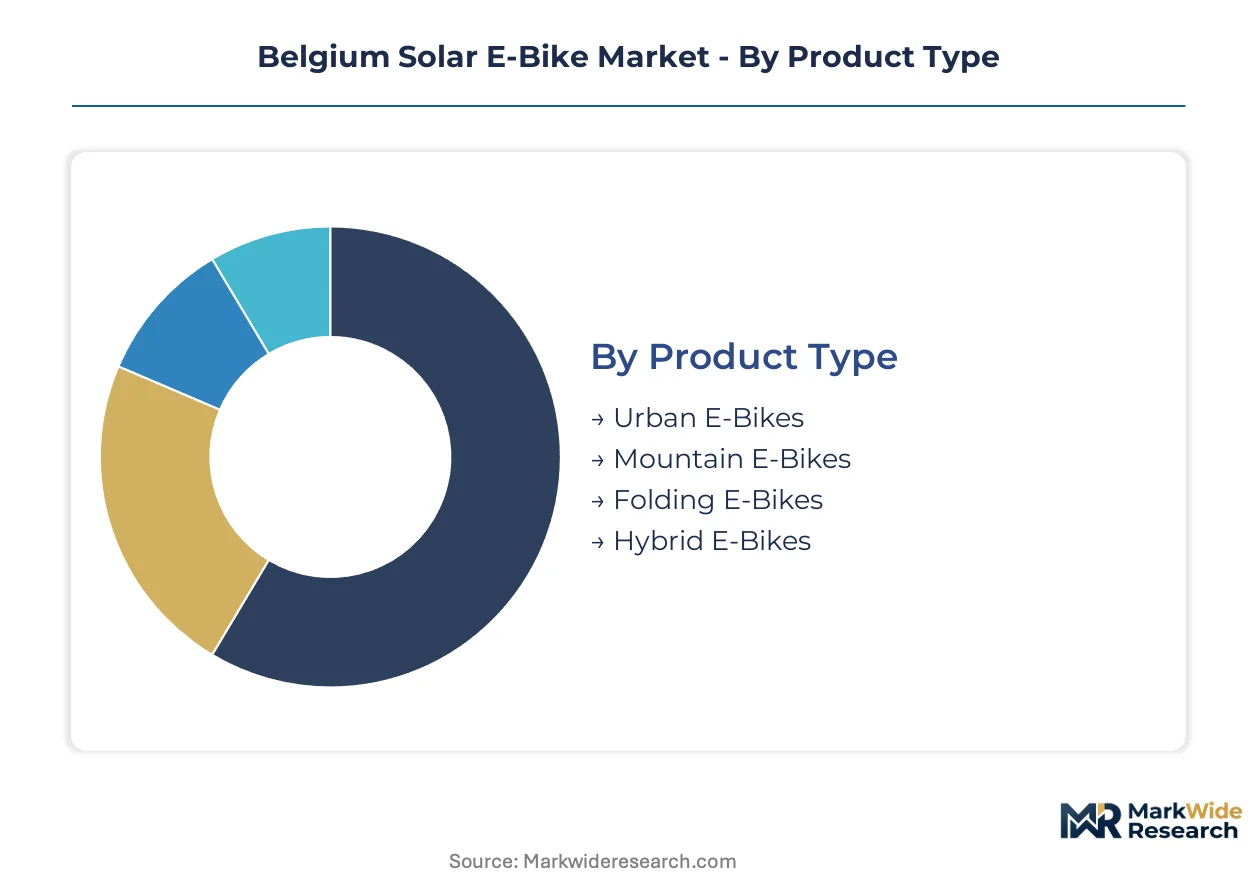
Belgium's solar e-bike market segments along four distinct dimensions that shape procurement priorities across Flemish and Walloon provinces. Each category reflects divergent technical specifications, user behaviors, and regulatory compliance requirements that vendors must navigate to capture fleet and consumer demand.
Product Type:
Urban e-bikes turn inventory fastest through municipal fleet contracts, while mountain e-bikes cycle slowest due to seasonal recreational demand and higher price points.
- Urban E-Bikes:Frame-integrated photovoltaic cells power 250W pedal-assist motors optimized for stop-start traffic in Brussels and Antwerp. Courier fleets under zero-emission mandates concentrate procurement here, with daily utilization rates exceeding other categories.
- Folding E-Bikes:Compact hinge-frame designs accommodate detachable solar panels for indoor apartment storage in Ghent and Brussels. Young professionals and last-mile delivery subcontractors drive demand for space-efficient configurations.
- Mountain E-Bikes:Reinforced suspension systems and higher-torque 500W motors serve recreational trail users in the Ardennes.
- Hybrid E-Bikes:Versatile tire profiles and moderate motor ratings bridge commuting and light touring applications across Flanders.
Urban e-bikes anchor the volume base while folding e-bikes gain share at the steepest rate.
Battery Type:
Cost tiers stratify sharply here, with premium solid-state configurations commanding multiples over commodity lithium-ion packs.
- Lithium-Ion:NMC and LFP chemistries dominate manufacturing scale, supplying cost-competitive packs to Belgian assemblers. Raw material volatility in cobalt and nickel channels creates margin pressure that fleet buyers absorb through extended leasing terms.
- Solid-State:Ceramic electrolyte architectures eliminate thermal runaway risks while doubling energy density for premium positioning. Cleanroom production requirements constrain supply, limiting deployment to high-value courier and executive commuter segments.
- Lead Acid:Legacy chemistry persists in price-sensitive rural markets with minimal photovoltaic integration.
- Nickel-Metal Hydride:Intermediate performance tier serves replacement battery demand in older e-bike fleets.
Lithium-ion chemistry sustains the installed base while solid-state technology captures the premium margin pool.
Charging Method:
Application context determines charging infrastructure investment, with commercial fleets prioritizing depot systems and residential users favoring flexibility.
- Solar Charging:Frame-integrated or trailer-mounted photovoltaic arrays enable continuous topping during daylight riding hours. Brussels-based courier pilots optimize dispatch algorithms around real-time solar yield telemetry.
- Regenerative Braking:Kinetic recovery systems extend range in hilly Walloon terrain and urban stop-start corridors.
- Grid Charging:Overnight depot charging remains standard for fleet operators with centralized parking infrastructure.
- Home Charging:Residential wall-mounted units serve commuter segments with secure garage or basement storage.
Solar charging leads technology differentiation while regenerative braking expands fastest among mixed-terrain users.
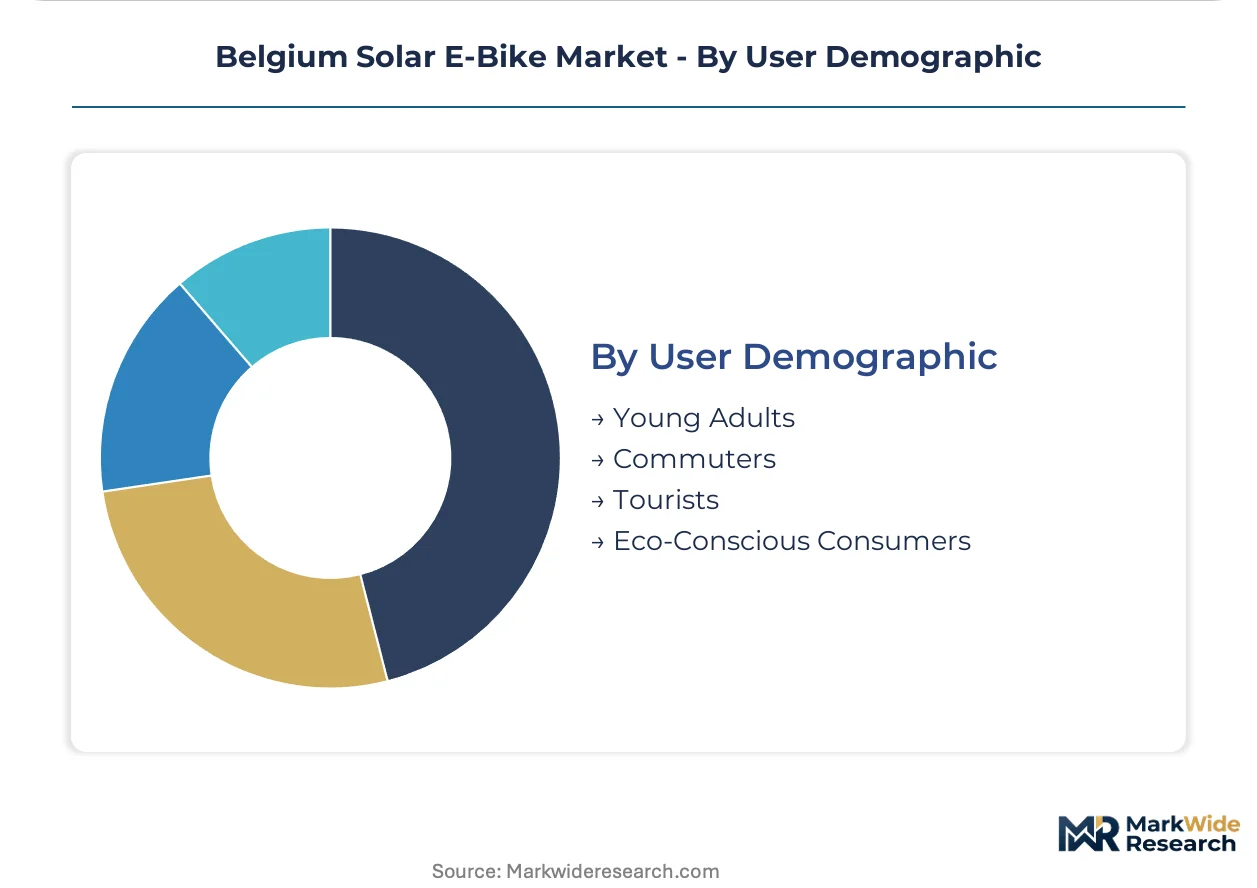
User Demographic:
Customer maturity varies widely, from digitally native young adults to institutional procurement officers administering employer-provided bicycle programs.
- Commuters:Daily riders leveraging federal bicycle allowance tax deductibility across Flemish cycling infrastructure corridors. Employer fleet conversion programs concentrate procurement volume in this segment.
- Eco-Conscious Consumers:Sustainability-motivated buyers prioritizing carbon accounting transparency and extended producer responsibility compliance. CE marking and EU Battery Regulation traceability requirements shape purchase criteria.
- Young Adults:Subscription-oriented users favoring app-integrated maintenance bundles and direct-to-consumer channels.
- Tourists:Seasonal rental demand in Bruges, Ghent, and coastal municipalities drives short-term utilization.
Commuters provide the revenue foundation while eco-conscious consumers expand most quickly as EU Green Deal carbon disclosure mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Belgian provinces. Flanders buyers absorb premium pricing for photovoltaic-integrated frames, while Wallonia procurement remains price-sensitive and dependent on federal subsidy thresholds.
Flanders
Daily commuter volumes and employer-provided bicycle programs concentrate procurement in Antwerp, Ghent, and Leuven corridors. The Flanders Region mobility subsidies reduce effective purchase prices for qualifying solar e-bike configurations. Cycling infrastructure density in East and West Flanders supports sustained utilization rates that justify higher upfront capital expenditure.
Wallonia
Rural commuting patterns and lower cycling modal share create demand fragmentation across Liège, Namur, and Charleroi. Belgium's federal bicycle allowance reform applies nationally, but uptake lags due to sparser charging infrastructure and longer average trip distances. Domestic assembly networks in Hainaut province control spare parts distribution, limiting service accessibility outside urban cores.
Brussels-Capital Region
Municipal zero-emission delivery mandates for courier fleets drive concentrated fleet procurement. Brussels-Capital regional transport authorities enforce CE marking compliance and monitor low-emission zone expansion proposals. Last-mile logistics operators pilot frame-integrated photovoltaic systems to optimize route planning around solar exposure data.
Antwerp Province
Port-related logistics activity and dense urban cycling networks generate dual demand streams: commercial fleets and affluent commuters. Employer-provided bicycle tax deductibility documentation requirements create administrative friction that HR departments navigate through specialized fleet management providers. The province anchors volume production for domestic assemblers serving both Belgian and adjacent Dutch markets.
Liège Province
Industrial heritage and moderate cycling adoption create niche demand among eco-conscious consumers and recreational touring segments. EU Green Deal carbon accounting standards influence procurement criteria for institutional buyers in the public sector. The Ardennes terrain limits urban e-bike utility but supports mountain e-bike rental operations serving seasonal tourism demand.
Belgium Solar E-Bike Market Competitive Landscape
Capability concentration sits with domestic assemblers controlling photovoltaic integration and battery management systems; scale advantage sits with direct-to-consumer brands leveraging app-integrated fleet management tools. The vendor base organizes around three archetypes: heritage manufacturers with cooperative service networks, technology-forward direct-to-consumer platforms, and regional assemblers with captive spare parts distribution. Competitive moves center on strategic partnerships with Flemish cycling cooperatives and proprietary charging algorithm development.
Within the domestic assembly tier, Veloci occupies a position anchored on spare parts distribution control in Wallonia. Cowboy represents the direct-to-consumer archetype through subscription-style maintenance bundles targeting Brussels and Antwerp demand. Minerva exemplifies heritage brand extension through cooperative maintenance networks unlocking rural commuter segments.
| Leading Market Players |
|---|
| Veloci |
| Venilu |
| Oxford |
| Minerva |
| Granville |
| Cowboy |
| Belgocycle |
| Bnewable |
| Ellio |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Belgian lithium-ion battery pack assembly is driving suppliers toward long-term offtake contracts with Asian cell manufacturers, compressing margin flexibility for domestic frame-integrators while pushing fleet buyers toward subscription pricing models that spread capital risk.
Pricing Analysis
Long-term offtake contracts between Belgian assemblers and South Korean cell suppliers dominate procurement, though spot-market cobalt sourcing introduces volatility that stratifies pricing across premium solid-state configurations and standard lithium-ion tiers. CE marking tier and photovoltaic integration depth serve as the primary price differentiation drivers. Cost compression in entry-level urban e-bikes is intensifying as Chinese frame manufacturers absorb margin pressure. Municipal fleet operators demonstrate lowest price sensitivity due to zero-emission mandate compliance deadlines, while individual commuters in Wallonia exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for Belgian solar e-bike assemblers sourcing carbon fiber frames and photovoltaic laminates. Manufacturing concentration rests on China for flexible solar cells, South Korea for NMC battery chemistry, and Taiwan for power management semiconductors. Cobalt hydroxide, nickel sulfate, and carbon fiber prepreg constitute critical input dependencies. Single-source vulnerability in solid-state electrolyte ceramic substrates constrains premium tier scaling. Distribution runs through direct-to-consumer platforms for urban commuters and Flemish cycling cooperative networks for rural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation delegated acts are accelerating market disruption by imposing traceability costs that favor capitalized incumbents while creating compliance barriers for smaller assemblers.
For Market Incumbents: Insulate margin position by deepening backward integration into photovoltaic lamination capabilities in Flanders assembly facilities and securing multi-year cobalt offtake agreements before raw material volatility intensifies. Battery passport documentation systems represent the critical defensive lever against regulatory displacement. For New Entrants and Emerging Players: Folding e-bike configurations for Brussels apartment dwellers represent the most penetrable entry point, given storage-constrained demand and underserved direct-to-consumer channel positioning. Wallonia rural commuter segments offer secondary white-space through heritage brand licensing partnerships. App-integrated maintenance subscription bundles provide the optimal go-to-market angle against established cooperative networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because EU Green Deal carbon accounting mandates will structurally favor solar-assisted mobility over conventional e-bike alternatives. Acquisition targets should concentrate on domestic assemblers with captive spare parts distribution and CE marking certification infrastructure. The signal to watch is Brussels-Capital Region low-emission zone expansion to light commercial pedal-assist vehicles.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Integration Partnership | Secures flexible solar cell supply from Taiwanese laminators for frame-embedded charging systems. |
| Battery Passport Compliance Investment | Builds traceability infrastructure meeting EU Battery Regulation delegated acts for Flanders fleet contracts. |
| Flemish Cooperative Network Expansion | Extends service coverage into rural Wallonia provinces beyond Veloci's spare parts distribution control. |
| Solid-State Battery Pilot Program | Positions premium tier offerings for executive commuter segments in Antwerp and Brussels corridors. |
| Direct-to-Consumer Platform Launch | Captures digitally native young adult demand through subscription-style maintenance bundles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, Belgian federal transport authority procurement databases, and photovoltaic industry trade data. Primary interviews engaged solar e-bike assemblers, Flemish cycling cooperative service managers, municipal fleet procurement officers in Brussels and Antwerp, battery management system engineers, and employer-provided bicycle program administrators. Secondary validation drew from CE marking compliance registries, EU Battery Regulation delegated act drafts, and Flanders Region mobility subsidy disbursement records. Bottom-up demand modeling triangulated against top-down market sizing from component supply chain analysis.
Forecast inputs incorporate product type segmentation across urban, folding, mountain, and hybrid configurations; battery chemistry tiers spanning lithium-ion and solid-state; charging method differentiation; and user demographic clustering. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Industry-specific inputs include photovoltaic cell efficiency improvement trajectories and municipal zero-emission mandate implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in lithium and cobalt commodity price indices, euro-dollar exchange rate volatility, or Belgian federal bicycle allowance reform timing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost-down curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
Africa Electric Scooter Market