
 Electric Vehicle Skateboard Chassis Market | 2026-2036
Electric Vehicle Skateboard Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Skateboard Chassis Market Insights
The direct-to-fleet sales channel is rewriting how skateboard chassis platforms reach commercial buyers. Rivian leverages its captive logistics partnerships to sustain volume commitments for delivery van configurations. REE Automotive anchors its position through corner-module standardization that reduces assembly complexity for multiple OEM programs. Canoo competes via subscription-based fleet access models that lower capital barriers for utility vehicle operators.
An electric vehicle skateboard chassis integrates the battery pack, electric motors, and suspension into a flat, low-profile platform that supports multiple body styles through standardized mounting interfaces. The architecture typically achieves a center of gravity below 300mm while accommodating battery capacities exceeding 100kWh for extended commercial duty cycles. Modular chassis configurations capture the widest addressable market as OEMs seek platform flexibility across passenger and light-commercial applications. Battery-integrated technology leads development investment, though smart chassis variants with active load management and predictive maintenance capabilities represent the fastest-expanding margin pool for Tier-1 suppliers.
The EPA's commercial vehicle emissions benchmarks and NHTSA crashworthiness standards for battery-protected occupant compartments shape North American platform specifications, while China's MIIT enforces GB standards for battery integration and thermal runaway containment. The EU's CE marking requirements under the MDR framework and REACH substance restrictions on chassis coatings influence material selection and cross-border market access. Stakeholders must monitor regulatory divergence between major markets as compliance costs fragment platform standardization strategies.
Market Dynamics
Fleet electrification mandates are compressing chassis development cycles as commercial operators demand platform flexibility across van, truck, and specialty body configurations from a single base architecture.
Growth Catalysts
- EU F-Gas Regulation:Thermal management system requirements are accelerating integrated cooling architectures that consolidate HVAC and battery thermal loops into chassis-level designs.
- Last-mile logistics:Urban delivery consolidation is pulling standardized low-floor platforms into high-volume deployment with minimal body customization.
- Cell-to-chassis bonding:Structural battery integration is eliminating separate pack enclosures and freeing packaging volume for cargo or auxiliary systems.
Market Restraints
- Lithium price volatility:Battery raw material cost swings compress chassis margin structures before platform scale economics stabilize procurement.
- Yangtze River Delta concentration:Critical component and cell manufacturing clustering creates single-point exposure to regional logistics or policy disruptions.
- GB standard divergence:China's MIIT battery-integrated platform specifications diverge from UN ECE crashworthiness protocols, fragmenting homologation paths.
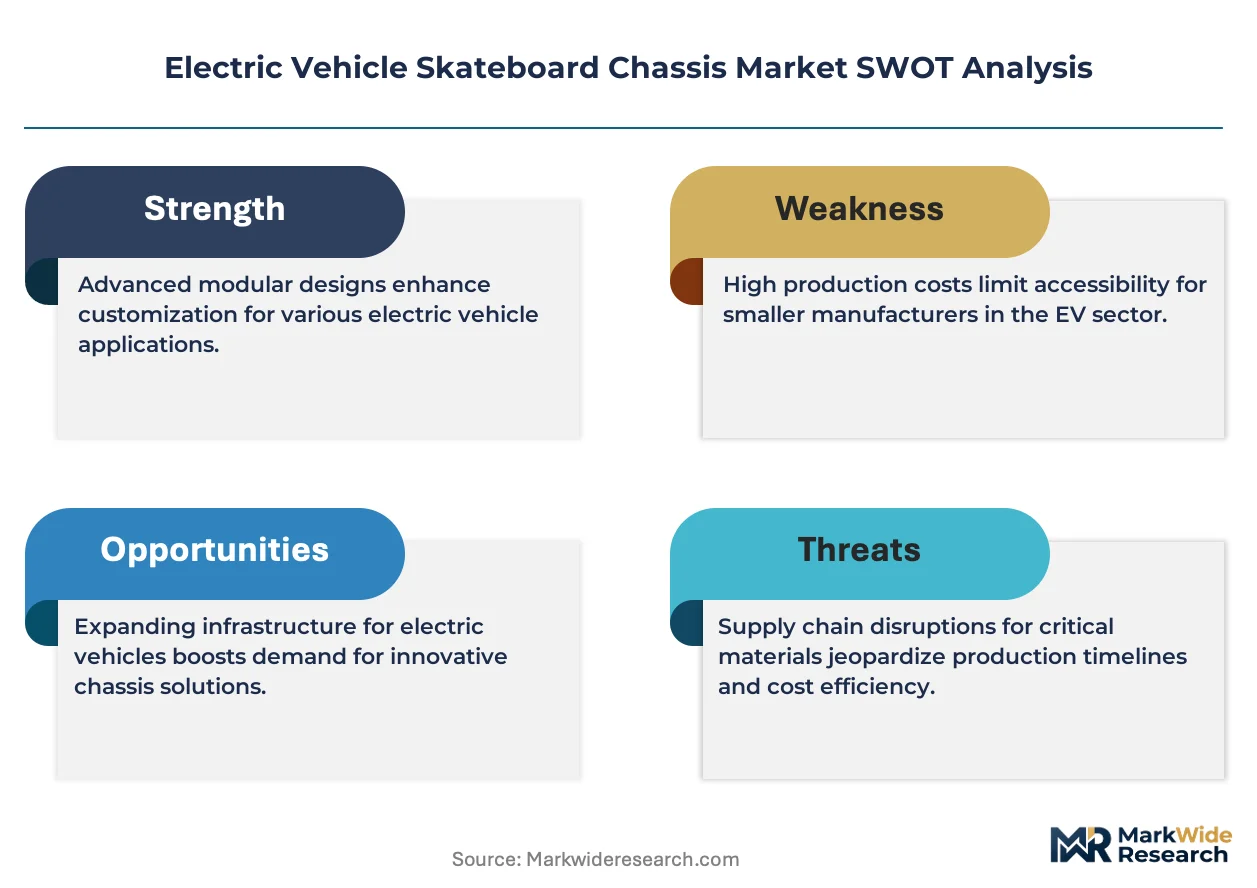
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are opening localized chassis assembly for domestic commercial vehicle programs.
- Active load management:Convergence of predictive suspension with real-time battery thermal control enables dynamic duty cycle optimization for variable freight densities.
- Subscription fleet access:Asset-light operating models are lowering capital barriers for utility operators entering electrified commercial vehicle pools.
Industry Challenges
- Multi-physics simulation talent:Shortage of engineers capable of integrating thermal, structural, and electrical domain modeling is extending development timelines.
- Homologation backlog:Certification queue compression at NHTSA and EU type-approval bodies is delaying platform launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Skateboard Chassis Market |
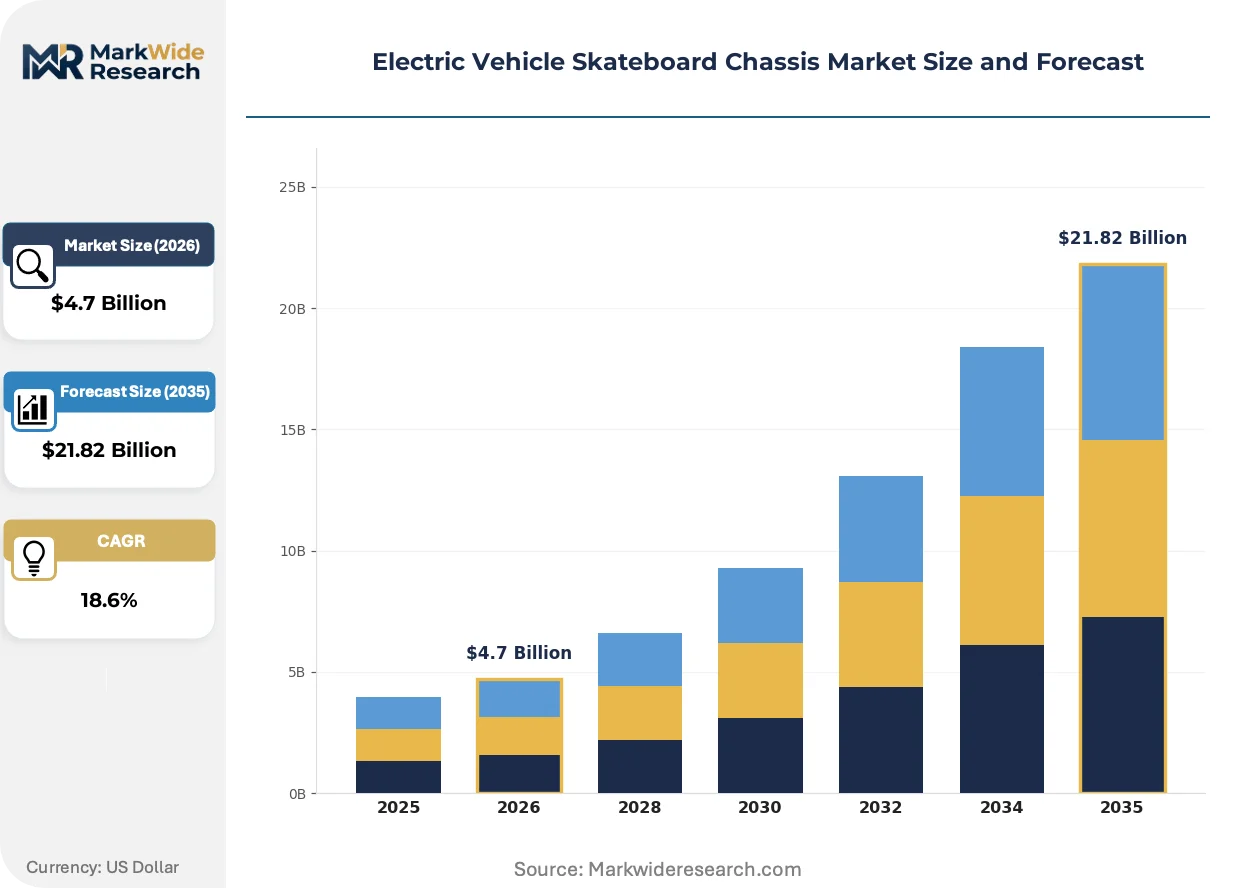
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Chassis, Modular Chassis, Lightweight Chassis, All-Terrain Chassis End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Startups Technology: Battery Integrated, Hub Motor, Regenerative Braking, Smart Chassis Application: Passenger Vehicles, Commercial Vehicles, Delivery Vans, Utility Vehicles |
| Companies Covered | U Power Tech, PIXMoving, Rivian, CATL, Olympian Motors, REE Automotive, ECAR Tech, Haomo Technology, Canoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Skateboard Chassis Market Trends and Innovations
Platform architecture is converging around standardized corner modules and structural battery integration, compressing the traditional separation between powertrain engineering and vehicle body development.
Structural battery enclosures are hybridizing with chassis frame rails to form continuous load-bearing members. Commercial fleet operators in Germany and the Netherlands are specifying these configurations for delivery van programs. The technology is hybridizing crash energy management with thermal runaway containment into unified structural solutions.
China's MIIT enforcement of GB standards for battery-integrated platforms is mandating cell-to-chassis bonding and thermal propagation barriers. Domestic OEMs must redesign legacy skateboard architectures to satisfy runaway containment timelines. Export-oriented programs targeting EU markets are dual-certifying against both GB and UN ECE requirements.
Fleet procurement is consolidating around direct platform sourcing with captive upfitter networks. Traditional dealer channels for commercial chassis are losing volume to OEM-direct fleet agreements with integrated body builder scheduling. This pattern concentrates in California and New York where state-level zero-emission mandates accelerate replacement cycles.
Electric Vehicle Skateboard Chassis Market Segmentation
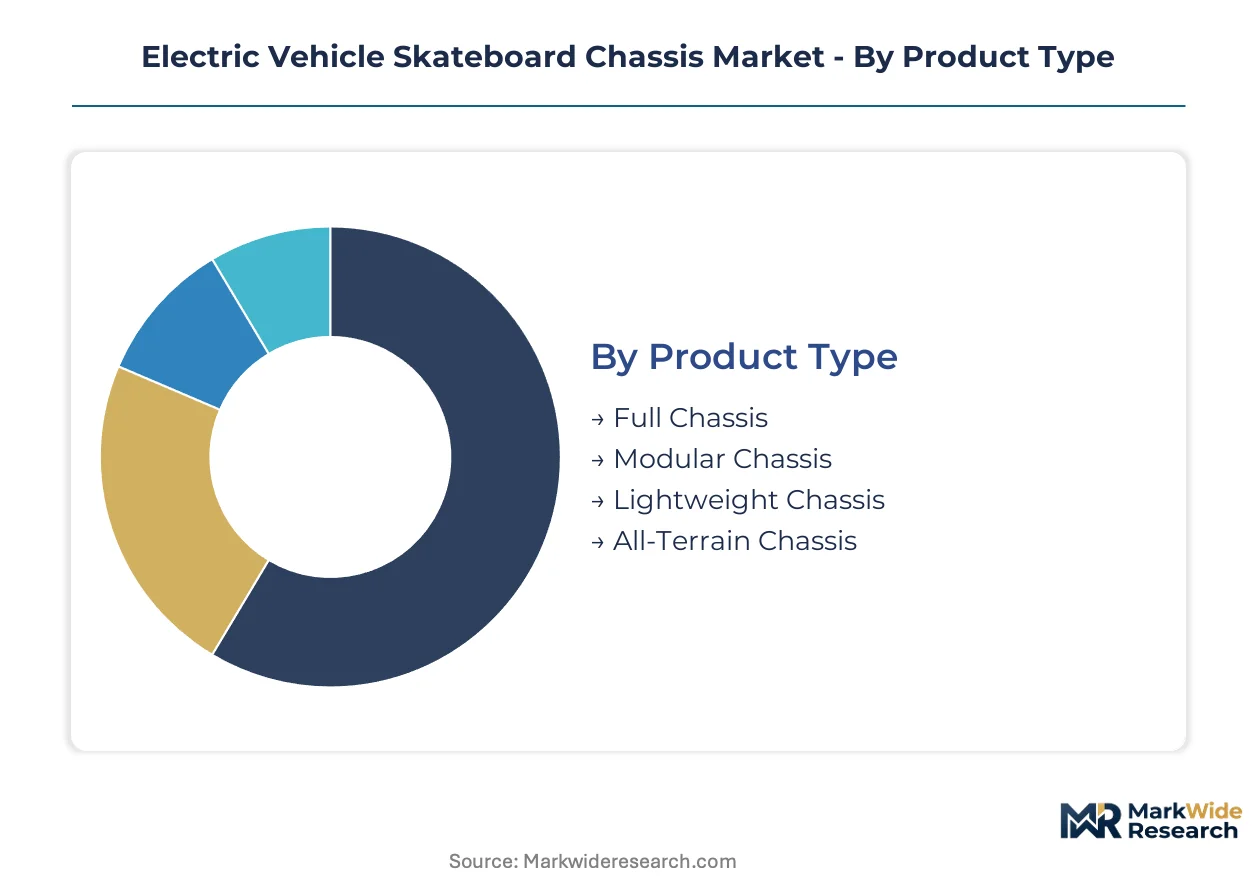
Platform architecture diversity in the electric vehicle skateboard chassis market reflects competing imperatives between standardization economics and application-specific performance requirements. Segmentation patterns reveal how battery integration depth, customer procurement authority, and duty cycle intensity reshape competitive positioning across the value chain.
Product Type:
Cost tier differentiation separates chassis platforms by structural complexity and reconfiguration flexibility for downstream body integration.
- Modular Chassis:Standardized mounting interfaces accommodate multiple body styles through interchangeable subframes and corner modules. Fleet operators in Germany and the Netherlands specify these configurations for delivery van programs requiring rapid upfitter turnaround.
- Full Chassis:Complete integrated platforms ship with pre-installed battery enclosures, thermal management loops, and suspension assemblies. OEMs in China's Yangtze River Delta manufacturing cluster source these for passenger vehicle programs where assembly line integration speed dominates procurement criteria.
- Lightweight Chassis:Aluminum-intensive and composite-hybrid structures reduce curb weight for extended range applications.
- All-Terrain Chassis:Reinforced frame rails and elevated ground clearance configurations serve utility vehicle operators in mining and agricultural sectors.
Full Chassis commands the established base. The steepest expansion runs through Modular Chassis.
End User:
Customer type segmentation tracks procurement authority and technical integration capabilities across the automotive value chain.
- OEMs:Vehicle manufacturers with captive engineering resources specify custom platform architectures aligned with brand-specific performance targets. California and New York state zero-emission mandates accelerate direct platform sourcing with integrated body builder scheduling.
- Tier-1 Suppliers:System integrators purchase chassis platforms for subassembly packaging before OEM handoff. These suppliers leverage corner-module standardization to reduce assembly complexity across multiple customer programs.
- Startups:New entrants without legacy manufacturing infrastructure rely on contract chassis supply to compress development timelines.
- Aftermarket Providers:Conversion specialists retrofit existing vehicle bodies onto skateboard platforms for niche electrification projects.
OEMs retain volume concentration. The steepest expansion trajectory belongs to Tier-1 Suppliers.
Technology:
Maturity gradients separate proven battery integration approaches from emerging smart chassis capabilities with predictive maintenance functions.
- Battery Integrated:Cell-to-chassis bonding eliminates separate pack enclosures and frees packaging volume for cargo or auxiliary systems. China's MIIT enforcement of GB standards mandates thermal propagation barriers and runaway containment timelines.
- Smart Chassis:Active load management converges predictive suspension with real-time battery thermal control for dynamic duty cycle optimization. Commercial fleet operators specify these capabilities for variable freight density applications.
- Hub Motor:In-wheel motor configurations reduce drivetrain packaging height and enable low-floor architectures.
- Regenerative Braking:Kinetic energy recovery systems integrated at the chassis level optimize thermal management co-design.
Battery Integrated technology anchors current deployment. Smart Chassis capabilities are climbing the fastest.
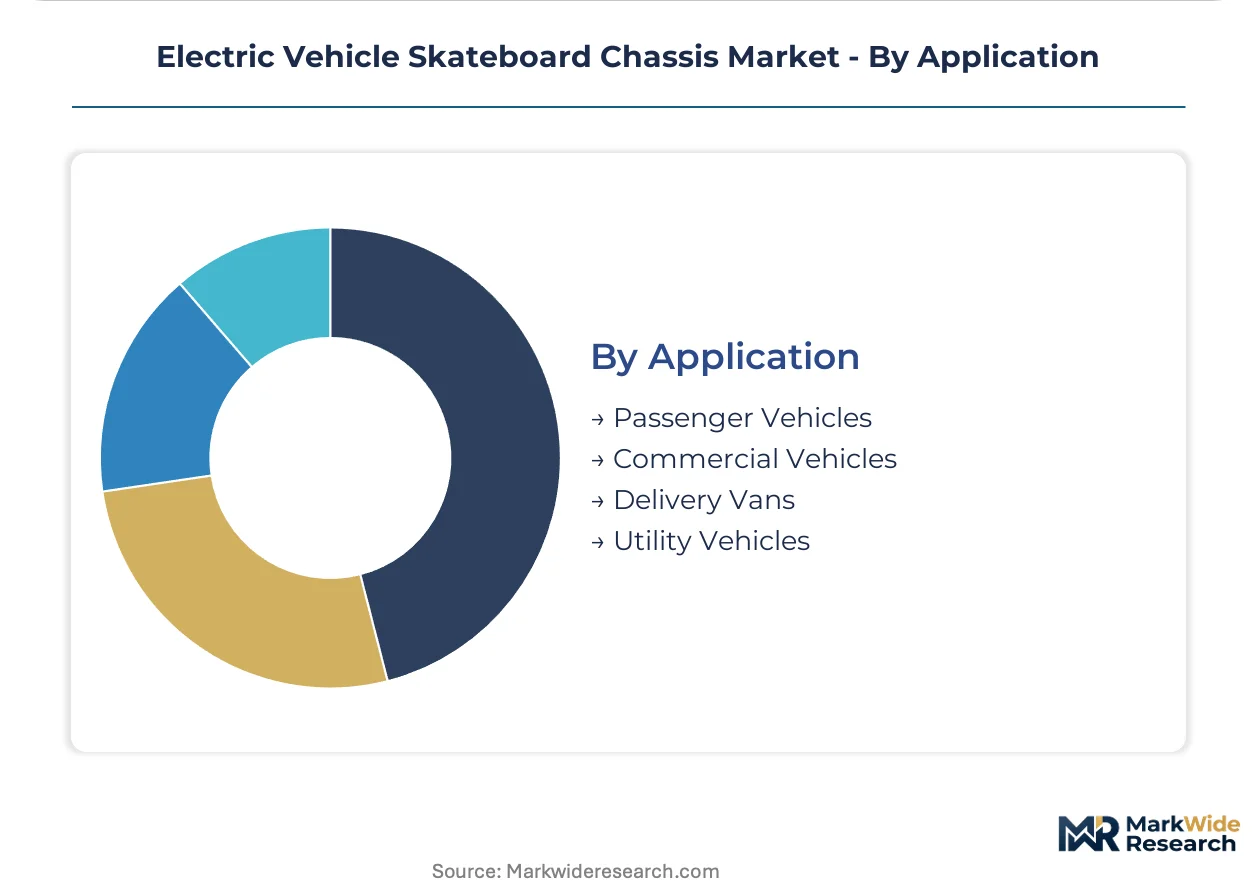
Application:
Volume concentration versus margin intensity separates high-unit passenger programs from specialized commercial configurations.
- Commercial Vehicles:Medium-duty truck platforms with reinforced frame rails and extended battery capacities serve regional freight operators. The EU's F-Gas Regulation on thermal management systems accelerates integrated cooling architectures for these duty cycles.
- Delivery Vans:Low-floor configurations with standardized upfitter interfaces dominate last-mile electrification procurement. Fleet operators leverage direct platform sourcing to bypass traditional dealer channels.
- Passenger Vehicles:Premium SUV and sedan applications prioritize center-of-gravity optimization below 300mm.
- Utility Vehicles:Specialty chassis with auxiliary power take-offs serve municipal and industrial equipment mounting.
Delivery Vans concentrate near-term volume. Commercial Vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and fleet electrification mandates are redirecting chassis procurement flows across major automotive markets. Battery-integrated platform standards and thermal management regulations are fragmenting homologation pathways between jurisdictions.
China
Domestic OEMs and export-oriented programs drive volume concentration in the Yangtze River Delta manufacturing cluster. MIIT enforcement of GB standards for cell-to-chassis bonding and thermal runaway containment is forcing redesigns of legacy skateboard architectures. CATL anchors production networks supplying battery-integrated platforms to multiple customer programs.
United States
Commercial fleet operators in California and New York accelerate direct platform sourcing with integrated body builder scheduling. EPA commercial vehicle emissions benchmarks and NHTSA crashworthiness standards for battery-protected occupant compartments shape platform specifications. Rivian leverages captive logistics partnerships to sustain volume commitments for delivery van configurations.
Germany
Commercial fleet operators specify structural battery enclosures hybridized with chassis frame rails for delivery van programs. EU F-Gas Regulation on thermal management systems accelerates integrated cooling architectures that consolidate HVAC and battery thermal loops. Industrial clusters in Bavaria and Baden-Württemberg host development centers for predictive suspension and active load management systems.
India
Production-linked incentives for advanced chemistry cell manufacturing are opening localized chassis assembly opportunities for domestic commercial vehicle programs. The central government's automotive PLI scheme reduces import dependency for battery components. Tamil Nadu and Gujarat manufacturing corridors attract contract chassis suppliers targeting regional freight operators.
Netherlands
Urban delivery consolidation pulls standardized low-floor platforms into high-volume deployment with minimal body customization. EU CE marking requirements under the MDR framework and REACH substance restrictions on chassis coatings influence material selection. Rotterdam and Amsterdam logistics hubs specify modular chassis configurations for rapid upfitter turnaround.
Electric Vehicle Skateboard Chassis Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated platform specialists, battery-technology originators, and contract manufacturing facilitators. Established automotive suppliers compete with venture-backed chassis developers for fleet procurement contracts. Corner-module standardization and structural battery integration represent the dominant competitive moves compressing assembly complexity.
Among venture-backed platform developers, REE Automotive and Canoo exemplify alternative go-to-market architectures. REE Automotive anchors its position through corner-module standardization that reduces assembly complexity for multiple OEM programs. Canoo competes via subscription-based fleet access models that lower capital barriers for utility vehicle operators. CATL represents the battery-technology originator archetype, supplying integrated cell-to-chassis platforms from its Yangtze River Delta production base.
| Leading Market Players |
|---|
| U Power Tech |
| PIXMoving |
| Rivian |
| CATL |
| Olympian Motors |
| REE Automotive |
| ECAR Tech |
| Haomo Technology |
| Canoo |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta battery cell concentration funnels pricing power toward integrated platform suppliers while compressing margins for non-captive assemblers. Tier-1 suppliers capture service-attach revenue streams that hardware margins alone cannot sustain.
Pricing Analysis
Volume-discount tiering structures separate fleet-direct procurement from smaller aftermarket orders. Pricing stratifies across premium certified, standard compliance, and economy non-certified tiers based on GB standard adherence and thermal runaway containment certification. Cost compression in economy tiers is intensifying because lithium price volatility feeds directly into chassis bill-of-materials. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while aftermarket conversion specialists face acute margin pressure.
Supply Chain Analysis
Extended payment terms from OEMs to module suppliers now stretch 90-120 days, forcing working capital facilities at the cell-packaging tier. Manufacturing draws from China, South Korea, and Germany for battery cells, corner modules, and suspension systems respectively. Single-source vulnerability concentrates in cell-to-chassis bonding equipment where European tooling suppliers dominate. Distribution runs through direct fleet agreements with captive upfitter scheduling rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins in skateboard chassis platforms are flattening while predictive maintenance subscriptions and thermal management service contracts expand at multiples of equipment growth. Recurring revenue layers now determine enterprise value in this market.
For Market Incumbents: Insulate core platform revenue through backward integration into cell-to-chassis bonding processes that non-captive competitors cannot replicate. Secure corner-module standardization patents before emerging modular specialists erode assembly-line advantages. Prioritize GB standard dual-certification capacity to serve both domestic Chinese and export EU programs without homologation delays. For New Entrants and Emerging Players: Pursue white-space opportunities in India PLI scheme corridors where localized chassis assembly for commercial vehicle programs lacks established suppliers. Target utility vehicle operators in mining and agricultural sectors requiring all-terrain configurations that mainstream platforms underserve. Lead with subscription fleet access models that lower capital barriers and bypass incumbent dealer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward smart chassis developers with active load management IP and predictive suspension capabilities that command service-attach multiples. Long-term viability hinges on software-defined thermal control architectures rather than commodity battery integration. Watch for inflection when NHTSA and EU type-approval backlogs clear and launch windows compress competitive timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Corner-module unification reduces assembly complexity for multiple OEM programs simultaneously. |
| Battery Supply Agreement | CATL cell-to-chassis partnerships anchor Yangtze River Delta production networks for export. |
| Software-Defined Vehicle Investment | Predictive suspension algorithms enable dynamic duty cycle optimization for variable freight densities. |
| Geographic Manufacturing Footprint | India PLI scheme corridors attract contract chassis suppliers targeting regional freight operators. |
| Charging Infrastructure Partnership | Fleet-direct agreements integrate depot charging scheduling with chassis delivery timelines. |
Research Methodology
Desk research of regulatory filings, patent databases, and fleet procurement records preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket conversion specialists, and commercial fleet operations directors. Primary fieldwork across China's Yangtze River Delta, Germany's Baden-Württemberg cluster, and India's Tamil Nadu corridor validated secondary intelligence from MIIT standards documentation, EU F-Gas Regulation impact assessments, and NHTSA crashworthiness protocols. Bottom-up chassis shipment tallies triangulated against top-down battery capacity deployment estimates.
Assumptions held fixed include continuation of EU F-Gas thermal management mandates, sustained lithium price volatility bands, and NHTSA battery-protected occupant compartment standards. Variables tested across the analysis window encompassed India PLI scheme uptake rates, GB standard divergence scenarios, and fleet subscription adoption curves. Modeled segmentation dimensions span chassis architecture type, battery integration depth, end-user procurement authority, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to fleet electrification mandate timelines and cell-to-chassis bonding yield improvements.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing, regional logistics disruption, or central bank capital cost regimes would shift the trajectory. Forecasts reflect documented assumptions without claiming predictive certainty. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Electric Two-Wheeler Market