
 New Zealand E-Bike Market | 2026-2036
New Zealand E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand E-Bike Market Foresight
Corporate fleet procurement is pivoting toward electrified two-wheel solutions as Auckland and Wellington employers expand staff transport programs. Avanti Bikes leverages its domestic assembly presence to anchor supply contracts with institutional buyers. Giant Manufacturing Co. sustains competitive pressure through manufacturing scale that spans multiple motor configurations. UBCO LIMITED specializes in utility-focused electric platforms that occupy a distinct niche between recreational and commercial applications.
An e-bike integrates a rechargeable battery pack, electric motor, and pedal-assist or throttle-based propulsion controller into a conventional bicycle frame, typically delivering supplementary power up to regulated speed thresholds. The device serves both individual mobility and commercial logistics functions where gradient terrain or delivery range would constrain unassisted cycling. Commuter bikes lead volume within the product type dimension as urban employers subsidize staff transport, while mid drive motors capture preference among mountain bike buyers seeking balanced weight distribution. Delivery services represent the fastest-growing end user segment as last-mile operators replace van fleets with electric two-wheel alternatives.
Waka Kotahi NZ Transport Agency administers road safety standards that classify e-bikes by maximum assisted speed and motor wattage, directly determining which products qualify for cycleway access and exemption from registration. Energy Efficiency and Conservation Authority frameworks influence battery charging infrastructure deployment, shaping where commercial fleets can operate without range interruption. Stakeholders must monitor how proposed amendments to Land Transport Rule definitions affect throttle-assist models and their eligibility for shared path access.
Market Dynamics
Waka Kotahi NZ Transport Agency incentive structures for low-emission corporate transport are redirecting procurement budgets toward electrified two-wheel fleets, compressing traditional van-based staff mobility programs in Auckland and Wellington.
Growth Catalysts
- Land Transport Rule amendments:Proposed regulatory clarity on throttle-assist eligibility for shared path access is accelerating fleet buyer confidence in urban deployment.
- Corporate sustainability mandates:Auckland-based employers are embedding e-bike subsidies into staff transport packages, creating institutional demand pull.
- Hill terrain topology:Wellington's steep gradients make electric assist functionally essential rather than optional, concentrating commuter adoption in high-gradient corridors.
Market Restraints
- Lithium-ion supply concentration:Battery cell sourcing depends on East Asian manufacturing clusters, exposing importers to shipping cost volatility and currency fluctuation.
- Mid-drive motor technical complexity:Higher maintenance requirements and specialized repair skill scarcity limit rural service coverage outside major urban centers.
- Energy Efficiency and Conservation Authority infrastructure gaps:Commercial charging point deployment lags fleet expansion in secondary cities, constraining operational range for delivery operators.
Strategic Opportunities
- Canterbury regional underpenetration:Christchurch cycling network investment creates whitespace for commuter fleet expansion beyond the dominant Auckland-Wellington axis.
- Last-mile logistics convergence:Courier and food delivery platforms are integrating e-bike dispatch with route optimization software, opening fleet-scale procurement channels.
- Waka Kotahi low-emission transport incentives:Expanding subsidy pools for institutional buyers present margin capture opportunities for domestic assembly operations.
Industry Challenges
- Certification timeline compression:Land Transport Rule compliance testing for new motor configurations creates product launch delays for manufacturers.
- Service technician skill scarcity:Battery diagnostics and mid-drive motor repair expertise concentrates in Auckland and Wellington, leaving regional coverage thin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand E-Bike Market |
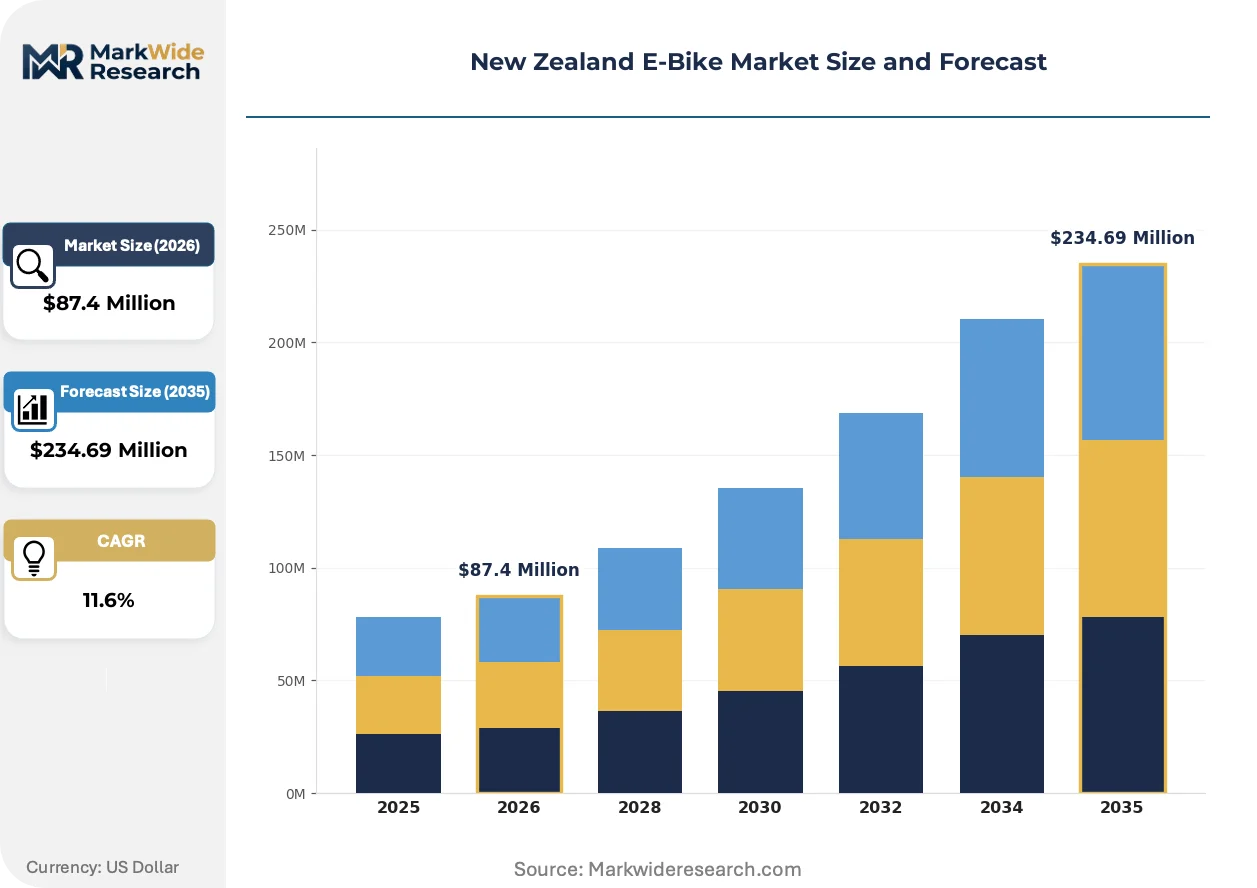
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bikes, Commuter Bikes, Folding Bikes, Cruiser Bikes End User: Individuals, Delivery Services, Rental Companies, Corporate Fleets Motor Type: Hub Motors, Mid Drive Motors, Rear Wheel Motors, Front Wheel Motors Battery Capacity: Below 400Wh, 400-600Wh, 600-800Wh, Above 800Wh |
| Companies Covered | Accell Group, Avanti Bikes, Electric Bike Company, Giant Manufacturing Co., MeloYelo, Scott Sports, Specialized Bicycle Components, Trek Bicycle Corporation, UBCO LIMITED, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand E-Bike Market Shifts & Advancements
Hardware-software integration is redefining fleet management capabilities as telematics-enabled e-bikes generate operational data that reshapes procurement criteria and service contract structures.
Mid-drive motor systems are expanding into the utility segment as courier and delivery operators seek balanced weight distribution for cargo loads. Food delivery platforms in Auckland are adopting these configurations at pace, replacing hub-mounted alternatives. The technology is expanding into fleet procurement specifications as a standard requirement rather than premium upgrade.
Waka Kotahi NZ Transport Agency classification frameworks for maximum assisted speed and motor wattage are tightening eligibility criteria for cycleway access. This industrial consequence is forcing product line rationalization among importers. Throttle-assist models face the most acute compliance pressure, with manufacturers accelerating pedal-assist platform development.
Corporate transport subsidy programs are consolidating purchasing authority under fleet managers rather than individual reimbursement schemes. Auckland employers are centralizing procurement through institutional contracts, displacing retail channel volume. This pattern is most visible in the professional services vertical, where sustainability reporting requirements drive standardized fleet specifications.
New Zealand E-Bike Market Segmentation
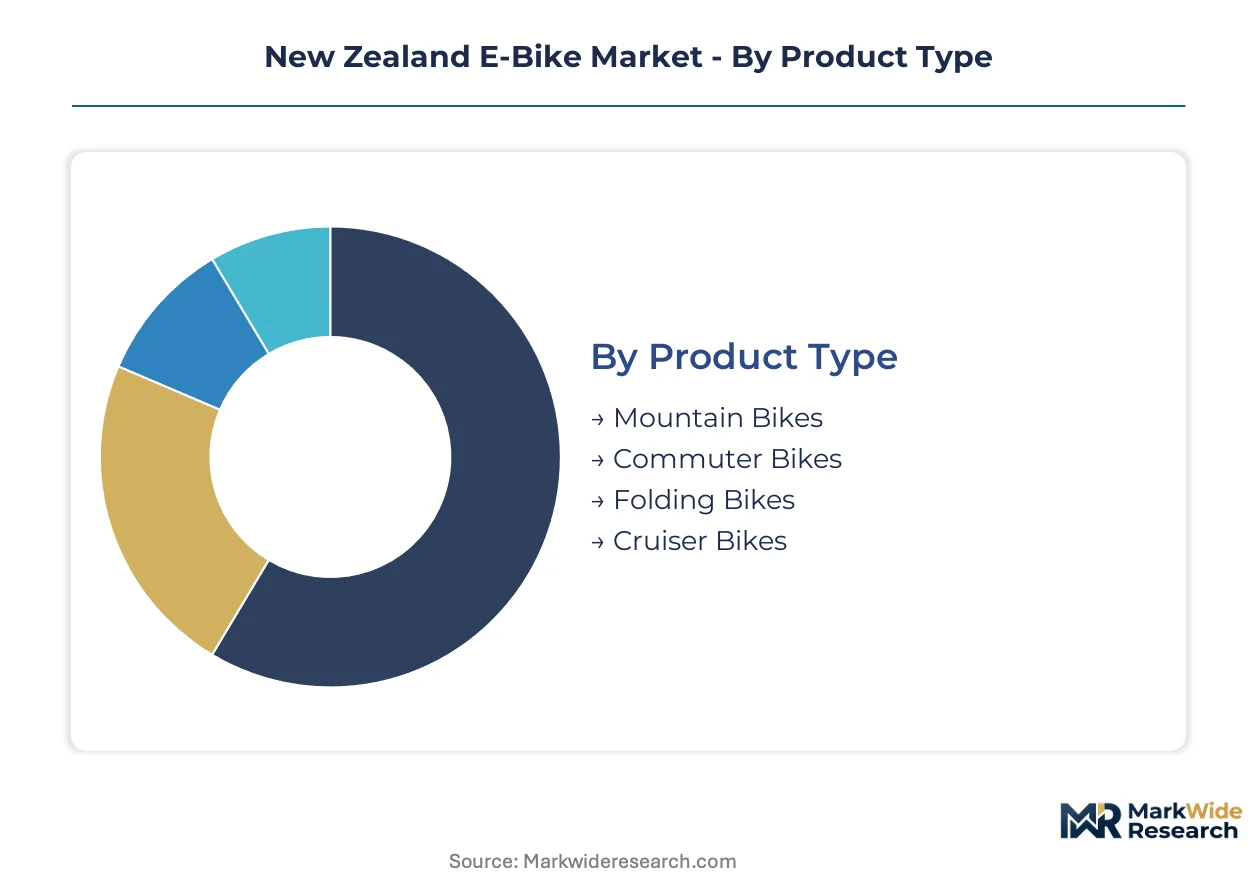
E-bike segmentation in New Zealand reflects distinct usage patterns shaped by terrain, fleet procurement priorities, and Waka Kotahi classification thresholds. Category boundaries determine which configurations qualify for cycleway access and institutional subsidy eligibility.
Product Type:
Frame geometry and riding position specifications align with Auckland's flat commuter corridors versus Wellington's steep gradient demands.
- Commuter Bikes:Step-through and diamond-frame configurations dominate Auckland corporate fleet contracts where Waka Kotahi low-emission transport incentives subsidize staff transport programs. Wellington employers specify enhanced motor torque ratings to manage hill terrain.
- Mountain Bikes:Full-suspension and hardtail variants with reinforced battery mounting systems serve recreational riders in Rotorua trail networks and Queenstown adventure tourism. Mid-drive motor compatibility drives specification priority over hub alternatives.
- Folding Bikes:Compact hinge-frame designs with reduced battery capacity suit intermodal Auckland commuters combining ferry and cycle segments.
- Cruiser Bikes:Upright handlebar geometry and balloon tires occupy niche recreational positioning along Christchurch coastal pathways.
Commuter bikes lead on scale; mountain bikes lead on momentum.
End User:
Procurement authority concentration varies sharply between individual retail purchases and institutional volume contracts.
- Corporate Fleets:Auckland-based professional services firms centralize purchasing through sustainability managers who negotiate standardized specifications across 50-plus unit deployments. Waka Kotahi incentive structures compress payback periods below eighteen months.
- Delivery Services:Courier and food delivery platforms in Wellington and Auckland integrate route optimization software with telematics-enabled hardware. Last-mile operators replace van fleets with electric two-wheel alternatives, expanding most quickly among all user categories.
- Individuals:Retail channel purchases concentrate in Auckland and Wellington where cycling infrastructure investment reduces perceived risk.
- Rental Companies:Tourism operators in Queenstown and Christchurch maintain seasonal fleets with simplified maintenance protocols.
Corporate fleets lead on scale; delivery services lead on momentum.
Motor Type:
Power delivery architecture determines weight distribution, maintenance complexity, and Waka Kotahi wattage classification compliance.
- Mid Drive Motors:Central crank-mounted units distribute mass low and center, critical for Wellington's gradient-heavy routes and courier cargo loads. Food delivery platforms specify these configurations as standard procurement requirements.
- Hub Motors:Rear-mounted variants dominate cost-sensitive commuter specifications where Auckland flat terrain reduces torque demands. Front hub systems face traction limitations on steep Wellington ascents.
- Rear Wheel Motors:Direct-drive hub configurations occupy utility-focused applications with sustained high-load operation.
- Front Wheel Motors:Geared hub systems appear primarily in retrofit conversion kits and entry-level folding bike specifications.
Hub motors lead on scale; mid drive motors lead on momentum.
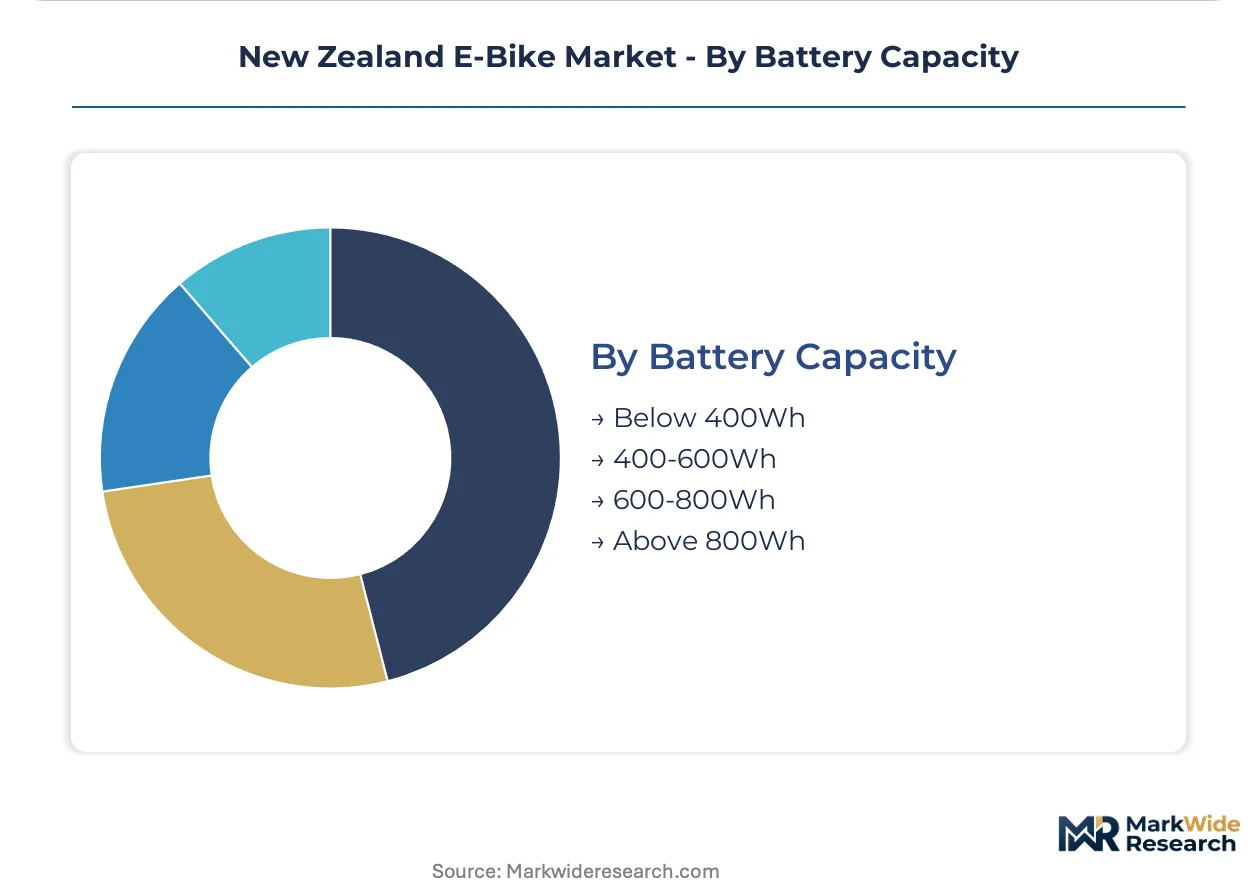
Battery Capacity:
Energy storage specifications directly constrain operational range and determine charging infrastructure dependency for commercial operators.
- 400-600Wh:Lithium-ion cell configurations balance weight and range for Auckland-Wellington commuter corridors. Corporate fleet managers specify this tier to align with Energy Efficiency and Conservation Authority infrastructure deployment schedules.
- Above 800Wh:Extended-range packs enable courier all-day operation without midday charging. Delivery services in Christchurch and secondary cities adopt these specifications where commercial charging point deployment lags Auckland density.
- Below 400Wh:Reduced-capacity systems suit folding bike form factors and short-haul rental applications.
- 600-800Wh:Mid-tier configurations occupy recreational mountain bike specifications where weight tolerance permits larger packs.
400-600Wh configurations lead on scale; above 800Wh systems lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's e-bike market trails New Zealand in fleet electrification velocity, yet both nations share Waka Kotahi-equivalent incentive structures that compress corporate procurement cycles. Policy divergence emerges in charging infrastructure deployment density.
Auckland Metro
Flat terrain corridors and ferry intermodal nodes concentrate commuter fleet procurement among professional services employers. Waka Kotahi low-emission transport incentives subsidize staff transport programs through standardized 50-plus unit contracts. Central business district employers centralize purchasing authority under sustainability managers.
Wellington Region
Steep gradient topology makes electric assist functionally essential for corporate mobility programs. Hill terrain corridors amplify mid-drive motor specification priority as employers seek balanced weight distribution. Government precinct proximity creates institutional demand concentration around Thorndon and Lambton Quay.
Canterbury
Christchurch cycling network investment creates whitespace for commuter fleet expansion beyond the dominant northern axis. Energy Efficiency and Conservation Authority infrastructure deployment lags Auckland density, constraining operational range for delivery operators. Post-earthquake urban rebuild embeds cycleway priority into arterial road design.
Queenstown-Lakes
Adventure tourism operators maintain seasonal rental fleets with simplified maintenance protocols. Mountain bike trail networks in Rotorua and Queenstown drive recreational mid-drive motor adoption. Tourism seasonality compresses procurement decisions into Q3 deployment windows.
New Zealand E-Bike Market Competitive Landscape
East Asian producers anchor manufacturing scale; Australasian specialists hold domestic assembly proximity. The vendor base splits between volume manufacturers with multi-motor configuration portfolios and regional assemblers leveraging tariff-advantaged supply contracts. Two strategic archetypes dominate: utility-focused electric platform specialists and recreational brand houses with corporate fleet certification. Competitive moves concentrate on institutional contract capture and charging infrastructure partnerships.
Among New Zealand-based operators, Avanti Bikes and UBCO LIMITED occupy distinct positioning within the domestic assembly tier. Avanti leverages local presence to anchor supply contracts with institutional buyers. UBCO exemplifies the utility-focused archetype bridging recreational and commercial applications. Giant Manufacturing Co. represents East Asian manufacturing scale across multiple motor configurations.
| Leading Market Players |
|---|
| Accell Group |
| Avanti Bikes |
| Electric Bike Company |
| Giant Manufacturing Co. |
| MeloYelo |
| Scott Sports |
| Specialized Bicycle Components |
| Trek Bicycle Corporation |
| UBCO LIMITED |
| Others |
Supply & Pricing Matrix
Lithium carbonate spot indices from East Asian commodity exchanges cascade through New Zealand importer cost structures, compressing margin buffers for domestic assemblers while amplifying pricing power for manufacturers with captive cell supply arrangements.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for lithium-ion cell procurement, enabling tiered pricing stratification across premium, standard, and economy levels. Certification tier under Waka Kotahi wattage classifications drives differentiation alongside volume scale in corporate fleet contracts. Pricing pressure stems from currency fluctuation exposure on landed component costs. Delivery services exhibit highest price sensitivity due to thin operational margins, while corporate fleet buyers prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Regional distribution centers in Auckland and Wellington operate hub-and-spoke patterns that concentrate inventory risk before last-mile deployment to service networks. Manufacturing gravity centers on China, Taiwan, and Vietnam for frame fabrication, motor assembly, and electronics integration. Battery cell sourcing draws from South Korean and Japanese suppliers. Single-source vulnerability concentrates in mid-drive motor controller firmware. Distribution runs through importer-wholesaler arrangements with domestic assembly operations capturing tariff-advantaged positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's e-bike market functions as a geographic-arbitrage play where domestic assembly operations exploit tariff differentials against fully-imported competitors, while Waka Kotahi incentive structures compress payback periods below Australian equivalent markets.
For Market Incumbents: Deploy certification investment as the primary lever to lock in Waka Kotahi low-emission transport incentive eligibility ahead of proposed Land Transport Rule amendments. Secure long-term lithium-ion cell offtake agreements to hedge against East Asian supply concentration. Channel control through exclusive service network arrangements defends against direct-to-fleet emerging entrants. For New Entrants and Emerging Players: The 400-600Wh commuter segment gap between premium mid-drive specifications and economy hub-motor alternatives offers the most penetrable entry point. Canterbury regional underpenetration presents whitespace beyond Auckland-Wellington concentration. Telematics-enabled fleet management bundling provides differentiated go-to-market positioning against retail-channel incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with utility-focused electric platform specialists bridging recreational and commercial applications. Long-term viability hinges on charging infrastructure partnership density and service network coverage expansion. Battery diagnostics capability concentration in Auckland and Wellington signals technician skill scarcity as an inflection indicator for regional acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | Captures Waka Kotahi tariff advantages while compressing lead times for corporate fleet contracts. |
| Telematics Platform Integration | Enables route optimization software convergence that delivery platforms now specify as standard procurement requirements. |
| Mid-Drive Motor Certification Investment | Secures Land Transport Rule compliance ahead of tightening wattage classification thresholds for shared path access. |
| Charging Infrastructure Partnership | Addresses Energy Efficiency and Conservation Authority deployment gaps that constrain operational range in secondary cities. |
| Service Technician Training Program | Builds battery diagnostics and motor repair capability to extend coverage beyond Auckland-Wellington concentration. |
Research Methodology
Direct dialogue with fleet procurement managers at Auckland-based professional services firms, sustainability directors, Waka Kotahi policy officers, and Energy Efficiency and Conservation Authority infrastructure planners grounded qualitative findings. Secondary validation drew from Waka Kotahi regulatory filings, EECA infrastructure deployment schedules, customs import records, and Land Transport Rule amendment consultations. Bottom-up unit deployment estimates triangulated against top-down market value projections.
Segment-level outputs across product type, motor configuration, battery capacity tier, and end-user category were generated through structured modeling across the projection horizon. CAGRs were derived from fitted growth curves applied to baseline deployment data, incorporating Waka Kotahi incentive pool trajectories and corporate fleet expansion pipelines as primary forecast inputs.
Caveats apply where Land Transport Rule amendments, lithium-ion supply disruption, or currency fluctuation could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle E-Axle Market